
 Architectural Coatings Market | 2026-2036
Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Coatings Market Intelligence
ISO 14024 environmental labeling is unwinding competitive barriers across the architectural coatings sector, forcing reformulation investments that favor scaled producers. PPG Industries leverages captive resin manufacturing to offset raw material cost swings. Akzo Nobel anchors its position through waterborne technology leadership in European decorative markets. Asian Paints dominates South Asian distribution through dense dealer networks that competitors struggle to replicate.
Architectural coatings are liquid or powder film-forming materials applied to building substrates for protection, decoration, or functional performance, typically comprising binders, pigments, solvents or water carriers, and additives that cure through evaporation, oxidation, or radiation crosslinking. Waterborne coatings now lead volume globally as VOC restrictions tighten, while powder coatings represent the fastest-expanding structural segment for metal facade applications where factory-applied durability matters. Residential buildings command the largest end-user share, though hospitality establishments are emerging as a concentrated margin pool where aesthetic differentiation supports premium pricing.
EPA regulations in the United States cap VOC content in architectural coatings, compelling manufacturers to shift acrylic and alkyd formulations toward compliant chemistries. ECHA enforces REACH registration and restriction protocols across Europe, raising compliance costs that filter smaller blenders from commercial tender pools. China's MEE implements GB standards for hazardous substance limits in building materials, reshaping import requirements and domestic production specifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capital allocation.
Market Dynamics
Waterborne formulation mandates are compressing solvent-borne capacity while forcing resin suppliers to retool polymer architectures, concentrating production among integrated chemical conglomerates with captive R&D pipelines.
Growth Catalysts
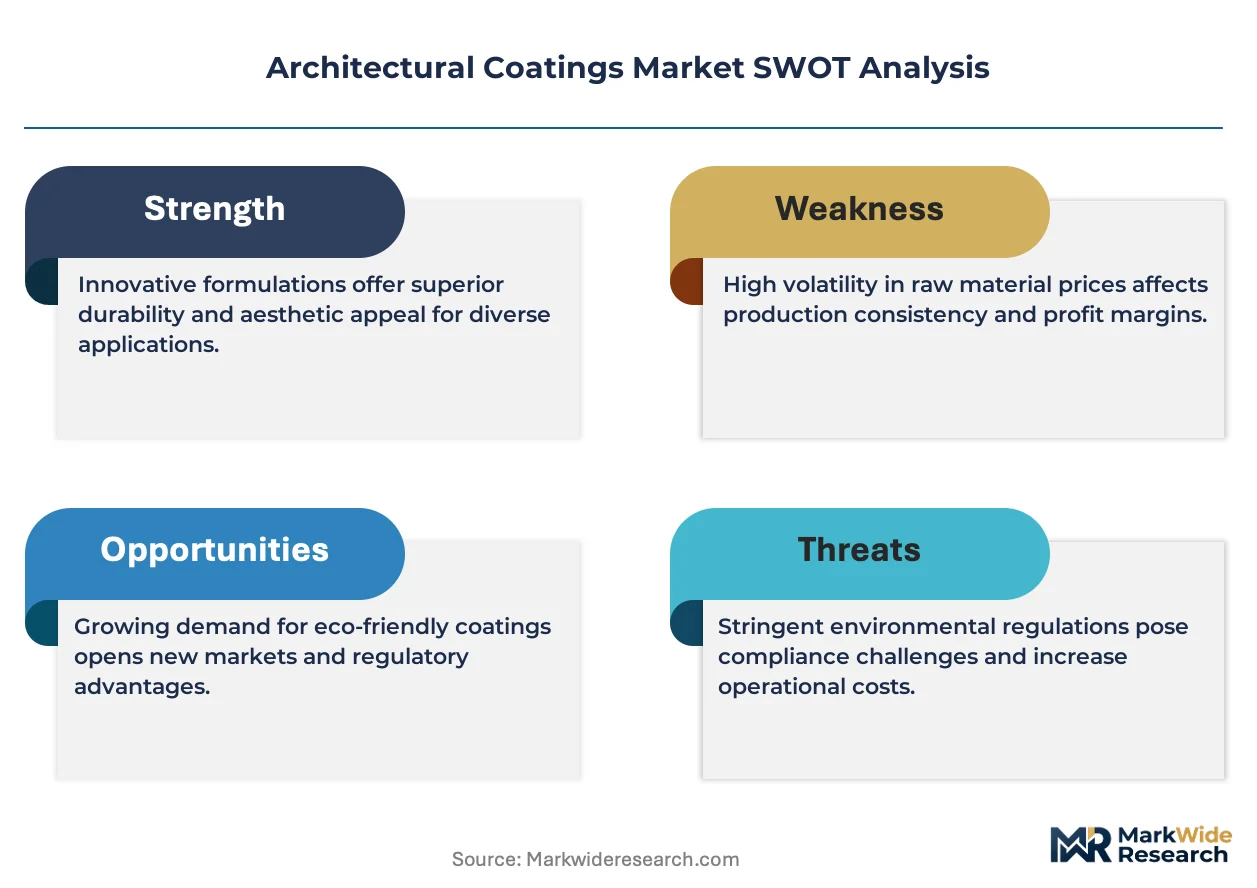
- EU Green Deal compliance deadlines:REACH restrictions on VOC content are redirecting renovation budgets toward certified low-emission products across German and French housing stock.
- Titanium dioxide substitution:Calcium carbonate and kaolin extenders are gaining traction in interior flat coatings as raw material cost hedges.
- China tier-two urban renewal:MEE enforcement of GB standards is accelerating facade refurbishment programs in Chengdu, Wuhan, and Xi'an.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and epoxy resin prices swing with naphtha cracking margins, squeezing formulation economics.
- Pigment supply concentration:Titanium dioxide production clusters in Chinese coastal provinces, exposing buyers to export duty fluctuations.
- Alkyd technical ceiling:Solvent-borne alkyds face hard performance limits in exterior durability versus silicone-modified alternatives.
Strategic Opportunities
- India PLI scheme for chemicals:Domestic resin manufacturing incentives are opening import-substitution plays for waterborne acrylic supply.
- Cool roof coatings:Infrared-reflective pigments address thermal management mandates in Saudi Arabian and UAE commercial construction.
- Direct-to-contractor digital platforms:E-procurement portals are disintermediating traditional distributor tiers in Brazilian and Mexican markets.
Industry Challenges
- Formulation chemist scarcity:Polymer science talent pipelines lag demand for hybrid waterborne-UV cure expertise.
- ISO 14024 certification timelines:Third-party eco-label verification stretches 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Coatings Market |
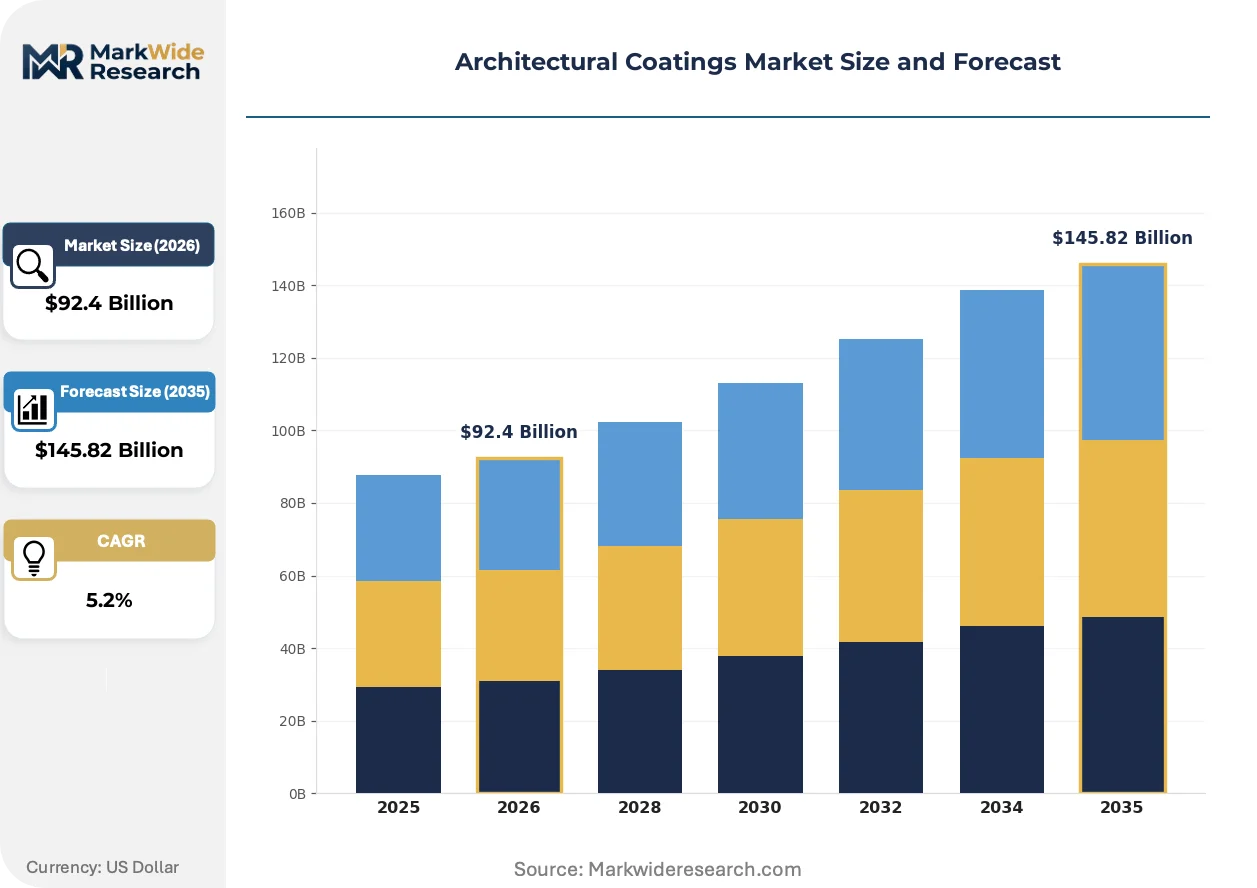
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $145.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne Coatings, Solventborne Coatings, Powder Coatings, UV Curable Coatings, Nanocoatings Application: Exterior Surfaces, Interior Walls, Ceilings, Facades, Doors & Windows Technology: Acrylic, Epoxy, Polyurethane, Alkyd, Silicone End User: Residential Buildings, Commercial Complexes, Institutional Facilities, Hospitality Establishments, Educational Institutions |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc, Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd, Asian Paints Limited, RPM International Inc., BASF SE, Kansai Paint Co., Ltd., Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Coatings Market Strategic Shifts & Innovations
Photocatalytic self-cleaning coatings are exiting laboratory demonstration into commercial specification, altering maintenance economics for high-rise facades and infrastructure assets.
Photocatalytic titanium dioxide surface treatments is decomposing organic atmospheric pollutants through UV-activated oxidation, enabling facade applications that reduce cleaning cycles. Commercial real estate developers in Singapore and Dubai are specifying these finishes for prestige towers. The technology is compressing lifecycle service contracts and redirecting facility management budgets.
EPA VOC content limits under 40 CFR Part 59 are compelling architectural coating manufacturers to eliminate exempt solvents from alkyd formulations. The rule tightens compliance windows for imported products entering US customs. California Air Resources Board companion rules extend these requirements to South Coast and Bay Area air districts.
Building information modeling integration is reshaping coating specification workflows, with architects embedding performance data directly into digital twin assets. Material libraries from NBS and BIMobject are displacing traditional product binders in UK and Australian commercial projects. Tier-one contractors in Germany and the Netherlands now require digital submittals for facade system packages.
Architectural Coatings Market Segmentation
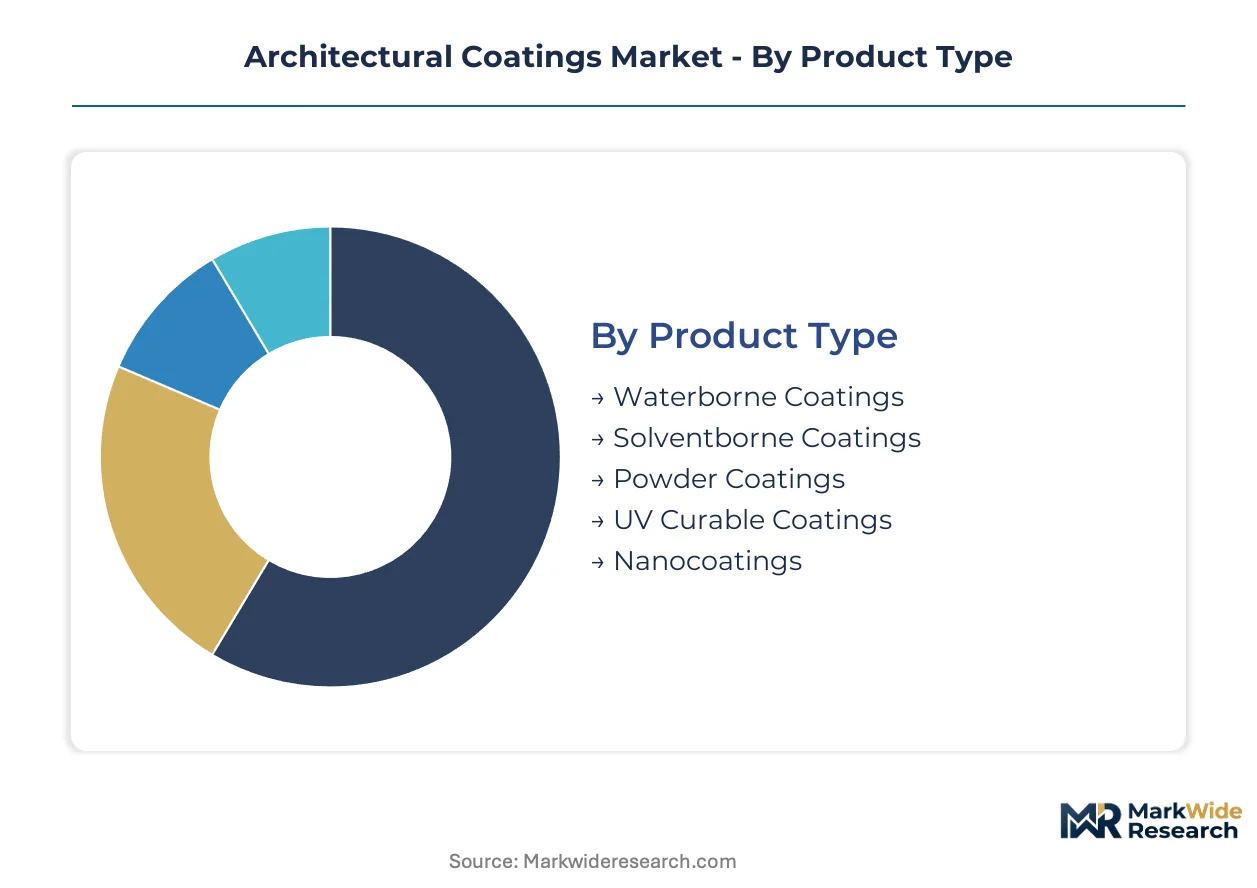
Architectural coatings segment along four intersecting dimensions that reshape procurement priorities and margin structures. Product type determines regulatory compliance burden and capital intensity. Application context drives performance specification and re-coating frequency. Technology selection locks in raw material exposure and durability profiles. End-user category dictates pricing power and contract terms.
Product Type:
Substitution pressure from waterborne formulations is dismantling solventborne capacity as VOC mandates tighten across German housing renovation and Chinese tier-two urban renewal programs.
- Waterborne Coatings:Acrylic and polyurethane dispersions in water carriers cure through evaporation and coalescence, achieving low-VOC compliance for interior residential applications in France and the Netherlands. Demand concentrates in German social housing refurbishment where EU Green Deal certification requirements redirect specification toward certified low-emission systems.
- Solventborne Coatings:Alkyd and acrylic solutions in organic carriers deliver superior flow and wet-edge retention for exterior metal substrates in humid climates. Share erodes fastest in California and New York where EPA 40 CFR Part 59 caps eliminate exempt solvent pathways for architectural applications.
- Powder Coatings:Thermosetting epoxy and polyester resins applied electrostatically to metal facades and window frames in factory conditions.
- UV Curable Coatings:Acrylate oligomers cross-linked by ultraviolet radiation for rapid-cure wood and plastic substrates in industrial prefabrication.
- Nanocoatings:Silica and metal oxide nanoparticles confer hydrophobic or photocatalytic properties for self-cleaning facade specifications in Singapore and Dubai.
Waterborne coatings anchor the volume base while nanocoatings gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity interior specifications from engineered facade systems commanding premium pricing in Saudi Arabian commercial towers.
- Exterior Surfaces:Elastomeric acrylics and silicone-modified systems accommodate thermal cycling and moisture intrusion on concrete and stucco substrates. Demand clusters in Chinese tier-two cities where MEE enforcement of GB standards accelerates weatherproofing upgrades in Chengdu and Wuhan residential compounds.
- Interior Walls:Vinyl acrylic and styrene-acrylic latexes provide scrub resistance and color retention for high-traffic residential and hospitality spaces. Specification concentrates in Indian metropolitan housing where Asian Paints dealer networks dominate distribution through dense urban penetration.
- Ceilings:Flat latex formulations with high hiding power and spatter resistance for residential and institutional overhead surfaces.
- Facades:Integrated coating-substrate systems specified through BIM workflows in UK and Australian commercial projects.
- Doors & Windows:Factory-applied coatings on aluminum and uPVC profiles for thermal break assemblies.
Interior walls generate the highest transaction frequency while facade applications capture the widest margin dispersion.
Technology:
Supply concentration in acrylic monomer production favors integrated resin manufacturers with captive feedstock positions.
- Acrylic:Thermoplastic and thermosetting polymers from acrylic acid and methacrylic acid esters deliver UV resistance and color stability for exterior emulsion paints. Formulation demand concentrates in waterborne architectural segments where PPG Industries leverages backward integration into resin manufacturing to offset petrochemical feedstock swings.
- Epoxy:Bisphenol A and epichlorohydrin condensation polymers providing chemical resistance and adhesion for industrial floor and wall systems. Specification clusters in German and Dutch healthcare and food processing facilities where hygiene standards mandate seamless, disinfectant-tolerant surfaces.
- Polyurethane:Isocyanate-cured systems for abrasion-resistant wood and metal finishes in high-end residential applications.
- Alkyd:Polyester-modified drying oils facing hard performance ceilings against silicone alternatives in exterior durability.
- Silicone:Siloxane backbone polymers conferring water repellency and vapor permeability for heritage facade restoration.
Acrylic technology commands the broadest application footprint while silicone-modified systems climb fastest in premium exterior specifications.
End User:
Customer type stratification separates price-sensitive residential volume from hospitality margin pools where aesthetic differentiation supports specification premiums.
- Residential Buildings:Single-family and multi-family housing stock driving renovation and new construction coating consumption. Demand concentrates in mature European economies where German and French housing renovation programs redirect budgets toward certified low-VOC products under EU Green Deal compliance deadlines.
- Commercial Complexes:Office and retail assets where lifecycle cost calculations favor durable systems with extended maintenance intervals. Specification clusters in UAE and Saudi Arabia where cool roof coatings with infrared-reflective pigments address thermal management mandates in commercial construction codes.
- Institutional Facilities:Government and healthcare buildings with procurement governed by public tender protocols.
- Hospitality Establishments:Hotels and resorts where brand identity drives custom color matching and texture specification.
- Educational Institutions:Schools and universities with phased maintenance budgets and durability requirements.
Residential buildings anchor the volume base while hospitality establishments expand share fastest through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal renovation subsidies are redirecting specification toward certified low-VOC systems across German and French housing stock. China's MEE enforcement of GB standards accelerates facade refurbishment in tier-two cities. US EPA 40 CFR Part 59 compliance windows tighten for imported alkyd formulations entering customs.
United States
California Air Resources Board rules extend EPA VOC caps to South Coast and Bay Area air districts, eliminating exempt solvent pathways for architectural applications. Commercial real estate developers in Texas and Florida specify cool roof coatings with infrared-reflective pigments to address thermal management mandates. The Southeast construction corridor from Atlanta to Charlotte concentrates waterborne acrylic demand for residential subdivision volume.
Germany
REACH restrictions on VOC content redirect renovation budgets toward certified low-emission products across social housing refurbishment programs. ECHA registration protocols raise compliance costs that filter smaller blenders from commercial tender pools. Industrial coating demand clusters in North Rhine-Westphalia where factory-applied powder systems serve metal facade and window frame manufacturers.
China
MEE enforcement of GB standards for hazardous substance limits accelerates weatherproofing upgrades in Chengdu, Wuhan, and Xi'an residential compounds. Tier-two urban renewal programs expand specification for elastomeric acrylics on concrete and stucco substrates. Titanium dioxide production concentrates in coastal provinces, exposing buyers to export duty fluctuations that squeeze formulation economics.
India
PLI scheme incentives for domestic resin manufacturing open import-substitution plays for waterborne acrylic supply chains. Dense dealer networks in Mumbai and Delhi-NCR dominate distribution through urban penetration that competitors struggle to replicate. Specification concentrates in metropolitan housing where vinyl acrylic latexes provide scrub resistance for high-traffic residential spaces.
UAE
Commercial construction codes mandate cool roof coatings with infrared-reflective pigments for thermal management in Saudi Arabian and UAE commercial towers. Photocatalytic self-cleaning titanium dioxide surface treatments gain specification in Dubai prestige developments, compressing lifecycle service contracts. Prestige tower developers specify these finishes to reduce facade cleaning cycles and redirect facility management budgets.
Architectural Coatings Market Key Industry Players
Listed leaders compete with private specialists across formulation technology and distribution reach, creating a tiered structure where scale advantages concentrate in integrated resin manufacturers. Private specialists occupy niche positions in regional color matching and custom texture specification. Three archetypes dominate: backward-integrated chemical conglomerates with captive polymer supply, waterborne technology specialists with ISO 14024 certification pipelines, and distribution-heavy regional players with dense dealer networks. Competitive moves center on M&A for resin capacity and strategic partnerships for digital procurement platform access.
Within the integrated chemical tier, BASF SE and PPG Industries exemplify backward-integrated manufacturers with captive resin production. Among Asia-Pacific specialists, Nippon Paint Holdings Co., Ltd. and Asian Paints Limited occupy positions defined by dense distribution infrastructure. At the premium specification end, Akzo Nobel N.V. represents waterborne technology leadership anchored in European decorative markets.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc |
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd |
| Asian Paints Limited |
| RPM International Inc. |
| BASF SE |
| Kansai Paint Co., Ltd. |
| Jotun A/S |
| Others |
Cost & Logistics Intelligence
Long-term resin offtake contracts with titanium dioxide suppliers lock in both feedstock access and price visibility for European and Asian coating manufacturers facing GB standards compliance deadlines in China. These arrangements insulate integrated producers from naphtha cracking margin swings while stranding smaller blenders exposed to spot acrylic acid markets.
Pricing Analysis
Certification level creates the primary spread between ISO 14024 eco-labeled premiums and uncertified commodity tiers in German and French housing renovation. Three-tier pricing structure across premium, standard, and economy levels reflects REACH compliance investment recovery, with hospitality specifiers least price-sensitive due to brand identity budgets. Cost compression in standard-tier interior emulsions is intensifying because calcium carbonate extenders displace titanium dioxide, while residential contractors in India exhibit highest price sensitivity through dealer network negotiations.
Supply Chain Analysis
Just-in-time resin delivery dominates European decorative coating plants, whereas Chinese manufacturers maintain strategic stockpiles of acrylic acid against MEE enforcement uncertainties. Feedstock concentration in coastal Chinese provinces, South Korean petrochemical complexes, and German chemical parks exposes formulators to tariff volatility on titanium dioxide exports. Supply chain risk centers on single-source vulnerability for photocatalytic nano-titanium dioxide used in Dubai prestige developments. Distribution runs through dense dealer networks in South Asia and direct-to-contractor digital platforms in Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne formulation mandates are accelerating substitution pressure on solvent-borne capacity, forcing incumbents to defend position through certification pipelines and captive resin supply while new entrants exploit white-space in nanocoating specifications and tier-two Chinese urban renewal.
For Market Incumbents: Shield margin position by deepening backward integration into acrylic resin manufacturing and accelerating ISO 14024 certification pipelines before EU Green Deal deadlines eliminate exempt solvent pathways. Prioritize capacity control in coastal Chinese provinces where titanium dioxide production concentrates and MEE enforcement is tightening. For New Entrants and Emerging Players: EMAS fast-track certification for low-VOC formulations opens specification access in German social housing refurbishment programs where incumbent compliance timelines lag. Target hospitality facade applications in UAE and Saudi Arabia where cool roof coating mandates and photocatalytic self-cleaning specifications command premium positioning through direct contractor platform partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated resin manufacturers with captive polymer supply and established eco-label pipelines. Acquisition focus should center on waterborne technology specialists in European decorative markets and distribution-heavy regional players in South Asian metropolitan clusters. Watch for MEE enforcement intensity in Chinese tier-two cities as inflection indicator for regional formulation demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin | Captive supply offsets naphtha cracking volatility for PPG Industries and BASF SE. |
| ISO 14024 Certification Pipeline | Eco-label verification accelerates specification in German and French housing renovation. |
| Digital Procurement Platform Partnership | E-procurement portals disintermediate distributor tiers in Brazilian and Mexican markets. |
| Photocatalytic Coating Scale-Up | Self-cleaning titanium dioxide treatments compress lifecycle contracts for Dubai developers. |
| Tier-Two China Distribution Expansion | Dealer network density captures MEE-driven facade refurbishment in Chengdu and Wuhan. |
Research Approach
A standing panel of coating plant managers, resin procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE regulatory disclosures. Bottom-up volume modeling triangulated against top-down value aggregation across product type, application context, technology selection, and end-user category dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation granularity spanning waterborne versus solvent-borne formulation, interior versus exterior application, acrylic versus silicone-modified technology, and residential versus hospitality end-use. CAGRs were derived from regression-adjusted historical trajectory projection, incorporating GB standards enforcement timelines, EU Green Deal subsidy allocation patterns, and petrochemical feedstock cost curves as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance investment and MEE enforcement continuity would require recalibration. Forecasts reflect documented assumptions on regulatory trajectory and raw material supply concentration. Revision becomes warranted when titanium dioxide export duty fluctuations or photocatalytic coating specification adoption cross volatility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Global Antifouling Paints and Coatings Market