
 Point of Care (Poc) Molecular Diagnostics Market | 2026-2036
Point of Care (Poc) Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care (Poc) Molecular Diagnostics Market Analysis
The capital-intensity divergence between integrated platform developers and assay-only suppliers is redrawing competitive boundaries in point-of-care molecular diagnostics. Abbott Laboratories leverages vertically controlled cartridge manufacturing to sustain margin structures across high-throughput hospital installations. Danaher Corporation anchors its position through precision optical and fluidic component ecosystems that feed multiple instrument generations. F. Hoffmann-La Roche Ltd. differentiates via centralized R&D hubs in Switzerland and the United States that compress assay development cycles.
Point of care molecular diagnostics encompasses portable or near-patient systems that amplify and detect nucleic acid sequences through miniaturized thermal cycling or isothermal chemistry, typically delivering results within fifteen to sixty minutes for clinical decision-making at the bedside, in clinics, or in field settings. Nucleic acid amplification platforms, particularly PCR-based cartridges, dominate current installed bases and command premium pricing due to their established clinical validity across infectious disease panels. Isothermal amplification methods, including LAMP chemistry, represent the fastest-expanding technology segment because they eliminate complex thermal cycling hardware and reduce instrument cost thresholds for clinics and home-care deployment. Microfluidic consumables capture recurring revenue streams that offset capital equipment discounts, creating durable margin pools for manufacturers with captive chip fabrication.
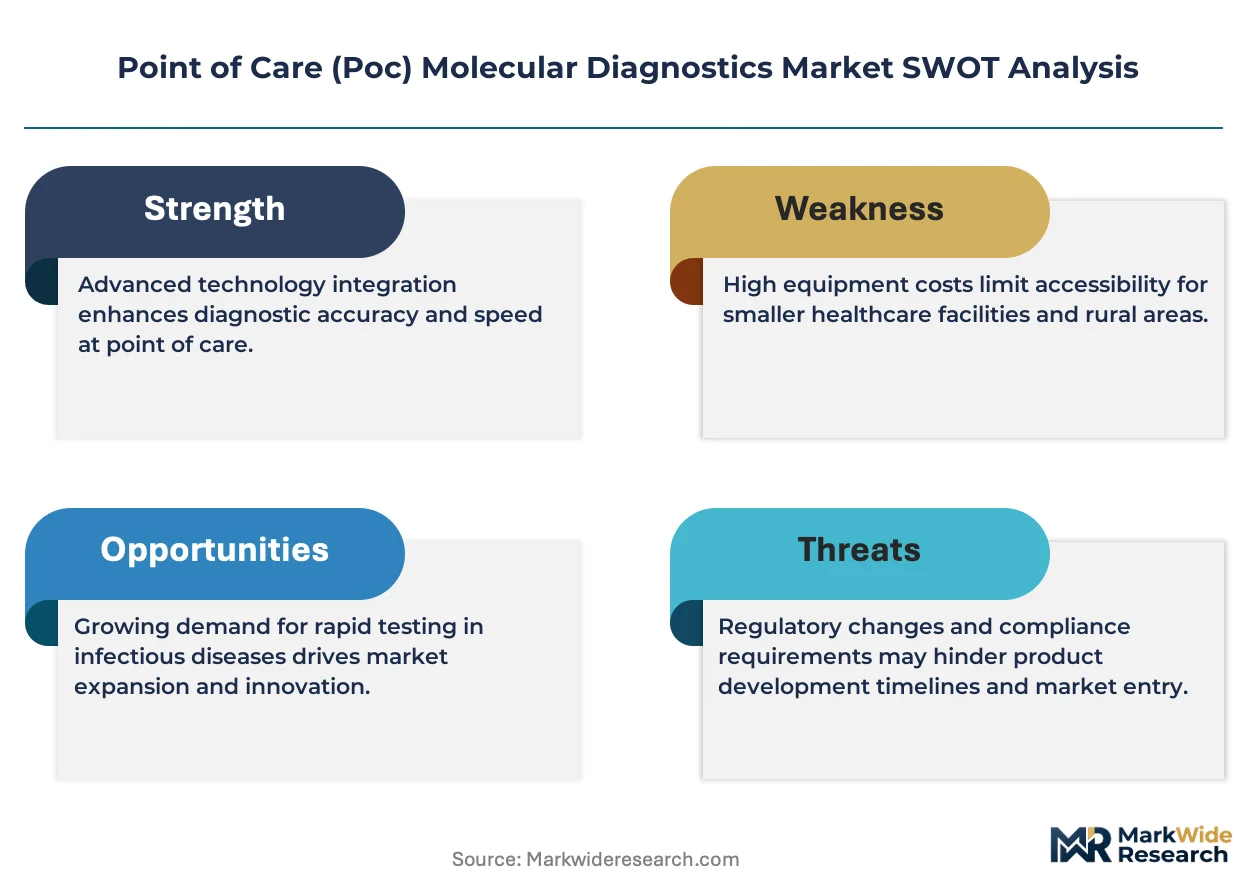
FDA premarket review pathways and EMA CE-IVD marking requirements under the In Vitro Diagnostic Medical Devices Regulation shape product development roadmaps, compliance spending, and geographic launch sequencing for platform developers. The EPA and OSHA maintain secondary influence through laboratory safety standards that affect cartridge manufacturing site certification and operator training protocols. Stakeholders must monitor how WHO prequalification criteria for decentralized molecular testing in low-resource settings create parallel design specifications that could fragment or harmonize with OECD regulatory benchmarks.
Market Dynamics
The convergence of isothermal amplification chemistry with microfluidic cartridge architectures is compressing instrument footprints and collapsing the cost threshold for decentralized nucleic acid testing, fundamentally restructuring competitive boundaries between integrated platform developers and assay-only suppliers.
Growth Catalysts
- Decentralized Infectious Disease Surveillance:Hospital emergency departments in the United States, Germany, and China are deploying rapid pathogen identification systems to reduce antibiotic stewardship delays and improve patient triage throughput.
- Regulatory Harmonization:FDA and EMA convergence on molecular test quality standards under IVDR and premarket review pathways is compressing approval timelines for multiplex assays and accelerating geographic launch sequencing.
- Isothermal Chemistry Maturation:LAMP-based platforms eliminate thermal cycling hardware complexity, reducing capital equipment costs and enabling clinic and home-care deployment models previously inaccessible to PCR-dependent systems.
Market Restraints
- Consumable Cost Concentration:Microfluidic chip fabrication requires specialized polymer substrates and precision molding equipment, with captive manufacturing concentrated among a limited supplier base in East Asia and Switzerland.
- Regulatory Fragmentation:WHO prequalification criteria for decentralized molecular testing in low-resource settings create parallel design specifications that diverge from OECD regulatory benchmarks, forcing dual development tracks.
- Technical Validity Gaps:Isothermal methods exhibit reduced multiplexing capacity and higher false-positive rates in complex sample matrices compared to gold-standard PCR, limiting clinical acceptance in high-acuity settings.
Strategic Opportunities
- Home-Based Respiratory Panels:Consumer-accessible molecular testing for influenza and SARS-CoV-2 variants represents underpenetrated demand in North American and European retail pharmacy channels.
- Antimicrobial Stewardship Mandates:CMS reimbursement incentives for rapid diagnostic-guided therapy decisions in US hospital systems create procurement preference for platforms with integrated resistance gene detection.
- AI-Assisted Result Interpretation:Integration of machine learning algorithms with handheld readers is reducing operator training burdens and expanding deployability to non-laboratory personnel in field settings.
Industry Challenges
- Multidisciplinary Talent Scarcity:Platform development requires simultaneous expertise in microfluidic engineering, nucleic acid chemistry, and regulatory affairs, with acute shortages in assay validation and clinical trial design functions.
- Legacy System Interoperability:Hospital IT infrastructure and electronic health record platforms in established healthcare systems resist seamless integration with point-of-care molecular data streams, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care (Poc) Molecular Diagnostics Market |
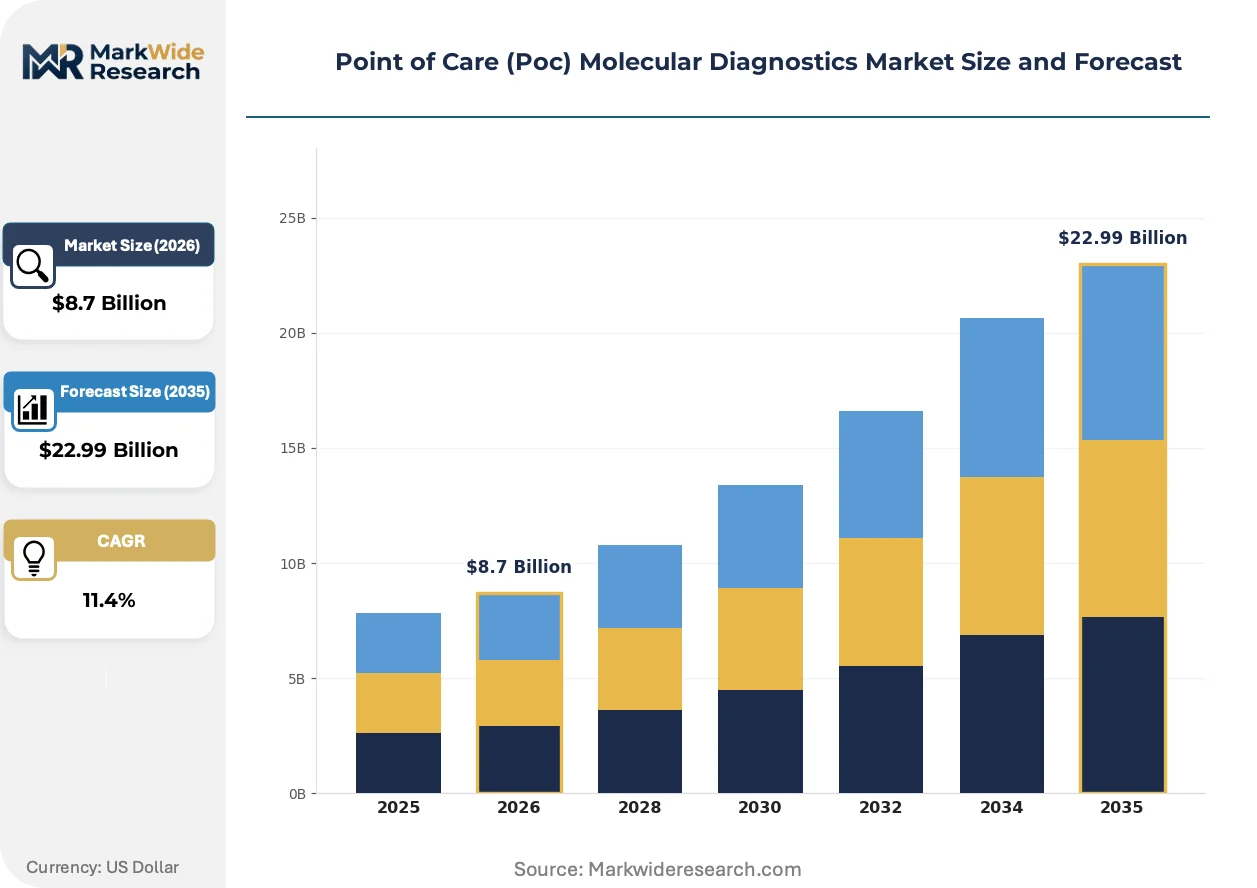
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidics, Nucleic Acid Amplification, Biosensors, Liquid Biopsy Technology: PCR, LAMP, Isothermal Amplification, Next-Generation Sequencing End User: Hospitals, Independent Labs, Home Care, Clinics Application: Infectious Diseases, Genetic Testing, Cancer Diagnostics, Therapeutic Drug Monitoring |
| Companies Covered | Abbott Laboratories, Danaher Corporation, F. Hoffmann-La Roche Ltd., QIAGEN N.V., bioMérieux SA, Thermo Fisher Scientific, Bio-Rad Laboratories, Becton Dickinson, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care (Poc) Molecular Diagnostics Market Emerging Trajectories
Instrument miniaturization and reagent stabilization are collapsing the operational boundary between centralized laboratory molecular diagnostics and near-patient testing, while regulatory frameworks race to accommodate accelerated validation paradigms for emerging platform architectures.
Digital PCR microchamber arrays are supplanting traditional real-time PCR thermal cyclers in high-sensitivity applications requiring absolute quantification of viral load or minimal residual disease. Oncology clinics and transplant centers are adopting these platforms for monitoring treatment response, with cartridge-based implementations reducing sample-to-answer intervals from hours to under thirty minutes. This transition is compressing the addressable market for conventional laboratory-based quantitative PCR systems and redirecting capital expenditure toward bedside-compatible instrumentation.
The EU In Vitro Diagnostic Medical Devices Regulation (IVDR) is tightening clinical evidence requirements for Class C and D molecular diagnostic devices, mandating expanded post-market surveillance and stricter notified body oversight. Manufacturers are restructuring quality management systems and accelerating performance study timelines to meet 2028 transition deadlines. High-plex respiratory panels and sexually transmitted infection assays face the steepest compliance burdens, with several platforms already withdrawn from European markets rather than undergo costly re-certification.
Hospital procurement committees are unbundling instrument placement from consumable supply agreements, demanding transparent per-test pricing and competitive bidding for cartridge contracts. This pattern disrupts the traditional razor-and-blade model that locked institutions into single-vendor ecosystems. The shift is most pronounced in German and US hospital networks with centralized laboratory governance, where multi-platform standardization is reducing training complexity and improving supply chain resilience through dual-source strategies.
Point of Care (Poc) Molecular Diagnostics Market Segmentation
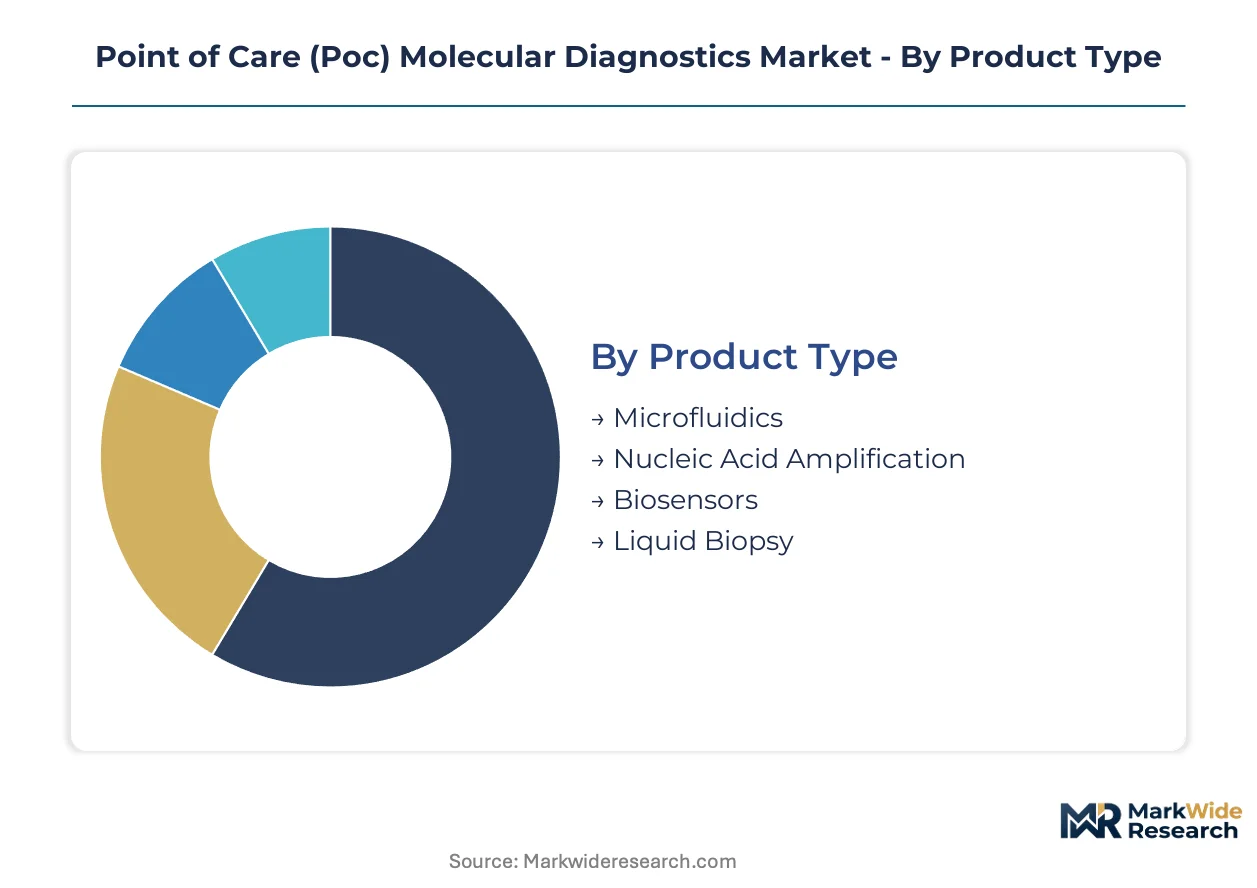
Segmentation in point-of-care molecular diagnostics reveals how regulatory pathways, cost thresholds, and clinical settings fragment platform architectures. Each dimension carries distinct compliance burdens and margin structures that determine manufacturer positioning.
Product Type:
FDA Class II and Class III designations, plus EMA IVDR classifications, impose divergent clinical evidence requirements across consumable formats. Microfluidic cartridges face stricter biocompatibility and sterility validation than instrument-only platforms.
- Microfluidics:Precision-molded polymer substrates integrate sample preparation, amplification, and detection in single-use cartridges. Hospital emergency departments in the United States and Germany concentrate procurement for respiratory and bloodstream pathogen panels where rapid turnaround reduces antibiotic stewardship delays.
- Nucleic Acid Amplification:Miniaturized thermal cyclers and isothermal chambers execute PCR or LAMP chemistry in portable footprints. Demand clusters in Chinese tier-1 cities building decentralized diagnostic networks under national infectious disease control mandates.
- Biosensors:Electrochemical and optical transducers detect amplified nucleic acids without fluorescence optics.
- Liquid Biopsy:Circulating tumor DNA and cell-free RNA analysis platforms enable non-invasive cancer monitoring.
Microfluidics handles the majority of throughput; liquid biopsy is expanding most quickly on share.
Technology:
Cost tier differentiation separates premium PCR platforms from emerging isothermal alternatives, with capital equipment thresholds determining clinic accessibility.
- PCR:Real-time fluorescence monitoring of thermal cycling delivers gold-standard sensitivity and multiplexing capacity. High-acuity settings in US academic medical centers maintain preference for PCR-based respiratory panels despite higher instrument costs.
- LAMP:Loop-mediated isothermal amplification operates at constant temperature, eliminating complex heating hardware. Clinics and home-care deployment in Germany and China accelerate adoption where simplified workflows reduce operator training burdens.
- Isothermal Amplification:NASBA, RPA, and helicase-dependent methods expand chemistry options beyond LAMP.
- Next-Generation Sequencing:Miniaturized sequencers enable targeted panels and metagenomic detection at point of care.
PCR retains the dominant installed base; LAMP is gaining share fastest among new placements.
End User:
Customer type determines reimbursement pathways, with CMS hospital incentives diverging from retail pharmacy and direct-to-consumer models.
- Hospitals:Emergency departments and intensive care units deploy rapid pathogen identification to reduce time-to-appropriate-therapy. US health systems under CMS antimicrobial stewardship mandates drive procurement preference for integrated resistance gene detection.
- Independent Labs:Reference laboratories extend molecular services to outreach clinics through portable platform placement.
- Home Care:Consumer-accessible molecular testing for influenza and SARS-CoV-2 variants penetrates North American and European retail channels.
- Clinics:Primary care and urgent care settings adopt isothermal platforms where capital constraints exclude PCR systems.
Hospitals absorb the largest test volume; home care is climbing the fastest on deployment growth.
Application:
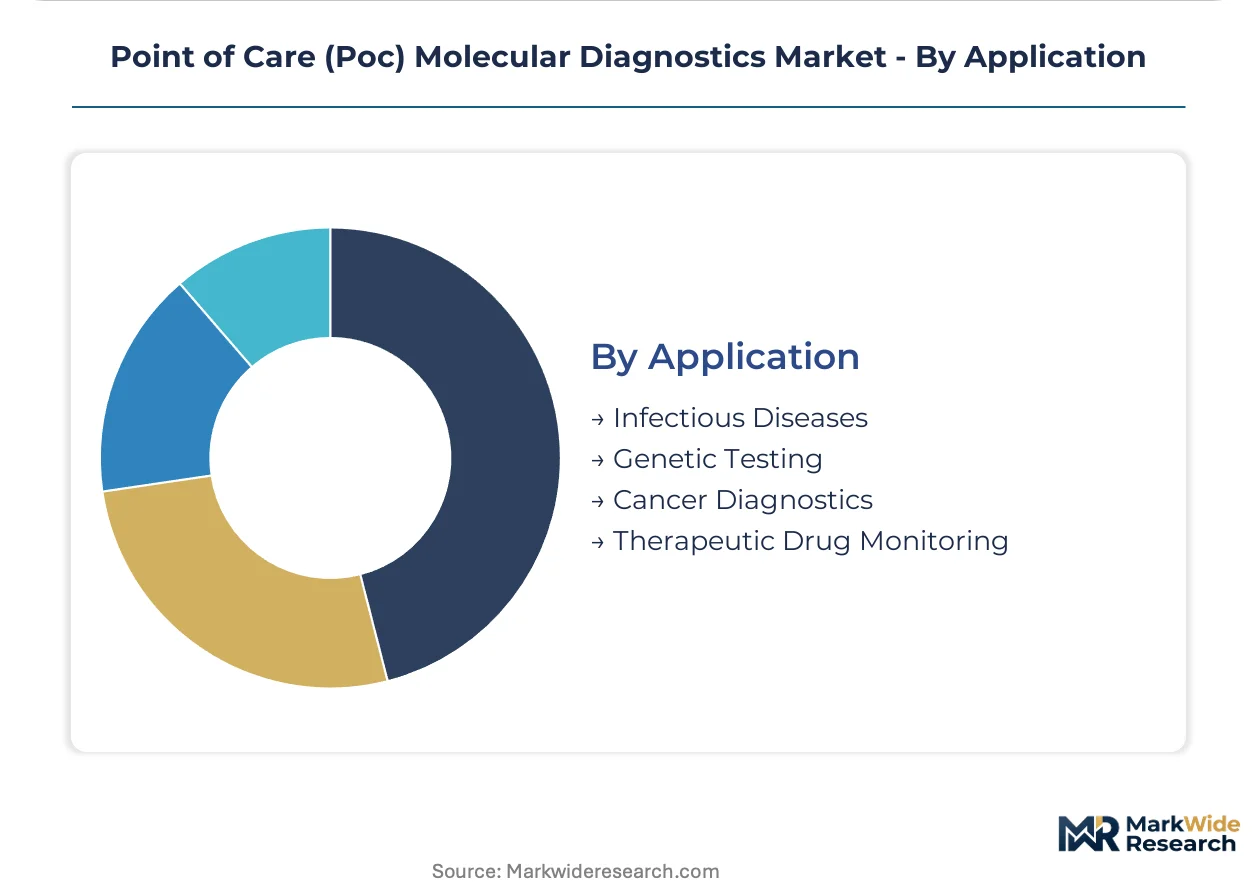
Application maturity varies by clinical evidence accumulation, with infectious disease panels holding established reimbursement codes while oncology and pharmacogenomics build payer acceptance.
- Infectious Diseases:Respiratory, bloodstream, and sexually transmitted pathogen panels dominate current utilization. German hospital networks and Chinese CDC-affiliated laboratories standardize on multiplex respiratory assays for seasonal surveillance.
- Genetic Testing:Pharmacogenomic and carrier screening applications expand point-of-care deployment.
- Cancer Diagnostics:Minimal residual disease monitoring and mutation profiling migrate from central laboratories to oncology clinics.
- Therapeutic Drug Monitoring:Immunosuppressant and anticoagulant level assessment via molecular methods remains nascent.
Infectious diseases handles the majority of throughput; cancer diagnostics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in China by approximately 40-60% for comparable respiratory panels, reflecting reimbursement rate differentials and patent protection strength. German hospital networks command intermediate pricing through centralized procurement consortia that aggregate demand across multiple states.
United States
CMS antimicrobial stewardship mandates drive emergency department procurement of rapid pathogen identification systems with integrated resistance gene detection. FDA premarket review pathways for Class III molecular devices compress approval timelines for multiplex assays. Boston and San Diego biotechnology clusters concentrate platform development activity, with Massachusetts General Hospital and UC San Diego Medical Center serving as early validation sites for next-generation cartridge architectures.
Germany
Hospital procurement committees unbundle instrument placement from consumable supply agreements, demanding transparent per-test pricing through competitive bidding. EMA IVDR Class C and D clinical evidence requirements mandate expanded post-market surveillance for high-plex respiratory panels. The Rhine-Ruhr metropolitan region hosts centralized laboratory governance structures that standardize multi-platform deployments across university hospital networks.
China
National infectious disease control mandates accelerate decentralized diagnostic network construction in tier-1 cities including Beijing, Shanghai, and Shenzhen. NMPA regulatory reforms streamline approval pathways for isothermal amplification platforms targeting clinic and home-care deployment. The Yangtze River Delta manufacturing corridor concentrates microfluidic chip fabrication capacity, with Suzhou and Wuxi emerging as precision polymer molding hubs.
Switzerland
Centralized R&D hubs in Basel and Zurich compress assay development cycles through proximity to pharmaceutical decision-makers and clinical trial infrastructure. Swissmedic maintains stringent quality standards that pre-validate platforms for subsequent EMA CE-IVD marking. The Basel metropolitan area anchors precision optical and fluidic component ecosystems feeding multiple instrument generations.
Japan
PMDA regulatory frameworks emphasize clinical utility evidence for point-of-care molecular diagnostics in aging-population care settings. METI industrial policy supports miniaturized thermal cycler development for home-based respiratory panel deployment. The Kansai region around Osaka concentrates diagnostic reagent manufacturing, with Kyoto-based suppliers specializing in stabilized enzyme formulations for ambient-temperature shipping.
Point of Care (Poc) Molecular Diagnostics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform developers sustaining premium pricing through vertically controlled cartridge manufacturing while assay-only suppliers compete on per-test economics. The market structure consolidates around three to five dominant platform ecosystems, each anchored by proprietary instrument-cartridge pairings that create switching costs for hospital laboratory directors. Two strategic archetypes predominate: diversified life science conglomerates with precision component manufacturing capabilities, and specialized molecular diagnostics firms with concentrated assay portfolios. Competitive dynamics center on M&A activity targeting microfluidic engineering talent and strategic partnerships with hospital procurement networks seeking multi-source supply resilience.
Among diversified conglomerates, Abbott Laboratories, Danaher Corporation, and F. Hoffmann-La Roche Ltd. occupy positions defined by captive control over critical manufacturing inputs. Abbott exemplifies the vertically integrated archetype through cartridge manufacturing self-sufficiency. Danaher anchors its market presence through precision optical and fluidic component ecosystems. Roche represents the centralized R&D model with development hubs compressing assay iteration cycles. These three firms collectively shape pricing benchmarks and technology roadmaps that smaller competitors reference in competitive positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN N.V. |
| bioMérieux SA |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Becton Dickinson |
| Hologic |
| Others |
Supply Flow & Price Mechanics
Long-term cartridge supply agreements with hospital procurement committees lock in both microfluidic chip access and per-test price visibility across US and German health systems. These contracts bundle instrument placement with multi-year consumable commitments, insulating manufacturers from spot-market polymer substrate volatility while anchoring buyer expectations to transparent unit economics.
Pricing Analysis
The customization-premium spread between FDA Class III multiplex respiratory panels and standard infectious disease cartridges runs approximately 40-60% in US academic medical centers. Pricing stratifies across premium, standard, and economy tiers based on multiplexing capacity and integrated resistance gene detection. Cost compression in the standard tier is intensifying because hospital procurement committees unbundle instrument placement from consumable agreements. Independent reference laboratories exhibit the highest price sensitivity, while emergency departments under CMS antimicrobial stewardship mandates show the least.
Supply Chain Analysis
Inventory lead times for precision-molded polymer substrates currently stretch 12-16 weeks due to captive fabrication concentration in Switzerland and the Yangtze River Delta corridor. Microfluidic chip supply draws from specialized polymer substrate suppliers in China and Switzerland, with stabilized enzyme formulations sourced from Kyoto-based manufacturers. Single-source vulnerability in East Asian precision molding equipment creates exposure to export licensing restrictions. Distribution runs through hospital procurement consortia in Germany and group purchasing organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care molecular diagnostics fragments into addressable niches as decentralized infectious disease surveillance shifts from hospital emergency departments toward retail pharmacy and home-care deployment models.
For Market Incumbents: Compound platform ecosystem stickiness through backward integration into cartridge manufacturing and captive control of precision optical component supply. Threats from isothermal amplification entrants with simplified hardware architectures demand defensive capacity expansion in Suzhou and Wuxi polymer molding hubs. Certification investment in FDA Class III and EMA IVDR Class D pathways remains the critical lever for maintaining pricing power in high-acuity settings. For New Entrants and Emerging Players: Differentiate on LAMP-based workflow simplicity to penetrate German primary care clinics and Chinese tier-2 city health centers where capital constraints exclude PCR systems. The most penetrable white-space sits in North American retail pharmacy channels for consumer-accessible respiratory panels. A direct-to-consumer go-to-market angle through pharmacy partnerships bypasses hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward specialized molecular diagnostics firms with concentrated isothermal assay portfolios and microfluidic engineering talent depth. Long-term viability over the next decade hinges on regulatory pathway clarity and reimbursement code expansion for home-based testing. Watch FDA premarket review pathway convergence with EMA IVDR standards as the inflection signal for accelerated geographic launch sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA IVDR Class C compliance unlocks German hospital procurement committee access for high-plex respiratory panels. |
| Hospital System Partnership | Multi-platform standardization agreements with Rhine-Ruhr metropolitan networks reduce training complexity and improve supply resilience. |
| Software Companion Development | AI-assisted result interpretation on handheld readers expands deployability to non-laboratory personnel in Chinese field settings. |
| Reimbursement Strategy | CMS antimicrobial stewardship mandate alignment secures procurement preference for integrated resistance gene detection platforms. |
| Backward Integration | Captive polymer substrate fabrication in Suzhou insulates margin structures from East Asian supplier concentration risk. |
Methodological Framework
Operator-level perspectives from emergency department physicians, hospital procurement managers, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA IVDR submissions, hospital procurement databases, and CMS reimbursement data. Bottom-up test volume modeling and top-down market sizing triangulation cross-checked segment-level assumptions across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory timeline delays and isothermal chemistry adoption curves. Segmentation dimensions modeled include product type, technology platform, end-user setting, application area, and regional regulatory cluster. CAGRs were derived from instrument placement trajectories and consumable pull-through rates, with inputs from infectious disease surveillance mandate implementation schedules and microfluidic chip fabrication capacity expansion plans.
The analysis sits within stated boundaries; outcomes outside FDA-EMA regulatory convergence or sustained CMS reimbursement incentives would require recalibration. Forecasts reflect documented assumptions about isothermal amplification clinical validity improvement and WHO prequalification criteria harmonization with OECD benchmarks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Antibody Testing Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
United Kingdom in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market