
 United Kingdom in-Vitro Diagnostics Market | 2026-2036
United Kingdom in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom in-Vitro Diagnostics Market Analytics
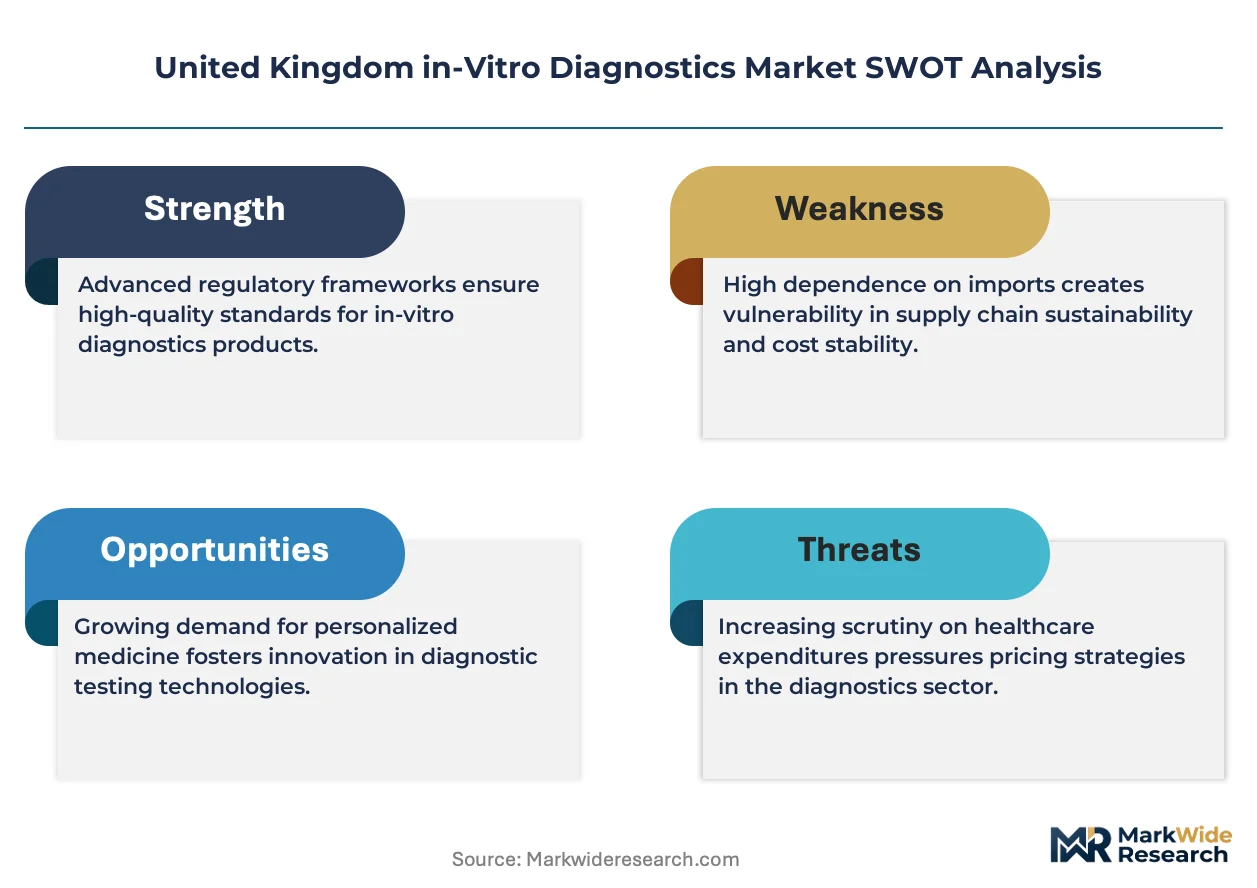
The gap between premium molecular platforms and commodity immunoassay workflows is realigning procurement priorities across NHS trusts and private laboratory networks. Thermo Fisher Scientific Inc. leverages its integrated reagent-instrument ecosystem to sustain high-margin positions in molecular diagnostics. Siemens Healthineers AG anchors its UK presence through extensive installed bases of hematology and immunodiagnostics systems in tertiary hospitals. Abbott Laboratories differentiates via point-of-care connectivity solutions that compete directly with centralized laboratory throughput models.
In-vitro diagnostics encompasses the analysis of biological specimens outside the living organism, utilizing reagent-based chemical reactions, optical detection systems, and software algorithms to quantify analytes with clinical specificity measured in nanograms per milliliter or gene copy numbers. These systems enable disease screening, therapeutic monitoring, and population health surveillance across primary and secondary care settings. Reagents capture the largest value pool given their recurring purchase rhythm and proprietary formulation lock-in, while molecular diagnostics registers the fastest structural expansion driven by oncology companion testing and infectious disease genotyping demand. Instruments retain concentrated margin pools among vendors who bundle long-term service contracts with hardware placement.
The UK Medicines and Healthcare products Regulatory Agency oversees post-Brexit device registration, while the NHS England MedTech Funding Mandate shapes adoption velocity for cost-saving diagnostic innovations. BSI Group operates as a designated UK approved body for CE-UKCA transition assessments, creating compliance bottlenecks that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor how the UKCA marking timeline and NHS Long Term Workforce Strategy intersect to determine whether capital investment or decentralized testing models receive priority funding.
Market Dynamics
NHS England's MedTech Funding Mandate is compressing adoption timelines for cost-saving diagnostic platforms while the UKCA marking transition creates compliance bottlenecks that favor established manufacturers with dedicated regulatory infrastructure.
Growth Catalysts
- Oncology companion testing:Genomic profiling for targeted therapies is expanding molecular diagnostics volumes in England's academic medical center clusters.
- UKCA regulatory framework:Post-Brexit device registration requirements are redirecting conformity assessment pathways toward BSI Group and other UK approved bodies.
- Point-of-care connectivity:Decentralized testing models in primary care networks are competing directly with centralized laboratory throughput for routine immunoassay panels.
Market Restraints
- Reagent supply concentration:Proprietary formulation lock-in creates recurring purchase dependencies that limit NHS trust negotiating leverage.
- Capital intensity of automation:High-throughput molecular platforms require substantial upfront investment that strains pathology network budgets.
- Technical limitation of legacy systems:Immunodiagnostics installed bases in tertiary hospitals face integration friction with newer digital pathology workflows.
Strategic Opportunities
- NHS Long Term Workforce Strategy:Staffing shortages in laboratory medicine create openings for automated sample-to-answer systems that reduce manual processing steps.
- Infectious disease genotyping:Emerging antimicrobial resistance surveillance applications are driving demand for rapid molecular identification platforms.
- Oxford-Cambridge-London triangle:Research-intensive hospital clusters present concentrated opportunities for premium platform placements with academic collaboration tie-ins.
Industry Challenges
- Specialized technician scarcity:Molecular diagnostics operations require trained personnel in nucleic acid extraction and bioinformatics interpretation that NHS laboratories struggle to retain.
- UKCA transition timeline uncertainty:Shifting deadlines for CE marking recognition are forcing manufacturers to maintain dual compliance documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom in-Vitro Diagnostics Market |
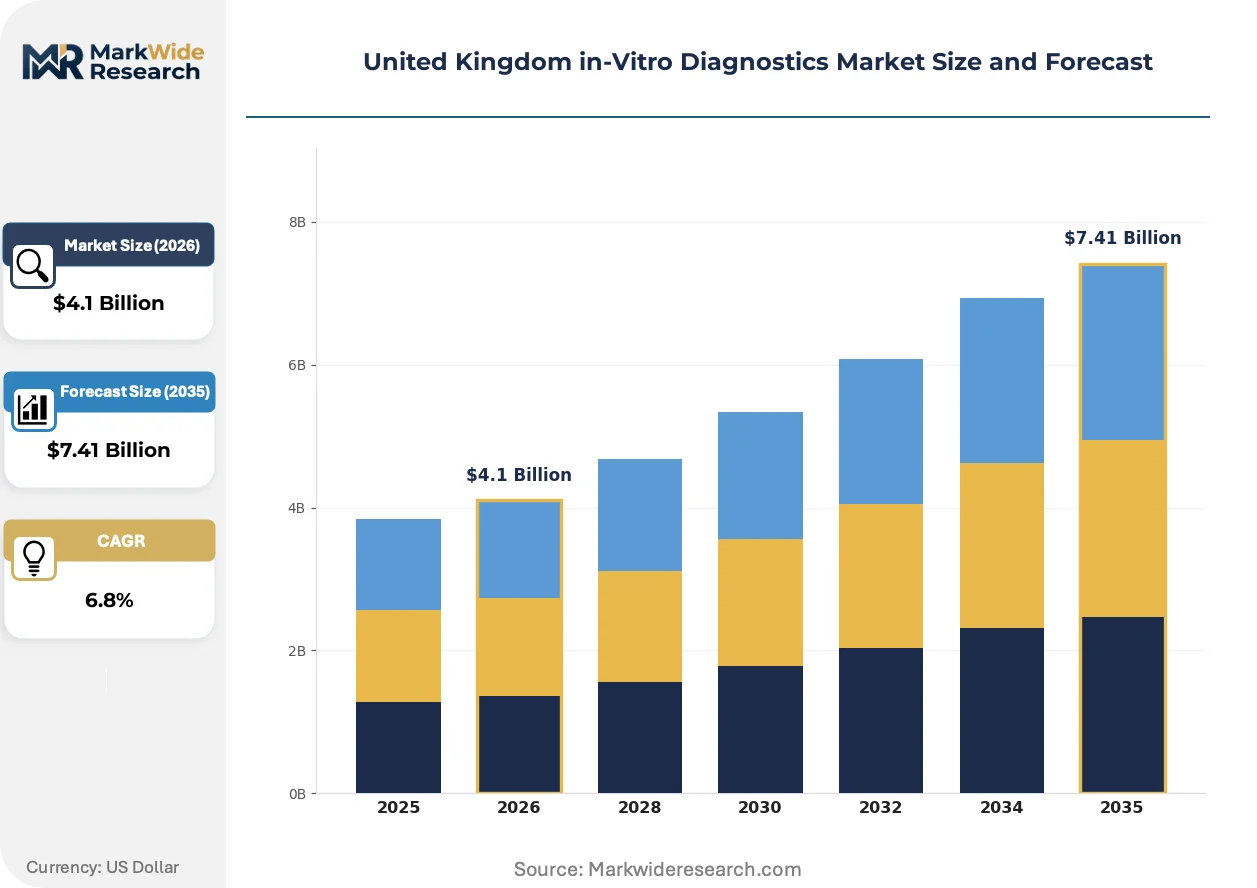
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables End User: Hospitals, Laboratories, Clinics, Home Care Technology: Immunodiagnostics, Molecular Diagnostics, Microbiology, Hematology Application: Infectious Diseases, Cancer, Metabolic Disorders, Pregnancy Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Siemens Healthineers AG, Abbott Laboratories, F. Hoffmann-La Roche AG, QIAGEN N.V., Danaher Corporation, Becton Dickinson and Company, Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom in-Vitro Diagnostics Market Evolving Landscape
Digital pathology integration and artificial intelligence-assisted diagnostic interpretation are restructuring workflow economics across NHS hospital laboratories and private diagnostic networks.
Next-generation sequencing platforms with automated library preparation are overtaking traditional Sanger sequencing for hereditary cancer screening panels. Regional genetics laboratories in Manchester and Birmingham are consolidating volumes onto centralized high-capacity instruments. This concentration is compressing per-test costs while extending turnaround times for non-urgent cases.
The UK Medicines and Healthcare products Regulatory Agency's post-Brexit framework is diverting conformity assessment resources toward UKCA marking timelines. Manufacturers with existing CE-IVD portfolios face parallel documentation burdens that delay new product introductions. Molecular diagnostics vendors are responding by prioritizing UK-specific regulatory affairs staffing in London and Cambridge.
Consolidated procurement frameworks through NHS Supply Chain are displacing trust-level purchasing autonomy for high-value instrument acquisitions. Private laboratory networks and independent pathology providers are capturing residual demand for specialized testing outside national contract scope. This bifurcation is most visible in London's hospital group structures where foundation trusts maintain separate negotiating positions.
United Kingdom in-Vitro Diagnostics Market Segmentation
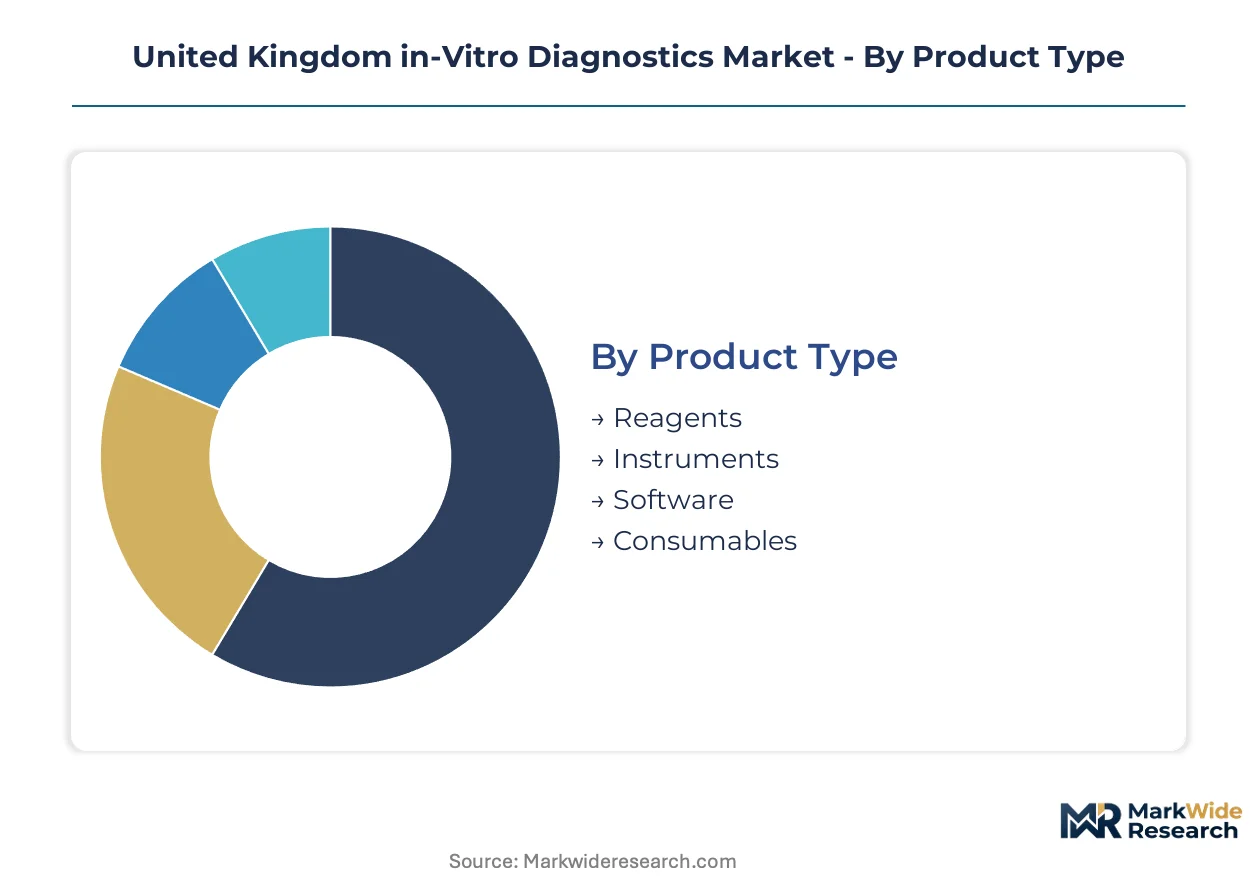
Segmentation in the United Kingdom in-Vitro Diagnostics Market reveals how procurement priorities diverge across NHS trusts, private laboratories, and primary care networks. Each dimension carries distinct regulatory burdens, cost structures, and automation requirements that shape vendor positioning.
Product Type:
UKCA marking requirements from the Medicines and Healthcare products Regulatory Agency apply differentially across hardware and consumable categories, with instruments facing extended conformity assessment timelines.
- Reagents:Proprietary chemical formulations with locked-in purchase rhythms generate recurring revenue streams. NHS hospital laboratories concentrate procurement through national frameworks, while private pathology networks negotiate direct supply agreements for specialized panels.
- Instruments:Automated analyzers and molecular platforms require substantial capital commitment and long-term service contracts. England's academic medical center clusters in the Oxford-Cambridge-London triangle prioritize high-throughput systems with sample-to-answer capabilities.
- Software:Laboratory information management systems and AI-assisted diagnostic interpretation tools.
- Consumables:Pipette tips, collection vessels, and disposable reaction cartridges.
Reagents sit at the top of the volume ranking, with software climbing the fastest.
End User:
Customer type determines whether procurement flows through NHS Supply Chain consolidation or maintains trust-level autonomy.
- Hospitals:Tertiary NHS foundation trusts operate centralized pathology departments with extensive installed bases of hematology and immunodiagnostics systems. The NHS Long Term Workforce Strategy pressures these sites toward automation that reduces manual processing steps.
- Laboratories:Regional genetics laboratories in Manchester and Birmingham consolidate volumes onto high-capacity instruments. Consolidated procurement frameworks displace independent purchasing for molecular diagnostics platforms.
- Clinics:Primary care networks in England deploy point-of-care connectivity solutions that compete with centralized laboratory throughput for routine immunoassay panels.
- Home Care:Self-testing devices for glucose monitoring and pregnancy detection.
Hospitals dominate current procurement value, with clinics gaining share fastest through decentralized testing expansion.
Technology:
Maturity curves and margin profiles vary sharply across detection methodologies.
- Immunodiagnostics:Established chemiluminescence and enzyme-linked immunosorbent assay platforms dominate routine screening. Legacy installed bases in tertiary hospitals face integration friction with digital pathology workflows.
- Molecular Diagnostics:Polymerase chain reaction and next-generation sequencing platforms enable genomic profiling for oncology companion testing. Demand concentrates in England's research-intensive hospital clusters with academic collaboration tie-ins.
- Microbiology:Culture-based identification and antimicrobial susceptibility testing systems.
- Hematology:Automated cell counters and coagulation analyzers for routine clinical chemistry.
Immunodiagnostics commands the largest installed base, while molecular diagnostics follows the steepest expansion trajectory.
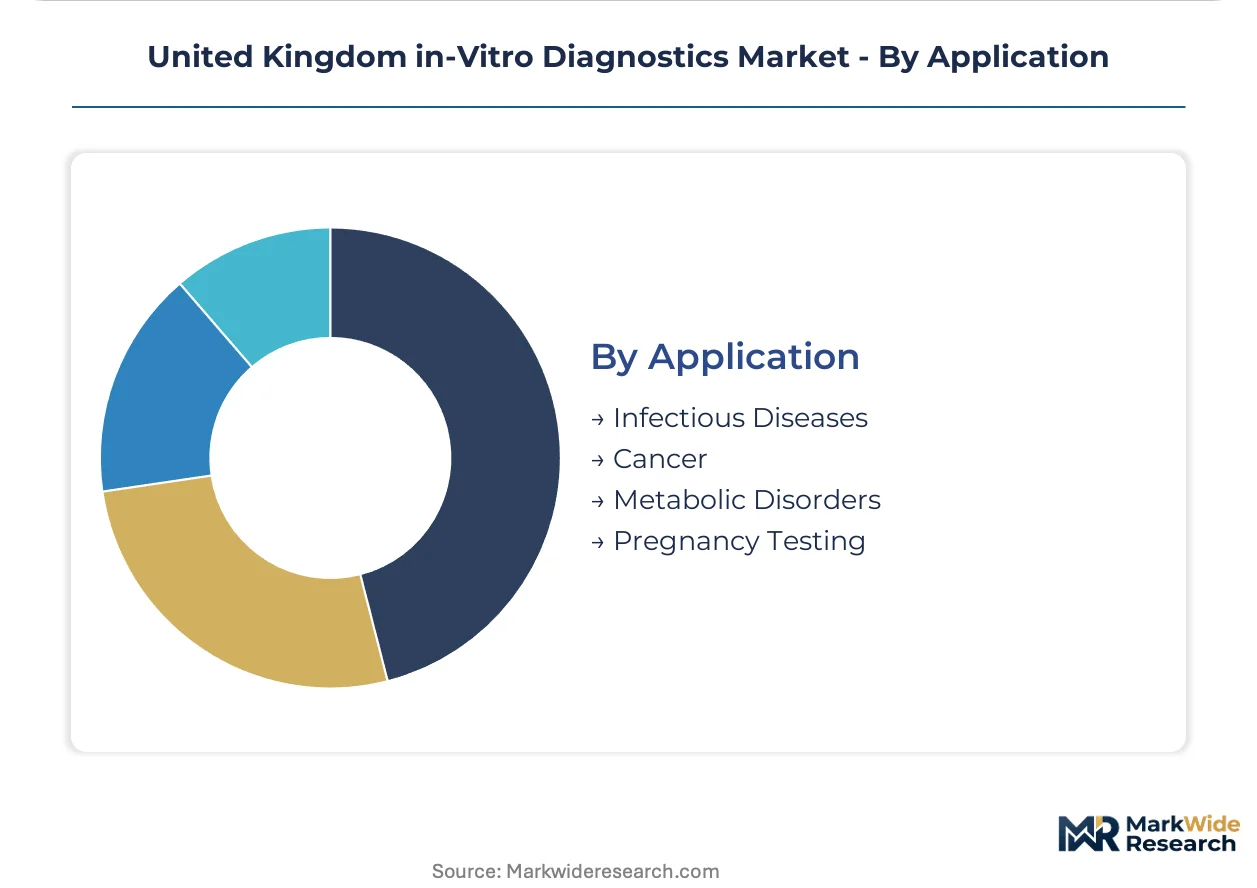
Application:
Clinical utility and reimbursement pathways shape segment economics.
- Infectious Diseases:Respiratory panel testing and antimicrobial resistance surveillance drive molecular platform utilization. Emerging genotyping applications for infection control create demand for rapid identification systems.
- Cancer:Hereditary screening panels and companion diagnostics for targeted therapies. Regional genetics laboratories consolidate oncology testing volumes to compress per-test costs.
- Metabolic Disorders:Diabetes monitoring and thyroid function testing through immunoassay workflows.
- Pregnancy Testing:Over-the-counter and clinical hCG detection products.
Infectious diseases leads in test volume throughput, with cancer applications expanding most quickly through precision medicine adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England commands the largest share of UK in-vitro diagnostics procurement, while Scotland and Wales operate under devolved health frameworks with distinct purchasing autonomy. Northern Ireland maintains cross-border regulatory alignment with Ireland that complicates UKCA transition timelines.
England
Oncology companion testing and infectious disease genotyping drive molecular diagnostics demand across NHS foundation trusts. The NHS England MedTech Funding Mandate accelerates adoption of cost-saving automated platforms. The Oxford-Cambridge-London triangle concentrates academic medical center clusters where premium instrument placements carry research collaboration requirements.
Scotland
Regional genetics laboratories in Glasgow and Edinburgh consolidate testing volumes onto centralized high-capacity sequencers. NHS Scotland operates procurement frameworks separate from NHS Supply Chain England. The Scottish National Blood Transfusion Service anchors specialized immunohematology capabilities in Edinburgh.
Wales
Pathology network consolidation under Velindre University NHS Trust reduces redundant instrument investments across South Wales. The Welsh Government's Test Trace Protect program created surge capacity in molecular diagnostics during respiratory panel expansion. Cardiff-based laboratories serve as reference hubs for rare disease screening.
Northern Ireland
Dual compliance requirements with UKCA and residual CE marking recognition strain regulatory resources for Belfast-based hospital laboratories. The Department of Health Northern Ireland maintains separate technology appraisal processes from NICE England. Regional genetics services concentrate in Belfast Health and Social Care Trust facilities.
United Kingdom in-Vitro Diagnostics Market Competitive Landscape
Top-tier vendors anchor the molecular diagnostics and immunodiagnostics segments, while mid-tier specialists compete on point-of-care connectivity and regional service presence. The vendor base stratifies across integrated reagent-instrument ecosystems, standalone platform manufacturers, and consumables-focused suppliers. Two dominant archetypes emerge: full-stack diagnostic conglomerates bundling hardware, reagents, and software; and focused molecular specialists leveraging NGS automation. Competitive moves concentrate on long-term service contract bundling and automated sample-to-answer system development.
Within the integrated ecosystem tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the reagent-instrument bundling archetype that locks in recurring revenue streams. Siemens Healthineers AG occupies a position among European-headquartered conglomerates with extensive installed bases in tertiary hospital hematology and immunodiagnostics. These three entities represent the concentration of vendor-side negotiating leverage against NHS Supply Chain consolidation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| QIAGEN N.V. |
| Danaher Corporation |
| Becton Dickinson and Company |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Specialty chemical feedstock indices for diagnostic reagent precursors cascade through UK supply chains into three-tier pricing structures across premium, standard, and economy instrument tiers. NHS Supply Chain consolidation amplifies volume leverage against vendors while UKCA compliance costs concentrate margin pressure on mid-tier manufacturers.
Pricing Analysis
Capacity additions in Ireland and the Netherlands are reshaping price floors for molecular reagent manufacturing across the UK market. Contract-based long-term offtake agreements dominate high-throughput platform procurement, with price differentiation hinging on UKCA certification tier and after-sales service bundling. Cost compression in standard-tier immunoassay consumables is intensifying because NHS national frameworks extract volume discounts. Primary care networks exhibit highest price sensitivity, while Oxford-Cambridge-London academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
UKCA marking requirements and IVDR technical documentation standards gate supplier qualification for reagent and instrument categories. Manufacturing concentrates in Germany, the United States, and Singapore for high-precision optical components and polymerase chain reaction thermal cyclers. Raw material dependencies include fluorophore-labeled antibodies, synthetic oligonucleotides, and medical-grade plastics. Single-source vulnerability persists for next-generation sequencing flowcell production. Distribution runs through NHS Supply Chain regional distribution centers and direct-to-laboratory agreements with private pathology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK in-vitro diagnostics market functions as a geographic-arbitrage play where regulatory divergence between the UKCA framework and residual CE marking recognition in Ireland creates compliance cost differentials for manufacturers serving both markets.
For Market Incumbents: Deploy long-term service contract bundling to lock in NHS trust recurring revenue against emerging point-of-care connectivity competitors. Consolidate regulatory affairs infrastructure in Cambridge and London to absorb UKCA transition documentation burdens. Counter specialized molecular diagnostics entrants by accelerating automated sample-to-answer system development that reduces NHS laboratory staffing dependencies. For New Entrants and Emerging Players: Capture residual demand from independent pathology providers in London foundation trusts that maintain separate negotiating positions outside NHS Supply Chain consolidation. Target infectious disease genotyping applications where antimicrobial resistance surveillance programs create procurement urgency. Enter through software companion development partnerships with established instrument manufacturers rather than capital-intensive hardware competition. For Investors and Strategic Acquirers: Asymmetric upside sits with molecular diagnostics specialists possessing UKCA-approved next-generation sequencing platforms and existing NHS reference laboratory relationships. Long-term viability hinges on navigating the intersection of NHS Long Term Workforce Strategy automation mandates and MedTech Funding Mandate cost-saving requirements. Watch for inflection signals in NHS England pathology network consolidation timelines that determine centralized versus decentralized testing capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Pathway | BSI Group assessment bottlenecks favor manufacturers with dedicated London regulatory affairs teams. |
| Hospital System Partnership | Oxford-Cambridge-London triangle placements require academic collaboration tie-ins for premium platforms. |
| Software Companion Development | AI-assisted diagnostic interpretation tools capture margin pools beyond hardware commoditization. |
| Reimbursement Strategy | NHS England MedTech Funding Mandate accelerates adoption for cost-saving automated sample-to-answer systems. |
| Reagent Manufacturing Scale-Up | Proprietary formulation lock-in generates recurring revenue streams resistant to NHS procurement pressure. |
Research Methodology
Multiple input streams — procurement database analysis, regulatory filing review, and laboratory operations benchmarking — were reconciled across primary interviews with NHS pathology network directors, biomedical engineers at tertiary foundation trusts, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from MHRA device registration databases, NHS Supply Chain tender announcements, BSI Group conformity assessment timelines, and hospital laboratory capital expenditure disclosures. Bottom-up instrument placement and reagent volume estimates were triangulated against top-down market sizing from national health expenditure accounts.
Historical procurement patterns were cross-referenced against expert panel inputs from laboratory medicine consultants and diagnostic industry executives. The analytical framework segmented volumes across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs were derived from regression analysis of installed base expansion rates and test volume per-capita trends against NHS workforce and funding trajectory assumptions. Forecast inputs incorporated UKCA transition timeline scenarios and NHS Long Term Workforce Strategy automation adoption curves.
Underlying measurement precision varies by segment; reagent procurement through national frameworks carries tighter precision than decentralized point-of-care device placement in primary care networks. Forecasts reflect assumptions regarding NHS capital allocation priorities and MHRA regulatory resource capacity. A model refresh is warranted upon material change in NHS England MedTech Funding Mandate eligibility criteria or UKCA marking deadline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Global Serological Testing Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Extraction Kits Market
Diagnostics
Semen Analysis Systems Market