
 Global Digital Diagnostics Market | 2026-2036
Global Digital Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Diagnostics Market Foresight
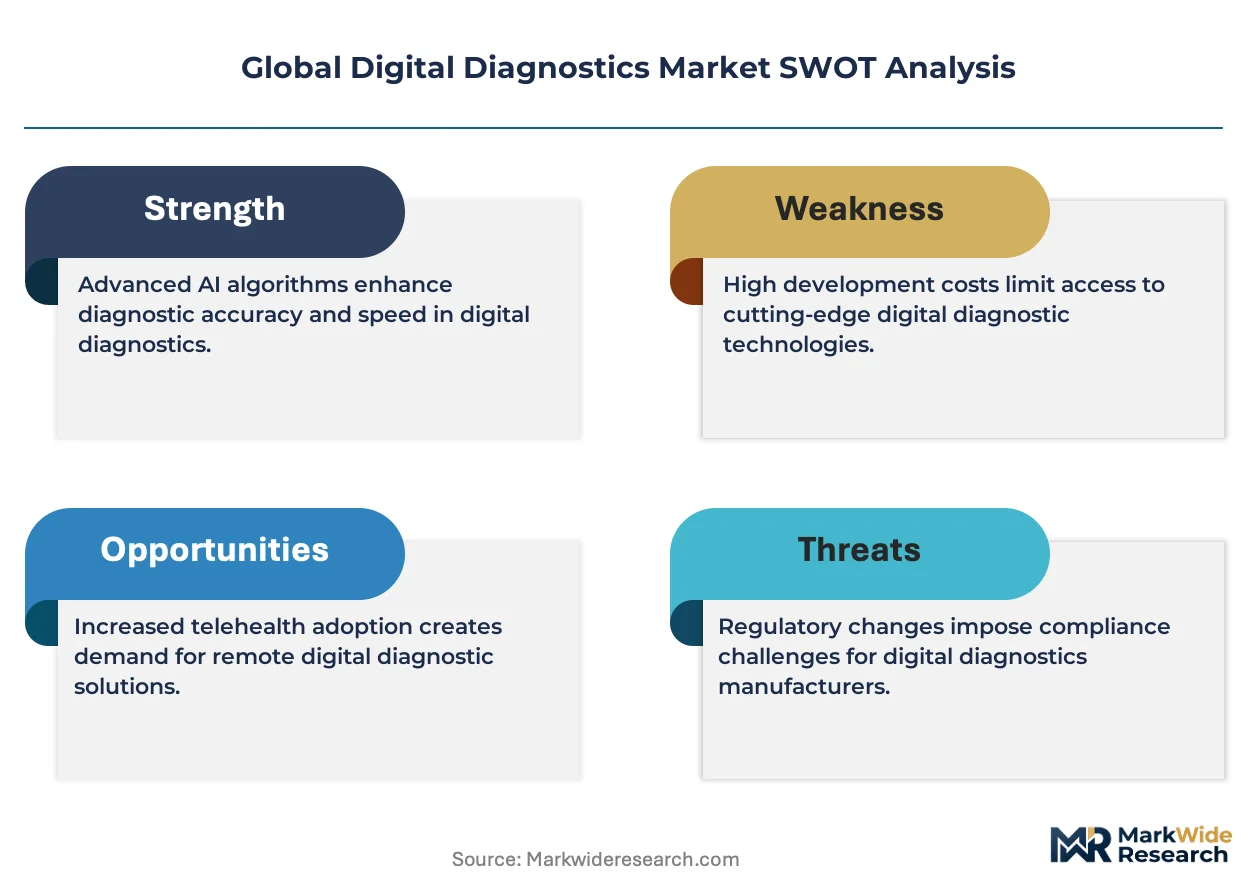
Capital-intensity divergence between imaging hardware manufacturers and cloud-native diagnostic software developers is bifurcating competitive dynamics across the sector. Siemens Healthineers leverages its installed base of MRI and CT systems to integrate AI overlays directly at the point of image acquisition. Digital Diagnostics Inc. specializes in autonomous diagnostic algorithms that operate without specialist interpretation, anchoring its position in primary care workflows.
Digital diagnostics encompasses computational tools that analyze clinical data—ranging from radiological images to genomic sequences—through algorithmic processing to generate diagnostic outputs with defined sensitivity and specificity thresholds. These systems serve to augment or replace human expert judgment in disease detection, risk stratification, and treatment selection across care settings. Molecular diagnostics and artificial intelligence segments are capturing disproportionate R&D investment as regulatory pathways for algorithm-based devices mature faster than for hardware-dependent platforms. Point of care devices, by contrast, occupy established margin pools in infectious disease monitoring but face compression as smartphone-connected peripherals commodify basic testing functions.
The FDA maintains premarket review authority over software-as-a-medical-device products through its Digital Health Center of Excellence, while the EU AI Act imposes risk-classification requirements on diagnostic algorithms deployed in European clinical environments. China's NMPA has accelerated approval timelines for AI-assisted imaging devices, reshaping market access priorities for multinational manufacturers. Stakeholders must monitor divergence between jurisdictional validation requirements as a determinant of product development sequencing and commercial launch timing.
Market Dynamics
The EU AI Act risk-classification framework is forcing algorithm developers to restructure clinical validation protocols before European market entry, compressing product launch timelines and redirecting R&D budgets toward compliance infrastructure.
Growth Catalysts
- FDA Digital Health Center of Excellence premarket pathways:Streamlined software-as-a-medical-device reviews accelerate commercialization timelines for autonomous diagnostic algorithms in the United States.
- Smartphone-connected peripherals:Infectious disease monitoring at the point of care expands access to molecular diagnostics in resource-limited settings without laboratory infrastructure.
- China NMPA accelerated approvals:AI-assisted imaging devices gain faster market access, incentivizing multinational manufacturers to prioritize Chinese regulatory submissions.
Market Restraints
- GPU and specialized compute hardware costs:Training foundation models for diagnostic imaging requires sustained capital outlays that exclude mid-tier developers from frontier capabilities.
- Jurisdictional validation divergence:FDA, EMA, and NMPA maintain non-harmonized performance thresholds, forcing redundant clinical studies across regulatory regimes.
- Cloud infrastructure concentration:Three hyperscalers dominate health data hosting, creating single-point-of-failure risks for diagnostic platform continuity.
Strategic Opportunities
- Primary care workflow integration:Autonomous diagnostic algorithms that operate without specialist interpretation address physician shortage gaps in rural United States markets.
- EU AI Act compliance services:Risk-management system documentation and conformity assessment support create adjacent revenue streams for quality consultancies.
- Genomic sequence analysis convergence:Integration of liquid biopsy data with radiological AI outputs enables multi-modal cancer screening protocols.
Industry Challenges
- Clinical informatics talent scarcity:Shortage of professionals fluent in both algorithm development and regulatory science slows validation team scaling.
- Legacy PACS integration complexity:Hospital radiology departments require custom middleware to embed AI overlays into existing Siemens, GE, and Philips imaging architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Diagnostics Market |
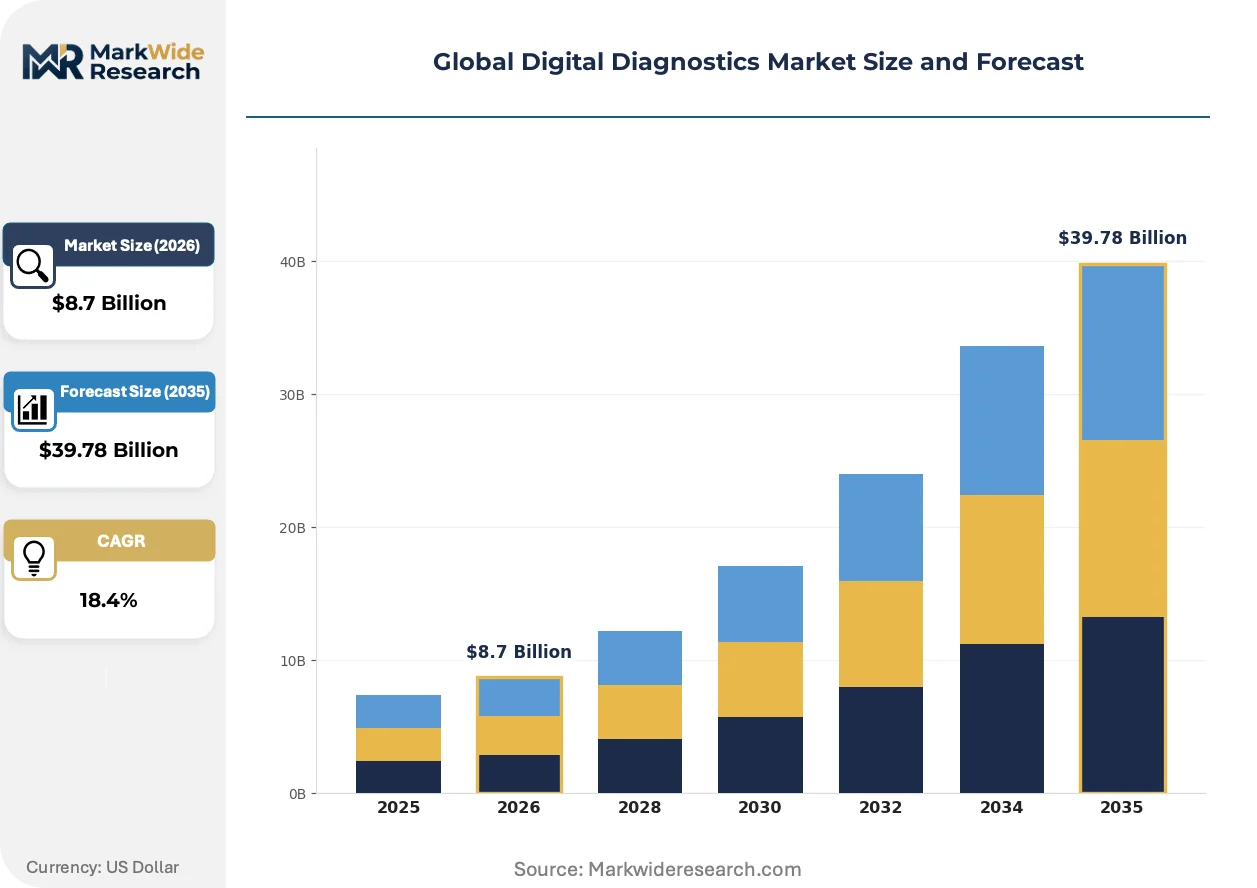
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Molecular Diagnostics, Point of Care Devices, Laboratory Information Systems, Clinical Decision Support, Telehealth Platforms Technology: Artificial Intelligence, Machine Learning, Digital Pathology, Cloud Computing, Mobile Health, Wearable Sensors Application: Chronic Disease Detection, Infectious Disease Monitoring, Genetic Testing, Personalized Medicine, Remote Patient Monitoring, Preventive Screening End User: Hospitals, Diagnostic Labs, Research Institutions, Telemedicine Providers, Specialty Clinics, Academic Centers |
| Companies Covered | GE Healthcare, Siemens Healthineers, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Koninklijke Philips N.V., Danaher Corporation, Abbott Laboratories, Hamamatsu Photonics K.K., Digital Diagnostics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Diagnostics Market Shifts & Advancements
Computational diagnostic hardware is collapsing into handheld and wearable form factors, while regulatory frameworks fragment across jurisdictions and procurement patterns shift toward subscription-based clinical decision support.
Portable ultrasound devices with embedded neural processing units are miniaturizing traditional cart-based imaging systems into battery-operated probes. Emergency departments and rural clinics in India and Brazil adopt these units for cardiac and obstetric screening. The form-factor reduction is miniaturizing capital requirements for imaging deployment, eroding the installed-base advantage of traditional hardware manufacturers.
The EU AI Act imposes conformity assessment obligations on high-risk diagnostic algorithms before European market deployment. Developers must establish risk-management systems and post-market monitoring protocols that exceed FDA software documentation requirements. AI-assisted radiology tools face the steepest compliance burden, with several manufacturers delaying European launches to rebuild validation datasets.
Hospital networks in the United States consolidate diagnostic software purchasing under centralized IT procurement offices. Traditional radiology department autonomy over imaging AI selection gives way to enterprise-wide clinical decision support contracts. Subscription pricing with per-study fees displaces perpetual licenses, compressing vendor cash conversion cycles and intensifying customer concentration risk.
Global Digital Diagnostics Market Segmentation
Segmentation in digital diagnostics reveals divergent capital requirements, regulatory pathways, and customer procurement patterns across product architectures. Distinct technology stacks command separate validation protocols and pricing models.
Product Type:
Domestic procurement concentrates in imaging hardware and point-of-care devices, while cloud-native platforms generate export-led revenue through multinational hospital network contracts.
- Imaging Systems:MRI and CT platforms with embedded neural processing units enable real-time inference at the point of acquisition. Siemens Healthineers and GE Healthcare dominate hospital procurement in Germany and the United States, though GPU-accelerated reconstruction algorithms inflate service contract pricing.
- Molecular Diagnostics:PCR and sequencing-based platforms analyze nucleic acid biomarkers for infectious and oncological applications. Chinese and South Korean manufacturers scale production for Southeast Asian export markets, where laboratory infrastructure gaps sustain demand for compact, automated systems.
- Point of Care Devices:Handheld analyzers for glucose, infectious disease, and cardiac markers bypass centralized laboratory workflows.
- Laboratory Information Systems:Middleware connecting analytical instruments to hospital electronic health records.
- Clinical Decision Support:Algorithmic risk stratification tools integrated into physician workflow software.
- Telehealth Platforms:Remote consultation infrastructure with diagnostic data integration capabilities.
Imaging Systems commands the established base. The steepest expansion runs through Clinical Decision Support.
Technology:
Cost tiers separate foundation-model developers requiring hyperscaler compute contracts from edge-deployment specialists optimizing for battery-constrained devices.
- Artificial Intelligence:Deep learning architectures for image classification, natural language processing of clinical notes, and predictive risk modeling. FDA premarket submissions for autonomous diagnostic algorithms exceed 150 active filings, with radiology applications capturing the largest validation investment.
- Machine Learning:Traditional statistical learning methods for structured clinical data analysis and biomarker discovery.
- Digital Pathology:Whole-slide imaging with computational analysis of histological specimens.
- Cloud Computing:Scalable infrastructure for diagnostic algorithm training and inference serving.
- Mobile Health:Smartphone-connected peripherals and application-based symptom assessment tools.
- Wearable Sensors:Continuous physiological monitoring devices with algorithmic anomaly detection.
Cloud Computing anchors current infrastructure spending. Wearable Sensors is climbing the fastest as continuous monitoring protocols expand beyond cardiac applications into metabolic and respiratory tracking.
Application:
Volume concentration varies sharply between high-frequency screening programs and low-incidence genetic testing, with reimbursement status determining geographic deployment patterns.
- Chronic Disease Detection:Algorithmic screening for diabetes, cardiovascular conditions, and renal impairment through retinal imaging, ECG analysis, and biomarker panels. India's national diabetes screening program deploys AI-assisted fundus cameras in primary health centers, creating concentrated demand for autonomous diagnostic devices.
- Infectious Disease Monitoring:Rapid molecular and antigen detection for respiratory, sexually transmitted, and hospital-acquired infections.
- Genetic Testing:Germline and somatic variant analysis for hereditary risk assessment and oncology profiling.
- Personalized Medicine:Pharmacogenomic and biomarker-guided therapy selection platforms.
- Remote Patient Monitoring:Continuous data collection for post-acute and chronic condition management.
- Preventive Screening:Population-scale early detection programs for cancer and metabolic disorders.
Chronic Disease Detection holds the largest installed base. Preventive Screening is gaining share fastest as national health systems in Japan and the United Kingdom expand funded cancer detection programs.
End User:
Customer type determines procurement autonomy, with hospital network consolidation shifting vendor selection power from clinical departments to centralized IT governance.
- Hospitals:Integrated delivery networks in the United States consolidate diagnostic software purchasing under enterprise IT procurement offices, displacing traditional radiology department autonomy over imaging AI selection. Subscription pricing with per-study fees compresses vendor cash conversion cycles.
- Diagnostic Labs:High-throughput reference laboratories and regional testing facilities.
- Research Institutions:Academic medical centers and translational research programs.
- Telemedicine Providers:Virtual-first care platforms requiring asynchronous diagnostic capabilities.
- Specialty Clinics:Cardiology, dermatology, and ophthalmology focused outpatient facilities.
- Academic Centers:Teaching hospitals with dual clinical and research missions.
Hospitals represent the dominant revenue concentration. Telemedicine Providers is expanding most quickly as virtual-first care models scale in Brazil and Indonesia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement elasticity varies sharply across jurisdictions. German buyers absorb premium pricing for EU AI Act-compliant systems, while Indian primary care centers prioritize low-cost autonomous diagnostic devices. United States health networks balance regulatory stringency with volume scale.
United States
Hospital network consolidation drives enterprise-wide clinical decision support contracts. FDA Digital Health Center of Excellence premarket pathways streamline software-as-a-medical-device approvals. The Boston-Cambridge cluster anchors AI diagnostic algorithm development, with academic medical centers serving as validation partners.
Germany
Siemens Healthineers leverages its installed MRI and CT base to integrate AI overlays at image acquisition points. EU AI Act risk-classification requirements force restructuring of clinical validation protocols. The Erlangen headquarters concentrates imaging hardware R&D alongside regulatory compliance infrastructure.
China
NMPA accelerated approval timelines for AI-assisted imaging devices redirect multinational submission priorities. Domestic manufacturers scale production of compact molecular diagnostics for Southeast Asian export. Shenzhen hardware clusters miniaturize ultrasound systems with embedded neural processing units.
India
National diabetes screening programs deploy AI-assisted fundus cameras in primary health centers. CDSCO regulatory pathways for software-based devices lag hardware approvals, creating commercialization friction. Bengaluru health-tech clusters develop smartphone-connected diagnostic peripherals for rural deployment.
Japan
METI-funded preventive screening expansions drive demand for multi-modal cancer detection platforms. PMDA maintains stringent performance thresholds for autonomous diagnostic algorithms. Tokyo-Osaka medical device corridors concentrate liquid biopsy and radiological AI convergence development.
Global Digital Diagnostics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sector. Imaging hardware manufacturers with deep installed bases compete against cloud-native algorithm developers with minimal capital requirements. Three archetypes dominate: legacy equipment vendors integrating AI overlays, autonomous diagnostic specialists, and molecular diagnostics platform builders. M&A activity concentrates on algorithm acquisitions by hardware incumbents, while strategic partnerships link software developers to hospital network procurement offices.
Among legacy imaging vendors, GE Healthcare and Siemens Healthineers exemplify the equipment-anchored archetype, leveraging service contract relationships to embed diagnostic algorithms at the point of acquisition. Digital Diagnostics Inc. represents the autonomous software specialist, positioning for primary care workflows without specialist interpretation requirements. These three companies illustrate the competitive tension between hardware-dependent and software-native market entry strategies.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Koninklijke Philips N.V. |
| Danaher Corporation |
| Abbott Laboratories |
| Hamamatsu Photonics K.K. |
| Digital Diagnostics Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day validation timelines for EU AI Act conformity assessments compress procurement cycles and concentrate pricing power with established hardware vendors holding pre-certified installed bases. Cloud-native algorithm developers face elongated sales cycles as hospital networks demand bundled service contracts that offset upfront software discounts with multi-year maintenance commitments.
Pricing Analysis
Service contract renewals drive lifetime value for imaging hardware manufacturers, with Siemens Healthineers and GE Healthcare embedding AI overlays into multi-year MRI and CT maintenance agreements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared autonomous algorithms from CE-marked equivalents and research-use-only tools. Cost compression in point-of-care peripherals intensifies as smartphone-connected glucose and infectious disease monitors commodify basic testing functions. Diagnostic laboratories exhibit highest price sensitivity due to reimbursement pressure, while academic medical centers absorb premium pricing for multi-modal cancer screening platforms.
Supply Chain Analysis
Trans-Pacific container availability fluctuations inflate inbound logistics costs for GPU and neural processing unit shipments from Taiwan and South Korea. Specialized compute hardware concentrates in Taiwan Semiconductor Manufacturing facilities and Samsung foundries, with cloud infrastructure for algorithm training drawing from hyperscaler data centers in the United States, Ireland, and Singapore. Single-source vulnerability in photolithography equipment for AI chip fabrication threatens diagnostic platform continuity. Distribution runs through hospital network procurement offices consolidating enterprise-wide clinical decision support contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals fluent in both algorithm development and regulatory science constrains validation team scaling across the sector, amplifying returns for firms that secure this hybrid talent base.
For Market Incumbents: Secure exclusive service contract renewals with German and United States hospital networks before EU AI Act compliance deadlines redirect procurement toward certified competitors. Prioritize backward integration into GPU-accelerated reconstruction algorithm development to defend margin position against cloud-native entrants offering pure-software alternatives. For New Entrants and Emerging Players: FDA Digital Health Center of Excellence premarket pathway acceleration enables faster commercialization than European conformity assessment timelines. Target rural United States primary care markets with autonomous diagnostic algorithms that bypass specialist interpretation requirements. Pursue hospital system partnership models with per-study subscription pricing to displace perpetual license incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional validation divergence creates acquisition opportunities for algorithm developers with multi-market clearance portfolios. Focus on autonomous diagnostic specialists with FDA-cleared radiology applications and emerging molecular diagnostics platform builders. Watch NMPA approval velocity for AI-assisted imaging devices as the inflection signal for Chinese market access prioritization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Digital Health Center of Excellence premarket pathways compress commercialization timelines for autonomous algorithms in radiology applications. |
| CE Marking Pathway Investment | EU AI Act risk-classification compliance creates barrier to entry for mid-tier developers lacking conformity assessment infrastructure. |
| Hospital System Partnership | Enterprise-wide clinical decision support contracts displace radiology department autonomy and concentrate vendor selection power. |
| Software Companion Development | AI overlays for existing Siemens, GE, and Philips imaging architectures reduce legacy PACS integration friction. |
| Reimbursement Strategy | CPT code establishment for autonomous diagnostic algorithms determines Medicare coverage and commercial payer adoption. |
Research Methodology
Desk research of FDA premarket submission databases, EU MDR technical documentation, and hospital procurement contract filings preceded structured interviews with biomedical engineers, GPO contracts managers, regulatory affairs specialists, and clinical informatics directors. Primary fieldwork validated algorithm performance claims and compliance infrastructure investments against secondary sources including CMS Medicare reimbursement data, GPO contract repositories, and NMPA approval registries. Bottom-up segment sizing triangulated with top-down market boundary analysis.
Variance decomposition across product type, technology stack, application area, and end-user procurement autonomy shaped the analytical framework. Segmentation dimensions modeled include imaging hardware versus cloud-native software deployment, AI-assisted versus autonomous diagnostic classification, chronic disease detection versus preventive screening application, and hospital network versus specialty clinic end-user concentration. CAGRs derived from logistic diffusion curves fitted to regulatory approval velocity and procurement pattern shifts. Forecast inputs incorporated EU AI Act implementation timelines and NMPA accelerated approval pathway utilization rates.
Underlying assumptions cover sustained hyperscaler cloud infrastructure investment, stable FDA premarket review staffing levels, and continued hospital network consolidation, with deviation risk concentrated in GPU supply chain disruptions and jurisdictional validation requirement divergence. Recalibration cycles align with material shifts in regulatory approval velocity, reimbursement policy changes, and hospital procurement centralization trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Connected Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market