
 Animal Auto-Immune Disease Diagnostics Market | 2026-2036
Animal Auto-Immune Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Auto-Immune Disease Diagnostics Market Outlook
Subscription-based instrument leasing and reagent rental programs are reshaping competitive access in veterinary diagnostics, allowing mid-sized clinics to deploy ELISA and immunofluorescence platforms without capital outlay. IDEXX Laboratories leverages its installed base of chemistry analyzers to lock in recurring reagent revenue across North American veterinary chains. Zoetis Services LLC anchors its position through field-deployed technical support and species-specific assay menus. Thermo Fisher Scientific competes by extending its human diagnostics manufacturing scale into validated veterinary immunoassay production.
Animal auto-immune disease diagnostics encompass serological, molecular, histopathological, and biochemical procedures that detect pathogenic antibodies, immune complex deposition, or cytokine dysregulation in veterinary patients, typically requiring species-specific reference ranges and controlled assay conditions to distinguish auto-immunity from infectious mimics. The primary commercial purpose is to enable targeted immunosuppressive therapy selection and disease monitoring in companion and production animals. ELISA-based test types dominate current volume due to standardized workflows and multi-analyte panel availability, while PCR segments capture margin pools through referral-lab pricing for rare auto-immune genotype confirmations. Veterinary clinics remain the structural backbone of distribution, though online retail channels are fragmenting reagent procurement for high-throughday practices.
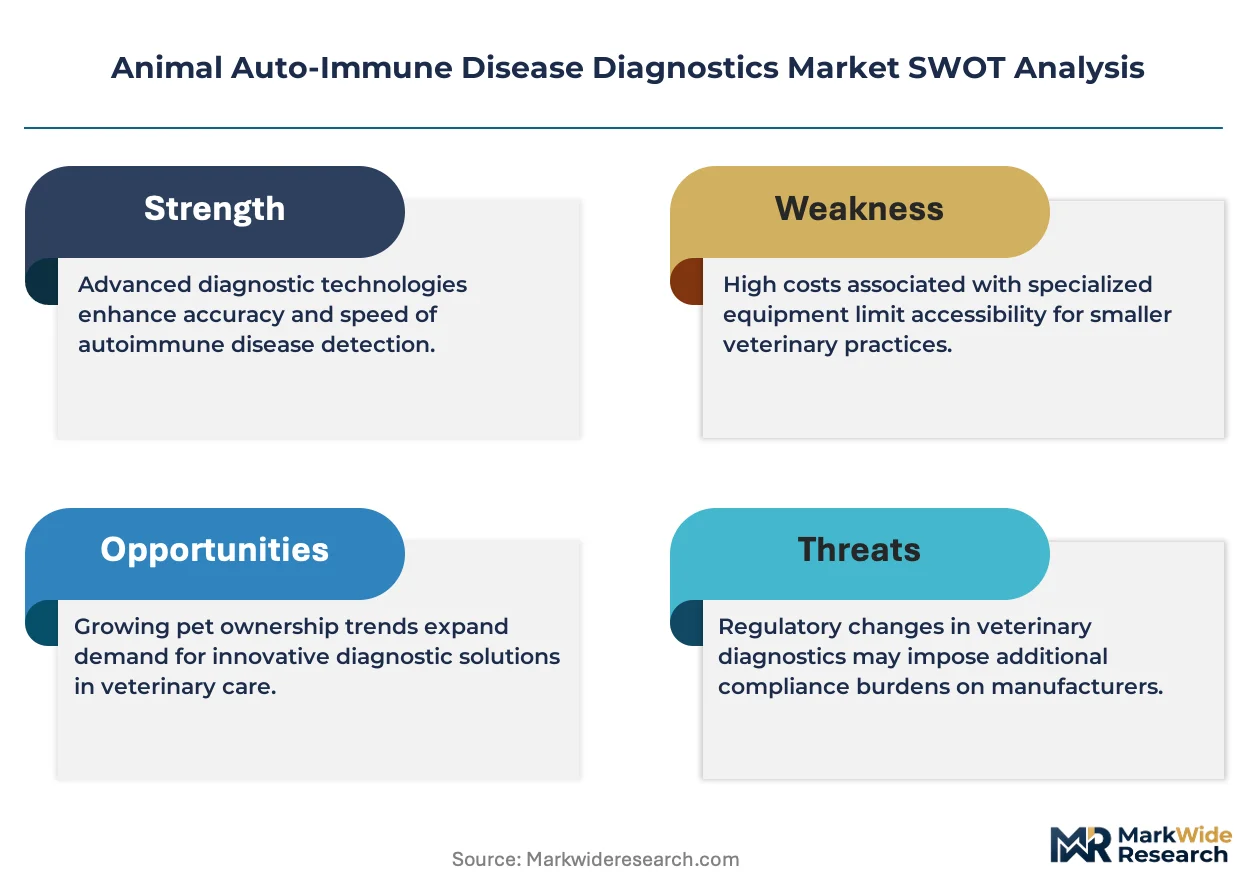
The FDA Center for Veterinary Medicine regulates diagnostic kit safety and labeling claims in the United States, while the USDA Animal and Plant Health Inspection Service governs interstate testing for production animals; the EU Veterinary Medicines Regulation and CE marking requirements shape product access across European member states. These frameworks elevate compliance costs for multi-market entrants but also create barriers that favor established manufacturers with regulatory affairs infrastructure. Stakeholders must monitor evolving species-specific reference standard harmonization efforts and decide whether to build in-house assay development capabilities or outsource to specialized contract diagnostic manufacturers.
Market Dynamics
Subscription-based instrument leasing is compressing capital barriers for mid-sized veterinary clinics, enabling ELISA and immunofluorescence platform deployment without upfront equipment purchases. This financing shift is restructuring competitive access and locking clinics into recurring reagent relationships.
Growth Catalysts
- Pet Insurance Penetration:High coverage rates in the United States reduce out-of-pocket diagnostic costs for companion animal owners, accelerating test authorization frequency.
- CE Marking Harmonization:Streamlined EU Veterinary Medicines Regulation pathways reduce multi-country registration burdens for assay manufacturers entering European member states.
- Species-Specific Reference Range Development:Standardized canine and feline immunology panels improve diagnostic accuracy and drive protocol adoption across referral laboratories.
Market Restraints
- Reagent Supply Concentration:North American manufacturers control critical antibody and conjugate supply chains, exposing purchasers to price volatility and allocation risk.
- USDA Interstate Testing Requirements:Production animal diagnostics face complex APHIS documentation for cross-border sample movement, limiting laboratory network expansion.
- Assay Validation Burden:Species-specific reference standard development demands extended clinical correlation studies, stretching R&D timelines for novel auto-immune markers.
Strategic Opportunities
- Online Retail Channel Expansion:E-commerce platforms are fragmenting reagent procurement for high-throughput practices, bypassing traditional distributor markups.
- PCR Genotype Confirmations:Rare auto-immune disease subtyping creates margin pools through referral-lab pricing models unavailable in routine serology.
- India Veterinary Infrastructure Buildout:Rising companion animal ownership and emerging pet insurance frameworks create underpenetrated demand for immunology testing services.
Industry Challenges
- Veterinary Immunopathology Specialist Shortage:Interpretation of complex auto-immune profiles requires board-certified expertise concentrated in academic referral centers.
- Multi-Market Compliance Complexity:Manufacturers must maintain parallel FDA Center for Veterinary Medicine, USDA APHIS, and EU regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Auto-Immune Disease Diagnostics Market |
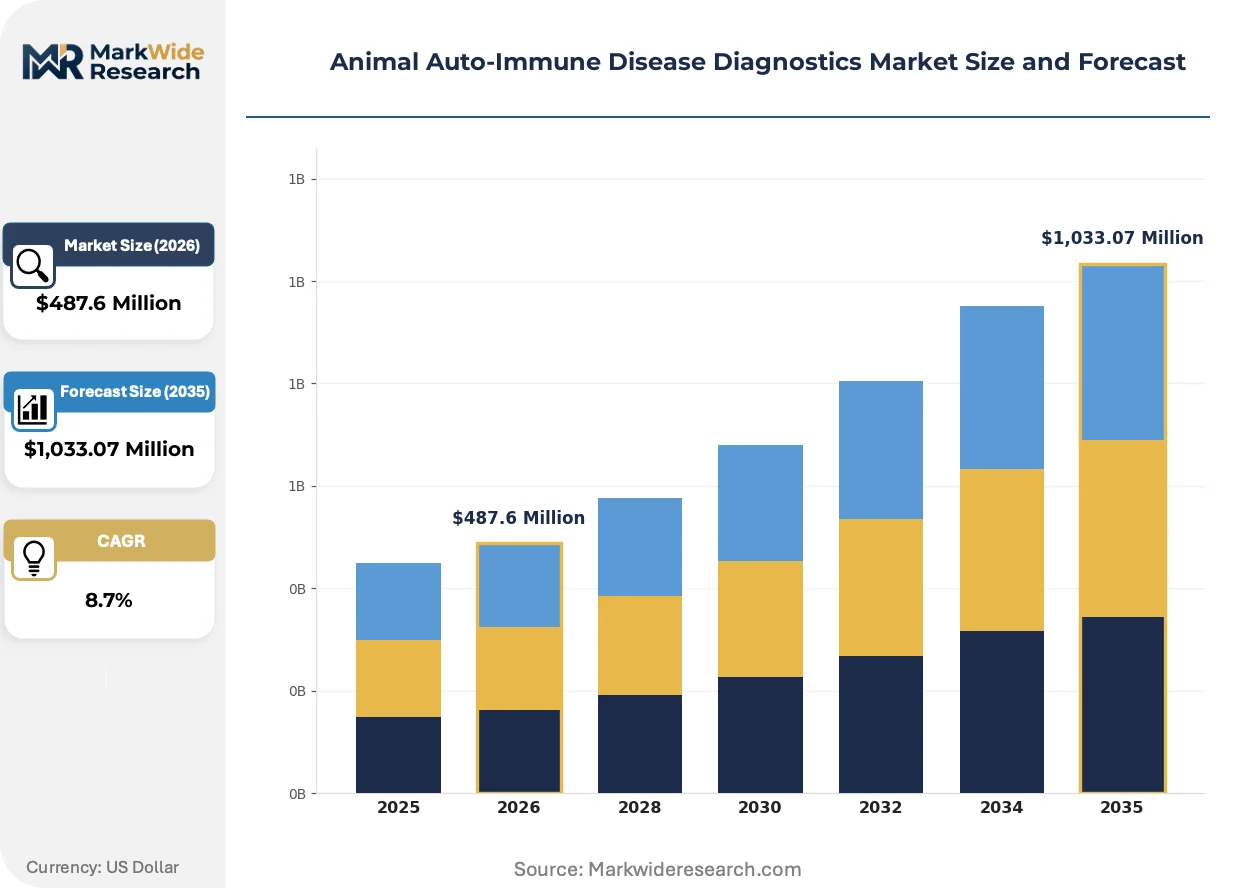
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ELISA, Immunofluorescence, PCR, Western Blot Animal Type: Dogs, Cats, Horses, Cattle Distribution Channel: Veterinary Clinics, Online Retail, Animal Hospitals, Distributors Procedure Type: Serological, Molecular, Histopathological, Biochemical |
| Companies Covered | Hoffmann-La Roche Ltd, Siemens Healthineers, Abbott Laboratories, Beckman Coulter Inc., Thermo Fisher Scientific, Quest Diagnostics, Bio-Rad Laboratories, IDEXX Laboratories, Zoetis Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Auto-Immune Disease Diagnostics Market Strategic Shifts
Digital pathology and cloud-based result interpretation are compressing diagnostic turnaround times and enabling remote specialist consultation. Three developments are restructuring how veterinary auto-immune diagnostics are delivered and consumed.
Multiplex bead-based immunoassay technology is virtualizing traditional single-analyte ELISA workflows by enabling simultaneous cytokine and auto-antibody quantification from minimal sample volumes. University veterinary teaching hospitals are adopting these platforms for immune-mediated disease phenotyping. The technology is virtualizing referral laboratory business models by collapsing panel pricing structures and reducing per-test technical labor requirements.
The FDA Center for Veterinary Medicine's evolving guidance on laboratory-developed tests is tightening quality system expectations for in-house assay validation. Manufacturers must now demonstrate analytical specificity against infectious disease mimics before claiming auto-immune diagnostic utility. United States-based reference laboratories are responding by building dedicated regulatory affairs functions and pre-submission consultation programs.
Pet owners are demanding direct digital access to diagnostic results, bypassing traditional veterinarian-mediated communication channels. Mobile application portals are displacing phone-based result delivery in urban companion animal practices. This behavioral shift is most visible in United States metropolitan markets where pet insurance portals already condition owners to expect real-time claims and outcome visibility.
Animal Auto-Immune Disease Diagnostics Market Segmentation
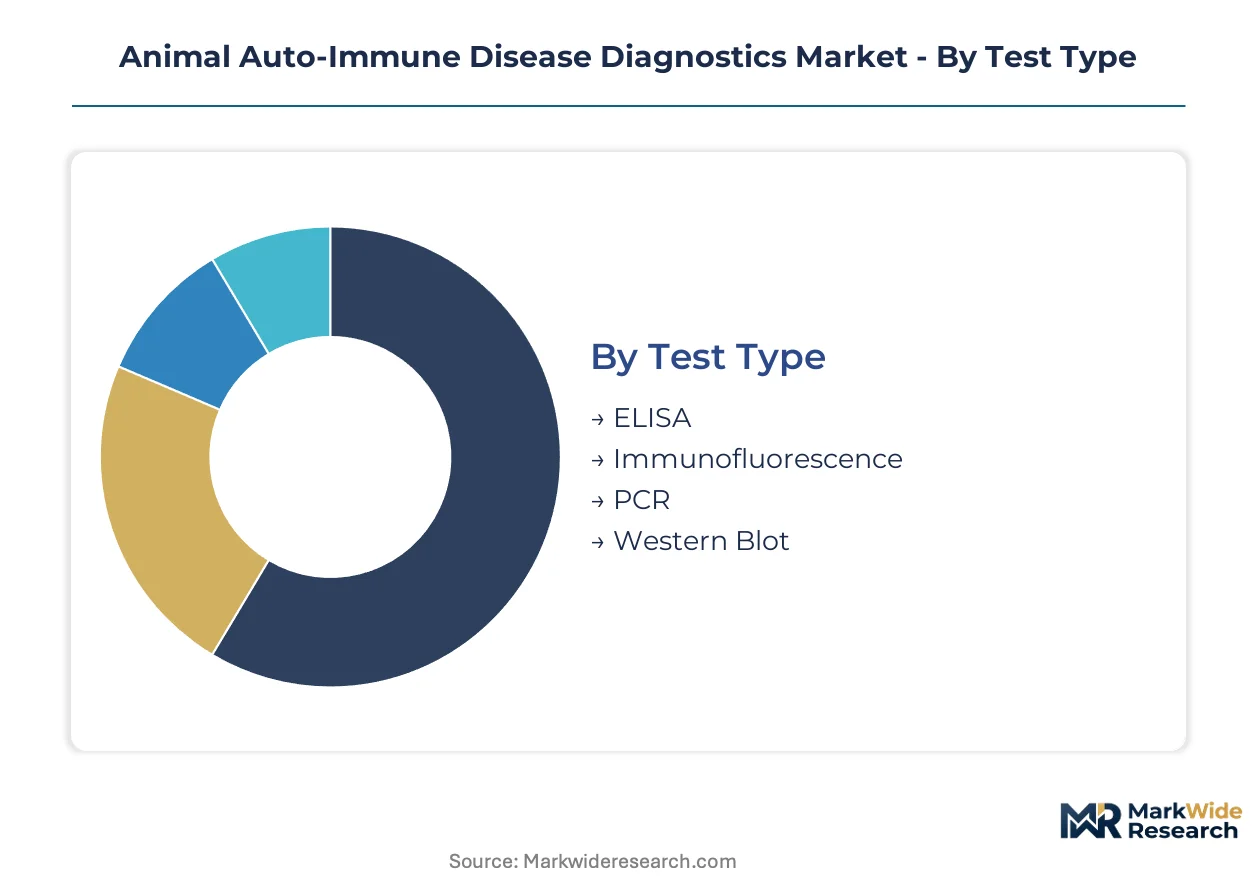
Veterinary diagnostic purchasing cycles vary dramatically across test modalities, with consumable reagents turning over monthly while capital platforms lock clinics into multi-year commitments. Understanding these velocity differentials helps manufacturers align inventory, pricing, and field service deployment to actual consumption patterns rather than aggregated demand signals.
Test Type:
Reagent consumption velocity separates high-frequency screening assays from low-volume confirmatory procedures, with cycle times ranging from weekly restocking to quarterly batch orders.
- ELISA:Enzyme-linked immunosorbent assays deliver standardized multi-analyte quantification through 96-well microplate formats with colorimetric or chemiluminescent readouts. United States veterinary chains concentrate demand here due to pet insurance reimbursement codes that favor documented quantitative results over qualitative screens.
- Immunofluorescence:Direct and indirect fluorescent antibody techniques visualize immune complex deposition patterns in tissue sections or cell substrates. Academic referral laboratories in Germany and the Netherlands anchor specialized demand for antinuclear antibody pattern interpretation in equine and canine systemic lupus cases.
- PCR:Polymerase chain reaction methods amplify rare auto-immune genotype sequences for disease subtyping confirmation.
- Western Blot:Electrophoretic protein separation with antibody probing validates atypical serological findings.
ELISA anchors the volume base while PCR gains share at the steepest rate.
Animal Type:
Species-specific assay development costs create tiered pricing structures, with companion animal panels amortizing R&D across larger installed bases than production animal tests.
- Dogs:Canine immunology panels target immune-mediated hemolytic anemia, thrombocytopenia, and polyarthritis with breed-specific reference ranges. United States metropolitan practices drive volume through wellness screening protocols that bundle thyroid auto-antibody testing with routine chemistry panels.
- Cats:Feline assays address systemic lupus erythematosus and pemphigus complex with species-adjusted cutoffs for low total IgG concentrations. Japanese and United Kingdom specialty clinics concentrate demand for rare purebred screening programs.
- Horses:Equine diagnostics focus on immune-mediated skin disease and recurrent uveitis with large-volume serum requirements.
- Cattle:Bovine applications center on persistent infection differentiation and reproductive auto-immunity in dairy herd health programs.
Canine testing commands the premium tier while feline panels expand most quickly among urban single-pet households.
Distribution Channel:
Channel economics diverge sharply between bundled service contracts and transactional reagent procurement, with margin structures reflecting inventory risk allocation.
- Veterinary Clinics:Primary care and specialty practices purchase through direct sales representatives with instrument-lease-linked reagent commitments. France and Italy show concentrated adoption of this model through consolidated veterinary group purchasing organizations.
- Online Retail:E-commerce platforms enable high-throughput practices to bypass distributor markups on bulk consumables. Australia and Canada demonstrate fastest uptake among multi-site corporate veterinary operators with centralized procurement functions.
- Animal Hospitals:24-hour emergency and referral centers maintain stat testing capabilities with premium pricing for rapid turnaround.
- Distributors:Regional veterinary supply houses provide credit terms and technical support for independent practices.
Veterinary clinics retain the dominant volume position while online retail captures the steepest expansion trajectory among consolidated practice groups.
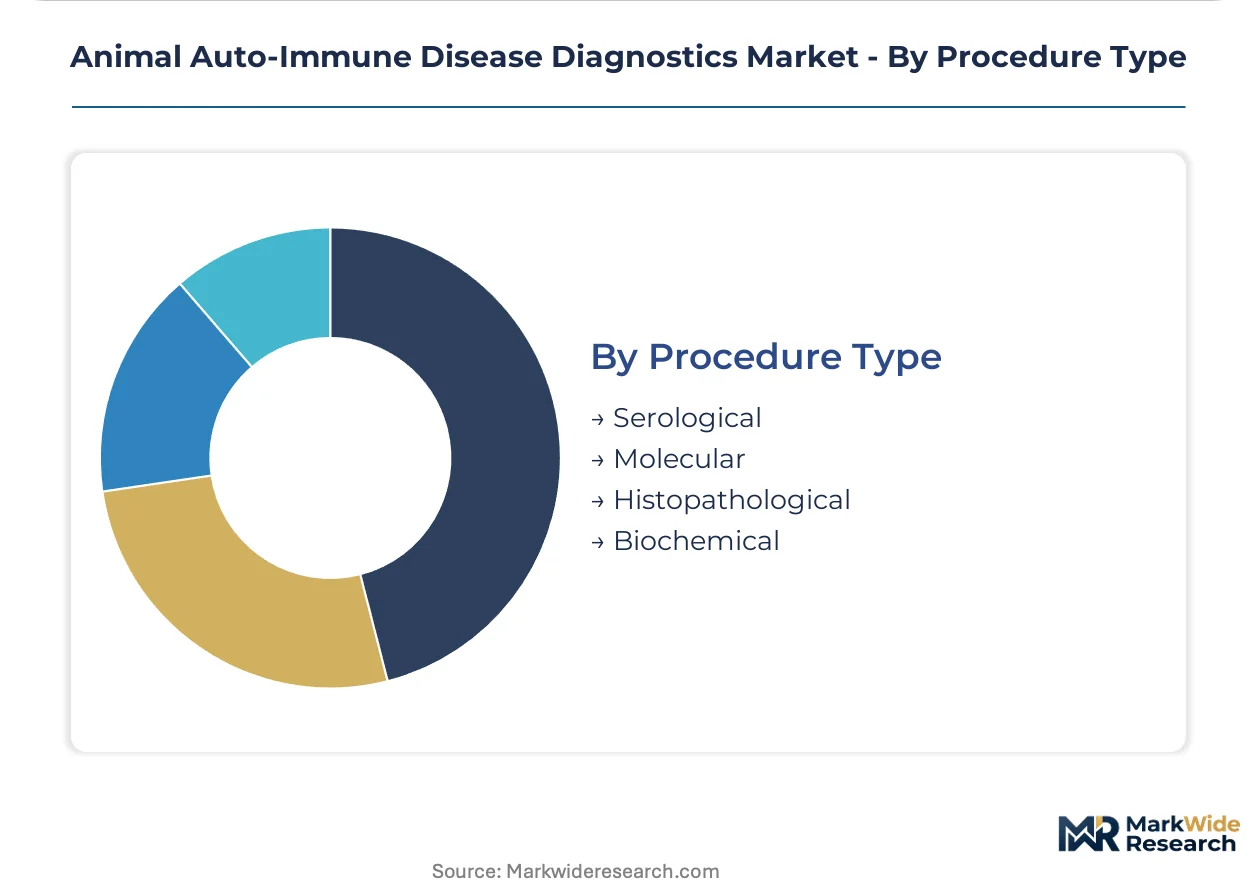
Procedure Type:
Technical complexity and specialist interpretation requirements stratify margins across diagnostic modalities, from automated high-throughput screens to labor-intensive morphological assessments.
- Serological:Antibody detection and immune complex quantification dominate routine screening through standardized ELISA and rapid test formats. Brazil and Mexico concentrate emerging market demand as veterinary laboratory networks expand beyond metropolitan centers.
- Molecular:Nucleic acid amplification and sequencing resolve diagnostic uncertainty in atypical presentations with infectious disease overlap. South Korea and Singapore anchor Asian adoption through university veterinary teaching hospital research programs.
- Histopathological:Tissue biopsy evaluation with immunohistochemical staining requires board-certified pathologist interpretation.
- Biochemical:Serum protein electrophoresis and acute phase protein measurement support disease monitoring.
Serological procedures generate the volume foundation while molecular methods climb the fastest among referral laboratory service menus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance subsidies and veterinary infrastructure grants in the United States accelerate diagnostic test authorization rates for companion animals. Germany's CE marking harmonization reduces multi-country registration burdens for assay manufacturers entering European markets. Japan's aging pet population drives demand for immune-mediated disease screening in metropolitan veterinary clinics.
United States
High pet insurance penetration reduces out-of-pocket diagnostic costs for companion animal owners, accelerating test authorization frequency. The FDA Center for Veterinary Medicine oversees diagnostic kit approvals and safety labeling claims. Greater Boston and Pacific Northwest veterinary teaching hospitals anchor specialized demand for antinuclear antibody pattern interpretation in equine and canine systemic lupus cases.
Germany
Academic referral laboratories in Bavaria and North Rhine-Westphalia concentrate specialized demand for immunofluorescence-based auto-immune phenotyping. The EU Veterinary Medicines Regulation and CE marking requirements shape product access across European member states. Munich and Heidelberg university veterinary hospitals drive adoption of multiplex bead-based immunoassay platforms for immune-mediated disease research.
Japan
Rising companion animal ownership in Tokyo and Osaka metropolitan areas expands wellness screening protocols bundling thyroid auto-antibody testing with routine chemistry panels. The Ministry of Agriculture, Forestry and Fisheries regulates veterinary diagnostic product safety and efficacy claims. Kansai region specialty clinics concentrate demand for rare purebred feline screening programs targeting systemic lupus erythematosus.
United Kingdom
Urban single-pet households in London and Southeast England drive fastest expansion of feline immunology panels with species-adjusted cutoffs for low total IgG concentrations. The Veterinary Medicines Directorate enforces diagnostic kit quality standards and post-market surveillance requirements. Cambridge and Edinburgh university veterinary centers anchor molecular diagnostics adoption for atypical presentations with infectious disease overlap.
Australia
Multi-site corporate veterinary operators with centralized procurement functions demonstrate fastest uptake of online retail channels for bulk consumables. The Australian Pesticides and Veterinary Medicines Authority regulates diagnostic product registration and labeling compliance. New South Wales and Victoria metropolitan practices lead adoption of subscription-based instrument leasing programs compressing capital barriers for mid-sized clinics.
Animal Auto-Immune Disease Diagnostics Market Competitive Environment
On the supply side, the industry is consolidating around diversified life science conglomerates with captive diagnostic manufacturing infrastructure and specialized veterinary service providers with field-deployed technical networks. Three archetypes dominate: human diagnostics manufacturers extending validated immunoassay production into veterinary applications, pure-play veterinary diagnostic companies leveraging installed bases of chemistry analyzers for recurring reagent revenue, and research-grade laboratory suppliers competing on analytical specificity and multi-analyte panel breadth. Dominant competitive moves include strategic partnerships between instrument manufacturers and reference laboratory networks, plus portfolio diversification into species-specific assay menus.
Among diversified diagnostics conglomerates, Hoffmann-La Roche Ltd and Siemens Healthineers exemplify the human-to-veterinary extension archetype, occupying positions where manufacturing scale and regulatory affairs infrastructure create multi-market entry advantages. IDEXX Laboratories and Zoetis Services LLC sit within the pure-play veterinary tier, representing business models built on recurring reagent relationships and field technical support density. Thermo Fisher Scientific anchors the research-grade supplier position, exemplifying analytical breadth and contract manufacturing capabilities that serve both academic referral centers and commercial assay developers.
| Leading Market Players |
|---|
| Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Abbott Laboratories |
| Beckman Coulter Inc. |
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Bio-Rad Laboratories |
| IDEXX Laboratories |
| Zoetis Services LLC |
| Others |
Value Chain & Pricing Dynamics
North American monoclonal antibody and conjugate suppliers command disproportionate pricing leverage over veterinary diagnostic manufacturers, translating upstream concentration into margin compression for mid-tier assay producers while premium-tier players capture value through regulatory certification bundling.
Pricing Analysis
Certification level creates the primary spread between premium and standard assay tiers, with FDA Center for Veterinary Medicine-validated panels commanding substantial premiums over CE-marked equivalents in United States veterinary chains. Subscription-based instrument leasing models embed reagent pricing into multi-year contracts, reducing transactional price transparency while locking clinics into recurring revenue relationships. Pricing pressure stems from online retail channel expansion enabling high-throughput practices to bypass distributor markups on bulk consumables. Independent veterinary practices demonstrate highest price sensitivity due to limited procurement scale, while consolidated corporate operators leverage centralized purchasing to extract volume discounts.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for critical antibody and enzyme conjugate inputs, straining working capital for mid-sized diagnostic manufacturers competing against diversified conglomerates with captive treasury functions. United States, Germany, and China concentrate supply for monoclonal antibody production, microplate substrates, and fluorescent dye chemistries respectively. The supply chain rests on rare earth-derived luminescent compounds and species-specific reference serum collections subject to biosecurity documentation. Single-source vulnerability pervades certain high-affinity antibody clones protected by proprietary hybridoma lines. Distribution runs through direct sales representatives for instrument-lease-linked reagent commitments, with e-commerce platforms fragmenting procurement for consolidated practice groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with pet insurance penetration in United States metropolitan markets creating conditioned demand for wellness screening protocols that bundle auto-immune testing with routine chemistry panels.
For Market Incumbents: Build regulatory affairs infrastructure as the primary moat against emerging contract diagnostic manufacturers lacking parallel FDA Center for Veterinary Medicine, USDA APHIS, and EU Veterinary Medicines Regulation capabilities. Deepen field-deployed technical support density to lock veterinary chains into species-specific assay menu dependencies. Capacity addition in Germany and the Netherlands addresses academic referral laboratory demand for immunofluorescence pattern interpretation expertise. For New Entrants and Emerging Players: Mid-market veterinary clinics in India and Brazil represent the most penetrable entry point, where rising companion animal ownership meets underdeveloped in-house immunology testing infrastructure. Subscription-based instrument leasing programs without capital outlay requirements lower adoption barriers for ELISA platform deployment. A go-to-market angle anchored on species-specific reference range development for emerging purebred screening programs differentiates against standardized panel offerings. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play veterinary diagnostic companies with installed bases of chemistry analyzers convertible to recurring reagent revenue across North American veterinary chains. Long-term viability over a multi-year horizon hinges on regulatory harmonization trajectory and pet insurance framework maturation outside United States markets. The signal to watch is CE marking pathway streamlining for multi-country European registration, which would accelerate consolidation economics for assay manufacturers with existing regulatory affairs infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Infrastructure Buildout | Parallel FDA, USDA, and EU capabilities create multi-market entry barriers favoring established manufacturers. |
| Subscription-Based Instrument Leasing | Zero-capital-outlay models compress adoption barriers for mid-sized veterinary clinics deploying ELISA platforms. |
| Species-Specific Assay Menu Expansion | Canine and feline reference range standardization improves diagnostic accuracy and drives protocol adoption. |
| Online Retail Channel Development | E-commerce procurement fragmentation enables high-throughput practices to bypass traditional distributor markups. |
| Multiplex Bead-Based Immunoassay Adoption | University veterinary teaching hospitals drive technology adoption for immune-mediated disease phenotyping research. |
Study Parameters
A standing panel of veterinary diagnostic product managers, regulatory affairs specialists at reference laboratories, companion animal practice owners, and procurement directors at consolidated veterinary groups provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, USDA APHIS interstate testing regulations, EU Veterinary Medicines Regulation submissions, and veterinary trade association technical standards. Bottom-up assay volume estimates triangulated against top-down market value reconstructions.
Scenario-bracketing around pet insurance penetration trajectories and regulatory harmonization timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include test type, animal species, distribution channel, and procedure complexity tier. CAGRs derived from fitted growth curves applied to validated baseline estimates, with inputs including veterinary clinic expansion rates, reference laboratory network development, and species-specific assay menu adoption curves.
Practitioners should monitor pet insurance framework maturation outside United States markets and evolving FDA guidance on laboratory-developed tests for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Viral Antigens Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Japan in-Vitro Diagnostics Market