
 Food Allergy Diagnostics and Therapeutics Market | 2026-2036
Food Allergy Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Food Allergy Diagnostics and Therapeutics Market Foresight
Multi-source procurement of diagnostic reagents is broadening as laboratories diversify supply relationships beyond single vendors. Thermo Fisher Scientific leverages its scale in immunoassay manufacturing to sustain global distribution reach. Siemens Healthineers anchors its position through integrated in-vitro diagnostic platforms spanning allergy testing workflows.
Food allergy diagnostics and therapeutics encompasses clinical methods and biologic interventions designed to detect immunoglobulin E and non-IgE mediated hypersensitivity reactions, with blood test assays quantifying specific IgE concentrations against allergen extracts at thresholds typically below 0.35 kU/L. The field serves to reduce anaphylaxis incidence and guide elimination diets in food-sensitive populations. Blood test assays occupy mature margin pools due to established reimbursement codes, while molecular diagnostic tools represent the fastest-growing segment as multiplexed component-resolved diagnostics replace single-allergen screens. Immunotherapy agents concentrate value in biologic formulations, though oral food challenges retain structural importance as the clinical reference standard for definitive diagnosis.
FDA oversees premarket approval for novel diagnostic platforms and biologic therapeutics, while EMA harmonizes allergen immunotherapy standards across European member states through centralized marketing authorization procedures. REACH compliance governs chemical constituents in diagnostic reagent formulations, influencing supplier qualification requirements for EU market access. Stakeholders must monitor evolving FDA guidance on companion diagnostic co-development with biologic therapies, as regulatory alignment between diagnostic validation and therapeutic indication will determine portfolio prioritization decisions.
Market Dynamics
Pediatric allergology practices are consolidating diagnostic workflows around multiplexed component-resolved diagnostics, compressing the addressable market for single-allergen screening assays while expanding biologic therapeutic pipelines.
Growth Catalysts
- EMA Centralized Authorization:Harmonized allergen immunotherapy standards across European member states accelerate cross-border product registration and reduce duplicate clinical trial burdens for biologic developers.
- Component-Resolved Diagnostics:Multiplexed molecular assays identifying specific allergen proteins enable precision elimination diets and reduce unnecessary food avoidance in pediatric populations.
- German Specialized Clinic Network:Dense concentration of university-affiliated allergy centers in Bavaria and North Rhine-Westphalia drives immunotherapy agent utilization through established desensitization protocols.
Market Restraints
- Oral Food Challenge Dependency:Definitive diagnosis still requires supervised provocation testing with anaphylaxis risk, limiting full substitution of in-vitro methods despite assay sensitivity improvements.
- Reagent Supply Concentration:Diagnostic laboratories face vendor lock-in for allergen extract formulations, with limited qualified alternative suppliers meeting ISO 13485 manufacturing standards.
- REACH Compliance Burden:Chemical constituent disclosure requirements for EU diagnostic reagent formulations extend supplier qualification timelines and raise regulatory documentation costs.
Strategic Opportunities
- Companion Diagnostic Co-Development:FDA guidance alignment between diagnostic validation and biologic therapeutic indication creates integrated product development pathways for precision immunotherapy.
- Pediatric Early Screening Programs:School-based allergy identification initiatives in Australia and Canada expand addressable testing volumes beyond symptomatic presentation models.
- Telemedicine-Enabled Challenge Supervision:Remote patient monitoring technologies allow decentralized oral food challenge administration, extending specialist reach into underserved rural markets.
Industry Challenges
- Cross-Functional Talent Scarcity:Clinical immunologists with dual training in molecular diagnostics and biologic therapeutic management command premium compensation, constraining clinic expansion.
- Legacy Assay Integration Complexity:Hospital laboratories face workflow disruption when embedding multiplexed platforms alongside established single-allergen immunoassay infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Allergy Diagnostics and Therapeutics Market |
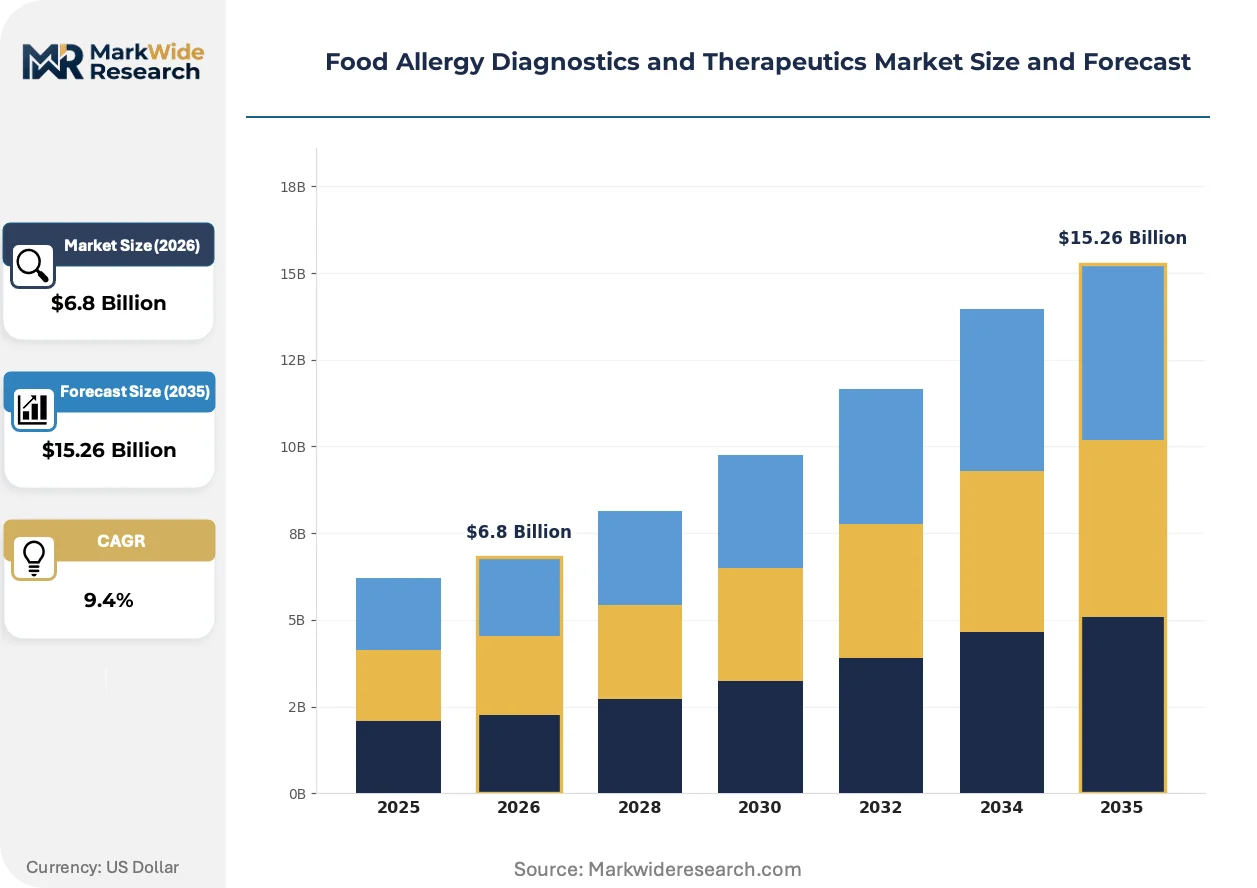
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Prick Test Kits, Blood Test Assays, Oral Food Challenges, Immunotherapy Agents, Molecular Diagnostic Tools Therapy Area: IgE-Mediated Allergies, Non-IgE-Mediated Responses, Food Protein-Induced Enterocolitis, Latex-Fruit Syndrome, Oral Allergy Syndrome End User: Allergy Clinics, Diagnostic Laboratories, Pediatric Practices, Specialized Research Centers, Nutrition Counseling Services Delivery Mode: In Vitro Diagnostics, Point-of-Care Testing, Hospital-Based Services, Home Testing Kits, Telehealth Platforms |
| Companies Covered | Thermo Fisher Scientific, Aimmune Therapeutics, Siemens Healthineers, ALK-Abelló, bioMérieux, HYCOR Biomedical, Omega Diagnostics Group PLC, Astellas Pharma, HOB Biotech Group Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Allergy Diagnostics and Therapeutics Market Shifts & Advancements
Diagnostic accuracy demands and therapeutic personalization are converging to reshape product development priorities, with technology vendors and biologic manufacturers pursuing tighter integration across the care continuum.
Multiplexed component-resolved diagnostics is integrating allergen protein microarray technology with automated sample processing, enabling simultaneous IgE quantification against hundreds of allergen components in a single assay run. Pediatric allergy clinics in the United States and Germany are adopting these platforms at replacement cycle intervals as capital budgets refresh. This compression of diagnostic information into single-test workflows is integrating molecular specificity into routine clinical practice, reducing referral bottlenecks for complex food sensitivity cases.
FDA draft guidance on companion diagnostic co-development with biologic therapies is reshaping portfolio prioritization decisions for diagnostic platform manufacturers. The agency's emphasis on prospective validation studies linking assay performance to therapeutic outcomes extends development timelines but reduces post-market label expansion risks. Biologic developers targeting food allergy indications now face structural pressure to synchronize diagnostic partnerships early in Phase II planning, particularly for therapies addressing peanut and multiple nut allergies.
Direct-to-consumer allergy testing kits are fragmenting traditional laboratory referral pathways, with consumers accessing specific IgE screening through retail pharmacy and e-commerce channels before presenting to specialists. This bypass of physician-mediated diagnostic ordering concentrates interpretive burden on allergists managing patient-generated data. The United Kingdom and Netherlands exhibit the most pronounced channel shift, where regulatory frameworks for self-testing devices remain less restrictive than clinical laboratory oversight regimes.
Food Allergy Diagnostics and Therapeutics Market Segmentation
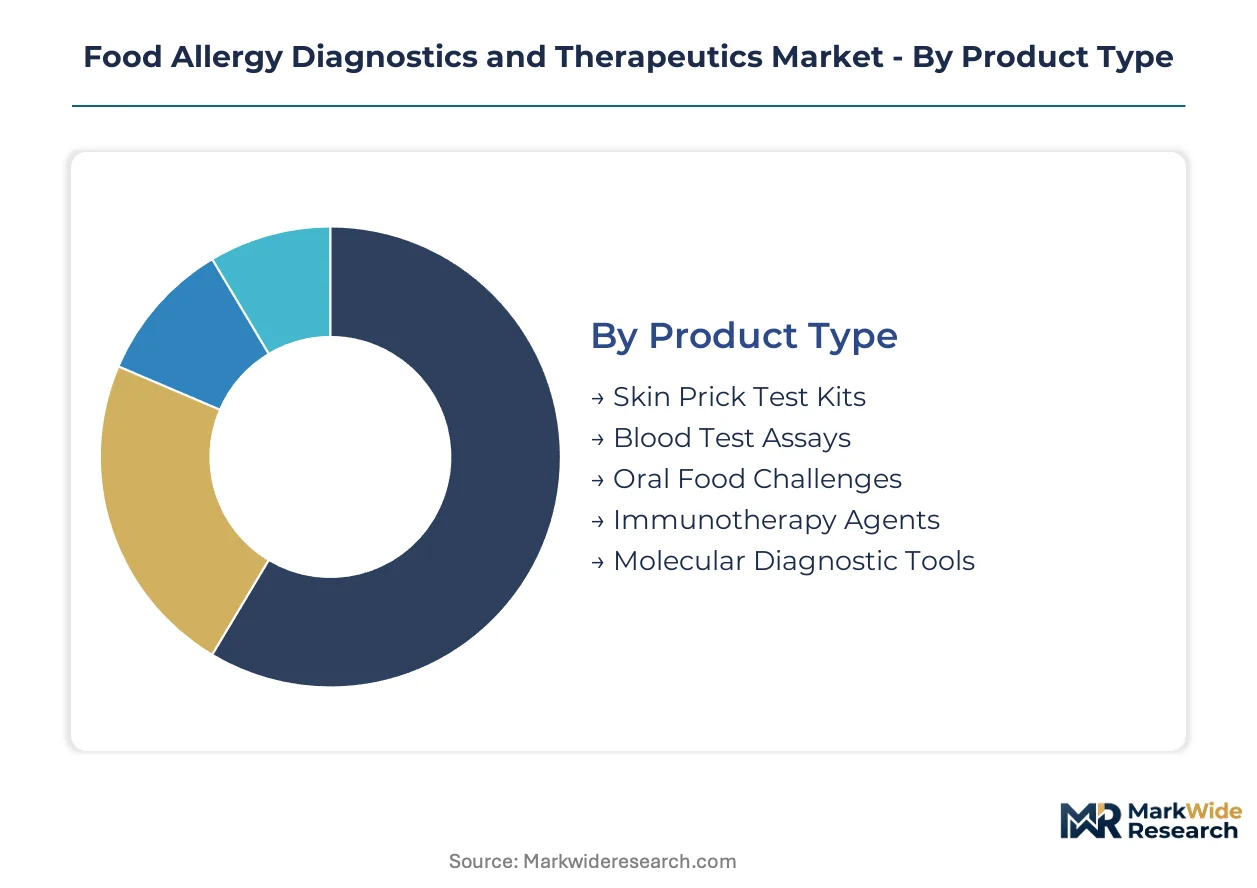
Segmentation in food allergy diagnostics and therapeutics reveals divergent margin structures between commoditized screening tools and precision biologic interventions. Product type stratification exposes how reimbursement codes favor established blood assays while molecular platforms capture capital investment cycles. Therapy area and delivery mode splits illuminate where clinical workflows consolidate versus fragment across care settings.
Product Type:
Volume concentration sits with legacy immunoassays, while premium capture shifts toward multiplexed molecular platforms and biologic therapeutics.
- Blood Test Assays:Quantify specific IgE concentrations against allergen extracts through standardized immunoassay protocols, typically reporting thresholds below 0.35 kU/L. Demand concentrates in Germany and the United States where established reimbursement codes sustain mature margin pools despite sensitivity limitations. Reagent supply relationships often lock laboratories into single-vendor arrangements due to ISO 13485 qualification barriers.
- Molecular Diagnostic Tools:Deploy multiplexed component-resolved diagnostics identifying specific allergen proteins through microarray or bead-based technologies. Pediatric practices in Bavaria and North Rhine-Westphalia drive replacement cycle adoption as capital budgets refresh, compressing diagnostic information into single-test workflows that reduce referral bottlenecks.
- Immunotherapy Agents:Biologic formulations targeting desensitization pathways concentrate value in specialized clinic networks with established protocols.
- Skin Prick Test Kits:Epicutaneous screening devices using allergen extracts remain prevalent in primary care settings with limited laboratory infrastructure.
- Oral Food Challenges:Supervised provocation testing retains structural importance as the clinical reference standard despite anaphylaxis risk and resource intensity.
Today's leader: Blood Test Assays. Tomorrow's challenger: Molecular Diagnostic Tools.
Therapy Area:
Application concentration follows IgE pathway prevalence, while emerging mechanisms attract development investment for underserved phenotypes.
- IgE-Mediated Allergies:Immediate hypersensitivity reactions driven by allergen-specific immunoglobulin E and mast cell activation constitute the dominant addressable population. Peanut and tree nut indications command biologic therapeutic development priority due to anaphylaxis severity and persistent prevalence across pediatric demographics.
- Non-IgE-Mediated Responses:Delayed hypersensitivity mechanisms including T-cell mediated inflammation present diagnostic complexity that component-resolved platforms increasingly address through expanded protein panels.
- Oral Allergy Syndrome:Pollen-food cross-reactivity patterns drive seasonal diagnostic demand in temperate climate regions with high allergic rhinitis prevalence.
- Food Protein-Induced Enterocolitis:Severe gastrointestinal hypersensitivity in infants creates acute care intervention requirements distinct from outpatient allergy management.
- Latex-Fruit Syndrome:Cross-reactive allergen clusters between natural rubber and tropical fruits occupy niche diagnostic volumes with specific occupational health relevance.
IgE-Mediated Allergies anchor current revenue. Non-IgE-Mediated Responses are climbing the fastest as diagnostic specificity improves.
End User:
Customer type stratification reflects workflow consolidation around specialized expertise versus decentralization into community settings.
- Allergy Clinics:Dedicated immunology practices concentrate both diagnostic interpretation and therapeutic administration, capturing margin across the full care continuum.
- Pediatric Practices:Early allergen identification programs expand molecular diagnostic adoption as practices consolidate workflows around multiplexed platforms.
- Diagnostic Laboratories:High-throughput processing centers sustain blood assay volumes through established referral relationships with primary care networks.
- Specialized Research Centers:Academic institutions drive validation studies for novel diagnostic platforms and biologic therapeutic candidates.
- Nutrition Counseling Services:Dietetic practices increasingly integrate specific IgE data to guide elimination diet precision and reduce unnecessary food avoidance.
Allergy Clinics dominate therapeutic value capture. Pediatric Practices are expanding most quickly through early screening program adoption.
Delivery Mode:
Channel configuration reveals tension between centralized laboratory economics and patient convenience demands reshaping access patterns.
- In Vitro Diagnostics:Laboratory-based blood and molecular assays sustain the highest throughput volumes with established quality control frameworks.
- Point-of-Care Testing:Rapid specific IgE devices enable immediate clinical decision-making in settings without full laboratory infrastructure.
- Telehealth Platforms:Remote consultation and monitoring capabilities extend specialist reach into underserved rural markets for challenge supervision.
- Hospital-Based Services:Acute care settings manage severe reactions and controlled provocation testing with resuscitation capacity.
- Home Testing Kits:Direct-to-consumer specific IgE screening fragments traditional referral pathways, concentrating interpretive burden on subsequent specialist consultations.
In Vitro Diagnostics retains volume leadership. Telehealth Platforms represent the steepest expansion trajectory as remote monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where diagnostic reagent manufacturing concentrates, with REACH compliance costs in the European Union pushing some suppliers toward jurisdictions with lighter chemical disclosure burdens while specialized therapeutic development remains anchored in markets with harmonized clinical trial frameworks.
United States
Pediatric allergology practices in Boston and New York Metro are consolidating diagnostic workflows around multiplexed molecular platforms, compressing demand for single-allergen screens. FDA draft guidance on companion diagnostic co-development with biologic therapies extends development timelines but reduces post-market label expansion risks for developers targeting peanut and tree nut indications.
Germany
Dense networks of university-affiliated allergy centers in Bavaria and North Rhine-Westphalia drive immunotherapy agent utilization through established desensitization protocols. EMA centralized authorization procedures harmonize allergen immunotherapy standards across member states, accelerating cross-border product registration for biologic developers while REACH compliance governs chemical constituents in diagnostic reagent formulations.
United Kingdom
Direct-to-consumer specific IgE screening fragments traditional laboratory referral pathways in London and the Southeast, concentrating interpretive burden on allergists managing patient-generated data. Regulatory frameworks for self-testing devices remain less restrictive than clinical laboratory oversight regimes, enabling retail pharmacy and e-commerce channel expansion.
Australia
School-based allergy identification initiatives in New South Wales and Victoria expand addressable testing volumes beyond symptomatic presentation models. TGA oversight of in-vitro diagnostic devices maintains quality thresholds while telemedicine-enabled challenge supervision extends specialist reach into rural Queensland and Western Australia.
Canada
Health Canada harmonizes premarket approval pathways with FDA frameworks for novel diagnostic platforms, reducing duplicate validation burdens for manufacturers serving both markets. Pediatric early screening programs in Ontario and British Columbia are adopting molecular diagnostic tools for early allergen identification as capital budgets refresh.
Food Allergy Diagnostics and Therapeutics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue multiplexed molecular diagnostics and companion diagnostic co-development partnerships. The vendor base stratifies across three maturity tiers: diversified diagnostics conglomerates with global distribution infrastructure, mid-cap specialists concentrating on allergen extract formulations, and biologic developers building immunotherapy pipelines. Consolidation pressure concentrates around diagnostic platform manufacturers seeking therapeutic partnerships and biologic developers requiring synchronized validation studies. Strategic moves favor capacity expansion in ISO 13485-qualified reagent manufacturing and technology licensing for microarray-based component-resolved diagnostics.
Among diversified diagnostics conglomerates, Thermo Fisher Scientific and Siemens Healthineers occupy positions exemplifying scale-driven supply relationships and integrated in-vitro diagnostic platform strategies. Within the biologic therapeutic tier, Aimmune Therapeutics represents the archetype of developers targeting severe food allergy indications through desensitization pathways. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Aimmune Therapeutics |
| Siemens Healthineers |
| ALK-Abelló |
| bioMérieux |
| HYCOR Biomedical |
| Omega Diagnostics Group PLC |
| Astellas Pharma |
| HOB Biotech Group Corp |
| Others |
Supply & Pricing Matrix
Pediatric allergy clinic procurement networks concentrate purchasing power for molecular diagnostic platforms, anchoring contract-based pricing structures that reward multi-year reagent commitments with preferential per-assay rates. This buyer concentration creates tiered access economics where high-throughput laboratories capture standard-tier pricing while smaller practices face premium markups for equivalent technology.
Pricing Analysis
Distributor margin layering compresses net realized prices for diagnostic reagent manufacturers by 15-25 points before reaching end-user laboratories. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified allergen extracts from research-use-only formulations and unvalidated imports. Pricing pressure stems from direct-to-consumer testing kits bypassing traditional channel economics entirely. Hospital laboratories exhibit highest price sensitivity due to fixed DRG reimbursement ceilings, while specialized allergy clinics demonstrate lowest sensitivity where therapeutic margins subsidize diagnostic costs.
Supply Chain Analysis
Single-source vulnerability sits with German and Austrian allergen extract suppliers dominating ISO 13485-qualified reagent manufacturing for European and North American markets. Microarray substrate materials draw from specialized Japanese and South Korean semiconductor-grade suppliers, while biologic therapeutic active pharmaceutical ingredients rest on Swiss and Danish contract manufacturing networks. Tariff exposure on Chinese-sourced diagnostic consumables creates procurement risk concentration. Distribution runs through temperature-controlled logistics partnerships with 2-8°C chain-of-custody requirements from manufacturing through clinical laboratory delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in food allergy diagnostics hinges on component-resolved diagnostic platform consolidation, where capital equipment placements lock in recurring reagent revenue streams with 3-5 year replacement cycles.
For Market Incumbents: Anchor defensive positioning through backward integration into allergen extract manufacturing, securing ISO 13485-qualified capacity in Germany or Austria to neutralize single-source supply risk. Deepen molecular diagnostic platform installed bases before replacement cycle windows open, as pediatric practice consolidation around multiplexed workflows threatens legacy immunoassay revenue retention. Prioritize companion diagnostic partnership structures with biologic developers in Phase II planning to synchronize validation timelines. For New Entrants and Emerging Players: Capture white-space opportunity in telemedicine-enabled oral food challenge supervision platforms, where rural market extension creates addressable volume without direct competition from established laboratory networks. Target Australian and Canadian school-based screening program procurement channels, where public health initiative funding offers penetrable entry points outside entrenched hospital laboratory relationships. Deploy direct-to-consumer testing kit regulatory arbitrage in United Kingdom and Netherlands markets where self-testing frameworks remain permissive. For Investors and Strategic Acquirers: Biologic developers with food allergy pipelines are the most active acquirers in this space, seeking diagnostic platform partnerships to satisfy FDA companion diagnostic guidance requirements. Long-term viability favors integrated diagnostic-therapeutic portfolios over standalone reagent or device plays. Signal to watch: EMA centralized authorization timelines for allergen immunotherapy biologics, which will indicate competitive entry velocity and pricing power compression in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA guidance alignment reduces post-market label expansion risk for peanut allergy biologics. |
| ISO 13485 Manufacturing Scale-Up | Qualified allergen extract capacity in Germany secures supply relationships with high-throughput laboratories. |
| Telemedicine Platform Integration | Remote challenge supervision extends specialist reach into rural Australian and Canadian markets. |
| Pediatric Screening Program Partnership | School-based initiatives in Victoria and Ontario expand addressable testing volumes beyond symptomatic models. |
| Direct-to-Consumer Channel Launch | United Kingdom regulatory permissiveness enables retail pharmacy distribution bypassing laboratory referral economics. |
Research Methodology
Bottom-up pediatric practice and allergy clinic modeling reconciled against top-down diagnostic reagent manufacturing tracking forms the analytical core. Primary interviews with clinical immunologists, laboratory directors, biologic therapeutic development executives, and hospital procurement managers combined with secondary validation against FDA 510(k) filings, EMA centralized authorization procedures, ClinicalTrials.gov entries, and ISO 13485 certification databases. Triangulation between demand-side procedure volume estimates and supply-side reagent production capacity confirms market sizing integrity.
Input-output matrices map allergen-specific IgE assay volumes through molecular diagnostic platform placements, immunotherapy agent administration rates, and oral food challenge supervision encounters across the projection horizon. Segmentation dimensions include product type stratification, therapy area mechanism, end-user facility category, and delivery mode channel. CAGRs derive from procedure volume growth trajectories moderated by reimbursement code stability and capital equipment replacement cycle timing. Forecast inputs incorporate EMA authorization pipeline status and REACH compliance cost pass-through assumptions.
Regulatory timeline delays, companion diagnostic validation failures, and direct-to-consumer channel regulatory tightening are the dominant revision risks. Forecasts reflect documented assumptions regarding pediatric screening program adoption curves and biologic therapeutic pricing persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fungal Antigens Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Microdialysis Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Blood Ketone Test Meter Market