
 Influenza Diagnostic Tests Market | 2026-2036
Influenza Diagnostic Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Diagnostic Tests Market Analysis
The FDA's Emergency Use Authorization framework is realigning the cost-of-entry calculus for new entrants seeking rapid commercialization pathways. Abbott Laboratories leverages its vertically integrated manufacturing footprint to sustain supply continuity during peak respiratory seasons. Thermo Fisher Scientific anchors its competitive position through nucleic acid amplification platforms that dominate reference laboratory workflows. QuidelOrtho Corporation specializes in lateral-flow immunoassay formats that occupy the point-of-care segment with sub-fifteen-minute turnaround protocols.
Influenza diagnostic tests comprise in-vitro diagnostic devices designed to detect influenza A and B viral antigens or nucleic acids from respiratory specimens, typically employing lateral-flow chromatography, reverse-transcription polymerase chain reaction, or direct fluorescent antibody techniques with analytical sensitivities ranging from 10² to 10⁴ copies per milliliter. These products serve primarily to differentiate influenza from other respiratory pathogens, guide antiviral therapy decisions, and inform public health surveillance systems. Rapid Tests command the largest installed base due to minimal infrastructure requirements, while RT-PCR instruments capture premium pricing in centralized laboratories where sensitivity thresholds determine clinical utility. Home Care represents the fastest-expanding end-user channel as decentralized testing protocols gain reimbursement traction.
FDA clearance pathways and Clinical Laboratory Improvement Amendments complexity shape product development timelines and commercial access for influenza diagnostic manufacturers. The Centers for Medicare and Medicaid Services reimbursement schedules directly influence hospital laboratory procurement decisions and test menu expansion. Stakeholders must monitor evolving multiplex panel regulatory criteria and seasonal variant surveillance data to align R&D pipelines with circulating strain patterns.
Market Dynamics
The FDA's Emergency Use Authorization pathway is compressing validation timelines for multiplex respiratory panels, accelerating product cycles while fragmenting competitive moats. This regulatory acceleration is redistributing market power toward manufacturers with established clinical trial infrastructure and pre-positioned manufacturing capacity.
Growth Catalysts
- CLIA Complexity Thresholds:Moderate-complexity laboratory certifications under Clinical Laboratory Improvement Amendments are expanding test access beyond centralized reference laboratories into physician office laboratories and urgent care networks.
- Antigen Detection Sensitivity Gains:Lateral-flow immunoassay formats achieving sub-fifteen-minute turnaround are displacing culture-based confirmation in emergency department triage protocols.
- United States:Seasonal immunization policy mandates drive predictable annual testing cycles, creating recurring procurement windows that stabilize manufacturer revenue forecasting.
Market Restraints
- Reagent Supply Concentration:Reverse transcription polymerase chain reaction enzyme production concentrates among three specialty chemical suppliers, exposing test manufacturers to input cost volatility during respiratory season demand spikes.
- Technical Specificity Limitations:Rapid antigen tests exhibit reduced analytical sensitivity for influenza B strains compared to influenza A, creating diagnostic gaps during mixed-circulation seasons.
- Substitution Threat:Syndromic respiratory panels detecting twenty-plus pathogens simultaneously are compressing standalone influenza test volumes in integrated health systems.
Strategic Opportunities
- Home Care Channel Expansion:Over-the-counter self-test formats are gaining reimbursement traction through Medicare Advantage supplemental benefit structures, opening direct-to-consumer distribution.
- Connectivity Convergence:Smartphone-integrated result reporting is unifying diagnostic data capture with public health surveillance systems, enabling real-time outbreak detection.
- Indian Regulatory Tailwind:CDSCO accelerated approval pathways for infectious disease diagnostics are lowering market entry barriers for manufacturers seeking emerging market diversification.
Industry Challenges
- Molecular Biology Talent Scarcity:Assay development for nucleic acid amplification platforms requires specialized expertise in primer-probe design that outpaces current training program output.
- Legacy Laboratory Information System Integration:Point-of-care instruments face interoperability friction with hospital electronic health record architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Diagnostic Tests Market |
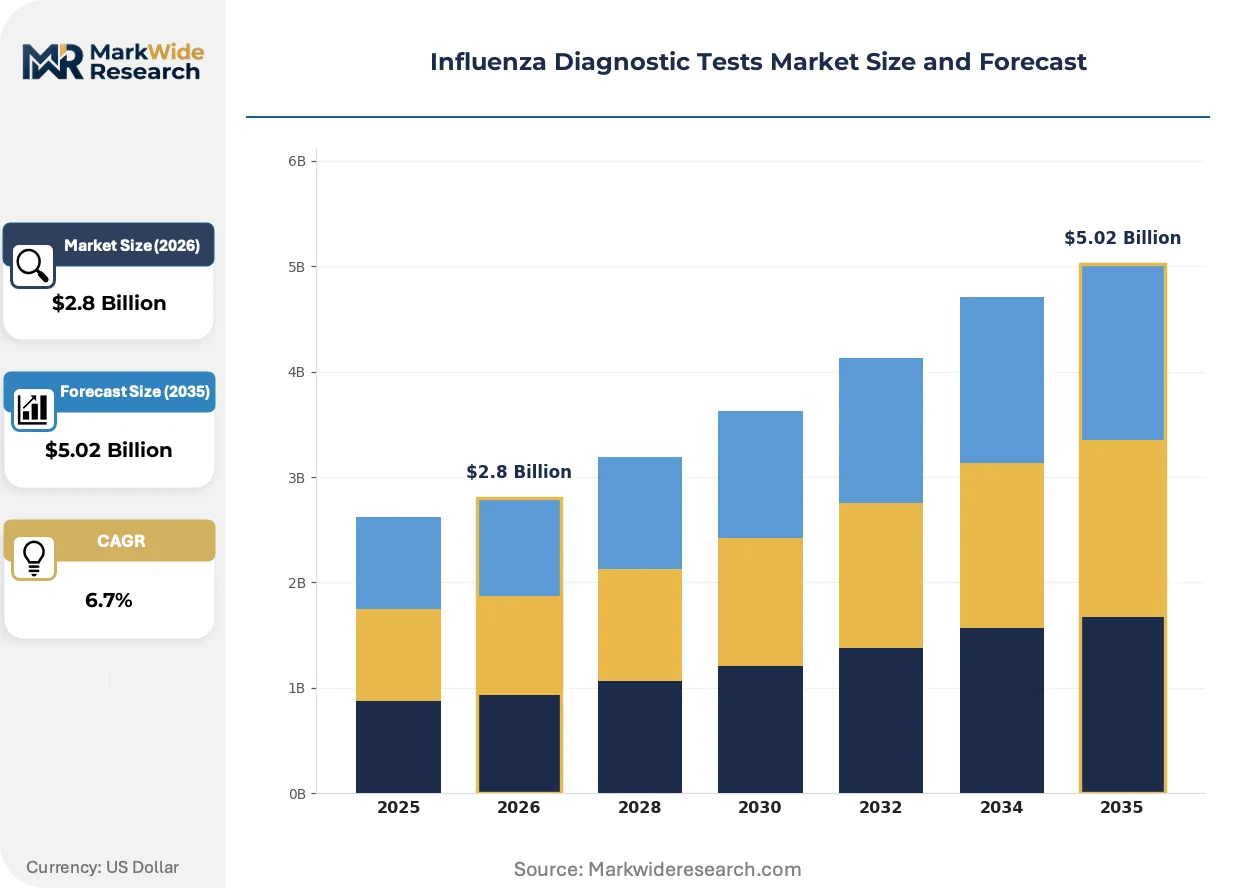
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, RT-PCR, Serological Tests, Viral Culture End User: Hospitals, Diagnostic Laboratories, Home Care, Outpatient Clinics Technology: Immunoassay, Nucleic Acid Amplification, Microarray, Next-Generation Sequencing Application: Clinical Diagnosis, Epidemic Surveillance, Research, Vaccine Development |
| Companies Covered | Abbott Laboratories, Becton, Dickinson and Company, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, QuidelOrtho Corporation, Hologic, 3M Company, Siemens Healthineers, Meridian Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Diagnostic Tests Market Emerging Trajectories
Multiplex detection architectures are consolidating previously discrete testing workflows, while regulatory frameworks adapt to accommodate accelerated validation paradigms. These shifts are compressing product development cycles and redistributing competitive advantage.
Isothermal amplification chemistries are unifying rapid turnaround requirements with laboratory-grade analytical sensitivity. Hospital emergency departments are adopting these platforms at accelerated pace during respiratory season surges. This convergence is unifying point-of-care accessibility with centralized laboratory performance thresholds, collapsing the traditional segmentation between rapid and reference testing modalities.
REACH substance restriction frameworks in Europe are phasing out certain preservative compounds common in viral transport media formulations. Manufacturers are reformulating specimen collection devices to maintain stability under tightened chemical safety thresholds. In-vitro diagnostic device producers serving EU markets are accelerating alternative buffer development to preempt supply discontinuities.
Hospital procurement committees are consolidating respiratory test menus around integrated platform vendors capable of seasonal surge capacity guarantees. Standalone influenza test suppliers face exclusion from multi-year supply agreements favoring broader respiratory panel providers. This concentration is most visible in United States integrated delivery networks managing centralized laboratory operations across multiple acute care facilities.
Influenza Diagnostic Tests Market Segmentation
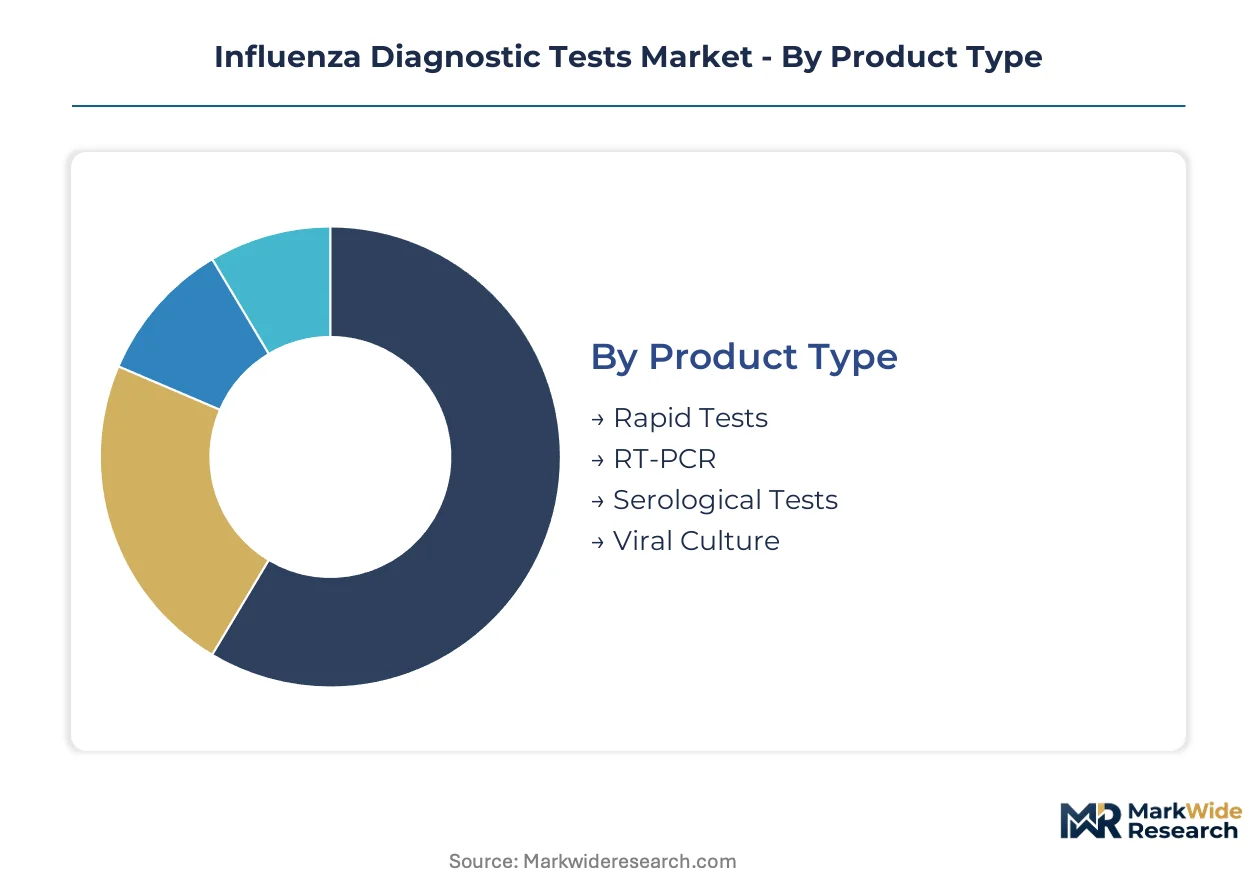
Product architecture in influenza diagnostics directly determines reimbursement pathways and procurement cycles. Segment boundaries are blurring as manufacturers engineer platforms that span multiple settings.
Product Type:
Replacement cycles accelerate when new sensitivity thresholds invalidate prior-generation formats.
- Rapid Tests:Lateral-flow chromatography strips detect viral antigens within 15 minutes without instrumentation. Demand clusters in United States emergency departments where triage throughput dictates procurement decisions.
- RT-PCR:Reverse-transcription polymerase chain reaction instruments achieve analytical sensitivity of 10² copies per milliliter through thermal cycling amplification. Reference laboratories in Germany and Japan anchor installed base expansion as these facilities prioritize sensitivity over speed.
- Serological Tests:Antibody detection assays support retrospective outbreak investigation and vaccine efficacy studies.
- Viral Culture:Cell-based isolation methods retain niche utility for strain characterization in public health reference centers.
Volume placements concentrate in Rapid Tests; the faster expansion belongs to RT-PCR.
End User:
Customer procurement authority shapes pricing tolerance and contract duration.
- Hospitals:Acute care facilities operate 24/7 laboratories with CLIA moderate-complexity certification, enabling STAT testing protocols. United States health systems with seasonal surge capacity requirements drive multi-year platform agreements.
- Diagnostic Laboratories:Centralized reference sites process high-throughput specimen volumes using automated nucleic acid extraction systems.
- Home Care:Over-the-counter self-test formats bypass clinical infrastructure entirely. Medicare Advantage supplemental benefit structures in the United States are creating direct-to-consumer reimbursement pathways.
- Outpatient Clinics:Physician office laboratories favor waived-complexity devices that minimize regulatory overhead.
Procurement authority tilts toward Hospitals; Home Care is climbing the fastest.
Technology:
Platform selection locks customers into reagent supply ecosystems with multi-year switching costs.
- Immunoassay:Antigen-antibody binding reactions power lateral-flow and enzyme-linked formats with minimal capital requirements.
- Nucleic Acid Amplification:PCR and isothermal chemistries deliver laboratory-grade sensitivity at point-of-care speeds. Hospital emergency departments in France and the United Kingdom are adopting these platforms during respiratory season surges.
- Microarray:Multiplex probe arrays enable simultaneous pathogen detection in syndromic panels.
- Next-Generation Sequencing:Whole-genome characterization supports variant surveillance and vaccine strain selection. Public health agencies in the United States and United Kingdom anchor demand for this capability.
Installed base concentrates in Immunoassay; Nucleic Acid Amplification is gaining share fastest.
Application:
Use case specificity determines regulatory pathway complexity and reimbursement coding.
- Clinical Diagnosis:Patient-level treatment decisions require FDA-cleared or CE-marked devices with defined sensitivity specifications. United States hospital laboratories prioritize this application for antiviral therapy guidance.
- Epidemic Surveillance:Population-level outbreak detection demands connectivity infrastructure for real-time reporting. CDC and ECDC funding streams support dedicated procurement for this function.
- Research:Investigational use devices support assay development without full regulatory validation.
- Vaccine Development:Strain selection and efficacy trials require high-throughput serological profiling. Manufacturers in Belgium and the United States contract for dedicated capacity during candidate evaluation cycles.
Revenue concentration sits with Clinical Diagnosis; Vaccine Development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and special economic corridors in India concentrate manufacturing and distribution infrastructure for diagnostic reagents, attracting contract manufacturers seeking tariff-efficient supply chain positioning.
United States
Hospital emergency departments in Texas and Florida drive seasonal test volume surges during winter respiratory peaks. FDA Emergency Use Authorization pathways compress validation timelines for multiplex panels. Boston's biotechnology corridor anchors nucleic acid amplification platform development.
Germany
Reference laboratories in Munich and Hamburg prioritize analytical sensitivity over turnaround speed for surveillance applications. EMA regulatory frameworks influence CE marking standards adopted across EU member states. Baden-Württemberg's industrial cluster concentrates automated extraction system manufacturing.
India
CDSCO accelerated approval pathways lower market entry barriers for infectious disease diagnostics manufacturers. Physician office laboratories in Maharashtra and Karnataka expand moderate-complexity testing access. Hyderabad's pharmaceutical corridor attracts contract research organizations for clinical trial execution.
Japan
PMDA regulatory harmonization with ICH guidelines streamlines import pathways for foreign manufacturers. METI funding supports domestic production capacity for pandemic preparedness. Osaka's medical device cluster specializes in miniaturized point-of-care instrument development.
United Kingdom
NHS procurement frameworks consolidate respiratory test purchasing around integrated platform vendors. MHRA post-Brexit regulatory autonomy enables accelerated approval for novel amplification chemistries. Cambridge's life sciences cluster advances isothermal detection technology research.
Influenza Diagnostic Tests Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale advantages in manufacturing coexist with agility in assay design. The vendor base spans three strategic archetypes: vertically integrated life sciences conglomerates, diagnostic-focused mid-cap specialists, and emerging platform technology developers. Competitive dynamics center on M&A activity to acquire amplification chemistry IP and strategic partnerships to secure seasonal surge manufacturing capacity.
Among diversified life sciences conglomerates, Abbott Laboratories and Thermo Fisher Scientific occupy positions spanning point-of-care and reference laboratory segments, while QuidelOrtho Corporation exemplifies the focused diagnostic specialist archetype with concentrated expertise in rapid immunoassay formats. These three anchors represent distinct strategic postures: conglomerate breadth, platform technology depth, and segment-specific agility.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Becton, Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| QuidelOrtho Corporation |
| Hologic |
| 3M Company |
| Siemens Healthineers |
| Meridian Bioscience |
| Others |
Supply Flow & Price Mechanics
Captive production of reverse transcription enzymes by three specialty chemical suppliers anchors both supply security and pricing power for nucleic acid amplification test manufacturers. This upstream concentration allows input providers to command premium pricing during respiratory season demand spikes while forcing diagnostic OEMs to absorb cost volatility or pass through to hospital laboratory customers.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations during November through March respiratory surges, with United States hospital systems paying 15-30% above contract baselines for STAT delivery of rapid antigen test lots. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from moderate-complexity waived devices and unregulated research-use-only formats. Pricing pressure stems from Medicare reimbursement compression for standalone influenza tests as integrated respiratory panels capture coding preference. Physician office laboratories exhibit highest price sensitivity due to thin operating margins, while integrated delivery networks leverage volume aggregation for lowest net unit costs.
Supply Chain Analysis
ISO 13485 and FDA Quality System Regulation certifications gate entry to contract manufacturing partnerships for lateral-flow device assembly, limiting viable supplier pools to established medical device producers in China, Mexico, and Malaysia. Nitrocellulose membrane substrates, colloidal gold conjugates, and viral transport medium buffers constitute critical input dependencies drawing from specialty chemical producers in Germany, Japan, and the United States. Single-source vulnerability concentrates in recombinant enzyme production for RT-PCR reagent kits. Distribution runs through medical device distributors holding state-level pharmacy licenses, with direct-to-hospital contracting gaining share among top-20 United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over reagent supply and seasonal surge manufacturing capacity determines competitive survival. Players are pursuing backward integration into enzyme production and forward integration into home care distribution to capture margin and lock in channel access.
For Market Incumbents: Acquire isothermal amplification chemistry intellectual property to defend against displacement by emerging platform developers commercializing sub-ten-minute nucleic acid detection. Consolidate manufacturing footprint through multi-year surge capacity agreements with United States integrated delivery networks facing respiratory season overflow. The substitution threat from syndromic respiratory panels compressing standalone influenza test volumes demands immediate menu expansion into multiplex detection architectures. For New Entrants and Emerging Players: CDSCO accelerated approval pathways in India open a window for cost-optimized rapid test formats targeting physician office laboratories in Maharashtra and Karnataka. Home Care represents the most penetrable segment given Medicare Advantage supplemental benefit structures creating direct-to-consumer reimbursement traction. A go-to-market angle pairing smartphone-connected result reporting with public health surveillance integration addresses connectivity gaps that frustrate hospital emergency department adoption of point-of-care instruments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life sciences conglomerates seeking point-of-care diagnostic platform assets. Long-term viability over a 5-10 year horizon hinges on successful navigation of FDA multiplex panel regulatory evolution and CMS reimbursement coding consolidation. The signal to watch as inflection indicator is seasonal immunization policy mandate expansion beyond current United States coverage, which would structurally expand annual testing cycles and stabilize manufacturer revenue forecasting.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emergency Use Authorization Pathway | EUA submissions for multiplex respiratory panels compress validation timelines against traditional 510(k) routes. |
| Backward Integration into Enzyme Production | In-house reverse transcriptase manufacturing insulates against input cost volatility from three-supplier concentration. |
| Hospital System Partnership | Multi-year platform agreements with United States integrated delivery networks secure seasonal surge capacity commitments. |
| Software Companion Development | Smartphone-integrated result reporting unifies diagnostic data capture with CDC and ECDC surveillance systems. |
| Reimbursement Strategy | Medicare Advantage supplemental benefit navigation opens direct-to-consumer Home Care channel access. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced against primary interviews with hospital laboratory directors, GPO contracts managers, biomedical engineers, and diagnostic manufacturer regulatory affairs leads. FDA 510(k) premarket notifications, CDC influenza surveillance reports, CMS Medicare claims data, and hospital procurement database extracts provided quantitative grounding. Bottom-up test volume modeling by end-user segment triangulated against top-down market sizing from manufacturer revenue disclosures.
Granularity-level modeling deployed product type, end user, technology, and application dimensions at the country level for United States, Germany, India, Japan, and United Kingdom. CAGRs across the analysis window derived from regression analysis of historical test volume trends against seasonal immunization policy coverage expansion and multiplex panel adoption curves. Forecast inputs incorporated CLIA complexity certification expansion rates, FDA EUA pathway utilization frequency, and Medicare reimbursement coding evolution for standalone versus syndromic respiratory testing.
The model assumes a particular technology adoption path; alternative pathways for isothermal amplification chemistries displacing traditional RT-PCR in hospital emergency departments would alter the outlook. Forecasts reflect assumptions regarding sustained United States seasonal immunization policy mandates and stable reagent supply concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market