
 Infectious Disease in Vitro Diagnostics Market | 2026-2036
Infectious Disease in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Infectious Disease in Vitro Diagnostics Market Intelligence
The divergence between premium molecular platforms and commodity rapid antigen kits is hardening across procurement channels. Abbott Laboratories leverages its integrated assay-instrument ecosystem to sustain pricing power in hospital laboratories. Danaher Corporation anchors its position through vertical control over sample preparation chemistry and automated workflow instrumentation.
Infectious disease in vitro diagnostics encompasses assays, reagents, instruments, and software designed to detect viral, bacterial, fungal, or parasitic pathogens from clinical specimens, typically requiring sensitivity thresholds at picogram-per-milliliter concentrations for bloodstream infection panels. These systems serve the primary commercial purpose of enabling clinicians to identify causative agents and guide antimicrobial therapy decisions within clinically actionable timeframes. Molecular diagnostics occupies the fastest-expanding margin pool as multiplex PCR and next-generation sequencing displace slower culture-based methods in tertiary care settings. Immunoassays retain dominant volume share in serology and point-of-care screening where turnaround speed outweighs analytical sensitivity.
The FDA regulates in vitro diagnostic devices through premarket notification and premarket approval pathways, while the Clinical Laboratory Improvement Amendments govern analytical performance standards for laboratory-developed tests. In Europe, the In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations that reshape product registration strategies. The EU AI Act introduces additional conformity assessment layers for diagnostics incorporating machine learning algorithms. Stakeholders must monitor how divergent regulatory timelines across FDA, IVDR, and emerging frameworks for software-as-medical-device affect portfolio prioritization and geographic launch sequencing.
Market Dynamics
Hospital laboratories are consolidating purchasing power around integrated molecular platforms while decentralized point-of-care sites demand simplified, instrument-agnostic assays. This bifurcation is fragmenting vendor go-to-market strategies and reshaping R&D allocation across the product portfolio.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation's staged enforcement timeline is accelerating product registration investments. Manufacturers are prioritizing high-margin multiplex panels to justify clinical evidence costs.
- Antimicrobial Stewardship Mandates:US hospital accreditation standards now require rapid pathogen identification for bloodstream infections. This institutional pressure drives molecular platform upgrades in tertiary care networks.
- Sample-to-Answer Automation:Closed-system walkaway instruments are reducing laboratory technician touchpoints. Community hospitals with limited molecular expertise are adopting these systems to expand test menus without specialist hiring.
Market Restraints
- Reagent Supply Concentration:Polymerase and reverse transcriptase production concentrates among three specialty chemical suppliers. Any disruption to this upstream tier propagates through assay manufacturing timelines.
- FDA LDT Enforcement Uncertainty:Pending guidance on laboratory-developed test oversight creates capital planning paralysis. Health systems are deferring platform investments until regulatory clarity emerges.
- Culture-Based Method Persistence:Antibiotic susceptibility testing still requires viable organisms. This technical limitation forces laboratories to maintain dual workflows, diluting the economic case for full molecular conversion.
Strategic Opportunities
- Over-the-Counter Molecular Expansion:The FDA's reclassification of certain respiratory multiplex panels for home use opens direct-to-consumer channels. Manufacturers with consumer brand recognition can capture margin previously retained by clinical intermediaries.
- AI-Assisted Interpretation:Machine learning algorithms for resistance prediction are converging with sequencing platforms. Early movers can differentiate through automated reporting that reduces specialist interpretation burden.
- India's PLI Scheme:Production-linked incentives for medical device manufacturing are attracting component assembly investments. Multinational firms are qualifying Indian facilities for regional export supply.
Industry Challenges
- Bioinformatics Talent Scarcity:Next-generation sequencing adoption outpaces the supply of computational biologists capable of pipeline validation. Laboratories are competing with pharmaceutical and agricultural genomics sectors for the same limited talent pool.
- Legacy LIS Integration:Hospital information systems built on 1990s architectures require costly middleware development to receive structured molecular results. Vendors absorb these integration expenses or risk exclusion from RFP shortlists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infectious Disease in Vitro Diagnostics Market |
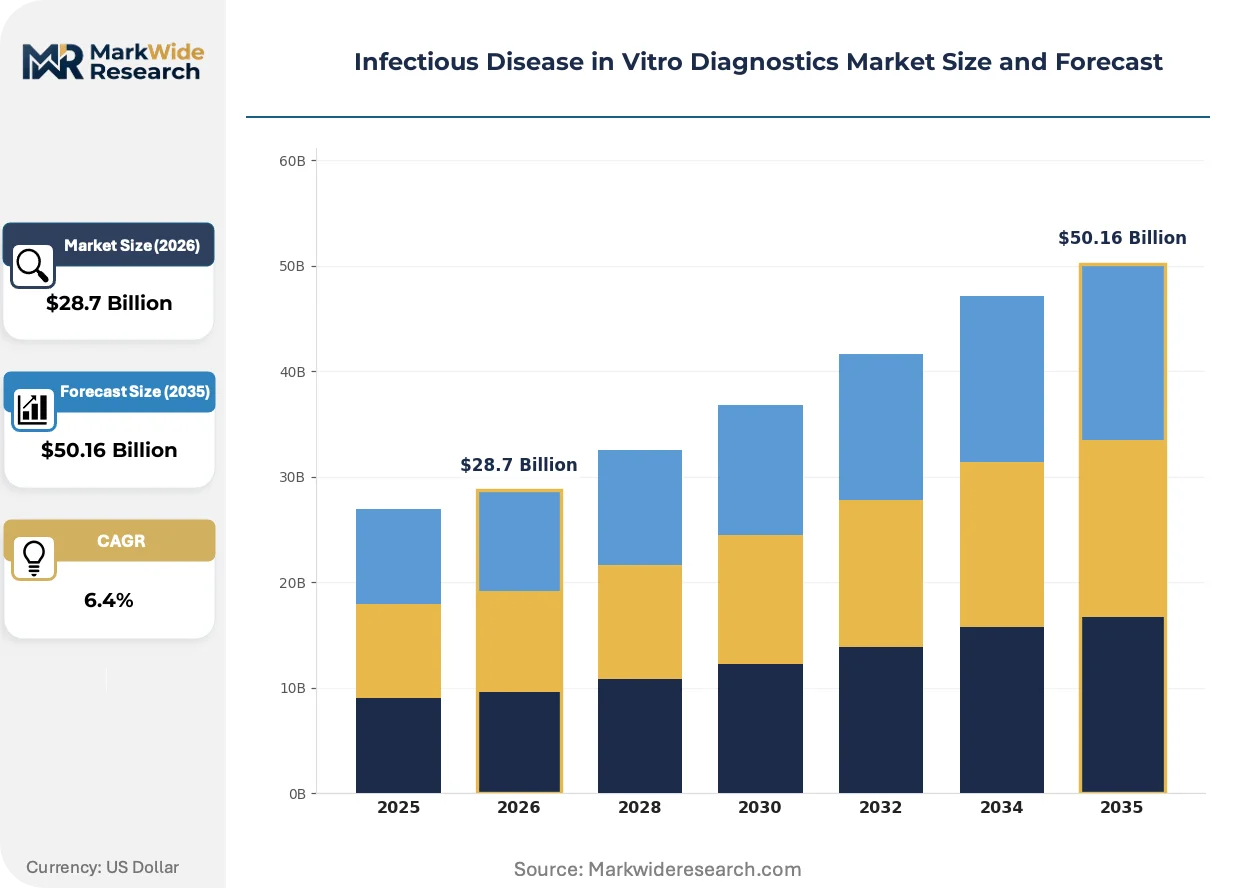
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Reagents, Instruments, Software Testing Method: Molecular Diagnostics, Serology, Immunoassays, Microbiology End User: Hospitals, Laboratories, Clinics, Research Institutions Application: Viral Infections, Bacterial Infections, Fungal Infections, Parasitic Infections |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Danaher Corporation, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Becton Dickinson and Company, bioMérieux SA, Bio-Rad Laboratories, Inc., Qiagen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infectious Disease in Vitro Diagnostics Market Strategic Shifts & Innovations
Digital connectivity and assay miniaturization are collapsing the physical and temporal distance between specimen collection and diagnostic result. These capabilities are redrawing competitive boundaries between centralized laboratories and distributed care settings.
Cartridge-based molecular systems are decentralizing infectious disease testing from hospital core laboratories into urgent care clinics and retail health settings. These platforms consolidate nucleic acid extraction, amplification, and detection into single-use consumables. Pharmacy chains and employer health clinics are deploying them to capture patient volume through same-visit diagnosis and treatment initiation.
The EU AI Act introduces conformity assessment requirements for diagnostics incorporating machine learning algorithms for pathogen identification or resistance prediction. Manufacturers must document training data provenance and algorithmic performance across diverse populations. Multiplex panel developers with European market exposure are restructuring quality management systems to accommodate these software-specific obligations.
Health system procurement departments are consolidating vendor relationships to reduce contract management overhead. Integrated supply agreements spanning instruments, reagents, and service are displacing transactional purchasing of individual assay SKUs. This concentration is most pronounced in Germany, where hospital procurement cooperatives negotiate multi-year framework contracts on behalf of member institutions.
Infectious Disease in Vitro Diagnostics Market Segmentation
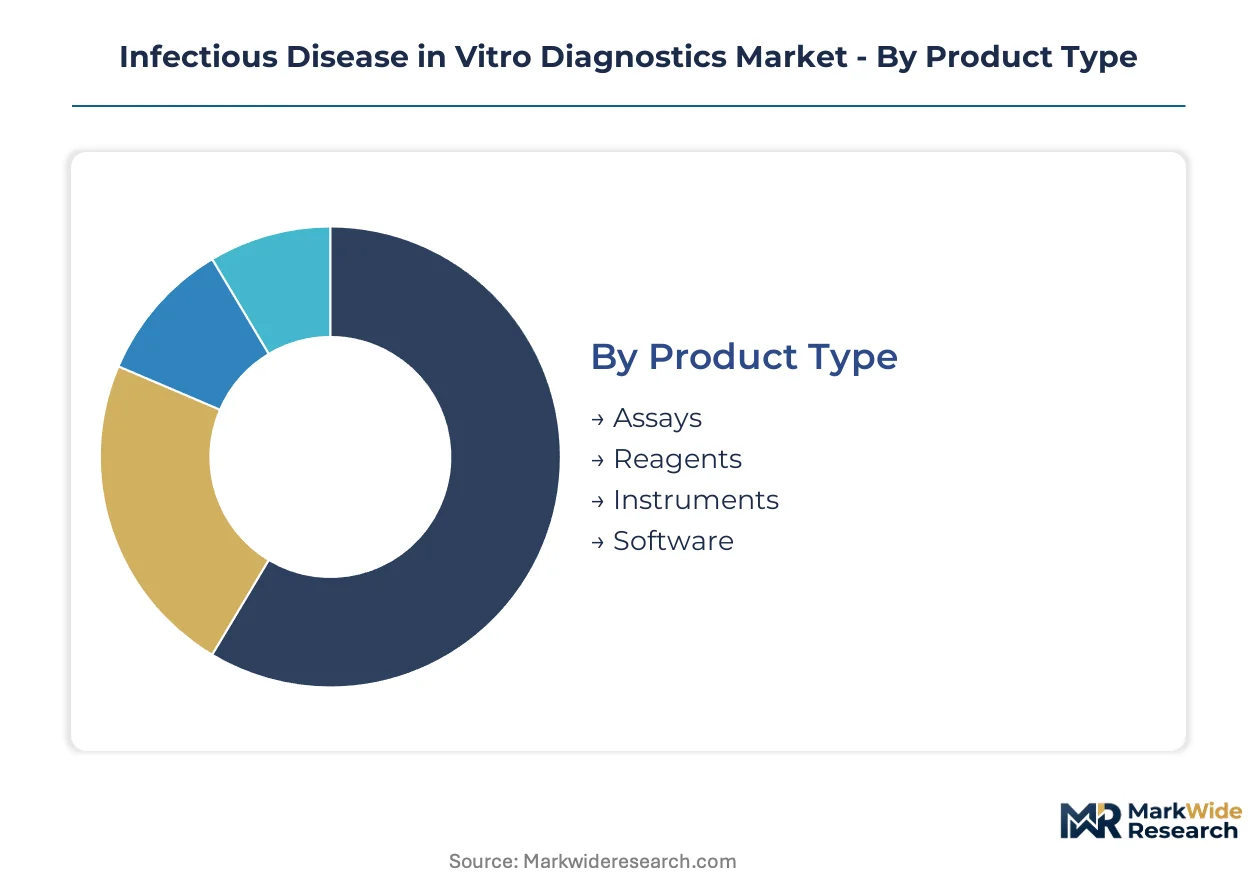
Product architecture in infectious disease diagnostics fragments across workflow stages, with vendor strategies diverging between integrated platform ecosystems and modular consumable sales. Testing methodology determines reimbursement pathways and capital intensity, while end-user concentration shapes distribution economics and service model design.
Product Type:
Supply concentration in polymerase and detection chemistry manufacturing concentrates margin capture among reagent specialists, while instrument OEMs compete through workflow automation and software integration.
- Assays:Nucleic acid amplification panels and antigen detection cartridges constitute the primary recurring revenue stream. Hospital laboratories in the United States and Germany are consolidating purchasing around multiplex respiratory and bloodstream infection panels to satisfy antimicrobial stewardship mandates.
- Reagents:Enzyme formulations, master mixes, and extraction buffers represent the highest-margin consumable tier. Production concentrates among three specialty chemical suppliers, creating vulnerability in upstream supply chains that propagates through assay manufacturing timelines.
- Instruments:Sample-to-answer platforms and high-throughput sequencers anchor capital equipment sales. Community hospitals adopt closed-system walkaway instruments to expand test menus without specialist hiring.
- Software:Laboratory information system middleware and AI-assisted interpretation modules bridge instrument output to clinical decision support. EU AI Act conformity requirements are restructuring quality management systems for algorithmic diagnostics.
Reagents absorb the bulk of installed capacity; software is expanding most quickly.
Testing Method:
Cost tier stratification separates premium molecular platforms from commodity rapid methods, with reimbursement differentials driving procurement segmentation across care settings.
- Molecular Diagnostics:PCR, isothermal amplification, and next-generation sequencing deliver picogram-per-milliliter sensitivity for bloodstream infection panels. Tertiary care networks in China are displacing culture-based methods with multiplex PCR to reduce time-to-result.
- Serology:Antibody detection assays support epidemiological surveillance and convalescent screening. Public health laboratories retain volume share for population-level immunity assessment.
- Immunoassays:Lateral flow and chemiluminescent antigen tests dominate point-of-care screening where turnaround speed outweighs analytical sensitivity. Pharmacy chains deploy cartridge-based systems for same-visit diagnosis.
- Microbiology:Culture-based isolation and phenotypic susceptibility testing persists for antibiotic resistance confirmation. Laboratories maintain dual workflows due to viable organism requirements for stewardship protocols.
Molecular diagnostics commands the steepest expansion trajectory; microbiology retains residual volume from regulatory-mandated susceptibility workflows.
End User:
Customer type fragmentation splits vendor go-to-market models between capital-intensive hospital contracts and distributed clinic consumable sales.
- Hospitals:Integrated delivery networks consolidate purchasing power around multi-year instrument-service-reagent agreements. German procurement cooperatives negotiate framework contracts spanning member institutions.
- Laboratories:Reference laboratories and hospital core labs drive high-throughput platform adoption. FDA LDT enforcement uncertainty is deferring capital planning for laboratory-developed test expansion.
- Clinics:Urgent care and retail health settings demand simplified, instrument-agnostic assays. Pharmacy chains capture patient volume through decentralized molecular testing deployment.
- Research Institutions:Academic medical centers and public health agencies fund assay development for emerging pathogens. Bioinformatics talent scarcity constrains next-generation sequencing pipeline validation.
Hospitals absorb the bulk of installed capacity; clinics are expanding most quickly.
Application:
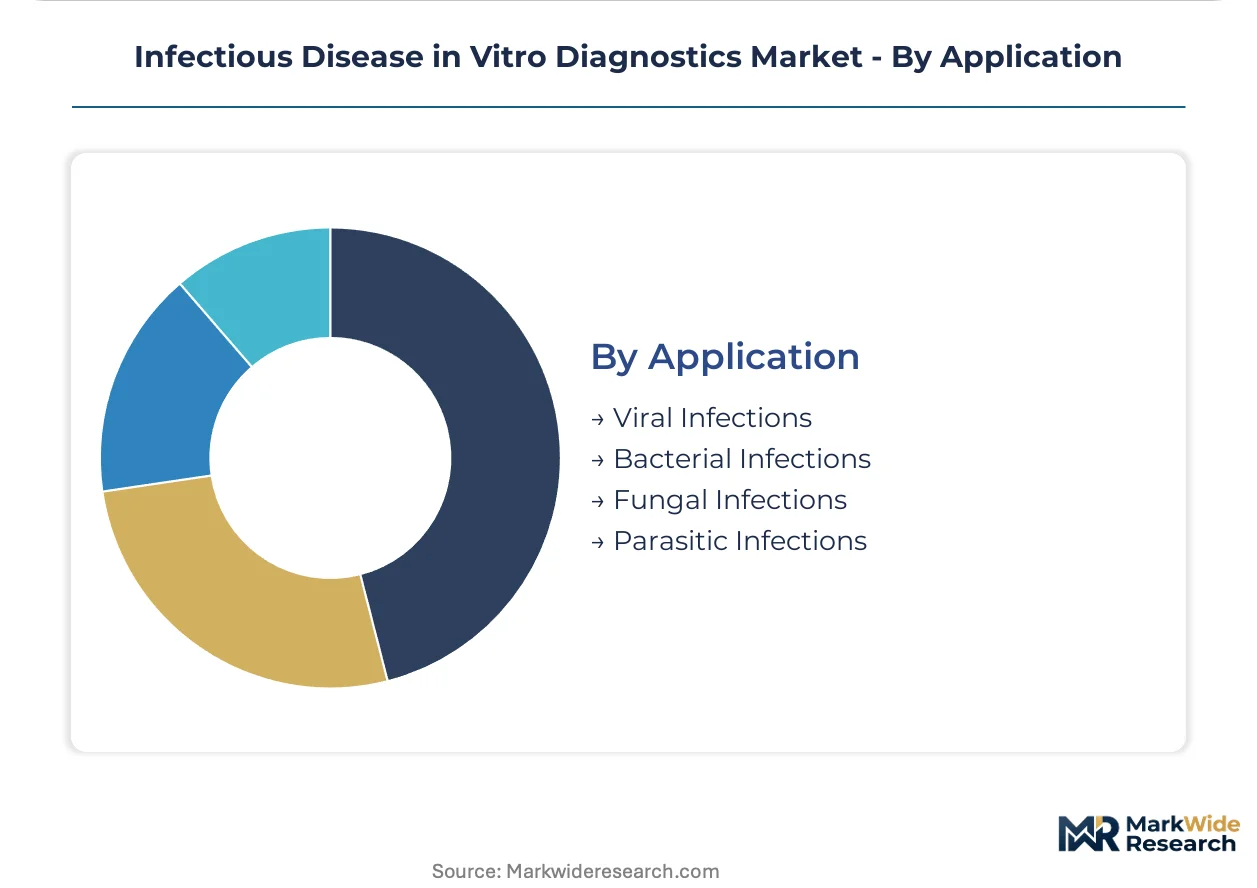
Volume distribution across pathogen categories reflects disease burden, seasonal variability, and pandemic preparedness investment cycles.
- Viral Infections:Respiratory multiplex panels and SARS-CoV-2 assays drove recent capacity expansion. Over-the-counter molecular reclassification by the FDA is opening direct-to-consumer channels for home-use respiratory diagnostics.
- Bacterial Infections:Bloodstream infection panels and sexually transmitted infection assays anchor hospital laboratory menus. Antimicrobial stewardship mandates require rapid pathogen identification for accreditation compliance.
- Fungal Infections:Invasive candidiasis and aspergillosis detection serves immunocompromised patient populations. Tertiary oncology and transplant centers concentrate demand for specialized assays.
- Parasitic Infections:Malaria, toxoplasmosis, and intestinal parasite detection retains importance in travel medicine and immigrant health screening. Reference laboratories maintain expertise for low-incidence pathogen identification.
Viral infections absorb the bulk of installed capacity; bacterial infections are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors infectious disease diagnostics activity through its concentration of academic medical centers and molecular biology research clusters. The metropolitan area hosts reference laboratories and instrument development facilities that shape procurement standards nationwide.
United States
Hospital laboratories in the United States are consolidating purchasing around integrated molecular platforms to satisfy Joint Commission antimicrobial stewardship mandates. FDA guidance on laboratory-developed test enforcement creates capital planning uncertainty that defers some platform investments. The Boston-Cambridge corridor concentrates next-generation sequencing pipeline development and bioinformatics talent pools.
Germany
German hospital procurement cooperatives negotiate multi-year framework contracts spanning instruments, reagents, and service for member institutions. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements that reshape product registration strategies for manufacturers. The Rhine-Ruhr and Baden-Württemberg regions concentrate automated workflow instrumentation manufacturing and reference laboratory networks.
China
Tertiary care networks in China are displacing culture-based methods with multiplex PCR to reduce bloodstream infection time-to-result. The National Medical Products Administration accelerates review pathways for domestic molecular diagnostic manufacturers. The Yangtze River Delta clusters high-throughput sequencer assembly and reagent production facilities serving regional hospital demand.
India
Production-linked incentives for medical device manufacturing attract component assembly investments from multinational diagnostic firms. The Central Drugs Standard Control Organization harmonizes quality standards with international norms for imported instruments. Maharashtra and Karnataka host emerging contract manufacturing facilities qualifying for regional export supply to Southeast Asian markets.
Japan
Japanese hospital networks prioritize closed-system walkaway instruments to address laboratory technician shortages in community hospitals. The Ministry of Economy, Trade and Industry supports domestic production of critical diagnostic reagents under supply chain resilience programs. The Kansai region around Osaka maintains specialized manufacturing for isothermal amplification chemistry and detection systems.
Infectious Disease in Vitro Diagnostics Market Key Industry Players
Premium-margin players sit above commodity-margin players across the sensitivity-throughput spectrum, with integrated platform ecosystems commanding higher pricing power than instrument-agnostic consumables. The vendor base organizes into three tiers: diversified conglomerates with full workflow control, specialized reagent houses with enzyme chemistry expertise, and emerging cartridge-based system developers. Consolidation pressure concentrates among mid-scale instrument manufacturers seeking reagent recurring revenue. Competitive moves center on backward integration into polymerase supply and strategic partnerships for AI-assisted interpretation modules.
Within the diversified conglomerate tier, Abbott Laboratories and Danaher Corporation exemplify contrasting approaches to ecosystem control. Abbott anchors its position through integrated assay-instrument systems designed for hospital laboratory consolidation. Danaher occupies a position emphasizing vertical control over sample preparation chemistry and automated workflow instrumentation. F. Hoffmann-La Roche Ltd represents the European archetype of diagnostics-pharmaceutical convergence, sitting within a structure that links companion diagnostic development to therapeutic pipelines.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Becton Dickinson and Company |
| bioMérieux SA |
| Bio-Rad Laboratories, Inc. |
| Qiagen N.V. |
| Others |
Cost & Logistics Intelligence
EU IVDR clinical evidence requirements gate qualified supply access and premium-tier pricing power for multiplex panel manufacturers serving European hospital networks. Reagent specialists with validated quality management systems command pricing premiums while commodity assay producers face margin compression from procurement consolidation.
Pricing Analysis
Outcome-linked value-based pricing anchors hospital laboratory contracts, with instrument-reagent bundles tied to time-to-result guarantees and antimicrobial stewardship compliance. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform ecosystems from modular consumables and rapid antigen kits. Cost compression in the economy tier intensifies because of pharmacy chain volume aggregation and point-of-care commoditization. Reference laboratories exhibit least price sensitivity due to reimbursement pass-through structures, while urgent care clinics demonstrate highest sensitivity to per-test consumable costs.
Supply Chain Analysis
Freight cost volatility for temperature-controlled enzyme shipments from Germany and the United States to Asian assembly facilities is reshaping regional sourcing strategies. Polymerase and reverse transcriptase production concentrates in Germany, the United States, and Japan, creating single-source vulnerability for specialty thermostable formulations. Assay manufacturing draws from extraction chemistry, detection probes, and plastic consumables as core inputs. Distribution runs through hospital procurement cooperatives in Germany, integrated delivery networks in the United States, and regional distributor hierarchies in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infectious disease in vitro diagnostics market operates as a vertical-integration race, with players pursuing captive control over polymerase supply chains to defend margin pools against reagent commoditization.
For Market Incumbents: Cement ecosystem lock-in through multi-year instrument-service-reagent framework contracts with German hospital procurement cooperatives and United States integrated delivery networks. Secure backward integration into thermostable enzyme chemistry to neutralize supply concentration risk from the three dominant specialty chemical suppliers. Prioritize AI-assisted interpretation module development to meet EU AI Act conformity requirements before competitors restructure quality management systems.
For New Entrants and Emerging Players: Community hospital laboratories without molecular specialists represent the most penetrable buyer archetype for simplified sample-to-answer cartridge systems requiring minimal technician training. India's production-linked incentive scheme offers white-space manufacturing capacity for regional Southeast Asian export supply. Pursue over-the-counter molecular respiratory panel registration as the primary go-to-market angle to bypass clinical intermediary margin capture.
For Investors and Strategic Acquirers: FDA LDT enforcement guidance publication is the leading indicator that capital planning paralysis will resolve and platform investment cycles will resume. Position portfolios for a five-to-ten year window favoring vertically integrated platform vendors with recurring reagent revenue over instrument-only manufacturers. Target mid-scale cartridge-based system developers with validated European quality management systems as acquisition candidates. Monitor antimicrobial stewardship mandate expansion into community hospital accreditation standards as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerase Chemistry | Captive enzyme supply secures margin pools against three-supplier concentration risk in thermostable formulations. |
| EU AI Act Conformity Pathway | Machine learning algorithm documentation enables European market access for resistance prediction modules. |
| Hospital System Partnership | Multi-year framework contracts with German procurement cooperatives lock out modular consumable competitors. |
| Software Companion Development | LIS middleware integration resolves legacy system compatibility barriers for molecular platform adoption. |
| Reimbursement Strategy | Antimicrobial stewardship mandate alignment positions multiplex panels for favorable hospital budget allocation. |
Research Approach
Independent corroboration across hospital laboratory directors, procurement committee chairs, and biomedical engineering specialists underwrites the qualitative findings on platform adoption drivers. Primary interviews with GPO contracts managers, regulatory affairs leads at diagnostic manufacturers, and reference laboratory operations heads were cross-referenced against FDA 510(k) filings, EU IVDR technical documentation, hospital procurement database records, and CMS Medicare reimbursement schedules. Bottom-up test volume modeling and top-down market sizing triangulate to the segment outputs presented.
Comparable-period anchoring to pre-pandemic baseline utilization patterns and post-acute normalization trajectories structured the forecast window calibration. The analytical framework models across product type, testing method, end user, and application dimensions, with geographic regulatory cluster differentiation for FDA, IVDR, and NMPA pathway timing. CAGRs were derived from installed base expansion curves and reagent pull-through assumptions. Antimicrobial stewardship mandate penetration rates and point-of-care decentralization velocity serve as industry-specific forecast inputs.
Revisions become necessary when FDA LDT enforcement guidance materializes with unexpected laboratory-developed test restrictions, or when polymerase supply disruptions propagate through assay manufacturing timelines. Forecasts reflect documented assumptions regarding IVDR transition completion and hospital capital expenditure recovery trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Sperm Count Test Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Blood Culture Media Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Pathogen Detection Market