
 Global Companion Diagnostic Technologies Market | 2026-2036
Global Companion Diagnostic Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Companion Diagnostic Technologies Market Analysis
Oncology clinical workflows are decoupling from traditional histopathology as molecular profiling becomes standard-of-care. F. Hoffmann-La Roche leverages its vertically integrated assay-drug portfolio to anchor co-development partnerships with major pharmaceutical sponsors. QIAGEN competes through broad sample-to-insight automation platforms that span tissue, liquid biopsy, and bioinformatics analysis. Illumina specializes in next-generation sequencing panel architectures that enable comprehensive genomic profiling alongside single-gene companion tests.
Companion diagnostic technologies encompass in vitro diagnostic assays, biomarker detection systems, and algorithmic interpretation software designed to identify patient subpopulations who will benefit from specific drug therapies. These systems typically employ immunohistochemistry, polymerase chain reaction, fluorescence in situ hybridization, or sequencing-based detection methods with defined analytical sensitivity and specificity thresholds to guide therapeutic decision-making. Assays and kits represent the established revenue base where margin pools remain deepest due to recurring consumable demand and locked-in platform ecosystems. Software tools constitute the fastest-expanding segment as laboratories require artificial intelligence-enabled variant interpretation and regulatory-grade reporting to manage escalating test complexity. Biomarker categories within oncology dominate current development pipelines, though cardiovascular and neurology applications are attracting expanded pharmaceutical investment.
FDA premarket approval requirements and EMA In Vitro Diagnostic Regulation framework impose stringent analytical and clinical validation standards that shape product development timelines and market access conditions. ISO 13485 quality management certification and CDSCO licensing in India add further compliance layers for manufacturers pursuing multi-jurisdictional distribution. Stakeholders must monitor evolving payer evidence requirements for companion test reimbursement as health technology assessment bodies tighten their scrutiny of clinical utility data.
Market Dynamics
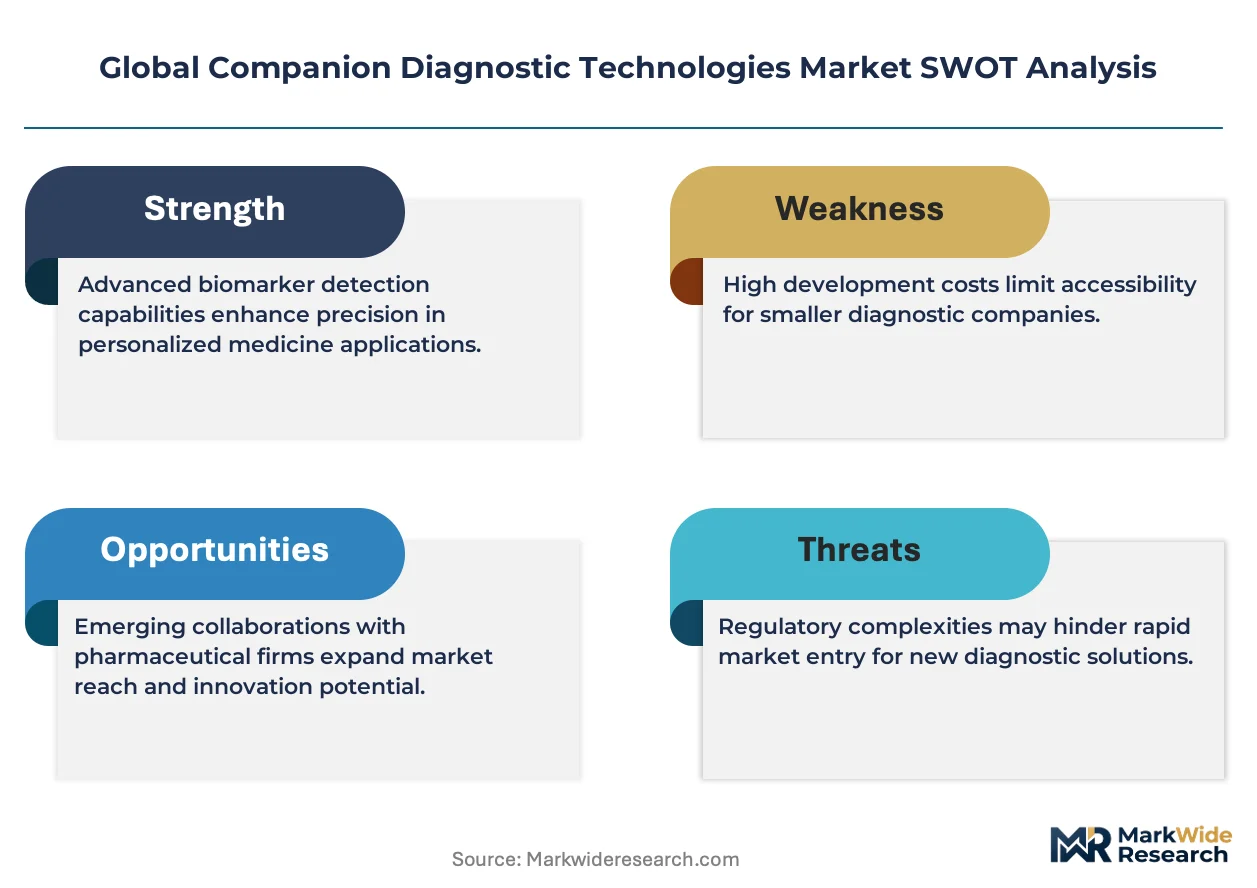
Precision medicine reimbursement frameworks are forcing diagnostic manufacturers to front-load clinical utility evidence generation before commercial launch, compressing development timelines and reshaping partnership structures with pharmaceutical sponsors.
Growth Catalysts
- EMA IVD Regulation harmonization:The synchronized approval pathway with FDA PMA processes accelerates co-development timelines for oncology assays targeting European and North American markets simultaneously.
- Liquid biopsy adoption:Circulating tumor DNA detection methods expand addressable patient populations beyond tissue-adequate cases in metastatic cancer monitoring protocols.
- Japan's precision medicine reimbursement:METI-backed coverage expansion for genomic profiling tests creates sustainable payment infrastructure for companion diagnostic deployment.
Market Restraints
- Reimbursement evidence requirements:Health technology assessment bodies in Germany and France demand randomized controlled trial data for test coverage, extending commercialization timelines.
- Platform ecosystem lock-in:Closed instrument-reagent systems from dominant vendors create switching costs that fragment laboratory standardization efforts.
- Variant interpretation complexity:The exponential growth in biomarker-drug pairings outpaces clinical decision support infrastructure, creating reporting bottlenecks.
Strategic Opportunities
- India's CDSCO licensing expansion:Streamlined IVD registration pathways attract manufacturers seeking volume growth in Asia-Pacific's emerging precision medicine markets.
- Cardiovascular biomarker development:Clopidogrel metabolism testing and statin response markers represent underdeveloped therapeutic areas with pharmaceutical investment acceleration.
- AI-enabled variant classification:Machine learning algorithms integrated with sequencing platforms reduce manual interpretation burden and enable scaled test menu expansion.
Industry Challenges
- Bioinformatics workforce scarcity:Laboratory information management system integration and regulatory-grade reporting development require specialized talent pools concentrated in Boston and San Francisco clusters.
- Multi-jurisdictional quality management:ISO 13485 maintenance alongside FDA QSR and EMA IVDR compliance creates documentation overhead that strains mid-cap manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Companion Diagnostic Technologies Market |
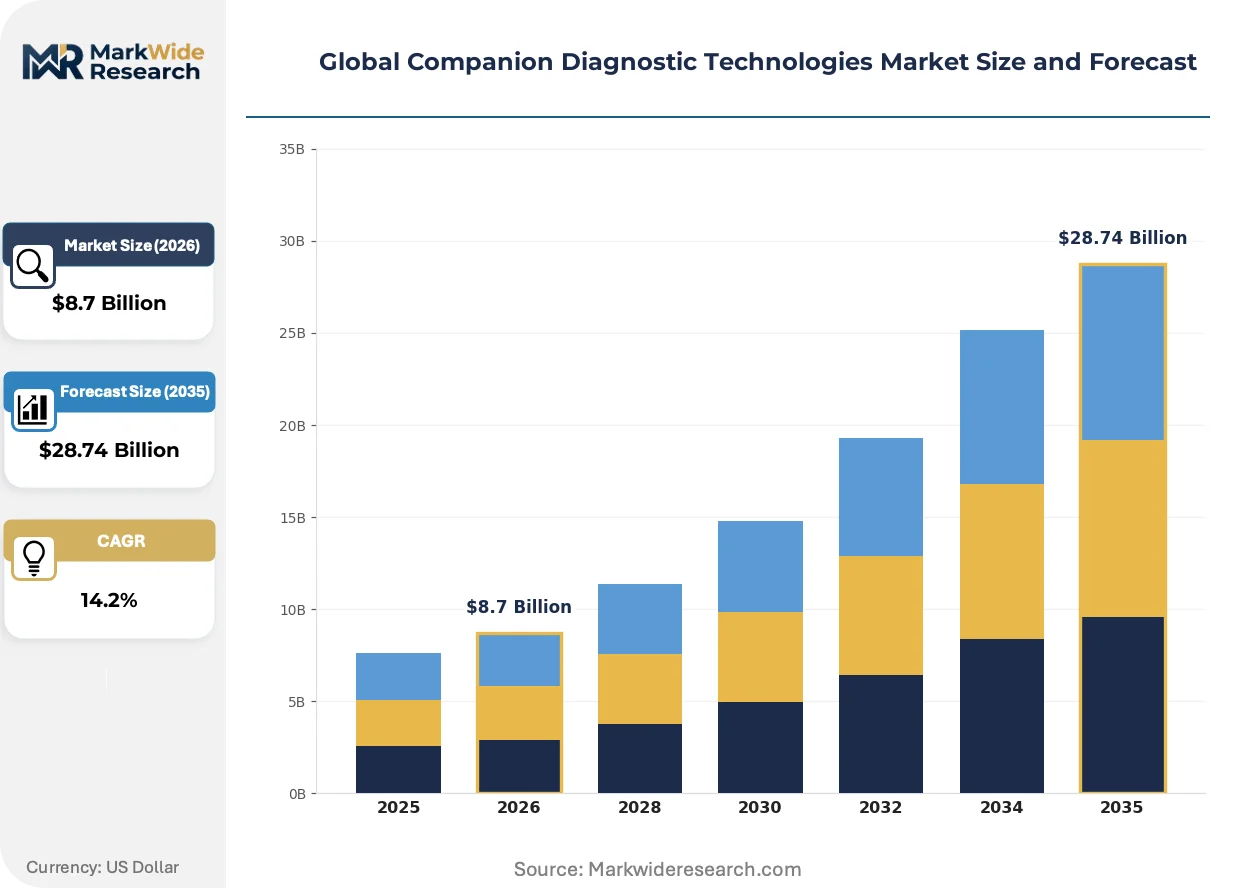
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Kits, Software Tools, Biomarkers End User: Pharmaceutical Companies, Diagnostic Laboratories, Research Institutes, Healthcare Providers Therapy Area: Oncology, Infectious Diseases, Cardiovascular, Neurology Delivery Mode: Point-of-Care, Laboratory-Based, Remote Monitoring, Others |
| Companies Covered | F. Hoffmann-La Roche, QIAGEN, Agilent Technologies, Abbott Laboratories, Thermo Fisher Scientific, Illumina, Myriad Genetics, bioMérieux, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Companion Diagnostic Technologies Market Emerging Trajectories
Next-generation sequencing architectures are compressing per-sample costs while expanding genomic coverage, enabling comprehensive profiling to displace single-analyte testing in academic medical center workflows.
Point-of-care molecular testing platforms are decentralizing companion diagnostic execution from centralized reference laboratories into community oncology clinics and regional hospital networks. Community oncologists in the United States and Germany now perform rapid EGFR mutation testing during patient consultations. This geographic diffusion compresses time-to-treatment initiation and reduces sample logistics complexity.
FDA's streamlined PMA supplement pathway for biomarker expansion within approved platform families reduces regulatory friction for incremental test menu growth. The policy revision enables Roche and Illumina to append new oncology indications to existing instrument clearances. European manufacturers face parallel EMA IVDR conformity assessment streamlining that mirrors this efficiency gain.
Oncology department procurement committees now mandate health economic evidence packages alongside analytical validation data for test adoption decisions. Hospital systems in Japan and the United Kingdom require budget impact models demonstrating cost-per-quality-adjusted-life-year improvements. This evidentiary bar reshapes vendor sales cycles toward collaborative outcomes research partnerships with institutional payers.
Global Companion Diagnostic Technologies Market Segmentation
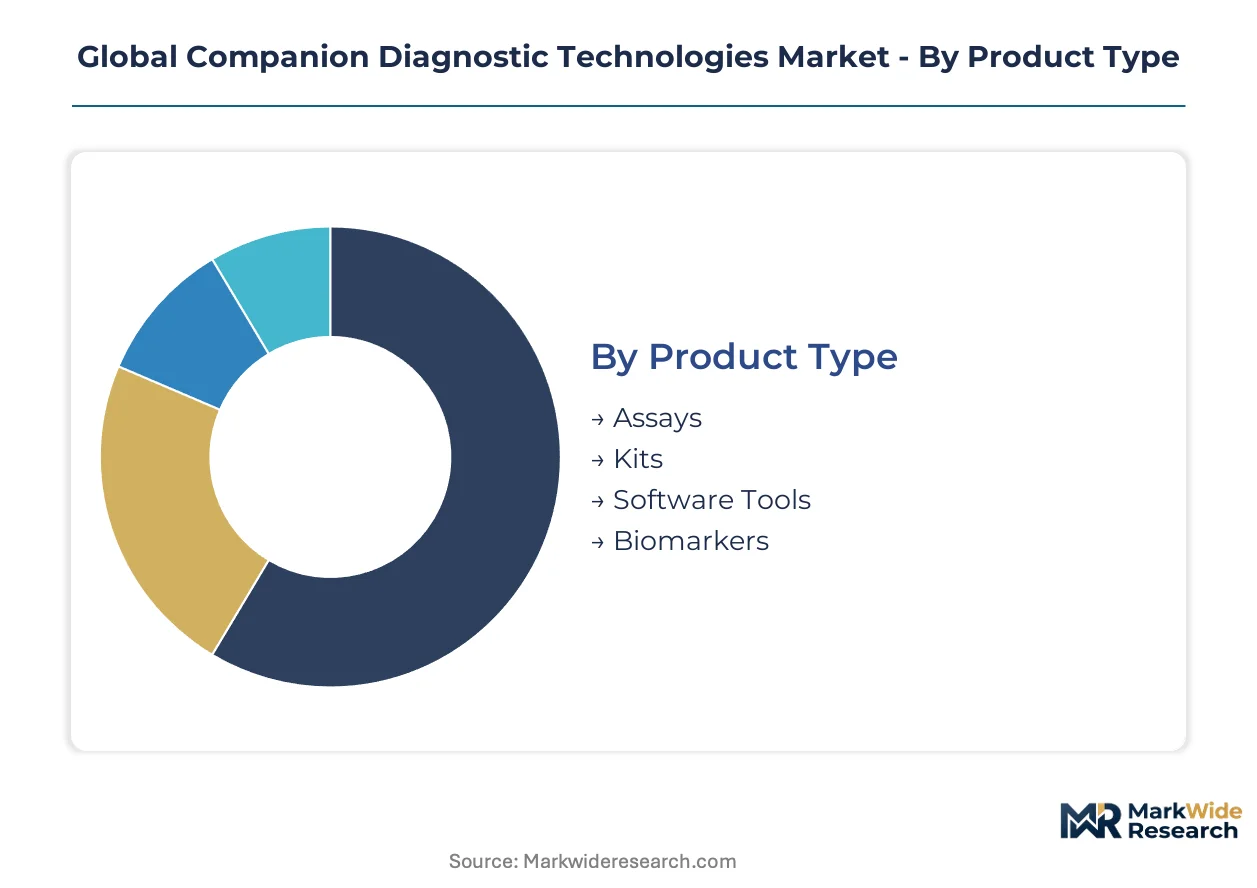
Companion diagnostic technologies fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type distinctions separate consumable revenue streams from capital-intensive platform sales. End user segmentation reveals divergent technical requirements between pharmaceutical co-development partners and clinical service laboratories.
Product Type:
Buyers differentiate primarily by recurring revenue potential versus upfront development investment.
- Assays:Single-use reagent sets with locked-in instrument compatibility dominate hospital laboratory procurement budgets. United States academic medical centers standardize on FDA PMA-cleared assay families to minimize validation overhead.
- Kits:Pre-configured testing packages bundle consumables, controls, and protocols for rapid deployment. German pathology networks favor kit-based workflows to achieve inter-laboratory analytical concordance without custom development.
- Software Tools:Algorithmic variant interpretation platforms reduce manual review burden in high-volume sequencing operations.
- Biomarkers:Analytical targets requiring clinical validation for specific drug pairings represent partnership-dependent revenue.
Volume sits with Assays; growth tilts toward Software Tools.
End User:
Customer technical sophistication spans regulated pharmaceutical manufacturing to decentralized clinical service.
- Pharmaceutical Companies:Co-development sponsors demand regulatory-grade validation packages aligned with FDA PMA and EMA IVDR submission timelines. Roche and AstraZeneca partnerships exemplify vertically integrated assay-drug approval strategies.
- Diagnostic Laboratories:High-throughput reference labs in Japan and the United States prioritize automation compatibility and LIS integration over per-test cost.
- Research Institutes:Exploratory biomarker discovery programs drive demand for research-use-only panel flexibility.
- Healthcare Providers:Community oncology clinics in Germany adopt point-of-care platforms to compress time-to-treatment initiation.
Revenue concentrates with Diagnostic Laboratories; partnership complexity peaks with Pharmaceutical Companies.
Therapy Area:
Clinical validation requirements vary sharply by disease mechanism understanding and regulatory precedent.
- Oncology:Solid tumor and hematologic malignancy applications anchor current test menus with established reimbursement pathways. EGFR, ALK, and PD-L1 biomarker testing commands the deepest assay development investment from manufacturers.
- Infectious Diseases:Antimicrobial resistance profiling and viral load monitoring applications expand beyond oncology with simpler analytical validation frameworks.
- Cardiovascular:Clopidogrel metabolism and statin response markers attract pharmaceutical investment but lack standardized payer coverage.
- Neurology:Alzheimer's disease therapeutic development drives exploratory companion diagnostic programs with extended clinical timelines.
Development pipelines cluster in Oncology; cardiovascular applications are expanding most quickly.
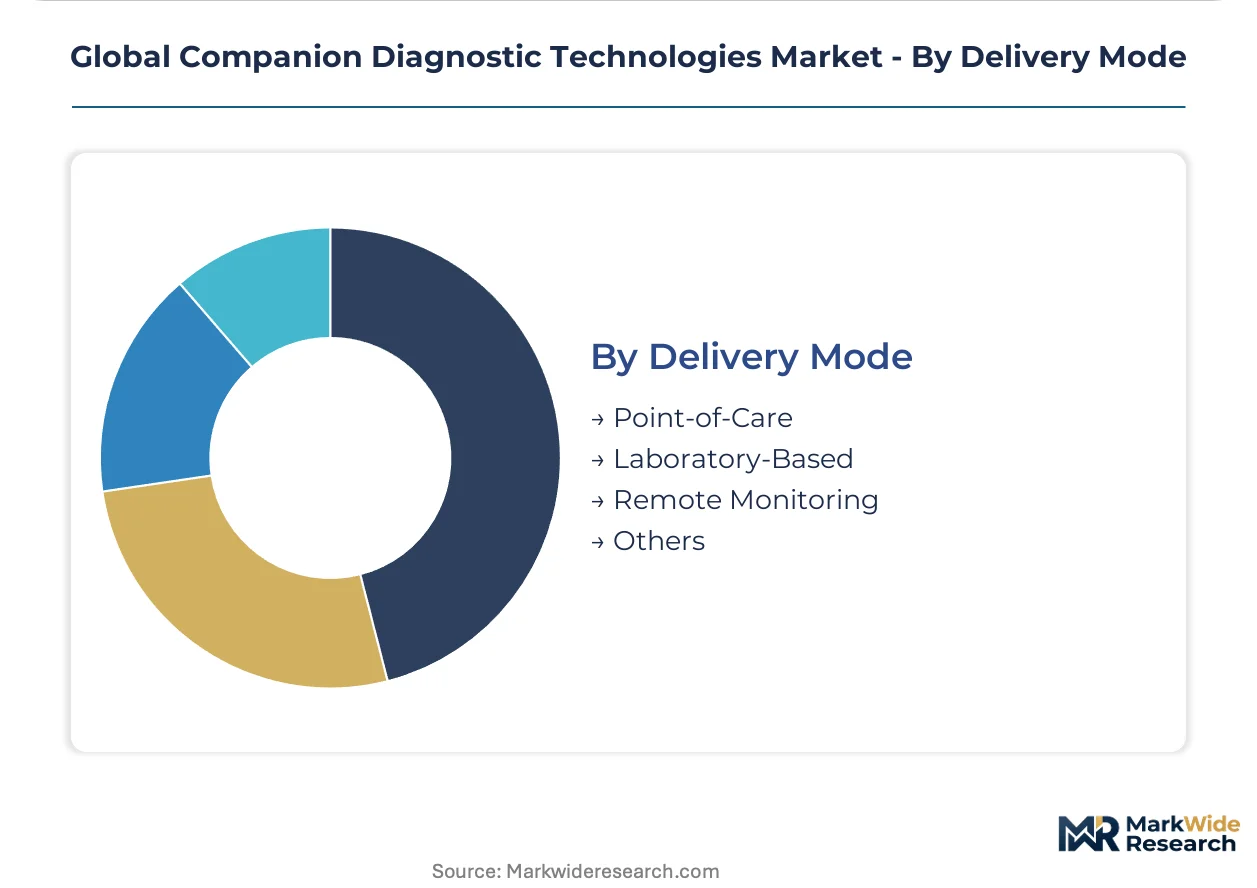
Delivery Mode:
Geographic distribution of testing infrastructure shapes platform architecture requirements.
- Point-of-Care:Decentralized molecular testing platforms enable EGFR mutation analysis during patient consultations. Community oncology networks in the United States deploy cartridge-based systems to eliminate sample logistics delays.
- Laboratory-Based:Centralized reference laboratories in Japan and Germany execute comprehensive genomic profiling with batch-optimized NGS workflows.
- Remote Monitoring:Circulating tumor DNA collection protocols support longitudinal treatment response assessment without facility-based visits.
- Others:Hybrid models combining centralized confirmation with local screening address tissue-adequacy constraints in metastatic disease.
Test volume aggregates in Laboratory-Based settings; deployment flexibility favors Point-of-Care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts' life sciences tax incentive zone concentrates companion diagnostic R&D, attracting manufacturers seeking proximity to Boston's clinical trial infrastructure and FDA pre-submission pathways.
United States
Oncology departments at academic medical centers in Boston and San Francisco drive assay standardization. FDA PMA pathway harmonization accelerates co-development timelines for pharmaceutical sponsors. The San Diego biocluster anchors liquid biopsy platform development for circulating tumor DNA applications.
Germany
Pathology networks in Bavaria and North Rhine-Westphalia prioritize kit-based workflows for inter-laboratory concordance. Health technology assessment bodies demand randomized controlled trial data for test coverage decisions. The Heidelberg-Düsseldorf corridor concentrates NGS platform deployment for comprehensive genomic profiling.
Japan
METI-backed reimbursement expansion for genomic profiling tests creates sustainable payment infrastructure. PMDA consultation pathways align with FDA pre-submission timelines for simultaneous approval strategies. The Tokyo-Osaka axis hosts centralized reference laboratories executing batch-optimized sequencing workflows.
India
CDSCO licensing streamlines IVD registration for manufacturers targeting Asia-Pacific volume growth. Research institutes in Bangalore and Hyderabad drive exploratory biomarker discovery programs. The Delhi-Mumbai corridor attracts diagnostic kit assembly operations serving domestic precision medicine demand.
United Kingdom
NHS England's genomic medicine service mandates health economic evidence packages for test adoption. MHRA recognition of FDA PMA approvals reduces duplicate validation requirements for US-cleared assays. The Cambridge-London corridor concentrates bioinformatics workforce development for regulatory-grade reporting.
Global Companion Diagnostic Technologies Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated assay-drug portfolios commanding premium positioning in oncology co-development. The vendor base concentrates around three tiers: multinational conglomerates with locked-in platform ecosystems, mid-cap automation specialists, and emerging liquid biopsy disruptors. Dominant competitive moves include strategic partnerships with pharmaceutical sponsors for simultaneous FDA-EMA submissions and backward integration into bioinformatics software to capture variant interpretation margins.
Among Swiss and German conglomerates, F. Hoffmann-La Roche and QIAGEN exemplify contrasting platform strategies—Roche through captive assay-drug portfolios, QIAGEN through broad sample-to-insight automation. Illumina occupies a specialist position in sequencing panel architectures. These three represent archetypes of vertical integration, workflow automation, and genomic technology depth respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| QIAGEN |
| Agilent Technologies |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Illumina |
| Myriad Genetics |
| bioMérieux |
| Guardant Health |
| Others |
Supply Flow & Price Mechanics
Polymerase chain reaction reagent costs cascade through three pricing tiers based on FDA PMA certification status and manufacturing origin, with Singapore-sourced master mixes commanding premiums over Indian-assembled alternatives in German hospital procurement.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to FDA PMA-cleared assay families held in regional distribution centers, while spot inventory of research-use-only panels trades at discounts in United States group purchasing organization negotiations. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated platform vendors from mid-cap kit assemblers and unbranded reagent suppliers. Pricing pressure stems from health technology assessment bodies demanding randomized controlled trial evidence before coverage approval, extending commercialization timelines and compressing margins in European markets. Community oncology clinics in Germany exhibit highest price sensitivity due to fixed reimbursement caps, while academic medical centers in Boston prioritize analytical validation over per-test cost.
Supply Chain Analysis
ISO 13485 certification and FDA QSR compliance requirements gate entry for consumable manufacturers, concentrating production among established quality management system holders in the United States, Germany, and Singapore. Supply chains draw from specialized inputs including fluorophore-conjugated antibodies, synthetic oligonucleotide probes, and sequencing-grade polymerases sourced from Swiss and Japanese chemical suppliers. Single-source vulnerability concentrates in rare earth-dependent fluorescent detection components subject to export licensing from Chinese refiners. Distribution runs through captive logistics networks operated by platform vendors, with third-party cold-chain specialists handling kit fulfillment for mid-cap manufacturers serving Indian and Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into bioinformatics software to capture variant interpretation margins and lock in laboratory information system relationships.
For Market Incumbents: Anchor platform ecosystem stickiness through expanded assay menu clearances under FDA PMA supplement pathways, defending against liquid biopsy disruptors by integrating circulating tumor DNA detection into existing instrument families. Prioritize capacity addition in Singapore and Germany to compress lead times for European and Asia-Pacific customers facing EMA IVDR compliance deadlines. Certification investment in CDSCO licensing opens volume growth in Indian diagnostic laboratory networks. For New Entrants and Emerging Players: Community oncology clinics in Germany represent an underserved buyer archetype seeking point-of-care EGFR mutation testing without centralized laboratory logistics. Cardiovascular biomarker development for clopidogrel metabolism testing offers the most penetrable therapeutic expansion with accelerating pharmaceutical sponsor investment. A go-to-market angle emphasizing health economic evidence packages aligned with NHS England budget impact requirements differentiates against incumbent analytical validation-only positioning. For Investors and Strategic Acquirers: FDA PMA pathway harmonization with EMA IVDR regulation is the leading indicator that simultaneous approval capabilities will command acquisition premiums across the analysis window. Long-term viability favors mid-cap automation specialists with captive bioinformatics development and established pharmaceutical co-development partnerships. The signal to monitor is Japan METI reimbursement expansion for genomic profiling tests, which validates sustainable payment infrastructure for precision medicine deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Co-Development Partnership | Roche-AstraZeneca vertical integration locks in assay-drug simultaneous FDA-EMA submission timelines. |
| AI-Enabled Variant Interpretation Platform | Illumina's algorithmic reporting reduces manual review burden in high-volume sequencing operations. |
| Point-of-Care Molecular Testing Expansion | QIAGEN cartridge-based systems eliminate sample logistics delays in United States community oncology. |
| CDSCO Licensing Streamlining | Mid-cap manufacturers capture Asia-Pacific volume growth in Bangalore and Hyderabad research corridors. |
| Health Economic Evidence Generation | Vendor outcomes research partnerships with NHS England satisfy procurement committee budget impact requirements. |
Methodological Framework
Independent corroboration across FDA 510(k) and PMA filings, EMA IVDR technical documentation, and pharmaceutical sponsor clinical trial protocols underwrites the qualitative findings in this study. Primary interviews with diagnostic laboratory directors, regulatory affairs specialists at IVD manufacturers, hospital procurement committee members, and payer access managers combined with secondary validation from ClinicalTrials.gov, CMS Medicare reimbursement databases, and GPO contract disclosures. Bottom-up assay volume modeling and top-down precision medicine expenditure triangulation anchored market sizing.
Rate-of-change decomposition across therapy area expansion, technology platform substitution, and geographic reimbursement adoption shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type distinctions, end user technical sophistication tiers, therapy area clinical validation requirements, and delivery mode infrastructure distribution. CAGRs derived from biomarker-drug pairing pipeline analysis and health technology assessment coverage trajectory assumptions, with inputs from liquid biopsy adoption curves and point-of-care platform deployment rates in community oncology networks.
Revisions become necessary when EMA IVDR conformity assessment timelines extend beyond baseline assumptions or when Japan METI reimbursement expansion stalls. Forecasts reflect documented assumptions regarding pharmaceutical sponsor co-development partnership formation and laboratory information system integration complexity. Regulatory harmonization delays between FDA PMA and EMA IVDR pathways, or health technology assessment body evidence requirement tightening in Germany and France, constitute specific risk factors. A model refresh is warranted upon material change in precision medicine reimbursement framework adoption across the analysis window.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Poultry Diagnostics Market
Diagnostics
Prostate Cancer Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Singleplex Immunoassay Market