
 Antibody Testing Market | 2026-2036
Antibody Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Testing Market Analytics
North American contract research organizations is broadening serological assay production capacity to meet post-pandemic institutional demand. Roche Holding AG leverages automated immunoassay platforms to sustain high-throughput clinical diagnostics. Abbott Laboratories anchors point-of-care antibody detection through its lateral flow infrastructure. Thermo Fisher Scientific Inc. competes on reagent standardization and research-grade antibody panel breadth.
Antibody testing encompasses laboratory and point-of-care methods that detect immunoglobulin presence against specific antigens, typically employing enzyme-conjugated reporter systems or colloidal gold nanoparticle visualization with sensitivity thresholds measured in nanograms per milliliter. The primary purpose spans infectious disease surveillance, autoimmune diagnosis, and transfusion safety verification. Lateral Flow Assay occupies the fastest-expanding product tier due to decentralization of testing into Home Care Settings and resource-limited clinics. Infectious Disease Testing leads application revenue pools, though Autoimmune Disorders command premium pricing on specialized immunofluorescence protocols.
FDA emergency use authorization and Clinical Laboratory Improvement Amendments shape product entry requirements and quality benchmarks for US commercialization. EMA's In Vitro Diagnostic Regulation imposes post-market surveillance obligations that extend compliance costs for European market access. Stakeholders must monitor evolving multiplex assay reimbursement codes and CLIA-waived certification pathways to align portfolio investments with shifting site-of-care economics.
Market Dynamics
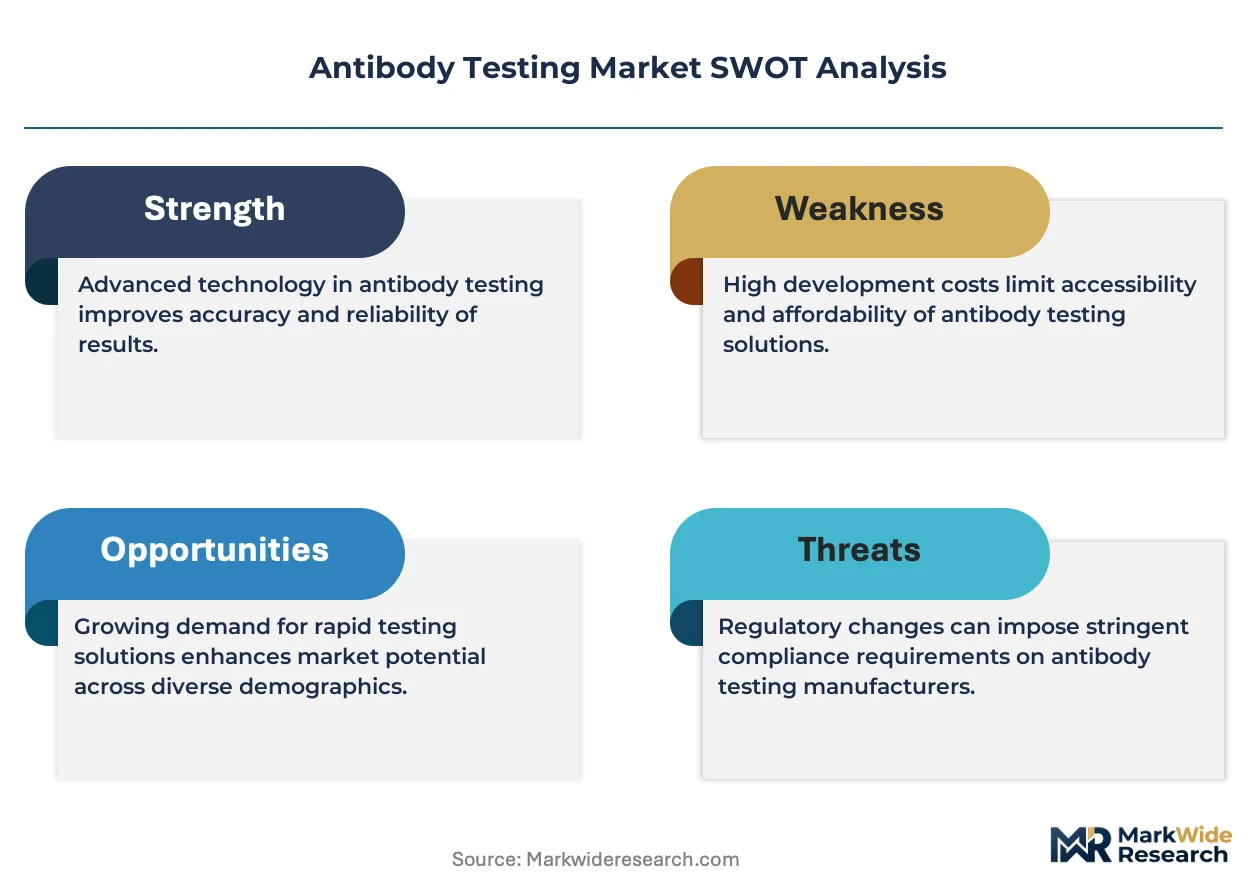
The decentralization of diagnostic workflows toward point-of-care settings is compressing traditional laboratory revenue models while amplifying demand for CLIA-waived immunoassay formats. This structural shift forces manufacturers to rebalance R&D portfolios between high-complexity reference platforms and rapid lateral flow devices.
Growth Catalysts
- FDA Emergency Use Authorization Pathway:The streamlined validation framework for serological assays during public health emergencies has permanently shortened commercialization timelines for novel immunoglobulin detection formats.
- Home Care Settings:Post-pandemic patient preference for self-administered health monitoring is pulling antibody testing into residential environments, expanding addressable volume beyond clinical facilities.
- Autoimmune Disorder Prevalence:Rising incidence of systemic lupus erythematosus and rheumatoid arthritis in aging populations sustains demand for specialized immunofluorescence protocols at premium reimbursement tiers.
Market Restraints
- Reagent Supply Concentration:Production of high-affinity monoclonal antibodies for diagnostic conjugates clusters among contract biologics manufacturers in Switzerland and Germany, creating single-source vulnerability.
- Colloidal Gold Price Volatility:Precious metal cost fluctuations in nanoparticle raw materials directly compress gross margins on lateral flow consumables.
- Cross-Reactivity Limitations:Serological assays for endemic coronaviruses exhibit technical specificity constraints that generate false-positive signals, undermining clinical confidence.
Strategic Opportunities
- Multiplex Assay Development:Convergence of chemiluminescence immunoassay platforms with microfluidic cartridge technology enables simultaneous detection of multiple antibody classes from single specimens.
- India Diagnostic Expansion:The country's national health mission is procuring point-of-care serological kits for district hospital networks, creating volume anchor demand.
- EMA In Vitro Diagnostic Regulation Transition:Extended post-market surveillance obligations for European market access favor manufacturers with established quality management systems and clinical evidence libraries.
Industry Challenges
- CLIA-Waived Certification Timelines:Obtaining waived status under Clinical Laboratory Improvement Amendments requires extensive analytical precision studies that delay US commercialization by 12-18 months.
- Immunoassay Specialist Talent Scarcity:Shortage of experienced assay development scientists with dual expertise in antigen engineering and regulatory submission strategy constrains pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Testing Market |
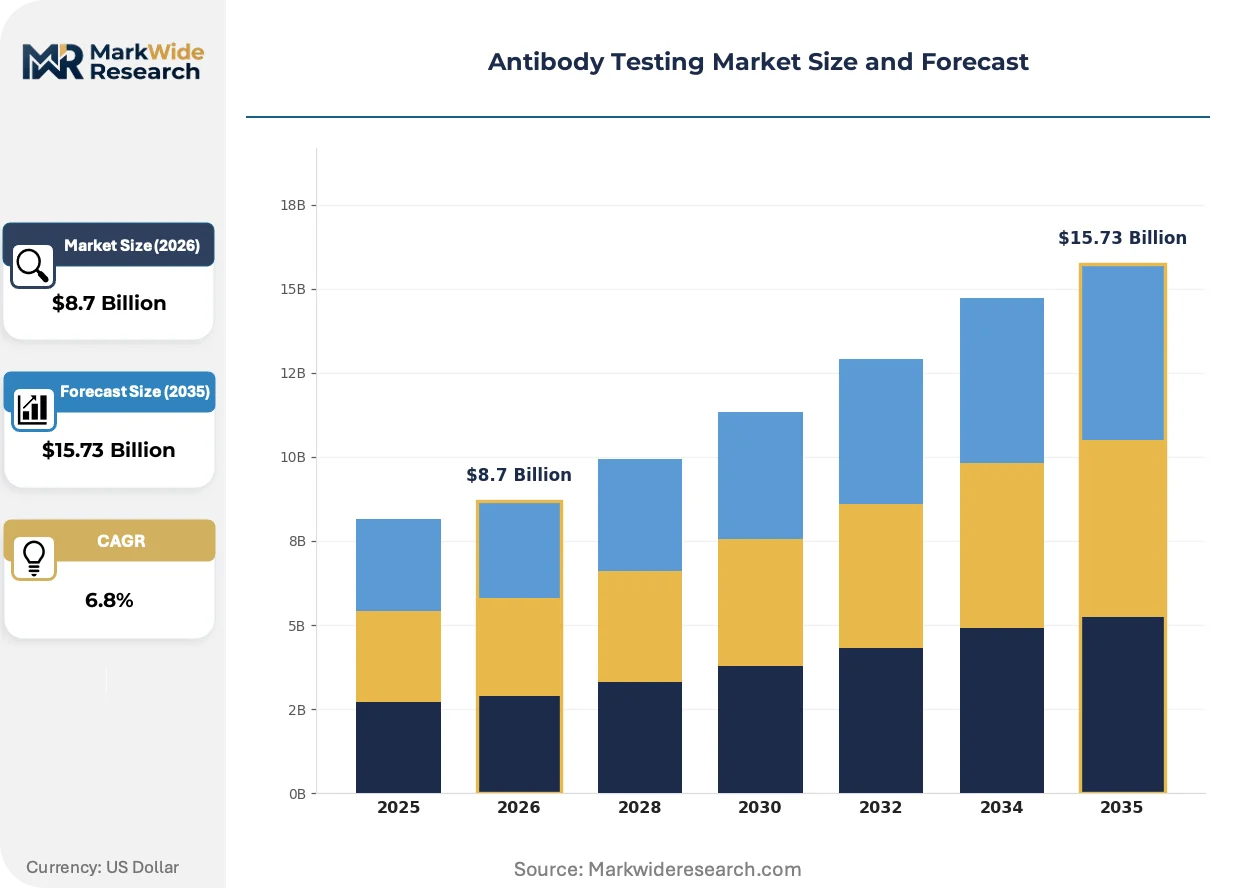
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Lateral Flow Assay, Radioimmunoassay, Western Blot End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Settings Application: Infectious Disease Testing, Autoimmune Disorders, Blood Type Determination, Transplant Compatibility Testing Distribution Channel: Direct Sales, Online Retail, Third-Party Distributors, Medical Supply Stores |
| Companies Covered | Roche Holding AG, Abbott Laboratories, Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., Siemens Healthineers AG, Becton, Dickinson and Company, Merck KGaA, Agilent Technologies Inc., Abcam plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Testing Market Evolving Landscape
Antibody testing technology is fragmenting into modular, software-configurable platforms that accommodate multiple detection chemistries without hardware replacement. This evolution is compressing capital expenditure cycles while expanding test menu flexibility.
Microfluidic cartridge systems are modularizing serological workflows by integrating sample preparation, antigen-antibody binding, and signal amplification into disposable consumables. Regional hospital networks in Spain and Italy are adopting these platforms to reduce benchtop instrument counts. The architecture is compressing per-test operational costs while enabling same-day result delivery for infectious disease panels.
EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for class C and D devices, forcing manufacturers to sponsor prospective validation studies. The compliance burden is reshaping competitive positioning toward larger entities with dedicated regulatory affairs infrastructure. Autoimmune testing portfolios face the steepest documentation demands due to diagnostic claim complexity.
Hospital procurement committees are consolidating antibody testing contracts under centralized laboratory management organizations, displacing decentralized purchasing by individual departments. Group purchasing organizations in the United States are negotiating multi-year reagent supply agreements with exclusive volume commitments. This concentration is most visible in integrated delivery networks across Texas and Florida, where standardized assay menus reduce variation costs.
Antibody Testing Market Segmentation
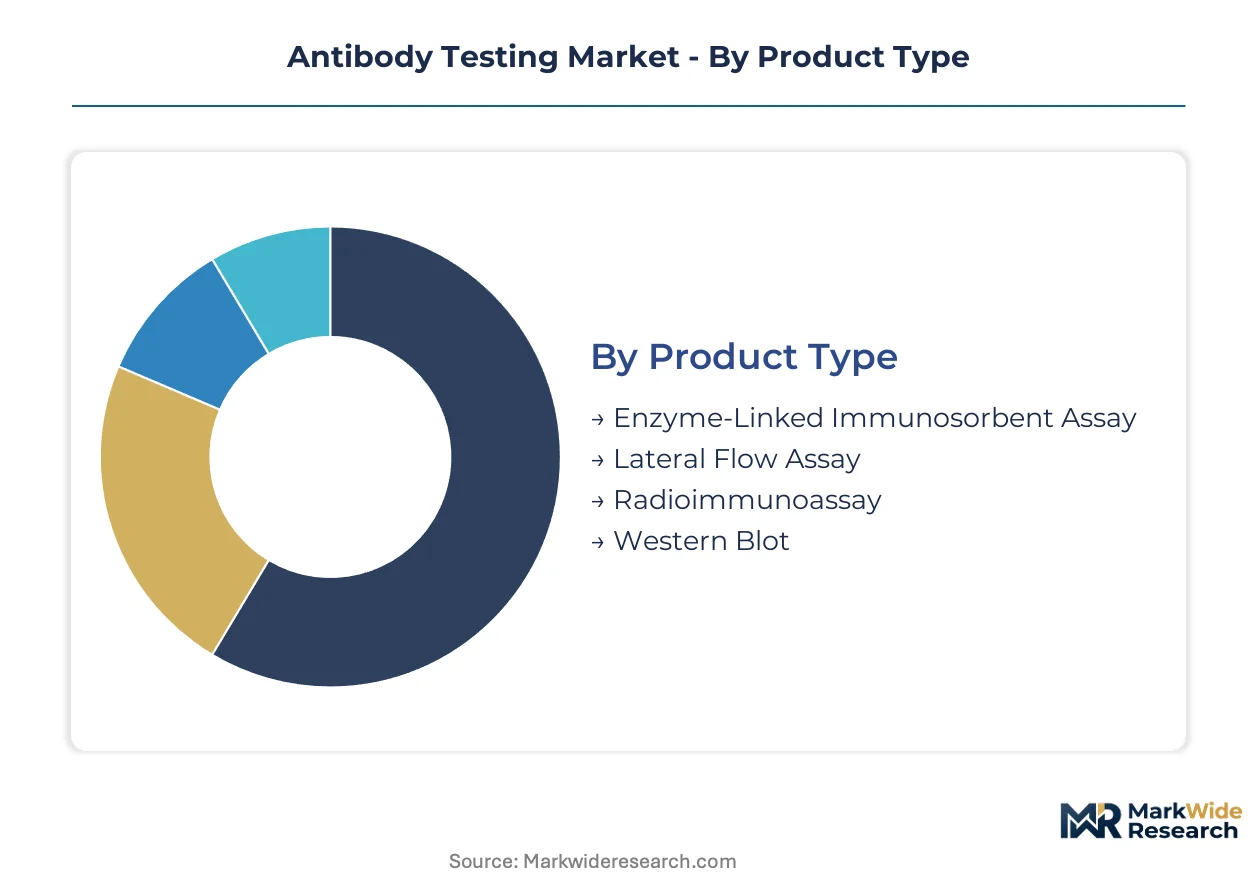
Antibody testing technology fragments across detection chemistries, care settings, and procurement channels that each carry distinct margin profiles and regulatory burdens. Manufacturers must align R&D investments with the structural economics of each segment tier.
Product Type:
Supply concentration in high-affinity monoclonal antibody production shapes competitive positioning across detection platforms.
- Lateral Flow Assay:Colloidal gold nanoparticle visualization enables rapid immunoglobulin detection without laboratory infrastructure. Demand concentrates in Home Care Settings across the United States, driven by patient preference for self-administered monitoring and CLIA-waived certification pathways that reduce clinical oversight costs.
- Enzyme-Linked Immunosorbent Assay:Enzyme-conjugated reporter systems deliver quantitative sensitivity thresholds measured in nanograms per milliliter for reference laboratory environments. Diagnostic laboratories in Germany and Switzerland anchor volume procurement, though automated platform integration requirements extend capital replacement cycles.
- Western Blot:Electrophoretic separation combined with immunodetection serves confirmatory testing protocols in research-grade environments.
- Radioimmunoassay:Isotope-labeled antigen competition methods persist in specialized endocrinology reference laboratories requiring picomolar detection limits.
Today's leader: Lateral Flow Assay. Tomorrow's challenger: Enzyme-Linked Immunosorbent Assay.
End User:
Site-of-care migration is compressing traditional hospital laboratory revenue pools while amplifying decentralized testing economics.
- Diagnostic Laboratories:High-throughput automated immunoassay platforms process serological screening panels at scale. Integrated delivery networks in Texas and Florida consolidate procurement under centralized laboratory management organizations, negotiating multi-year reagent supply agreements with exclusive volume commitments.
- Home Care Settings:Self-administered lateral flow devices bypass clinical infrastructure entirely. Residential demand in the United States climbs fastest as post-pandemic behavior patterns normalize decentralized health monitoring.
- Hospitals:Acute care facilities maintain STAT testing capabilities for transfusion safety and infectious disease triage protocols.
- Research Institutes:Academic medical centers drive demand for multiplex antibody panels and novel biomarker validation studies.
Diagnostic Laboratories capture current revenue concentration. Home Care Settings gain share fastest.
Application:
Premium reimbursement tiers separate autoimmune diagnostics from high-volume infectious disease screening.
- Infectious Disease Testing:Serological surveillance for viral and bacterial pathogens commands the largest absolute volume. District hospital networks in India procure point-of-care serological kits under national health mission programs, creating volume anchor demand for lateral flow manufacturers.
- Autoimmune Disorders:Specialized immunofluorescence protocols for systemic lupus erythematosus and rheumatoid arthritis detection sustain premium pricing. Aging population demographics in Japan and Western Europe reinforce demand concentration.
- Blood Type Determination:Pre-transfusion serological compatibility verification remains mandatory in hospital blood bank operations.
- Transplant Compatibility Testing:HLA antibody screening protocols protect graft survival in organ transplantation programs.
Infectious Disease Testing dominates transaction volume. Autoimmune Disorders defend margin concentration.
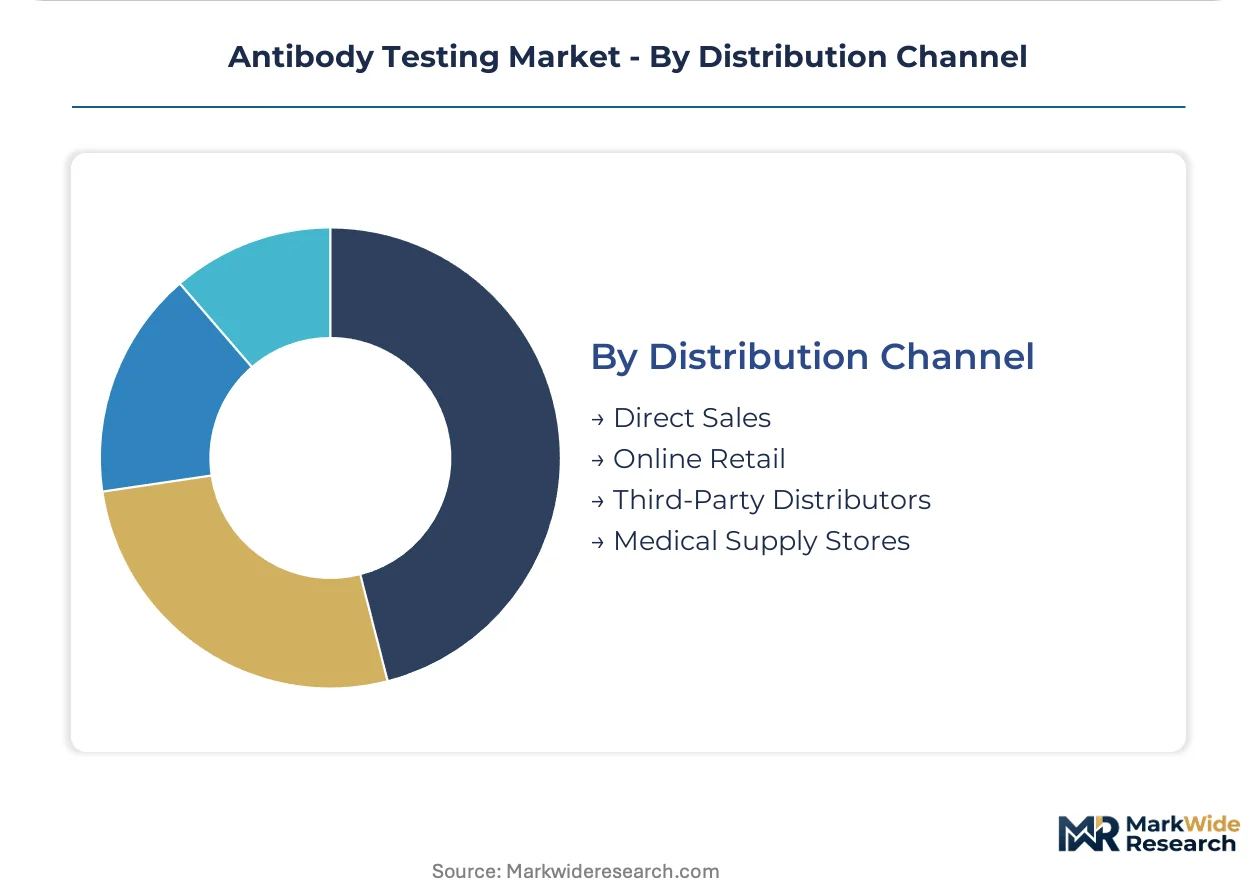
Distribution Channel:
Procurement consolidation through group purchasing organizations is displacing fragmented departmental purchasing.
- Third-Party Distributors:Regional medical supply networks aggregate fragmented demand from independent clinics and smaller hospital systems. Distributor relationships in Spain and Italy reduce customer acquisition costs for manufacturers entering European markets.
- Direct Sales:Manufacturer field organizations serve integrated delivery networks and national laboratory chains with customized reagent supply contracts and dedicated technical support.
- Online Retail:E-commerce platforms enable direct-to-consumer lateral flow kit distribution in regulatory-permissive jurisdictions.
- Medical Supply Stores:Brick-and-mortar procurement persists in resource-limited settings with underdeveloped digital infrastructure.
Third-Party Distributors anchor current reach. Direct Sales deepens strategic account penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are steering diagnostic reagent manufacturing toward jurisdictions with streamlined quality system requirements while high-margin test development concentrates in markets with premium reimbursement codes.
United States
Integrated delivery networks in Texas and Florida consolidate antibody testing procurement under centralized laboratory management organizations with multi-year exclusive volume commitments. FDA emergency use authorization pathways and CLIA-waived certification frameworks shape product entry requirements. North American contract research organizations expand serological assay production capacity to meet post-pandemic institutional demand.
Germany
Diagnostic laboratories in Germany anchor volume procurement of enzyme-linked immunosorbent assay platforms with automated integration requirements. EMA's In Vitro Diagnostic Regulation imposes post-market surveillance obligations that extend compliance costs for European market access. The country's contract biologics manufacturers cluster production of high-affinity monoclonal antibodies for diagnostic conjugates.
India
District hospital networks procure point-of-care serological kits under the national health mission, creating volume anchor demand for lateral flow manufacturers. CDSCO regulatory pathways govern in vitro diagnostic commercialization with evolving import licensing frameworks. Manufacturing clusters in Maharashtra and Gujarat scale colloidal gold nanoparticle consumable production for resource-limited clinic supply.
Switzerland
Swissmedic oversight of class C and D devices maintains stringent clinical evidence requirements for autoimmune testing portfolios with complex diagnostic claims. The country's precision manufacturing base supplies specialized immunofluorescence reagents at premium pricing tiers. Basel and Zurich regions host concentrated biologics contract manufacturing for diagnostic antibody production.
Japan
Aging population demographics sustain demand for specialized immunofluorescence protocols in systemic lupus erythematosus and rheumatoid arthritis detection. PMDA regulatory review timelines for novel immunoassay formats shape commercialization pacing. The Kanto region around Tokyo anchors high-throughput reference laboratory infrastructure with automated platform deployment.
Antibody Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue multiplex microfluidic formats and home-based lateral flow distribution. The vendor base stratifies across automated platform specialists, point-of-care consumable suppliers, and reagent standardization houses. Three archetypes dominate: high-throughput clinical diagnostics platforms, decentralized rapid testing devices, and research-grade antibody panel providers. Competitive moves center on CLIA-waived certification acceleration and exclusive group purchasing organization contract capture.
Among Switzerland-based diagnostics conglomerates, Roche Holding AG exemplifies the high-throughput platform archetype through automated immunoassay infrastructure. Abbott Laboratories, an Illinois-incorporated healthcare corporation, occupies a position in point-of-care antibody detection exemplifying the lateral flow decentralization strategy. Thermo Fisher Scientific Inc., a Massachusetts-registered scientific instrumentation company, represents the reagent standardization and research-grade panel breadth segment. These three entities anchor distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Roche Holding AG |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| Siemens Healthineers AG |
| Becton, Dickinson and Company |
| Merck KGaA |
| Agilent Technologies Inc. |
| Abcam plc |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in Texas and Florida command contract-based long-term reagent supply agreements with exclusive volume commitments, compressing margins for lateral flow manufacturers while sustaining premium tiers for specialized immunofluorescence protocols.
Pricing Analysis
Distributor margins on lateral flow consumables absorb colloidal gold price volatility, forcing manufacturers toward direct sales channels for integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-waived home care devices from automated platform reagents and research-grade antibody panels. Cost compression in lateral flow consumables is intensifying because precious metal input fluctuations directly compress gross margins. Home care settings exhibit highest price sensitivity, while autoimmune disorder diagnostics defend premium positioning through specialized immunofluorescence reimbursement codes.
Supply Chain Analysis
Regional distribution centers in Basel and Zurich anchor hub-and-spoke patterns for high-affinity monoclonal antibody production, with secondary nodes in Maharashtra and Gujarat scaling colloidal gold nanoparticle consumable output. Manufacturing concentration in Switzerland and Germany creates single-source vulnerability for diagnostic conjugate inputs. Raw material dependencies span purified immunoglobulins, enzyme reporter systems, and nanoparticle colloids. Tariff exposure on European-sourced reagents threatens margin stability for US-based lateral flow assemblers. Distribution runs through third-party medical supply networks in Spain and Italy, supplemented by direct manufacturer field organizations serving national laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody testing operates as a regulatory compounder where FDA emergency use authorization pathways and EMA In Vitro Diagnostic Regulation transitions permanently elevate compliance investment as a barrier to demand capture.
For Market Incumbents: Deepen backward integration into high-affinity monoclonal antibody production to offset Swiss and German contract manufacturing concentration. Expand CLIA-waived certification acceleration capabilities to defend against emerging microfluidic cartridge entrants. Lock in multi-year exclusive reagent supply agreements with Texas and Florida integrated delivery networks before procurement consolidation peaks. For New Entrants and Emerging Players: Begin with district hospital networks in India under national health mission procurement programs, where point-of-care serological kit demand anchors volume without entrenched incumbent relationships. Target home care settings in the United States through e-commerce direct-to-consumer channels in regulatory-permissive jurisdictions. Pursue chemiluminescence-microfluidic multiplex convergence as the most penetrable technology white space. For Investors and Strategic Acquirers: Diagnostic platform conglomerates pursuing point-of-care decentralization are the most active acquirer in this space, seeking lateral flow infrastructure and CLIA-waived certification expertise. Acquisition target archetypes include mid-cap consumable suppliers with captive colloidal gold nanoparticle production and established GPO contract relationships. Watch for EMA In Vitro Regulation transition completion as the inflection signal for European market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Certification Acceleration | Shortens US commercialization timelines by 12-18 months for lateral flow entrants. |
| Multiplex Microfluidic Development | Enables simultaneous antibody class detection from single specimens on chemiluminescence platforms. |
| Backward Integration into Biologics | Captive monoclonal antibody production insulates against Swiss and German supply concentration. |
| India National Health Mission Contracting | District hospital network procurement creates volume anchor demand for point-of-care manufacturers. |
| EMA Post-Market Surveillance Investment | Established quality systems favor larger entities under In Vitro Diagnostic Regulation obligations. |
Research Methodology
Multiple input streams — primary interviews with diagnostic laboratory directors, regulatory affairs specialists, and GPO contracts managers; secondary validation through FDA emergency use authorization filings, EMA In Vitro Diagnostic Regulation documentation, and hospital procurement databases; plus customs records on diagnostic reagent trade flows — were reconciled through bottom-up and top-down triangulation to produce segment-level volume and value estimates.
Data-stream reconciliation across product type, end user, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled annual growth trajectories incorporating autoimmune disorder prevalence demographics, infectious disease surveillance program expansion, and site-of-care migration patterns toward decentralized testing environments.
Several conditions sit outside the modeled scope, including unforeseen pandemic declarations, abrupt regulatory pathway suspensions, and raw material export restrictions. Forecasts reflect documented assumptions on reimbursement code stability and CLIA certification timeline norms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
IVD Antibody Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Viral Antigens Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market