
 Febrile Antigen Kits Market | 2026-2036
Febrile Antigen Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Febrile Antigen Kits Market Insights
Modular panel configurations that bundle multiple febrile pathogen antigens into single-test formats is broadening procurement options for ministries of health and NGO buyers. Abbott Laboratories leverages its diagnostic platform breadth to sustain integrated supply relationships with national reference laboratories. Fortress Diagnostics anchors its position through specialized tropical fever panels distributed across African and Asian public health channels. Biotec competes on cost-optimized rapid test manufacturing for high-volume tender markets.
Febrile antigen kits are immunodiagnostic devices that detect specific antigens associated with fever-causing pathogens such as Plasmodium, Salmonella typhi, dengue virus, and Leptospira through lateral flow chromatography or enzyme-linked immunosorbent assay formats, typically requiring 15-30 minutes for qualitative or semi-quantitative results at the point of care or in laboratory settings. These kits serve primarily as screening and triage tools in resource-limited clinical environments where molecular confirmation remains unavailable or cost-prohibitive. Lateral flow products dominate procurement volumes due to minimal equipment requirements and ambient temperature stability, while ELISA formats capture margin pools in reference laboratory segments requiring higher analytical sensitivity. Point-of-care delivery mode leads absolute unit demand through malaria control programs and outbreak response protocols, though laboratory-based testing sustains higher per-test revenue in urban hospital networks conducting differential fever diagnosis.
FDA 510(k) clearance pathways and WHO prequalification programs shape product standards for manufacturers targeting regulated and donor-funded procurement channels respectively, with CE marking under the EU In Vitro Diagnostic Regulation creating additional compliance thresholds for European market access. National regulators in India, Nigeria, and Indonesia enforce import licensing and post-market surveillance that filter out uncertified suppliers. Stakeholders must monitor evolving WHO target product profiles for multiplex fever diagnostics and alignment of manufacturing quality systems with harmonized standards across priority disease control programs.
Market Dynamics
WHO prequalification requirements and ISO 13485 certification standards are compressing the supplier base while elevating quality thresholds for febrile antigen kit manufacturers serving donor-funded procurement channels. This regulatory tightening favors established diagnostic platforms with integrated quality management systems over opportunistic entrants.
Growth Catalysts
- Point-of-care testing protocols:Malaria control programs in Nigeria and Ethiopia are embedding rapid diagnostic testing into community health worker workflows, expanding test penetration beyond facility walls.
- CE marking under EU IVDR:The In Vitro Diagnostic Regulation's enhanced technical documentation requirements are filtering out substandard manufacturers and consolidating procurement toward certified suppliers.
- Multiplex panel configurations:Bundled detection of Plasmodium, dengue, and typhoid antigens within single-test formats reduces per-pathogen screening costs for ministries of health managing undifferentiated fever presentations.
Market Restraints
- Biological raw material volatility:Recombinant antigen and antibody supply concentrates among European and North American specialty chemical producers, exposing manufacturers to input cost fluctuations and currency risk.
- Reference laboratory capacity gaps:Molecular confirmation infrastructure remains scarce in rural Democratic Republic of Congo and northern Mozambique, limiting algorithmic deployment of antigen screening tools.
- Substitution by nucleic acid amplification:Loop-mediated isothermal amplification platforms are capturing differential diagnosis segments where analytical specificity outweighs cost sensitivity.
Strategic Opportunities
- Indonesia's archipelago logistics challenge:Cold chain-independent rapid tests with extended ambient temperature stability address last-mile distribution gaps across 17,000 islands.
- Digital result capture integration:Linking lateral flow readers to national surveillance platforms enables real-time outbreak detection and automated stock replenishment.
- India's PLI scheme for medical devices:Production-linked incentive structures are attracting contract manufacturing investment for export-oriented febrile diagnostic production.
Industry Challenges
- Regulatory harmonization complexity:Divergent prequalification timelines between WHO, FDA 510(k), and national regulators in Bangladesh and Pakistan extend product launch cycles.
- Quality control workforce scarcity:ISO 13485-competent auditors and validation specialists are concentrated in Western Europe and East Asia, complicating manufacturing scale-up in target markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Febrile Antigen Kits Market |
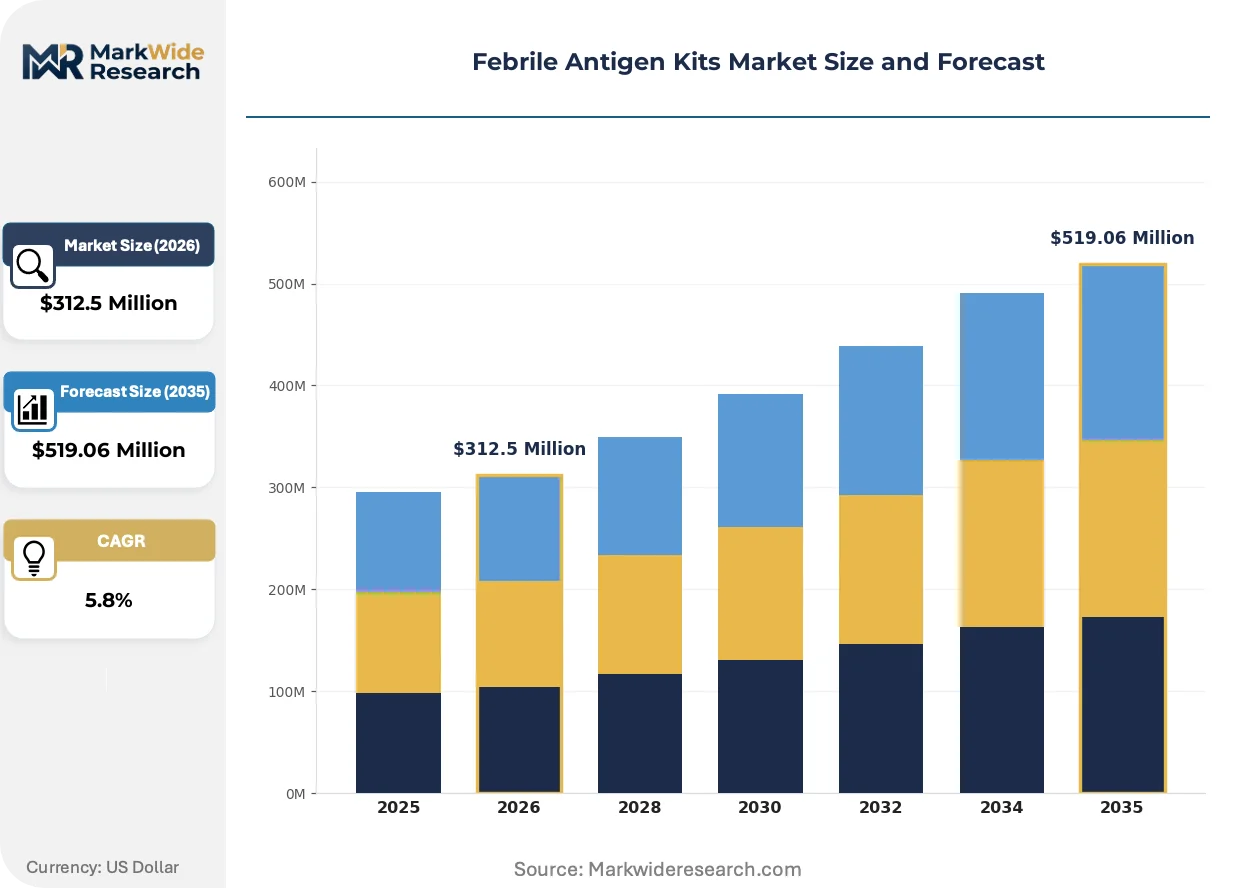
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
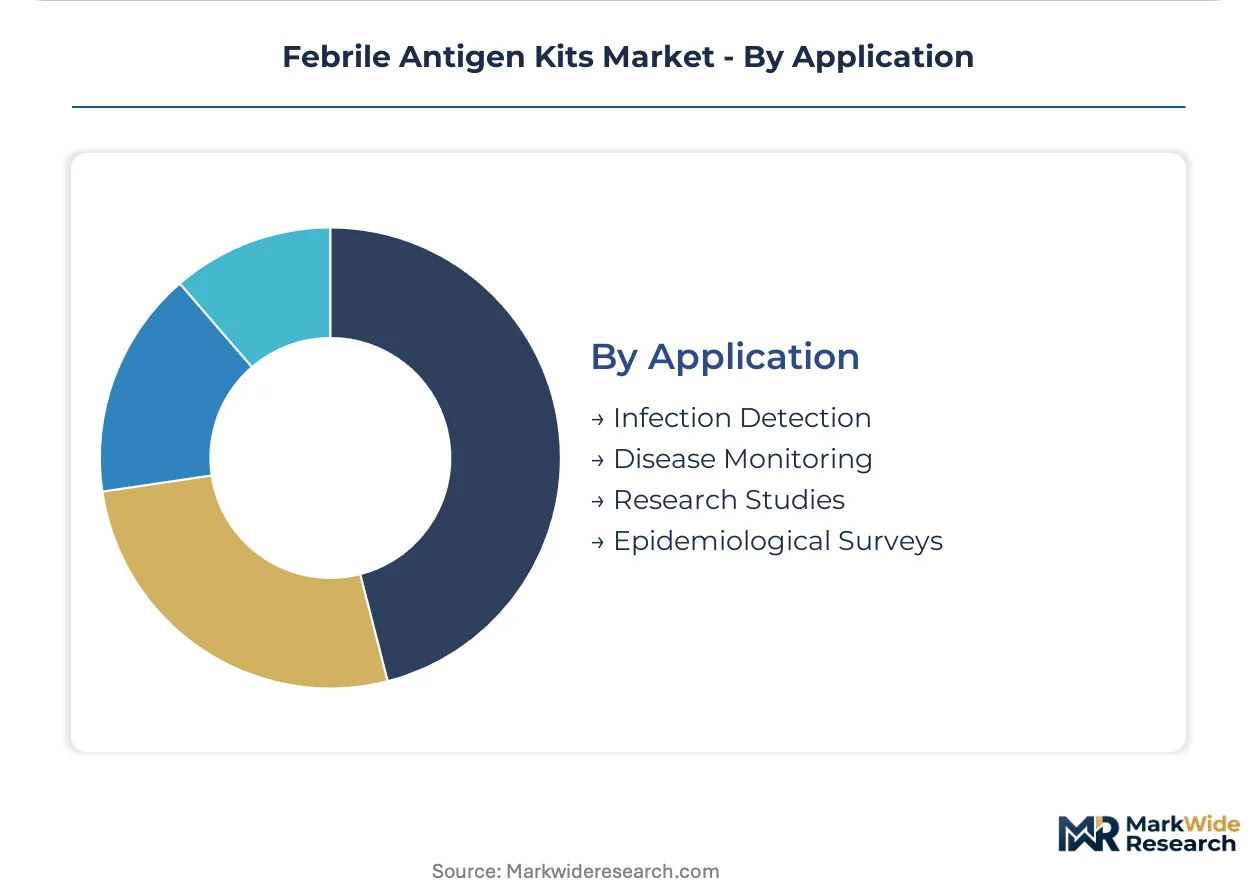
| Segmentation | Product Type: Lateral Flow, ELISA, PCR, Rapid Test Delivery Mode: Point of Care, Laboratory-Based, Home Testing, Telehealth End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Application: Infection Detection, Disease Monitoring, Research Studies, Epidemiological Surveys |
| Companies Covered | Abbott Laboratories, Fortress Diagnostics, Biotec, Cenogenics Corporation, ACON Laboratories Inc., Alfa Scientific Designs Inc., Artron Laboratories Inc., F. Hoffmann-La Roche AG, Beckman Coulter, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Febrile Antigen Kits Market Trends and Innovations
Multiplexing capabilities and connected diagnostic platforms are compressing the traditional separation between screening and confirmation testing. Manufacturers are embedding software integration and supply chain visibility as core product features rather than aftermarket add-ons.
Lateral flow immunoassay miniaturization is decentralizing fever diagnostics from centralized laboratories to community health posts and pharmacy counters. District health offices in Ghana and Senegal are deploying pocket-sized readers that deliver quantitative results without mains electricity. This capability shift is collapsing the infrastructure barrier that previously restricted testing to urban hospital networks.
CE marking transitions under the EU In Vitro Diagnostic Regulation are forcing manufacturers to rebuild technical documentation and clinical evidence packages. The MDR's stricter post-market surveillance obligations are extending compliance costs toward smaller kit producers. European reference laboratories are consolidating supplier relationships toward platforms with established notified body partnerships and pan-European distribution infrastructure.
Integrated supply contracts are replacing transactional tender purchasing in high-burden fever programs. Global health procurement agencies are bundling diagnostic kits with training, quality assurance, and data management services into multi-year agreements. This model concentrates purchasing power among vertically integrated suppliers capable of delivering end-to-end program support across South Asia and sub-Saharan Africa.
Febrile Antigen Kits Market Segmentation
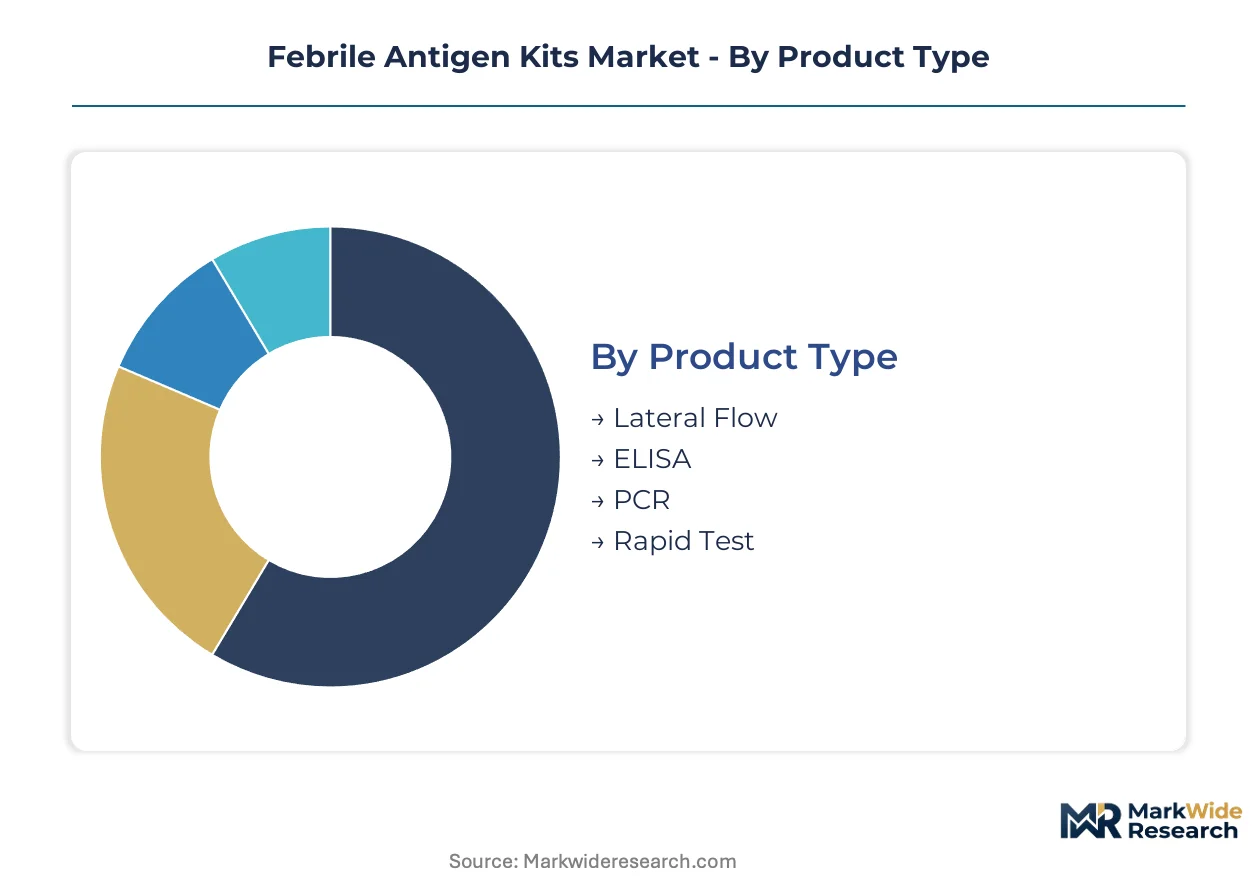
Segmentation in febrile antigen kits reflects divergent performance requirements across clinical settings, from village health posts lacking electricity to urban reference laboratories processing thousands of samples daily. Procurement patterns split sharply between donor-funded malaria programs optimizing for unit cost and hospital networks prioritizing analytical sensitivity for differential fever diagnosis.
Product Type:
Lateral flow and ELISA formats anchor the technology spectrum, with PCR and rapid tests occupying distinct performance-cost positions in the diagnostic hierarchy.
- Lateral Flow:These immunochromatographic strips detect target antigens through antibody-coated nitrocellulose membranes, producing visible lines within 15-20 minutes without equipment. Demand concentrates in Nigeria's community health worker programs and Ethiopia's malaria elimination zones, where ambient temperature stability and minimal training requirements override sensitivity limitations.
- ELISA:Enzyme-linked immunosorbent assays deliver quantitative optical density readings through microplate formats, capturing higher per-test margins in urban hospital laboratories conducting typhoid and leptospirosis surveillance in India and Bangladesh.
- PCR:Nucleic acid amplification platforms target reference laboratories requiring species-level Plasmodium differentiation that antigen tests cannot provide.
- Rapid Test:Simplified one-step formats with pre-dispensed reagents address pharmacy counter and emergency department triage in Indonesian district hospitals.
Lateral flow leads on scale through malaria control procurement volumes; PCR gains momentum through differential diagnosis substitution in urban networks.
Delivery Mode:
Distribution infrastructure and electricity access dictate where each delivery mode deploys, with cold chain requirements filtering options across archipelago and landlocked geographies.
- Point of Care:Battery-independent lateral flow readers and smartphone-connected result capture are expanding test penetration beyond facility walls into Senegal's community health posts and Ghana's pharmacy networks.
- Laboratory-Based:Centralized processing with trained technicians and quality control protocols sustains higher revenue per test in Indian metropolitan hospital chains and Nigerian federal medical centers.
- Home Testing:Self-administered formats with pictorial instructions address urban consumer segments in South African private health markets.
- Telehealth:Digital result transmission to remote clinicians supports outbreak surveillance in Indonesian outer islands beyond laboratory infrastructure reach.
Laboratory-based testing commands premium pricing; point-of-care delivery climbs fastest through community health worker integration.
End User:
Procurement authority and reimbursement pathways segment end users by volume scale and technical sophistication requirements.
- Hospitals:Inpatient fever workups and emergency department triage drive demand for multiplex panels in Indian tertiary care centers and Nigerian teaching hospitals.
- Diagnostic Laboratories:High-throughput reference facilities in South Africa and Kenya process government tender volumes with automated ELISA platforms and external quality assurance participation.
- Clinics:Primary health centers in Bangladesh and Pakistan rely on lateral flow stock maintained through essential medicines supply chains.
- Research Institutions:Academic medical centers in Thailand and Brazil conduct fever etiology studies requiring archived sample banks and standardized assay protocols.
Diagnostic laboratories dominate procurement tonnage; hospitals show steepest expansion trajectory through integrated fever management protocols.
Application:
Clinical purpose determines test specification, from binary screening algorithms to longitudinal cohort tracking with standardized methodologies.
- Infection Detection:Acute case identification for malaria, dengue, and typhoid dominates procurement in endemic districts of Myanmar and the Democratic Republic of Congo.
- Disease Monitoring:Recurrence tracking in treated patients supports therapeutic response assessment in Ethiopian malaria elimination districts.
- Research Studies:Standardized antigen detection underpins fever etiology investigations at Mahidol University and University of Ibadan.
- Epidemiological Surveys:Cross-sectional seroprevalence mapping guides resource allocation in Indonesian provincial health offices and Ugandan district surveillance units.
Infection detection anchors procurement volumes; epidemiological surveys gain share fastest through integrated disease surveillance platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Febrile antigen kit production traces its commercial roots to European diagnostic houses that pioneered malaria rapid tests for colonial health services in the mid-twentieth century. Manufacturing subsequently dispersed to Asian contract producers as procurement volumes scaled through WHO and Global Fund programs. Today, demand concentrates where tropical fever burden intersects with expanding diagnostic infrastructure.
Nigeria
Community health worker programs in Kano and Oyo states drive lateral flow procurement volumes for malaria elimination zones. The National Agency for Food and Drug Administration and Control enforces import licensing that filters uncertified suppliers from federal medical center tenders. Lagos anchors commercial distribution networks supplying northern clinics through essential medicines supply chains.
India
Typhoid and dengue surveillance in Uttar Pradesh and Bihar state hospitals sustains ELISA platform demand alongside rapid test volumes. The Central Drugs Standard Control Organization mandates manufacturing facility inspections under the Medical Devices Rules for kit registration. Gujarat's pharmaceutical clusters host contract manufacturers serving export markets through production-linked incentive structures.
Indonesia
Archipelago logistics across 17,000 islands favor cold chain-independent rapid tests with extended ambient temperature stability for outer island health posts. The national pharmaceutical regulator enforces post-market surveillance protocols that elevate quality thresholds for tender participation. Java's district hospital networks in Yogyakarta and Surabaya pilot digital result capture linked to national surveillance platforms.
Ethiopia
Malaria control program expansion into Afar and Somali regions embeds point-of-care testing into pastoralist health outreach. The Ethiopian Food and Drug Authority aligns import standards with WHO prequalification requirements for donor-funded procurement channels. Addis Ababa's federal medical centers process reference laboratory confirmation for differential fever diagnosis algorithms.
Bangladesh
Dengue outbreak response in Dhaka and Chittagong metropolitan areas sustains seasonal procurement surges for rapid diagnostic kits. The Directorate General of Drug Administration enforces batch release testing that extends product launch timelines for new market entrants. Khulna's medical college hospitals anchor regional reference capacity for southern district fever surveillance networks.
Febrile Antigen Kits Market Competitive Landscape
The competitive structure tilts toward vertically integrated diagnostic platforms with established quality management systems. Regulatory tightening under WHO prequalification and ISO 13485 certification compresses the supplier base toward incumbent manufacturers with notified body partnerships. Three archetypes dominate: multinational platform holders leveraging integrated supply relationships, regional specialists anchoring tropical fever panel distribution, and cost-optimized rapid test producers serving high-volume tender markets. Consolidation pressures manifest through multi-year integrated supply contracts replacing transactional purchasing, and manufacturing scale requirements filtering opportunistic entrants.
Among multinational platform holders, Abbott Laboratories and F. Hoffmann-La Roche AG occupy positions representing end-to-end diagnostic infrastructure. Fortress Diagnostics exemplifies the regional specialist archetype through concentrated tropical fever panel distribution. Biotec sits within the cost-optimized manufacturing tier addressing procurement-sensitive public health channels. These three anchors illustrate how competitive positioning stratifies across certification grade, geographic reach, and production scale rather than product differentiation alone.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Fortress Diagnostics |
| Biotec |
| Cenogenics Corporation |
| ACON Laboratories Inc. |
| Alfa Scientific Designs Inc. |
| Artron Laboratories Inc. |
| F. Hoffmann-La Roche AG |
| Beckman Coulter, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between WHO-prequalified and uncertified kits splits procurement budgets and manufacturing footprints across febrile antigen production. Ministries of health in Nigeria and Ethiopia pay premiums for prequalified lateral flow tests while informal channels absorb lower-grade inventory, concentrating high-spec production in ISO 13485-certified facilities in India and Germany.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the febrile antigen kit market by certification status and performance specifications. WHO prequalification and FDA 510(k) clearance command 40-60% markups over CE-marked standard tiers, while economy kits lacking notified body certification compete purely on unit cost for private pharmacy channels in Bangladesh and Pakistan. Price differentiation intensifies as Global Fund procurement shifts toward multiplex panel formats that bundle malaria, dengue, and typhoid detection. Government tenders in India and Indonesia exhibit extreme price sensitivity, while reference laboratories in South African metropolitan hospitals prioritize analytical sensitivity over per-test cost.
Supply Chain Analysis
Direct-to-ministry distribution channels handle high-volume tender awards across sub-Saharan Africa, while distributor networks serve fragmented private clinic demand in South Asia. Nitrocellulose membrane production concentrates in the United States and Germany, with recombinant antigen synthesis anchored in European biotechnology clusters. Supply chain risk manifests through biological raw material dependence on specialty chemical producers exposed to currency volatility and batch-to-batch consistency requirements. Distribution runs through cold chain-independent logistics for ambient-stable rapid tests reaching Indonesia's outer islands and Ethiopia's pastoralist zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The febrile antigen kit market operates as a regulatory compounder where WHO prequalification milestones determine procurement access across donor-funded malaria and dengue control programs.
For Market Incumbents: Lock in multi-year integrated supply contracts with national reference laboratories before IVDR compliance costs filter additional competitors from European tenders. Fortify positions by embedding digital result capture and automated stock replenishment into lateral flow platforms, countering substitution pressure from nucleic acid amplification technologies in urban hospital networks. Prioritize backward integration into recombinant antigen production to buffer margin compression from biological raw material volatility. For New Entrants and Emerging Players: Smartphone-connected quantitative readers offer a technology-first wedge for community health worker programs in Senegal and Ghana seeking laboratory-grade sensitivity without infrastructure investment. Target Indonesia's archipelago logistics gap with extended ambient temperature stability formulations that bypass cold chain requirements. Pursue contract manufacturing partnerships under India's PLI scheme for medical devices to access export-oriented production capacity without capital-intensive facility builds. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing established tropical fever panel distribution across African public health channels and notified body partnerships for accelerated CE marking. Five-to-ten-year viability hinges on consolidation of fragmented procurement toward vertically integrated platforms capable of delivering training, quality assurance, and data management alongside test kits. Monitor WHO target product profile releases for multiplex fever diagnostics as the critical signal for technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Global Fund and national malaria program procurement in Nigeria and Ethiopia. |
| Multiplex Panel Development | Bundles Plasmodium, dengue, and typhoid antigens to reduce per-pathogen screening costs for ministries of health. |
| Digital Platform Integration | Links lateral flow readers to national surveillance systems enabling real-time outbreak detection in Indonesia. |
| Regional Manufacturing Scale-Up | Leverages India's PLI scheme to capture export-oriented production for high-volume tender markets. |
| Quality Management Certification | ISO 13485 compliance filters opportunistic entrants from donor-funded procurement channels. |
Research Methodology
Coverage spans South Asia, sub-Saharan Africa, and Southeast Asia, with primary inputs from each region's diagnostic procurement landscape. Research combined structured interviews with biomedical engineers at Indian tertiary care centers, GPO contracts managers in Nigerian federal medical centers, and regulatory affairs specialists at WHO-prequalified manufacturers. Secondary validation drew from hospital procurement databases, Global Fund tender disclosures, and CDSCO manufacturing facility inspection records. Bottom-up unit demand modeling triangulated against top-down procurement budget allocations across priority disease control programs.
Rate-of-change decomposition separated volume expansion from price trajectory across lateral flow, ELISA, and emerging nucleic acid amplification formats. Segmentation dimensions included product type, delivery mode, end-user category, and application purpose across the projection horizon. CAGRs were derived from algorithmic fitting to historical tender volumes and forward-looking ministry of health budget commitments. Forecast inputs incorporated malaria elimination timeline assumptions and dengue outbreak frequency patterns from epidemiological surveillance data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to WHO prequalification timeline shifts and nucleic acid amplification cost curves. Base assumptions include sustained donor funding for malaria control programs and stable recombinant antigen supply from European specialty producers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Antibody Testing Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market