
 Sexually Transmitted Diseases Diagnostics Market | 2026-2036
Sexually Transmitted Diseases Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Sexually Transmitted Diseases Diagnostics Market Analytics
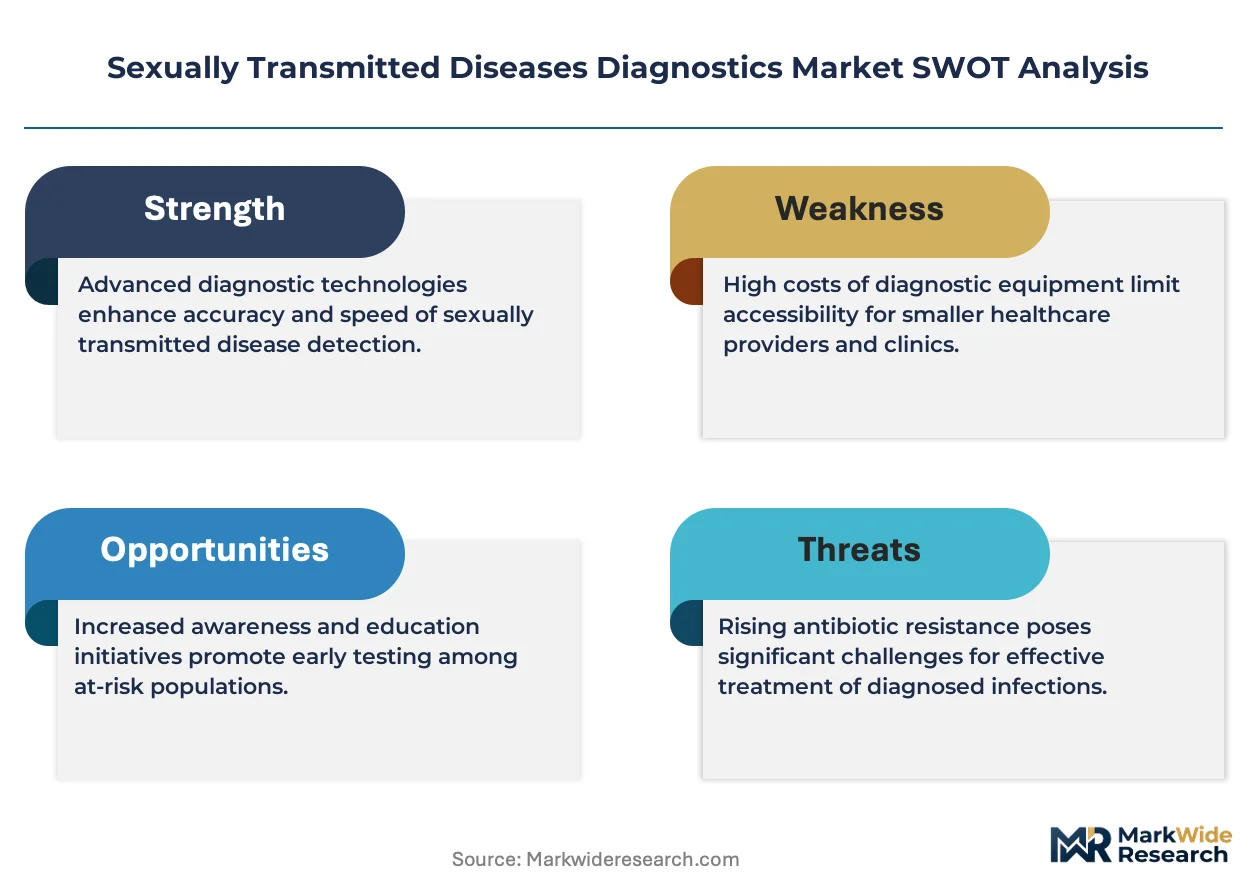
Hospital procurement of sexually transmitted disease diagnostics is tilting toward integrated platform vendors with full molecular workflows. Abbott Laboratories leverages its Alinity m system to anchor large reference lab contracts across North America. F. Hoffmann-La Roche sustains dominance in high-throughput PCR through its cobas franchise. BioMérieux specializes in syndromic multiplex panels that differentiate its BioFire platform in emergency department settings.
Sexually transmitted diseases diagnostics encompass laboratory and point-of-care assays designed to detect bacterial, viral, and parasitic pathogens through nucleic acid amplification, antigen detection, or serological response, with sensitivity specifications typically exceeding 95% for FDA-cleared PCR methods. These products serve public health screening, clinical treatment decisions, and partner notification protocols. PCR Tests occupy the largest revenue pool due to reimbursement stability and regulatory familiarity, while CRISPR-based assays represent the fastest-growing technology segment as developers pursue instrument-free formats. Home Testing Services command premium pricing but face margin pressure from return logistics and confirmatory testing requirements.
FDA premarket review shapes product development timelines for US manufacturers, while EMA CE-IVD requirements govern European market access and influence design control documentation. WHO prequalification programs expand addressable demand in low-resource settings by harmonizing performance standards. Stakeholders must monitor evolving CLIA complexity classifications for near-patient molecular platforms.
Market Dynamics
Molecular platform consolidation is compressing vendor diversity as hospital systems demand unified workflows spanning sample-to-result automation and interoperable data management. This structural pressure favors integrated system suppliers over point-solution developers.
Growth Catalysts
- CLIA complexity waivers:The FDA's streamlined 510(k) pathway for moderate-complexity molecular diagnostics accelerates point-of-care deployment in urgent care settings. Community health centers gain same-day result capability.
- German statutory screening mandates:Statutory health insurance in Germany requires blanket STI screening for at-risk populations, creating institutionalized demand for high-throughput PCR capacity in regional laboratory networks.
- CRISPR instrument-free formats:CRISPR-based assays eliminate thermal cycler dependency, enabling deployment in resource-limited clinics without capital equipment infrastructure. Developers target WHO prequalification for low-resource settings.
Market Restraints
- Reimbursement compression:US Medicare's clinical laboratory fee schedule exerts downward pressure on PCR test pricing, squeezing margins for independent reference laboratories.
- Supply concentration in oligonucleotide synthesis:Specialized reagent manufacturing concentrates among a limited supplier base, exposing test manufacturers to input cost volatility and allocation constraints.
- Confirmatory testing requirements:Positive rapid antigen results mandate follow-up nucleic acid confirmation, adding cost and logistical friction to home testing service models.
Strategic Opportunities
- Underpenetrated Indian urban corridors:Tier-2 and tier-3 Indian cities lack accessible molecular diagnostics infrastructure, presenting white space for hub-and-spoke laboratory networks.
- Telehealth-integrated home sampling:Digital health platforms combine remote consultation with self-collection kits, creating a direct-to-consumer channel bypassing traditional clinical access points.
- EMA CE-IVD harmonization:Converging European technical documentation requirements reduce redundant conformity assessments, accelerating multi-country commercialization for panel developers.
Industry Challenges
- Molecular diagnostics technologist shortage:Specialized training requirements for complex amplification protocols constrain laboratory expansion plans in competitive labor markets.
- Legacy LIS integration complexity:Hospital information systems require custom middleware development to accommodate new instrument data formats, extending implementation timelines.
- Multiplex patent thickets:Overlapping intellectual property claims on detection chemistries complicate freedom-to-operate analysis for syndromic panel developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sexually Transmitted Diseases Diagnostics Market |
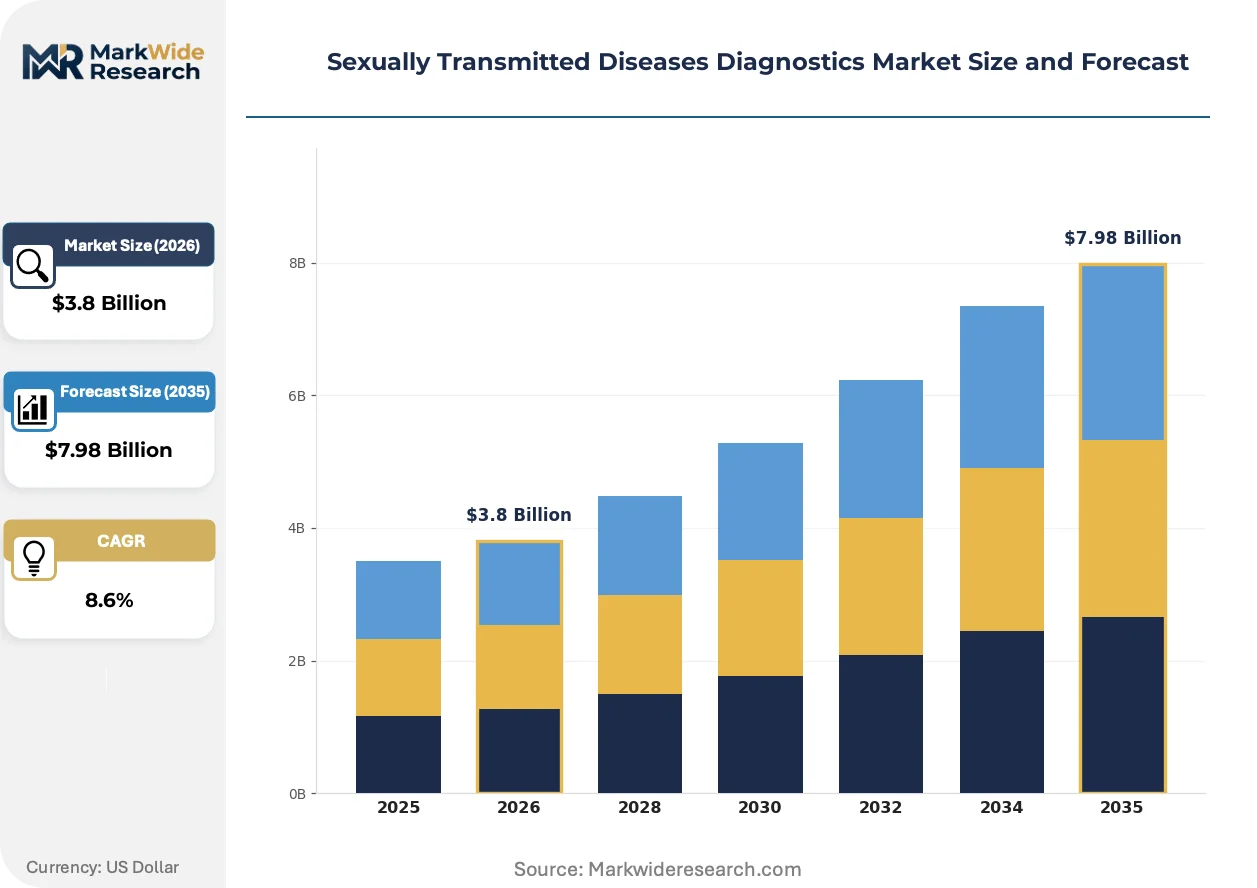
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Tests, Rapid Tests, Serology Tests, Nucleic Acid Tests Technology: Microfluidics, Immunoassays, Next-Generation Sequencing, CRISPR End User: Hospitals, Clinics, Laboratories, Home Testing Services Delivery Mode: Point-of-Care, Laboratory-based, At-home, Mobile Testing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Hologic, Thermo Fisher Scientific, Bio-Rad Laboratories, Danaher Corporation, Siemens Healthineers, Becton Dickinson and Company, BioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sexually Transmitted Diseases Diagnostics Market Evolving Landscape
Digital connectivity and miniaturized chemistry are converging to relocate diagnostic capability closer to patient encounter points, compressing the traditional centralized laboratory model while expanding test menu breadth at the edge.
CRISPR-Dx platforms leverage programmable RNA-guided nucleases for pathogen detection without thermal cycling infrastructure. Urgent care chains and retail health clinics are piloting cartridge-based formats for same-visit prescribing decisions. This architecture is virtualizing the molecular laboratory, collapsing sample transport and batch processing into single-patient workflows.
REACH chemical registration requirements in Europe now govern reagent manufacturing inputs, compelling diagnostics suppliers to document substance safety profiles across their supply base. Panel manufacturers face expanded due diligence obligations for oligonucleotide precursors. CE-IVD technical files must incorporate expanded chemical safety attestations, lengthening design history documentation.
Hospital procurement committees now bundle instrument placement with multi-year reagent supply commitments and service level agreements, displacing transactional test purchasing. Integrated delivery networks negotiate enterprise pricing spanning multiple facility sites. This concentration of buying authority is most visible in US metropolitan health systems consolidating independent laboratories into centralized hubs.
Sexually Transmitted Diseases Diagnostics Market Segmentation
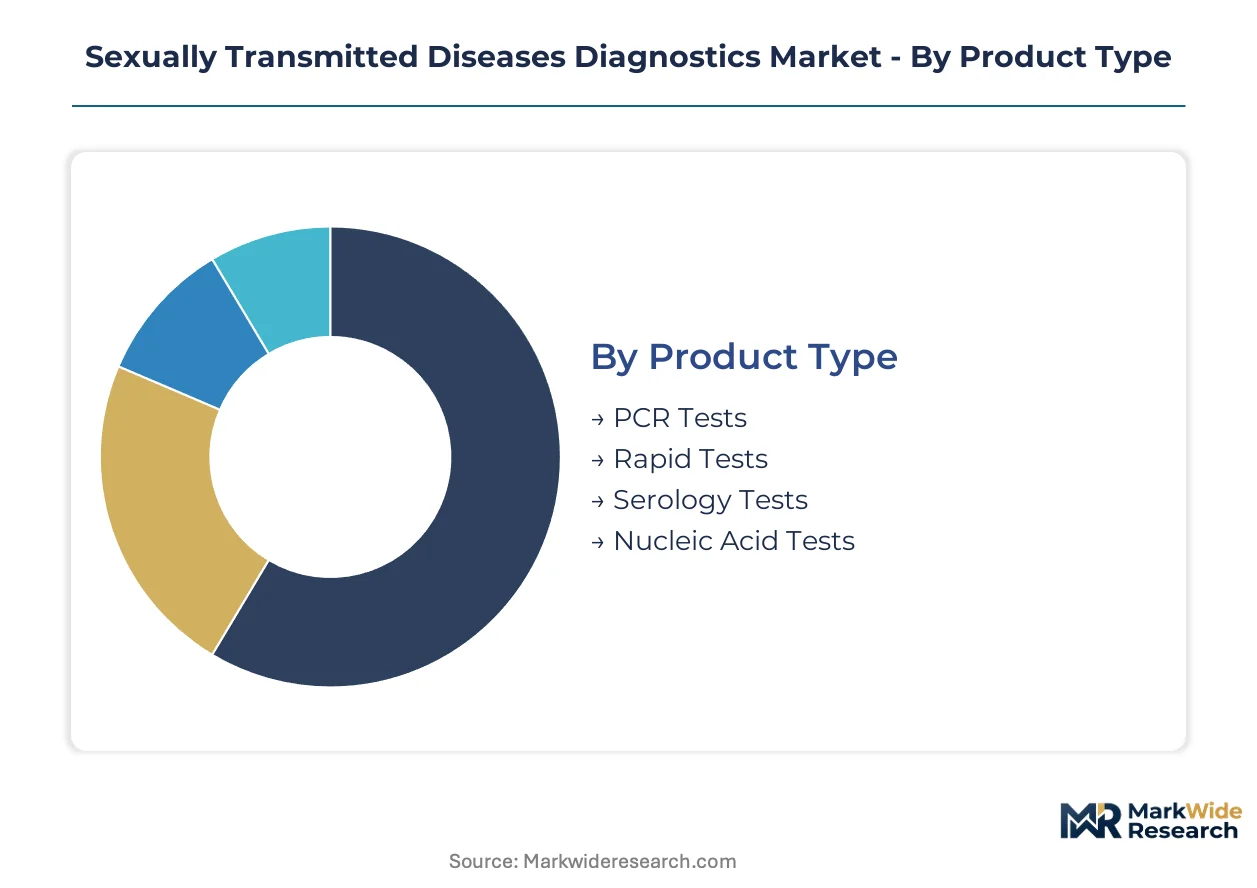
Segmentation in sexually transmitted diseases diagnostics reveals distinct service intensity profiles across product architectures. Technology choices determine capital deployment patterns, while end-user channels dictate regulatory complexity and margin structures differently.
Product Type:
After-sales service intensity varies sharply across assay formats, with instrument-dependent platforms requiring multi-year maintenance contracts and consumable-locked systems demanding continuous reagent supply logistics.
- PCR Tests:Thermal cycler-dependent amplification achieves sensitivity thresholds exceeding 95% for chlamydia and gonorrhea detection. US clinical laboratories anchor demand through Medicare reimbursement stability, though fee schedule compression squeezes independent reference lab margins.
- Rapid Tests:Lateral flow immunochromatography delivers results within 30 minutes without laboratory infrastructure. Community health centers in Germany deploy these for statutory screening compliance, constrained by confirmatory testing mandates for positive results.
- Serology Tests:Antibody detection platforms serve prevalence studies and partner notification protocols.
- Nucleic Acid Tests:Non-PCR amplification chemistries occupy niche applications in resource-limited settings.
PCR Tests hold the largest share; momentum sits with Rapid Tests.
Technology:
Cost tier stratification separates capital-intensive platforms from disposable cartridge systems, with mid-range automation capturing hospital procurement attention.
- Microfluidics:Lab-on-chip architectures integrate sample preparation, amplification, and detection into single-use cartridges. Emergency departments favor BioFire-style syndromic panels for differential diagnosis speed, limited by per-test cost premiums over batch PCR.
- CRISPR:Programmable RNA-guided nucleases enable instrument-free pathogen detection without thermal cycling. Developers pursue WHO prequalification for low-resource clinics lacking capital equipment infrastructure.
- Immunoassays:Antigen-antibody binding platforms dominate rapid test manufacturing.
- Next-Generation Sequencing:Whole-genome approaches support resistance profiling and outbreak investigation.
Immunoassays hold the largest share; CRISPR is expanding most quickly.
End User:
Customer type determines purchasing authority concentration, with integrated delivery networks consolidating laboratory procurement differently than retail health channels.
- Laboratories:High-throughput centralized facilities process batched samples for regional health systems. German statutory insurance mandates sustain volume concentration in accredited reference networks.
- Home Testing Services:Direct-to-consumer self-collection kits combine with telehealth consultation platforms. Return logistics and confirmatory testing requirements erode margin structures despite premium pricing.
- Hospitals:Inpatient and emergency settings demand rapid turnaround for treatment decisions.
- Clinics:Urgent care and retail health locations prioritize same-visit prescribing capability.
Laboratories hold the largest share; Home Testing Services are gaining share fastest.
Delivery Mode:
Volume concentration follows regulatory complexity gradients, with CLIA-waived formats expanding access points faster than moderate-complexity alternatives.
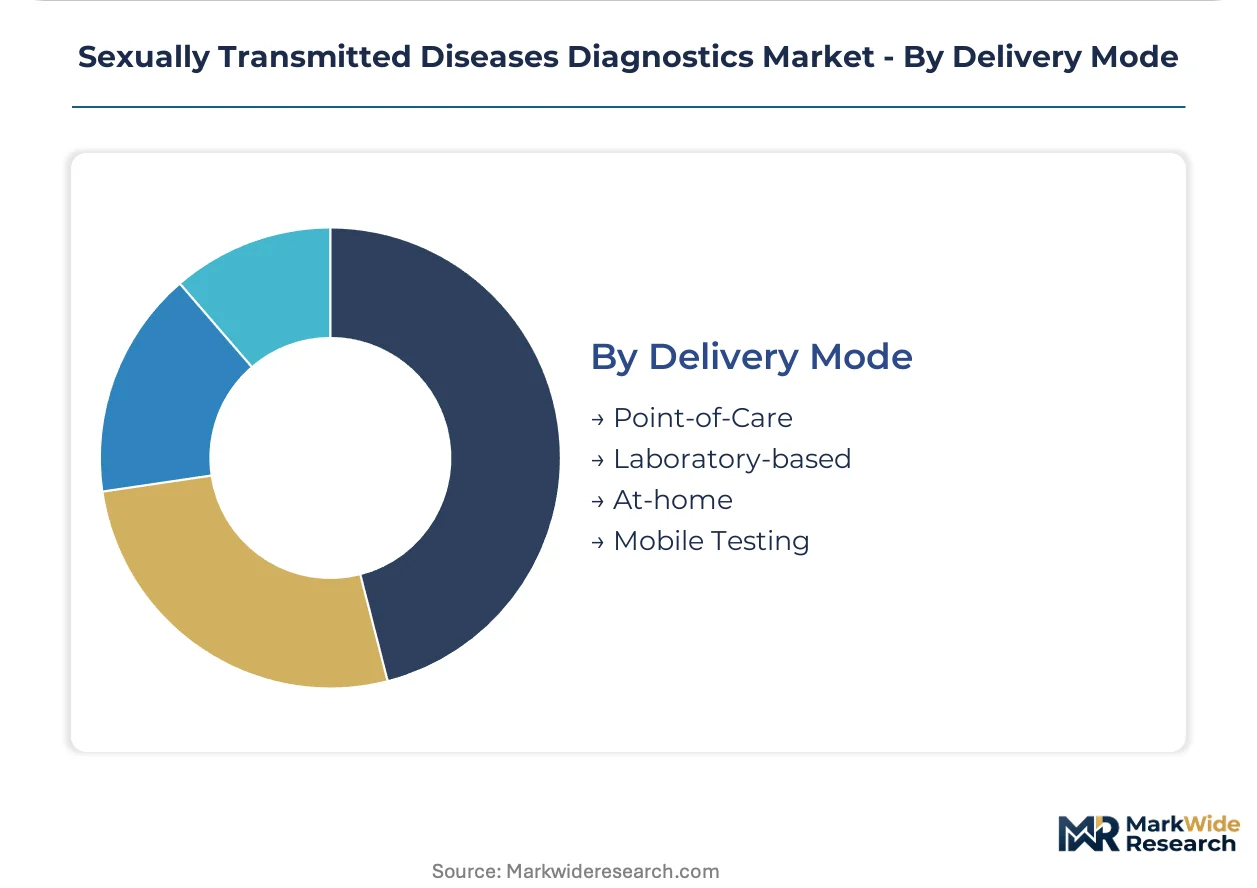
- Laboratory-based:Centralized batch processing maintains cost efficiency for high-volume screening programs. US hospital systems consolidate independent labs into metropolitan hubs, concentrating purchasing authority.
- Point-of-Care:Near-patient molecular platforms eliminate sample transport delays. FDA streamlined 510(k) pathways accelerate deployment in urgent care chains seeking same-day result capability.
- At-home:Self-administered collection with mail-back processing extends reach to privacy-sensitive populations.
- Mobile Testing:Van-based or pop-up services target transient or underserved communities.
Laboratory-based holds the largest share; Point-of-Care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing premiums through statutory screening mandates, while Indian urban corridors absorb cost-sensitive rapid test volumes. This asymmetry shapes regional deployment strategies for molecular platform vendors.
United States
Hospital systems in metropolitan hubs consolidate independent laboratories into centralized facilities, concentrating procurement authority. FDA streamlined 510(k) pathways for moderate-complexity molecular diagnostics accelerate point-of-care deployment in urgent care chains. Greater Boston and the San Francisco Bay Area anchor biotechnology clusters where CRISPR-based assay developers pursue CLIA complexity waivers.
Germany
Statutory health insurance mandates blanket STI screening for at-risk populations, institutionalizing demand for high-throughput PCR capacity. EMA CE-IVD requirements govern European market access and influence design control documentation for panel developers. Regional laboratory networks in North Rhine-Westphalia and Bavaria process screening volumes under accredited reference frameworks.
India
Tier-2 and tier-3 cities lack accessible molecular diagnostics infrastructure, presenting white space for hub-and-spoke laboratory networks. CDSCO regulates in vitro diagnostic imports and domestic manufacturing under the Medical Devices Rules framework. Maharashtra and Karnataka host diagnostic service chains expanding from metropolitan cores into secondary urban corridors.
China
NMPA nucleic acid test approvals concentrate manufacturing capacity for domestic consumption and Belt and Road export markets. National reimbursement catalogs determine hospital procurement eligibility for molecular platforms. Yangtze River Delta diagnostic manufacturers supply both domestic health systems and WHO prequalification programs for low-resource settings.
Brazil
ANVISA regulates IVD registration through risk-based classification pathways that extend review timelines for novel amplification chemistries. Public health laboratory networks in São Paulo and Minas Gerais anchor screening programs for bacterial STI pathogens. SUS reimbursement frameworks favor cost-efficient rapid antigen formats over capital-intensive PCR infrastructure.
Sexually Transmitted Diseases Diagnostics Market Competitive Landscape
Integrated platform vendors and point-solution specialists split the market along workflow automation versus menu flexibility lines. Three to five diversified conglomerates anchor high-throughput molecular diagnostics through multi-year reagent supply contracts. Strategic archetypes include instrument-locked ecosystem builders, syndromic panel specialists, and instrument-free chemistry disruptors. Competitive moves center on hospital procurement committee bundling and CLIA-waiver pathway acceleration.
Within the integrated platform tier, Abbott Laboratories and F. Hoffmann-La Roche exemplify instrument-locked ecosystem strategies, while BioMérieux occupies a position emphasizing syndromic differentiation. These three entities represent contrasting approaches to sample-to-result automation and emergency department workflow capture.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Hologic |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Siemens Healthineers |
| Becton Dickinson and Company |
| BioMérieux |
| Others |
Value Network & Pricing Analysis
Overcapacity in US independent reference laboratories compresses both utilization rates and pricing power, forcing suppliers to absorb cost volatility while buyers consolidate procurement authority into multi-year enterprise contracts.
Pricing Analysis
The customization-premium spread separates instrument-locked reagent contracts from configured-to-order syndromic panels. Three-tier pricing structure across premium, standard, and economy levels tracks FDA clearance tier and CLIA complexity classification. Cost compression in standard-tier PCR tests intensifies because Medicare fee schedule revisions squeeze independent laboratory margins. Hospital systems exhibit lowest price sensitivity due to bundled enterprise procurement, while urgent care chains face acute budget constraints.
Supply Chain Analysis
Extended payment terms from integrated delivery networks now reach 90-120 days, compelling oligonucleotide suppliers to activate supply-chain finance facilities. Manufacturing concentrates in Germany, China, and the United States. Specialized reagent production draws from synthetic oligonucleotide precursors, thermal cycler components, and CRISPR guide RNA synthesis kits. Single-source vulnerability in oligonucleotide synthesis exposes test manufacturers to allocation constraints. Distribution runs through regional laboratory networks and GPO contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement committees, as metropolitan health systems absorb independent laboratories and negotiate enterprise pricing spanning multiple facility sites.
For Market Incumbents: Insulate installed base positions through backward integration into oligonucleotide manufacturing, reducing exposure to supplier allocation constraints. Anchor multi-year reagent supply commitments with service level agreements that extend switching costs for hospital systems facing CLIA-waiver pathway acceleration from emerging CRISPR-based entrants.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian urban corridors present accessible white space lacking molecular diagnostics infrastructure. Target hub-and-spoke laboratory networks with instrument-free CRISPR formats that bypass capital equipment requirements. Pursue WHO prequalification as the go-to-market angle for low-resource clinic penetration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors with locked reagent ecosystems. Five-to-ten year viability favors instrument-locked suppliers over point-solution developers facing procurement committee bundling pressure. Watch FDA 510(k) clearance velocity for CRISPR-based assays as the inflection indicator for platform disruption risk.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Complexity Waiver Pursuit | Accelerates point-of-care deployment in urgent care chains seeking same-day prescribing capability. |
| Reagent Supply Contract Bundling | Locks hospital procurement committees into multi-year enterprise pricing across metropolitan facility networks. |
| WHO Prequalification Pathway | Opens low-resource settings in India and Africa to instrument-free CRISPR diagnostic formats. |
| Syndromic Panel CE-IVD Expansion | Harmonizes European technical documentation for accelerated multi-country commercialization under EMA convergence. |
| Telehealth Platform Integration | Creates direct-to-consumer channel bypassing traditional clinical access points for home testing services. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with clinical laboratory directors, hospital procurement committee members, molecular diagnostics technologists, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EMA CE-IVD technical file repositories, CMS clinical laboratory fee schedules, and WHO prequalification listings. Bottom-up demand modeling and top-down market sizing triangulated volume estimates.
Calibration against historical reimbursement trajectories and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions included technology platform, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derived from regression analysis of reimbursement stability indices and capital equipment deployment rates. Resistance profiling demand and telehealth integration velocity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by instrument-free chemistry disruptors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
D-Dimer Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market