
 Global Electronic Trial Master File (ETMF) Market | 2026-2036
Global Electronic Trial Master File (ETMF) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Trial Master File (ETMF) Market Foresight
Cloud infrastructure is hardening as the dominant deployment substrate across ETMF platforms, displacing legacy on-premise installations that carry heavier compliance maintenance burdens. Veeva Systems leverages multi-tenant cloud architecture to sustain leadership in life sciences verticals. Oracle Corporation anchors enterprise-scale deployments through deep database integration and existing pharmaceutical customer relationships. IQVIA competes by embedding ETMF functionality within broader clinical operations ecosystems.
An Electronic Trial Master File (eTMF) constitutes a digital content management repository that maintains inspection-ready documents for clinical trials, incorporating metadata schemas, automated indexing protocols, and role-based access controls to satisfy regulatory inspection requirements. The system serves pharmaceutical sponsors and contract research organizations by collapsing document retrieval times from days to minutes during regulatory audits. Cloud-based deployment captures the fastest expansion trajectory as biotech firms prioritize operational agility over capital-intensive infrastructure ownership. Document management solutions occupy the deepest margin pools given their centrality to every trial workflow and their integration complexity that raises switching costs substantially.
FDA 21 CFR Part 11, EMA ICH E6(R2), and Japan's PMDA GCP ordinance collectively mandate contemporaneous, attributable, and complete trial records, which directly elevates demand for validated eTMF systems with immutable audit trails. These frameworks impose inspection-readiness standards that legacy paper-based processes cannot satisfy, creating structural tailwinds for compliant software vendors. Stakeholders must monitor evolving EU AI Act provisions that could extend algorithmic transparency requirements into automated document classification tools within eTMF platforms.
Market Dynamics
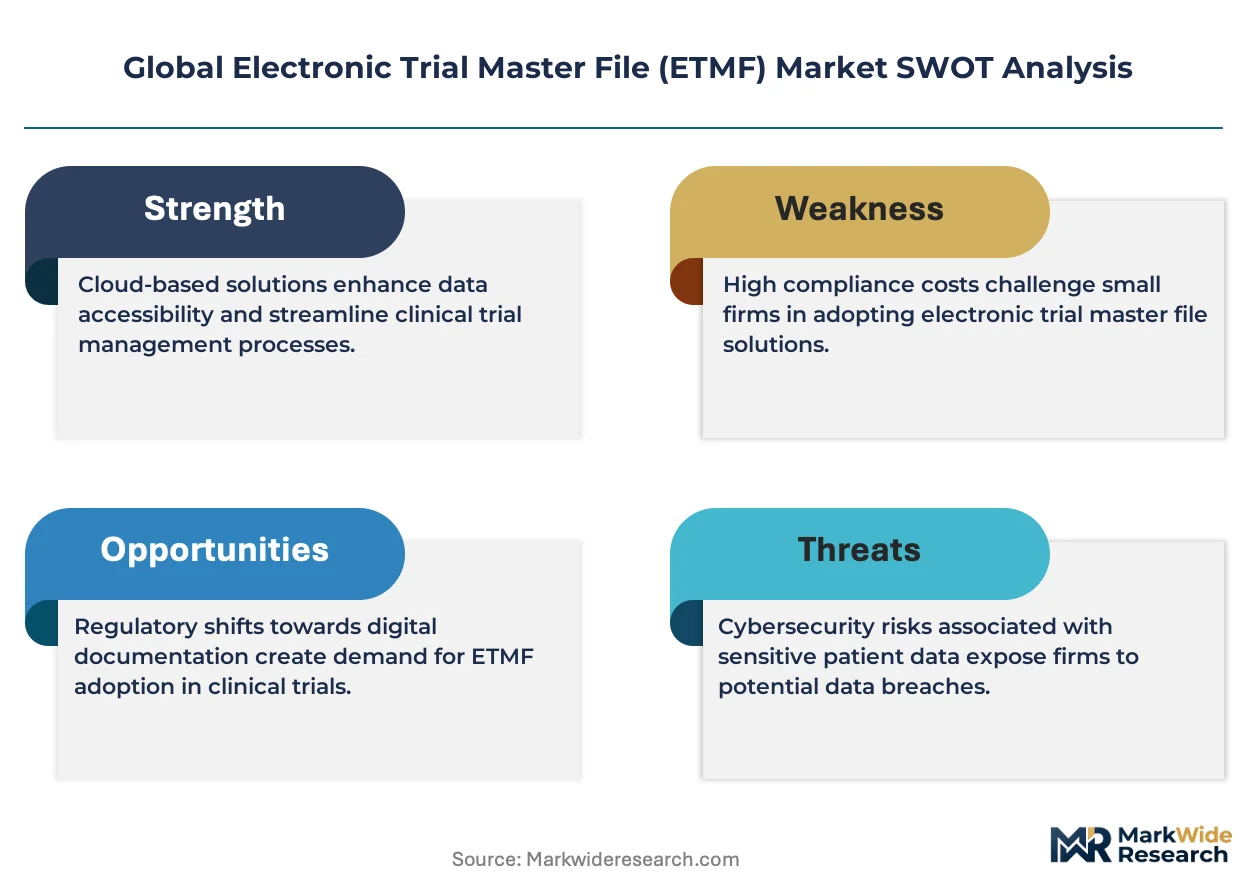
Cloud-native ETMF architectures are consolidating market power by collapsing the cost and complexity barriers that previously protected legacy on-premise installations, forcing incumbent vendors to re-platform or lose enterprise accounts.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates are compelling pharmaceutical sponsors to replace paper-based trial documentation with validated digital systems that ensure inspection readiness.
- Biotech operational agility:Venture-funded drug developers prioritize subscription-based cloud deployments over capital-intensive infrastructure ownership, accelerating vendor selection cycles.
- EMA ICH E6(R2) harmonization:The guideline's emphasis on quality risk management and document control is standardizing eTMF procurement across European trial sites.
Market Restraints
- Data residency requirements:China's NMPA and Russia's data localization laws fragment cloud infrastructure strategies, forcing redundant regional deployments.
- Validation cost concentration:Small contract research organizations face disproportionate compliance burdens relative to enterprise sponsors, constraining vendor addressable markets.
- Interoperability limitations:Proprietary metadata schemas impede seamless document exchange between sponsor and CRO eTMF instances.
Strategic Opportunities
- India clinical trial expansion:CDSCO regulatory reforms and cost arbitrage are attracting multinational sponsors seeking inspection-ready document infrastructure for emerging market studies.
- AI-assisted indexing convergence:Machine learning classification combined with natural language processing promises to automate document metadata extraction and reduce manual curation labor.
- Decentralized trial channels:Direct-to-patient delivery models require new document workflows for remote consent and telemedicine visit records.
Industry Challenges
- CSV talent scarcity:Computer system validation specialists with 21 CFR Part 11 expertise command premium compensation, constraining vendor implementation capacity.
- Legacy system integration friction:Hybrid environments combining existing CTMS, EDC, and eTMF platforms create data synchronization failures and audit trail gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Trial Master File (ETMF) Market |
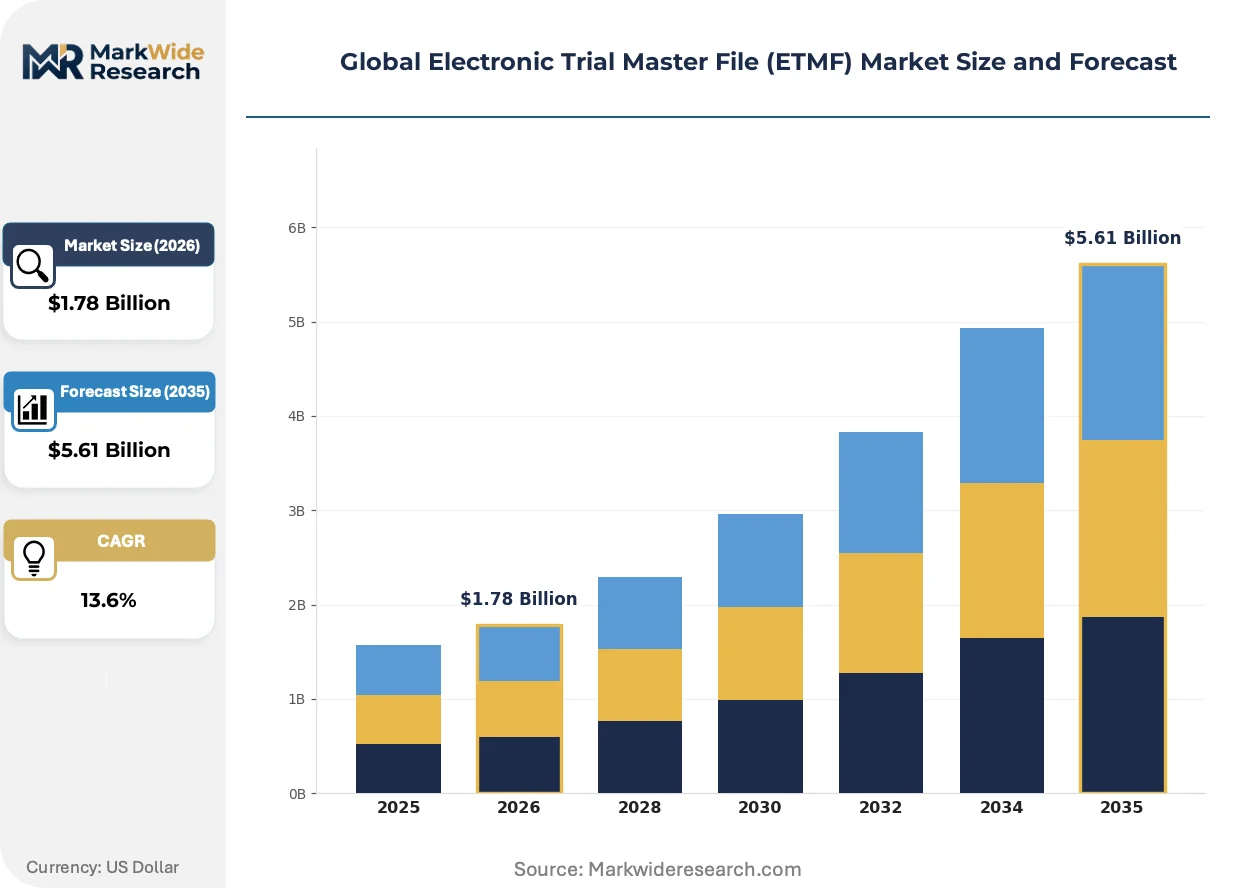
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $5.61 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Document Management, Metadata Management, Collaboration Tools, Compliance Monitoring, Audit Trail Application: Clinical Trials, Regulatory Submissions, Data Monitoring, Quality Assurance, Risk Management Client Type: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Research Institutions |
| Companies Covered | Veeva Systems, Oracle Corporation, IQVIA, Medidata, ArisGlobal, MasterControl, Phlexglobal, TransPerfect, Clinevo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Trial Master File (ETMF) Market Shifts & Advancements
Artificial intelligence and regulatory automation are compressing document lifecycle timelines while reshaping how sponsors and regulators interact with trial evidence.
Machine learning classification engines are consolidating control over document indexing workflows by automating metadata extraction from unstructured clinical content. Mid-tier pharmaceutical sponsors are adopting these tools fastest as they lack dedicated TMF operational staff. The technology is consolidating vendor differentiation around algorithm accuracy rather than storage capacity or user interface design.
The EU AI Act's risk-based framework for automated decision-making is extending transparency requirements into eTMF platforms deploying document classification algorithms. Sponsors must now maintain explainability logs for AI-assisted indexing decisions subject to regulatory inspection. European trial operations teams are responding by demanding vendor-provided algorithm documentation and bias testing protocols before procurement approval.
Subscription pricing models are displacing perpetual license structures across enterprise eTMF procurement, compressing upfront capital requirements into predictable operational expenditures. Vendor finance teams are restructuring revenue recognition while customer procurement functions negotiate consumption-based tiers tied to active trial volumes. This shift is most visible among US biotech sponsors managing cash runway constraints during clinical development.
Global Electronic Trial Master File (ETMF) Market Segmentation
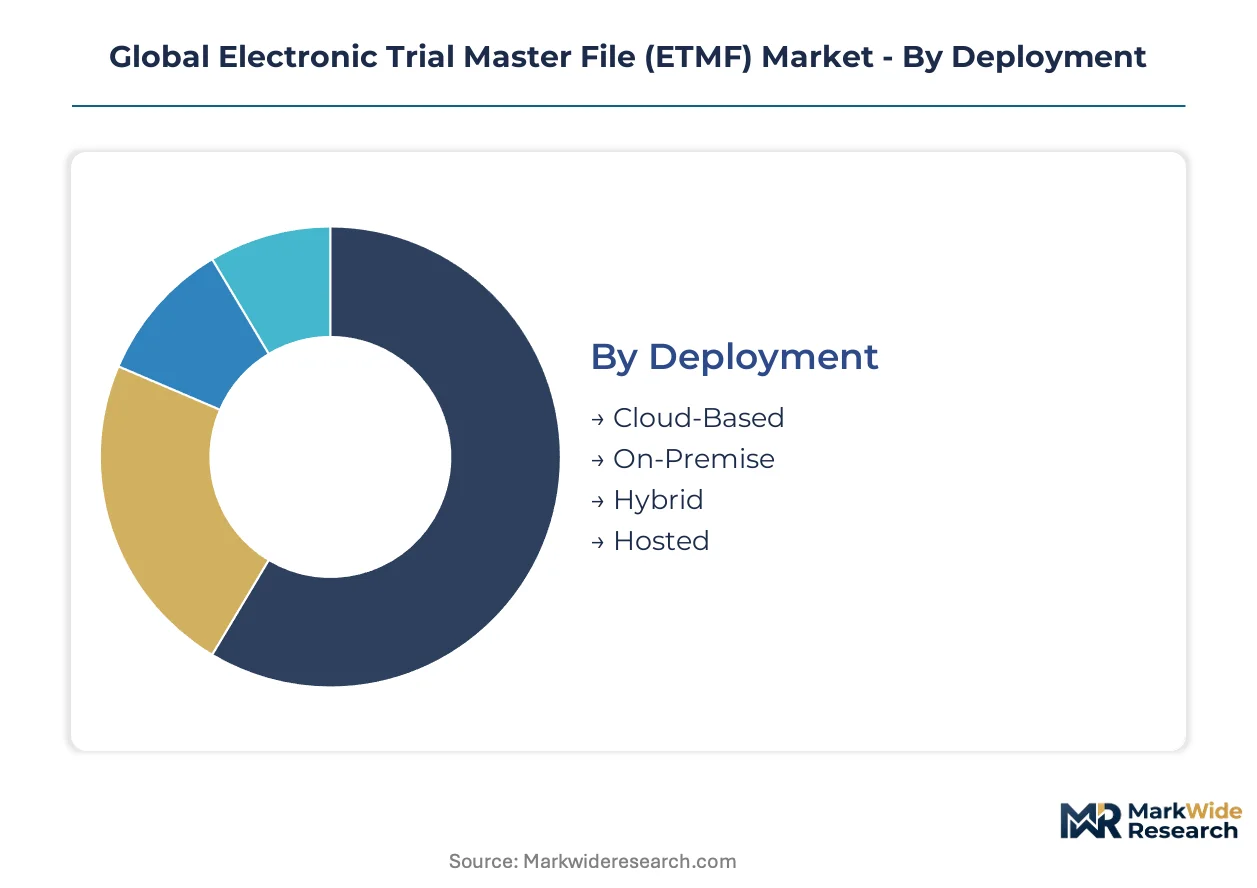
Segmentation in the ETMF market reflects divergent buyer priorities across infrastructure ownership models, regulatory complexity tiers, and organizational scale. Procurement decisions hinge on validation burden tolerance, trial portfolio size, and geographic data residency obligations rather than feature checklists alone.
Deployment:
Buyers select deployment architecture based on capital constraint severity and in-house IT specialization depth.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead and accelerate 21 CFR Part 11 validation through vendor-managed infrastructure. Biotech sponsors in the United States and Germany dominate procurement as they prioritize cash preservation over asset ownership during clinical development cycles.
- On-Premise:Dedicated hardware installations persist among Japanese pharmaceutical incumbents with existing data center investments and conservative security postures. METI cybersecurity guidelines and PMDA inspection precedents reinforce preference for physical control over primary clinical records despite higher operational overhead.
- Hybrid:Split configurations archive completed trial documents on-premise while active studies run in cloud environments, addressing tiered data sensitivity requirements.
- Hosted:Single-tenant managed deployments serve mid-tier sponsors seeking cloud agility without multi-tenant compliance complexity.
Cloud-based deployments lead on scale; hybrid configurations lead on momentum as transitional architectures gain favor among risk-averse enterprises.
Solution Type:
Module selection correlates with organizational TMF operational maturity and inspection history intensity.
- Document Management:Core repository functionality with automated indexing, version control, and role-based access forms the non-negotiable foundation of every ETMF implementation. This segment captures the deepest margin pools due to integration complexity that elevates switching costs.
- Metadata Management:Structured taxonomy engines and automated classification protocols reduce manual curation labor for sponsors managing multi-site global trials. European sponsors facing EMA ICH E6(R2) quality risk management mandates show concentrated adoption.
- Collaboration Tools:Real-time annotation and cross-organizational workflow coordination address sponsor-CRO document exchange friction.
- Compliance Monitoring:Automated inspection-readiness dashboards and deviation flagging systems serve sponsors with recent FDA warning letter experience.
- Audit Trail:Immutable logging with electronic signature verification satisfies the most stringent regulatory evidence requirements.
Document management anchors revenue concentration; metadata management climbs fastest as AI-assisted indexing reduces manual labor dependency.
Application:
Use case prioritization reflects sponsor regulatory exposure and therapeutic area complexity.
- Clinical Trials:End-to-end trial documentation from protocol approval through study closeout constitutes the primary ETMF workload. Phase III oncology sponsors in the United States drive premium module adoption due to FDA inspection intensity.
- Regulatory Submissions:eCTD assembly and health authority correspondence management integrates ETMF content with submission publishing workflows. Japanese sponsors navigating PMDA consultation pathways show distinctive demand concentration.
- Data Monitoring:Centralized statistical review documentation and data quality query resolution support risk-based monitoring implementations.
- Quality Assurance:CAPA tracking and deviation investigation records extend TMF scope beyond core clinical operations.
- Risk Management:Integrated risk assessment documentation and mitigation action tracking aligns with ICH E6(R2) quality by design principles.
Clinical trials command absolute volume share; regulatory submissions expand most quickly as submission-ready documentation becomes a competitive differentiator.
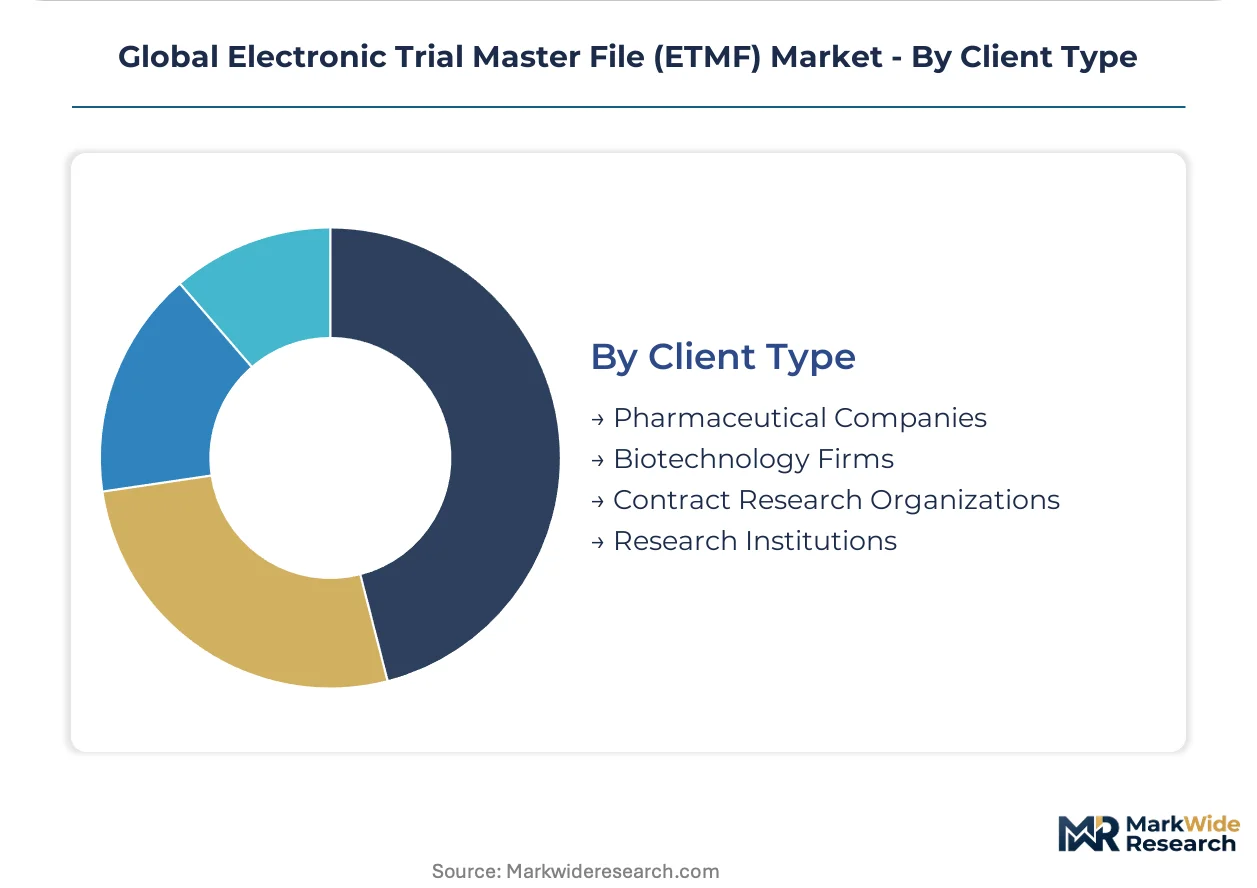
Client Type:
Organizational scale and outsourcing strategy determine solution complexity requirements and pricing tier accessibility.
- Pharmaceutical Companies:Large-cap sponsors with global trial portfolios demand enterprise-scale deployments integrating CTMS, EDC, and regulatory publishing systems. German and Japanese headquarters locations correlate with highest per-seat licensing values.
- Biotechnology Firms:Venture-funded developers prioritize cloud-native platforms with rapid implementation timelines and consumption-based pricing. United States coastal clusters dominate addressable volume.
- Contract Research Organizations:Multi-sponsor service providers require tenant isolation capabilities and standardized inspection-readiness protocols across client portfolios.
- Research Institutions:Academic medical centers and government research bodies seek grant-compliant documentation systems with limited customization requirements.
Pharmaceutical companies dominate contract value; biotechnology firms drive steepest expansion trajectory as venture funding cycles accelerate platform procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors the highest concentration of cloud-native ETMF deployments, driven by venture-funded sponsors prioritizing rapid clinical trial initiation over infrastructure ownership.
United States
FDA 21 CFR Part 11 enforcement intensity and Phase III oncology trial volume propel cloud-based procurement among Massachusetts and California biotech clusters. The FDA's 2023 draft guidance on electronic systems validation tightens vendor selection criteria. Greater Boston sponsors lead adoption of AI-assisted document indexing to compress TMF preparation timelines.
Germany
EMA ICH E6(R2) quality risk management mandates and BfArM inspection protocols standardize eTMF requirements across Bavarian pharmaceutical headquarters. The country's Medical Devices Act implementation extends documentation standards into combination product trials. Munich-based sponsors demand multi-language metadata management for pan-European trial coordination.
Japan
PMDA GCP ordinance amendments and METI cybersecurity guidelines reinforce preference for validated on-premise installations among Tokyo pharmaceutical incumbents. The regulator's 2024 inspection readiness guidelines elevate audit trail immutability requirements. Osaka-Kobe manufacturing clusters drive hybrid deployment adoption for active studies.
India
CDSCO regulatory reforms and cost arbitrage attract multinational sponsors to Hyderabad and Bengaluru clinical research hubs. The New Drugs and Clinical Trials Rules 2019 mandate inspection-ready documentation infrastructure for international study acceptance. Indian CROs in these cities accelerate cloud migration to serve global sponsor portfolios.
Switzerland
Swissmedic's alignment with EMA standards and Basel's pharmaceutical headquarters density sustain premium ETMF module demand. The country's data protection adequacy status simplifies cross-border document exchange with EU trial sites. Geneva-based sponsors prioritize compliance monitoring tools for health authority correspondence management.
Global Electronic Trial Master File (ETMF) Market Competitive Landscape
Platform consolidation dominates the current landscape as multi-product clinical technology suites absorb standalone document management vendors. The market structure concentrates around three tiers: enterprise-scale integrated suites, vertical-specialist platforms, and regional service providers. Two strategic archetypes define positioning: cloud-native SaaS architects leveraging subscription economics, and legacy database vendors exploiting installed-base relationships. M&A activity and API ecosystem expansion represent the dominant competitive vectors reshaping vendor rankings.
Among enterprise-suite providers, Veeva Systems and Oracle Corporation exemplify divergent architectural philosophies, with the former representing multi-tenant cloud specialization and the latter embodying database-centric enterprise integration. IQVIA occupies a distinct position as a clinical services organization embedding ETMF functionality within broader operational ecosystems. These three anchors illustrate how competitive positioning increasingly depends on ecosystem breadth rather than document repository features alone.
| Leading Market Players |
|---|
| Veeva Systems |
| Oracle Corporation |
| IQVIA |
| Medidata |
| ArisGlobal |
| MasterControl |
| Phlexglobal |
| TransPerfect |
| Clinevo Technologies |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS migration is compressing both infrastructure ownership economics and vendor concentration simultaneously, as multi-tenant architectures eliminate on-premise hardware procurement while locking buyers into subscription relationships with fewer platform providers.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers shapes vendor margin structures more than direct customer pricing. The dominant pricing structure is subscription-based SaaS with three-tier pricing structure across premium, standard, and economy levels, differentiated by integration complexity and 21 CFR Part 11 validation depth. Pricing pressure stems from venture-funded biotech sponsors managing cash runway constraints. Biotechnology firms exhibit highest price sensitivity due to funding cyclicality, while large-cap pharmaceutical companies prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Logistics and freight cost exposure remains minimal given software-as-a-service delivery, though data residency requirements fragment cloud infrastructure deployment. Supply concentrates in the United States, Germany, and Japan for primary platform development, with India emerging as a delivery hub for implementation services. Raw material dependencies center on cloud compute capacity, cybersecurity certification services, and specialized computer system validation talent. Single-source vulnerability runs through hyperscaler cloud infrastructure providers. Distribution runs through direct enterprise sales teams and strategic partnerships with contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market derives from AI-assisted document indexing automation reducing manual curation labor while enabling premium-tier pricing for algorithm-validated platforms.
For Market Incumbents: Deploy API ecosystem expansion to defend against standalone document management vendors being absorbed by clinical technology suites. Incumbents should deepen CTMS and EDC integration capabilities to raise switching costs, while investing in explainability documentation for AI-assisted indexing tools to preempt EU AI Act compliance challenges from emerging cloud-native competitors.
For New Entrants and Emerging Players: Direct-to-patient trial documentation workflows represent the most penetrable white-space target, as decentralized trial models lack established document infrastructure. New entrants should prioritize India-based CRO partnerships for cost-arbitrage positioning, leveraging CDSCO regulatory reforms to establish inspection-ready credentials before competing in United States or European procurement cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional service providers with validated 21 CFR Part 11 installations but limited multi-tenant SaaS architecture. Long-term viability favors vendors with embedded positions in pharmaceutical sponsor operational ecosystems rather than standalone repository functionality. The signal to watch is FDA draft guidance finalization on electronic systems validation, which would accelerate replacement demand and consolidate procurement toward enterprise-scale platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Indexing Deployment | Machine learning classification reduces manual metadata curation labor for mid-tier sponsors lacking dedicated TMF staff. |
| Multi-Tenant Cloud Migration | SaaS architecture eliminates server maintenance overhead while accelerating 21 CFR Part 11 validation timelines. |
| API Ecosystem Expansion | Integration with CTMS and EDC platforms raises switching costs and embeds vendors within clinical operations workflows. |
| EU AI Act Compliance Investment | Explainability documentation for algorithmic decisions satisfies emerging transparency mandates for automated document classification. |
| India CRO Partnership Development | CDSCO regulatory reforms create inspection-ready infrastructure demand for multinational sponsor emerging market studies. |
Research Methodology
Multiple input streams — regulatory filing analysis, vendor financial disclosures, and clinical operations stakeholder interviews — were reconciled to construct market estimates. Primary research incorporated discussions with drug development executives, regulatory affairs leads, contract research organization operations directors, and health authority inspection specialists. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA ICH E6(R2) implementation reports, ClinicalTrials.gov registration data, and CDSCO regulatory circulars. Bottom-up trial volume modeling and top-down enterprise software spending analysis were cross-referenced for triangulation.
Historical adoption curves were cross-referenced against panel input from platform vendors and sponsor procurement functions to anchor projections. Segmentation modeling incorporated deployment architecture, solution type, application use case, and client organizational scale across the projection horizon. CAGRs were derived from fitted growth curves calibrated to regulatory mandate implementation timelines and venture funding cycle patterns. Forecast inputs included cloud infrastructure cost trajectories, computer system validation talent availability, and inspection enforcement intensity variations by health authority.
The model assumes a particular technology adoption path; alternative pathways for on-premise persistence among Japanese pharmaceutical incumbents would alter the outlook. Forecasts reflect documented assumptions regarding regulatory harmonization progress and AI governance framework evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Patient Self-Service Kiosks Market