
 Companion Animal Diagnostic Services Market | 2026-2036
Companion Animal Diagnostic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Diagnostic Services Market Analytics
A capital-intensity divergence between in-house laboratory infrastructure and outsourced reference laboratory networks is redrawing competitive boundaries in companion animal diagnostics. IDEXX Laboratories sustains dominant channel control through integrated practice management and diagnostic platform ecosystems. Thermo Fisher Scientific leverages its life sciences manufacturing scale to supply reagents and instruments across multiple veterinary diagnostic brands. Zoetis anchors its position through pharmaceutical-diagnostic bundling and direct veterinary clinic relationships.
Companion animal diagnostic services encompass clinical pathology, imaging, molecular testing, and microbiology performed on dogs, cats, and other household pets, typically requiring sample volumes under 500 microliters and turnaround times ranging from minutes for point-of-care assays to 24–48 hours for reference laboratory cultures. These services enable disease detection, treatment monitoring, and preventive health management across the estimated one billion companion animals worldwide. Molecular diagnostics commands premium pricing due to nucleic acid extraction complexity and specialized technician training requirements, while point-of-care testing expands access through reduced sample handling and immediate clinical decision support. Veterinary clinics represent the most concentrated end-user channel, though mobile veterinary services are gaining traction in rural and suburban geographies where brick-and-mortar specialist access remains limited.
The FDA Center for Veterinary Medicine regulates veterinary diagnostic test kits as animal health devices, while USDA APHIS oversees infectious disease surveillance programs that create institutional demand for standardized testing protocols. State veterinary practice acts and laboratory licensing requirements further fragment market access, with California, New York, and Texas maintaining distinct personnel and quality control standards. Stakeholders must monitor evolving telemedicine regulations and cross-border reference laboratory accreditation frameworks as remote diagnostic consultation and international sample logistics reshape service delivery models.
Market Dynamics
Capital intensity divergence between in-house laboratory infrastructure and outsourced reference laboratory networks is redrawing competitive boundaries in companion animal diagnostics. Veterinary clinics face mounting pressure to consolidate diagnostic procurement around integrated platform ecosystems or surrender margin to specialized reference laboratory networks.
Growth Catalysts
- Pet Humanization Trajectory:Deepening emotional bonds between owners and companion animals elevate preventive care spending. Specialty and emergency animal hospital networks expand fastest in the United States.
- FDA Center for Veterinary Medicine Oversight:Standardized diagnostic assay validation protocols create institutional demand for compliant testing infrastructure. This regulatory clarity accelerates product commercialization timelines for validated manufacturers.
- Point-of-Care Technology Maturation:Reduced sample handling requirements and immediate clinical decision support expand access beyond traditional laboratory settings. Mobile veterinary services gain traction in rural and suburban geographies.
Market Restraints
- Reagent Supply Concentration:Thermo Fisher Scientific's manufacturing scale dominance in life sciences inputs creates dependency risk across multiple veterinary diagnostic brands.
- State Licensing Fragmentation:California, New York, and Texas maintain distinct personnel and quality control standards. Cross-border reference laboratory accreditation frameworks remain underdeveloped.
- Nucleic Acid Extraction Complexity:Molecular diagnostics require specialized technician training that limits service expansion in cost-constrained clinic environments.
Strategic Opportunities
- Telemedicine Regulatory Evolution:Remote diagnostic consultation frameworks are reshaping service delivery models. Stakeholders who monitor evolving state veterinary practice acts capture first-mover positioning.
- USDA APHIS Surveillance Programs:Infectious disease monitoring creates institutional demand for standardized testing protocols. Reference laboratories serving this channel secure recurring revenue streams.
- Mobile Veterinary Channel Expansion:Brick-and-mortar specialist access limitations in suburban markets create white space for equipped mobile operators.
Industry Challenges
- Sample Volume Microfluidics Expertise:Clinical pathology workflows requiring under 500 microliters demand specialized engineering talent that concentrates in select metropolitan clusters.
- Legacy Practice Management Integration:Diagnostic platform ecosystems must interface with entrenched software infrastructure. Compatibility failures erode clinic willingness to switch suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Diagnostic Services Market |
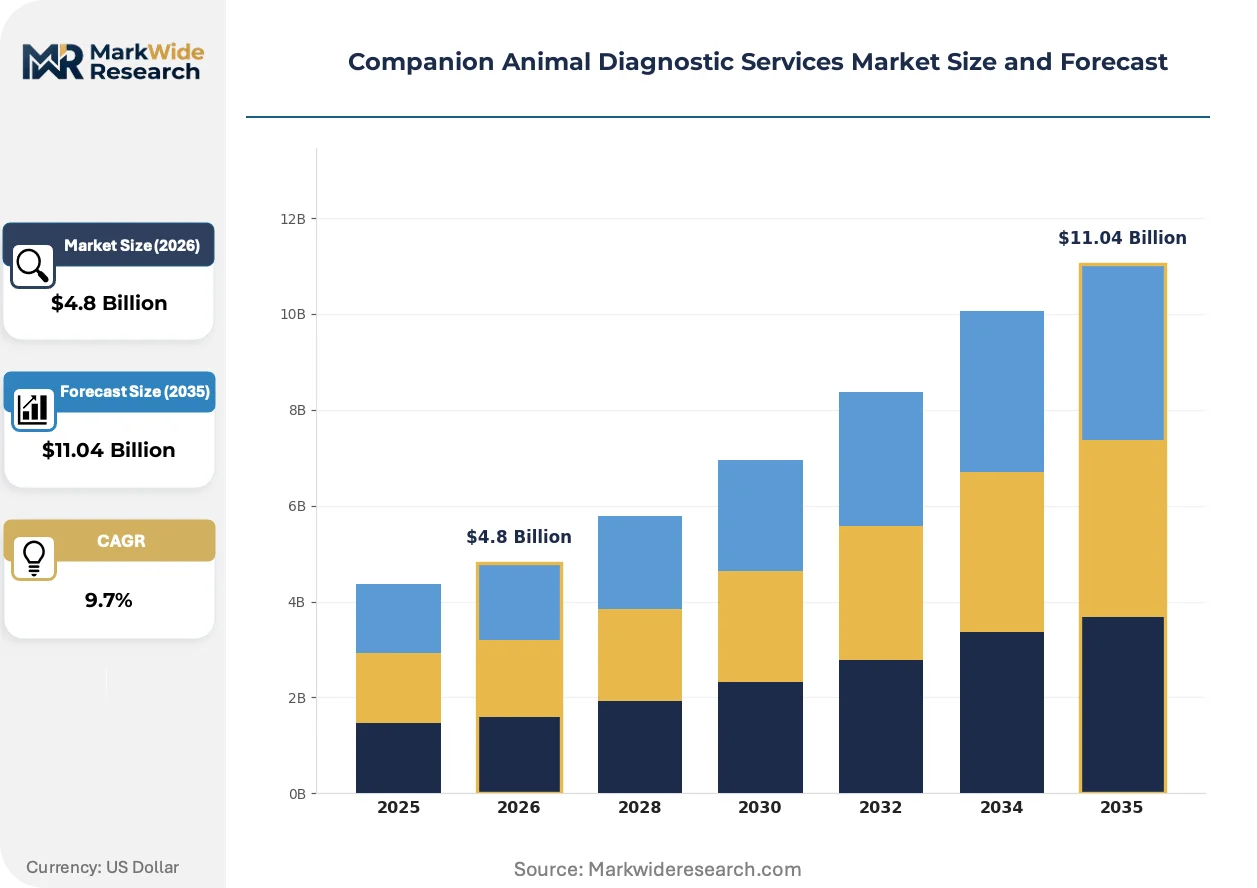
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Blood Tests, Imaging Services, Urinalysis, Fecal Tests Technology: Molecular Diagnostics, Immunoassays, Biochemical Analyzers, Point-of-Care Testing End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services Application: Infectious Diseases, Genetic Testing, Preventive Care, Oncology |
| Companies Covered | Thermo Fisher Scientific, Inc., Esaote SPA, IDEXX Laboratories, Inc., Virbac, Embark Veterinary, Inc., Zoetis, Neogen Corporation, FUJIFILM Corporation, Antech Diagnostics, Inc. (Mars Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Diagnostic Services Market Evolving Landscape
Diagnostic modality convergence and platform unification are compressing turnaround time expectations while elevating data interoperability requirements across veterinary practice networks.
Artificial intelligence-assisted image analysis is displacing radiologist-dependent interpretation workflows in companion animal imaging. Emergency and specialty hospitals deploy these tools for immediate trauma assessment and orthopedic screening. The technology is displacing overnight reference laboratory turnaround for preliminary diagnostic reads.
USDA APHIS infectious disease surveillance mandates are tightening sample chain-of-custody documentation requirements. Reference laboratories serving institutional contracts must upgrade laboratory information management systems. Molecular testing facilities face the steepest compliance burden due to nucleic acid traceability protocols.
Subscription-based diagnostic access models are fragmenting traditional per-test procurement in multi-site veterinary groups. Corporate consolidators negotiate enterprise pricing against point-of-care instrument placement. This shift concentrates most visibly in United States specialty hospital networks pursuing standardized care protocols.
Companion Animal Diagnostic Services Market Segmentation
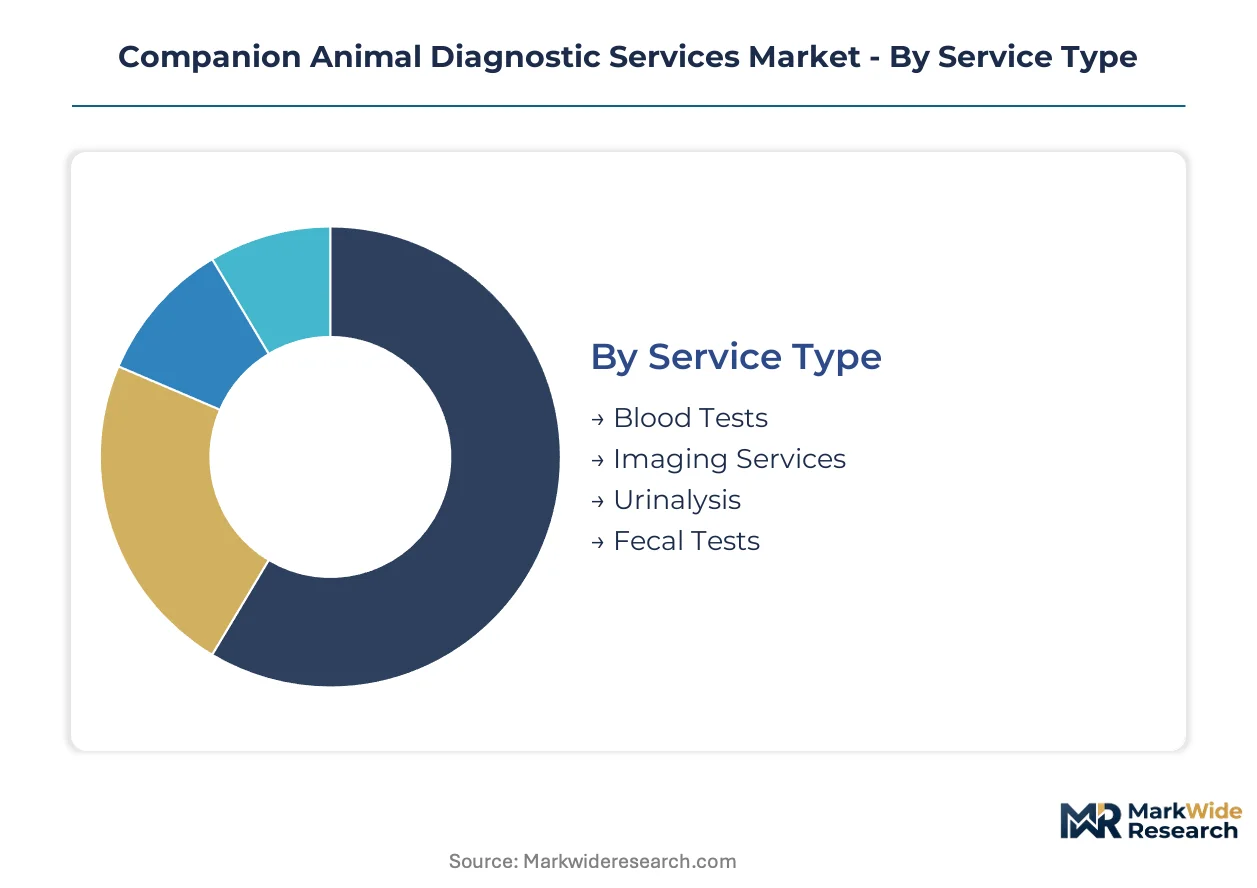
Diagnostic service segmentation in companion animal health reflects divergent regulatory pathways, capital requirements, and reimbursement structures. Each category channels procurement decisions toward either in-house infrastructure investment or outsourced reference laboratory relationships.
Service Type:
FDA Center for Veterinary Medicine assay validation requirements vary substantially across service modalities, with blood-based diagnostics facing the most stringent premarket review timelines.
- Blood Tests:Hematology and serum chemistry panels processed on automated analyzers require 200-500 microliter sample volumes. Veterinary clinics in Texas and California concentrate procurement around integrated platform ecosystems to minimize regulatory compliance overhead. These services generate recurring revenue through wellness screening protocols.
- Imaging Services:Radiography, ultrasonography, and computed tomography deliver immediate anatomical assessment without sample destruction. Specialty animal hospitals in the United States deploy artificial intelligence-assisted interpretation tools for trauma screening, displacing overnight reference laboratory turnaround expectations.
- Urinalysis:Sediment examination and biochemical dipstick analysis performed in-clinic or at reference laboratories.
- Fecal Tests:Parasitology screening and antigen detection for gastrointestinal pathogen identification.
Blood tests handle the majority of throughput; imaging services is the fastest mover on share.
Technology:
Cost tier differentiation separates premium molecular platforms from economy biochemical analyzers, with mid-tier immunoassays capturing volume in general practice settings.
- Molecular Diagnostics:Nucleic acid amplification and sequencing platforms detect pathogen DNA with analytical specificity exceeding culture-based methods. USDA APHIS surveillance programs in the United States create institutional demand for standardized PCR protocols. Specialized technician training requirements limit expansion in cost-constrained environments.
- Point-of-Care Testing:Cartridge-based and lateral flow devices deliver results within minutes at the veterinary examination table. Mobile veterinary services in suburban United States markets leverage these tools where brick-and-mortar laboratory access remains limited. Reduced sample handling expands service reach beyond traditional settings.
- Immunoassays:Antibody and antigen detection systems for endocrine and infectious disease screening.
- Biochemical Analyzers:Automated chemistry platforms for electrolyte, enzyme, and metabolite quantification.
Biochemical analyzers handle the majority of throughput; point-of-care testing is climbing the fastest on share.
End User:
Customer type determines procurement scale, with multi-site corporate groups negotiating enterprise pricing against single-clinic instrument placement decisions.
- Veterinary Clinics:General practice settings performing 60-70% of routine diagnostic volume in-house. State veterinary practice acts in New York, California, and Texas impose distinct personnel licensing requirements that fragment platform standardization. These facilities face mounting pressure to consolidate procurement around integrated ecosystems.
- Animal Hospitals:Emergency and specialty centers requiring 24-hour diagnostic turnaround for critical care decisions. United States metropolitan clusters concentrate the most advanced imaging and molecular capabilities. Corporate consolidators drive standardization across multi-site networks.
- Mobile Veterinary Services:Equipped vehicles serving rural and suburban geographies with point-of-care and sample collection capabilities.
- Research Institutions:Academic and pharmaceutical research facilities supporting drug development and disease mechanism studies.
Veterinary clinics handle the majority of throughput; mobile veterinary services is gaining share fastest.
Application:
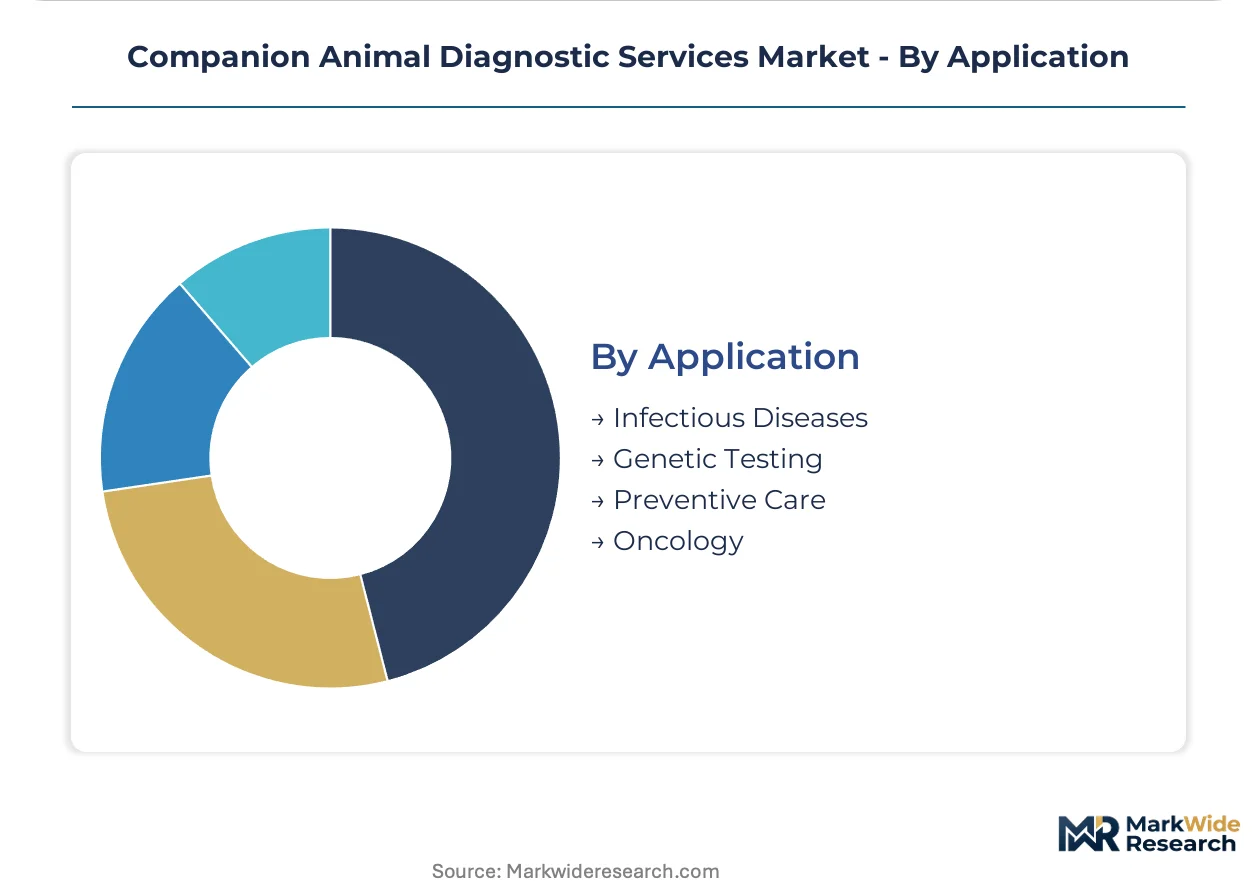
Maturity stage varies across application areas, with preventive care representing established volume and oncology diagnostics emerging as a premium growth segment.
- Preventive Care:Wellness screening and early disease detection protocols embedded in annual examination workflows. United States pet humanization trends elevate spending on baseline health monitoring. These services establish recurring client relationships and drive downstream therapeutic revenue.
- Oncology:Tumor marker detection, histopathology, and molecular profiling for therapeutic selection. Specialty animal hospitals in the United States deploy immunohistochemistry and flow cytometry for lymphoma classification. Premium pricing reflects pathologist expertise and extended turnaround times.
- Infectious Diseases:Pathogen identification for zoonotic risk assessment and treatment guidance.
- Genetic Testing:Breed identification and inherited disease screening for breeding program decisions.
Preventive care handles the majority of throughput; oncology is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for molecular diagnostics with minimal resistance, while Indian and Brazilian markets prioritize cost-efficient point-of-care alternatives. European purchasers occupy a middle tier, trading off assay sophistication against consolidated procurement budgets.
United States
Specialty and emergency animal hospital networks drive the steepest diagnostic spending growth worldwide. FDA Center for Veterinary Medicine oversight of assay validation creates institutional demand for compliant testing infrastructure. Metropolitan clusters in California, Texas, and New York concentrate the most advanced imaging and molecular capabilities.
Germany
Corporate veterinary consolidators negotiate enterprise pricing across multi-site networks with increasing sophistication. EMA-aligned regulatory frameworks for veterinary medicinal products extend to diagnostic quality standards. The Munich-Stuttgart corridor hosts the densest concentration of reference laboratory automation engineering.
United Kingdom
Pet insurance penetration exceeding forty percent elevates willingness-to-pay for preventive screening protocols. The Veterinary Medicines Directorate maintains post-Brexit alignment with EU diagnostic device classification. London and Southeast England concentrate specialty referral hospital capacity.
Japan
Aging pet demographics elevate chronic disease monitoring frequency among small-breed dog owners. METI industrial policy supports domestic diagnostic instrument manufacturing scale. The Tokyo-Osaka corridor dominates both veterinary specialist density and point-of-care device distribution.
Brazil
Rapid veterinary clinic formalization in São Paulo and Rio de Janeiro expands addressable market for standardized testing. ANVISA veterinary product regulation creates compliance barriers that favor established reference laboratory networks. Mobile veterinary services penetrate underserved suburban geographies with cartridge-based diagnostics.
Companion Animal Diagnostic Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in companion animal diagnostics. The upper tier commands channel control through bundled practice management and diagnostic platform ecosystems. Mid-tier players occupy positions in reagent supply, imaging hardware, or genetic testing specialization. Competitive moves concentrate on reference laboratory network expansion and point-of-care instrument placement contracts.
Within the integrated diagnostics tier, IDEXX Laboratories and Zoetis exemplify platform ecosystem strategies that consolidate veterinary clinic procurement. Thermo Fisher Scientific occupies a distinct position as a manufacturing-scale supplier serving multiple veterinary diagnostic brands. These three entities represent divergent archetypes: channel-integrated service providers, pharmaceutical-diagnostic bundlers, and life sciences infrastructure suppliers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Esaote SPA |
| IDEXX Laboratories, Inc. |
| Virbac |
| Embark Veterinary, Inc. |
| Zoetis |
| Neogen Corporation |
| FUJIFILM Corporation |
| Antech Diagnostics, Inc. (Mars Inc.) |
| Others |
Value Network & Pricing Analysis
FDA Center for Veterinary Medicine assay validation requirements gate both supplier qualification and price differentiation in companion animal diagnostics, creating tiered market access where validated manufacturers command premium positioning against unvalidated alternatives.
Pricing Analysis
After-sales revenue from reagent contracts and extended service agreements drives lifetime value more than instrument placement. Three-tier pricing structure across premium molecular platforms, standard immunoassay systems, and economy biochemical analyzers segments buyers by capability requirements. Pricing pressure stems from corporate veterinary consolidators negotiating enterprise pricing against per-test procurement. Mobile veterinary services exhibit highest price sensitivity due to capital constraints, while specialty animal hospitals absorb premium molecular pricing with minimal resistance.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled reagent shipments from European and Asian manufacturing hubs concentrate supply risk around container availability and cold-chain integrity. The supply chain draws from life sciences manufacturing clusters in Germany, the United States, and Japan for precision optical components and nucleic acid extraction chemistries. Single-source vulnerability concentrates in specialized microfluidic cartridge production. Distribution runs through integrated platform ecosystems controlled by dominant channel partners rather than open procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine-enabled remote diagnostic consultation represents a direct substitute threat to traditional reference laboratory revenue streams that incumbents must neutralize through platform integration.
For Market Incumbents: Shield reference laboratory relationships by embedding AI-assisted interpretation tools that compress turnaround times below remote consultation viability. Deepen backward integration into nucleic acid extraction chemistry production to reduce Thermo Fisher Scientific dependency. Channel control through practice management software integration remains the critical defensive lever against platform unification threats. For New Entrants and Emerging Players: Differentiate on mobile veterinary service enablement with cartridge-based diagnostics designed for vehicle-mounted deployment. Target suburban United States geographies where brick-and-mortar specialist access remains limited. A direct-to-clinic reagent subscription model bypasses entrenched platform ecosystem barriers. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine assay validation pathway acceleration reshapes the acquisition landscape toward pre-validated molecular testing assets. Five-to-ten-year viability favors reference laboratories with USDA APHIS surveillance program contracts securing recurring institutional revenue. The signal to watch is state veterinary practice act telemedicine amendments that would validate remote diagnostic business models.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Platform Integration | IDEXX Laboratories' ecosystem strategy demonstrates channel lock-in through combined instrument and software deployment. |
| Reference Laboratory Network Expansion | Antech Diagnostics leverages Mars Inc. corporate veterinary relationships to secure multi-site enterprise contracts. |
| AI-Assisted Imaging Development | FUJIFILM Corporation and Esaote SPA compete on algorithm accuracy for emergency trauma screening applications. |
| Molecular Diagnostics Certification | FDA Center for Veterinary Medicine validation accelerates commercialization timelines for PCR-based pathogen detection. |
| Mobile Service Equipment Partnership | Neogen Corporation cartridge distribution targets equipped vehicle operators in underserved suburban markets. |
Research Methodology
Desk research of FDA 510(k) veterinary device filings, USDA APHIS surveillance program procurement records, and state veterinary practice act amendments preceded structured interviews with diagnostic platform product managers, reference laboratory operations directors, and corporate veterinary group procurement officers. Secondary validation drew from SEC 10-K instrument revenue disclosures, trade customs data for diagnostic reagent imports, and veterinary hospital construction permit databases. Bottom-up clinic instrument placement estimates triangulated against top-down manufacturer reported segment revenues.
Variance decomposition across service type, technology tier, end-user channel, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included diagnostic modality, platform integration level, and practice size category. CAGRs derived from logistic diffusion curves fitted to historical instrument placement saturation patterns, with nucleic acid testing volume trajectories and point-of-care cartridge consumption rates as veterinary-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued pet humanization spending trajectories and stable FDA Center for Veterinary Medicine regulatory timelines; material deviation in telemedicine reimbursement policy or reagent supply concentration would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Microdialysis Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
GCC in-Vitro Diagnostics Market