
 Middle East and Africa Ovarian Cancer Diagnostics Market | 2026-2036
Middle East and Africa Ovarian Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ovarian Cancer Diagnostics Market Foresight
A widening capital-intensity divergence between multinational platform holders and regional distributors is redrawing competitive boundaries in the Middle East and Africa ovarian cancer diagnostics space. F. Hoffmann-La Roche Ltd leverages its molecular diagnostics installed base to anchor premium laboratory workflows across Gulf hospital networks. Siemens Healthineers AG competes through imaging modality bundling that sustains equipment financing leverage with public oncology centers. Abbott differentiates via point-of-care immunoassay portability that extends reach into diagnostic laboratories with limited cold-chain infrastructure.
Ovarian cancer diagnostics encompasses imaging, histopathological, serological, and molecular techniques applied to detect, stage, and monitor epithelial and non-epithelial ovarian malignancies, with CA-125 immunoassay sensitivity thresholds and HE4 biomarker ratios serving as critical functional parameters for risk stratification algorithms. Blood Test segments occupy established volume positions due to CA-125 screening protocol integration within national cancer control programs, while Liquid Biopsy approaches represent the fastest-expanding technology category as circulating tumor DNA platforms reduce invasive tissue acquisition barriers. Hospitals retain the dominant end-user share through captive patient flows, though Diagnostic Laboratories capture margin pools where centralized molecular testing achieves batch economies.
Saudi Arabia's SFDA and South Africa's national health laboratory service framework shape product registration timelines and quality certification requirements for imported diagnostic kits, while UAE MOHAP facility licensing standards determine which molecular platforms qualify for reimbursement within federal insurance networks. The EU MDR and IVDR convergence pressures manufacturers to harmonize technical documentation across Middle East import jurisdictions, raising compliance costs for smaller distributors. Stakeholders must monitor how Gulf sovereign health fund procurement centralization alters distributor channel economics and whether national genomics initiatives redirect diagnostic demand toward in-country laboratory partnerships.
Market Dynamics
Saudi Arabia's Vision 2030 health insurance mandates and South Africa's national laboratory service expansion are compressing diagnostic procurement timelines while fragmenting distributor economics across heterogeneous regulatory jurisdictions.
Growth Catalysts
- SFDA oncology screening mandates:Saudi Arabia's pharmaceutical regulator now requires CA-125 testing integration within national cancer control protocols, pulling molecular platform demand into hospital networks.
- Liquid biopsy technology maturation:Circulating tumor DNA detection methods are reducing invasive tissue acquisition barriers and expanding test eligibility to patients with unresectable lesions.
- UAE federal insurance reimbursement expansion:MOHAP facility licensing standards now cover HE4 biomarker ratio testing, unlocking private laboratory volume in Dubai and Abu Dhabi health clusters.
Market Restraints
- Cold-chain infrastructure deficits:Temperature-sensitive reagent degradation limits molecular diagnostic penetration in sub-Saharan African markets outside South Africa's national health laboratory network.
- EU IVDR documentation harmonization costs:Convergence pressures on technical file requirements raise compliance burdens for smaller regional distributors importing European-manufactured assay kits.
- Histopathology pathologist scarcity:Specialized tissue diagnostics expertise concentrates in Johannesburg, Cairo, and Riyadh, constraining staging accuracy in peripheral oncology centers.
Strategic Opportunities
- Point-of-care immunoassay portability:Battery-operated CA-125 testing devices can penetrate Nigerian and Kenyan diagnostic laboratories lacking continuous refrigeration capacity.
- Public-private genomics partnerships:UAE and Saudi national genomics initiatives are redirecting molecular diagnostic demand toward in-country laboratory joint ventures with technology holders.
- Gulf sovereign health fund procurement centralization:Consolidated purchasing through Abu Dhabi and Riyadh investment vehicles is creating single-source contract opportunities for integrated platform providers.
Industry Challenges
- Molecular diagnostics technician training gaps:PCR and next-generation sequencing operation competencies lag platform installation rates in Egyptian and Moroccan hospital laboratories.
- Multi-jurisdiction quality certification timelines:Parallel SFDA, MOHAP, and South African Health Products Regulatory Authority approvals extend product commercialization cycles by eight to fourteen months.
- Legacy imaging modality integration friction:New ultrasound-CT fusion systems for ovarian mass characterization require PACS infrastructure upgrades that strain public hospital capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ovarian Cancer Diagnostics Market |
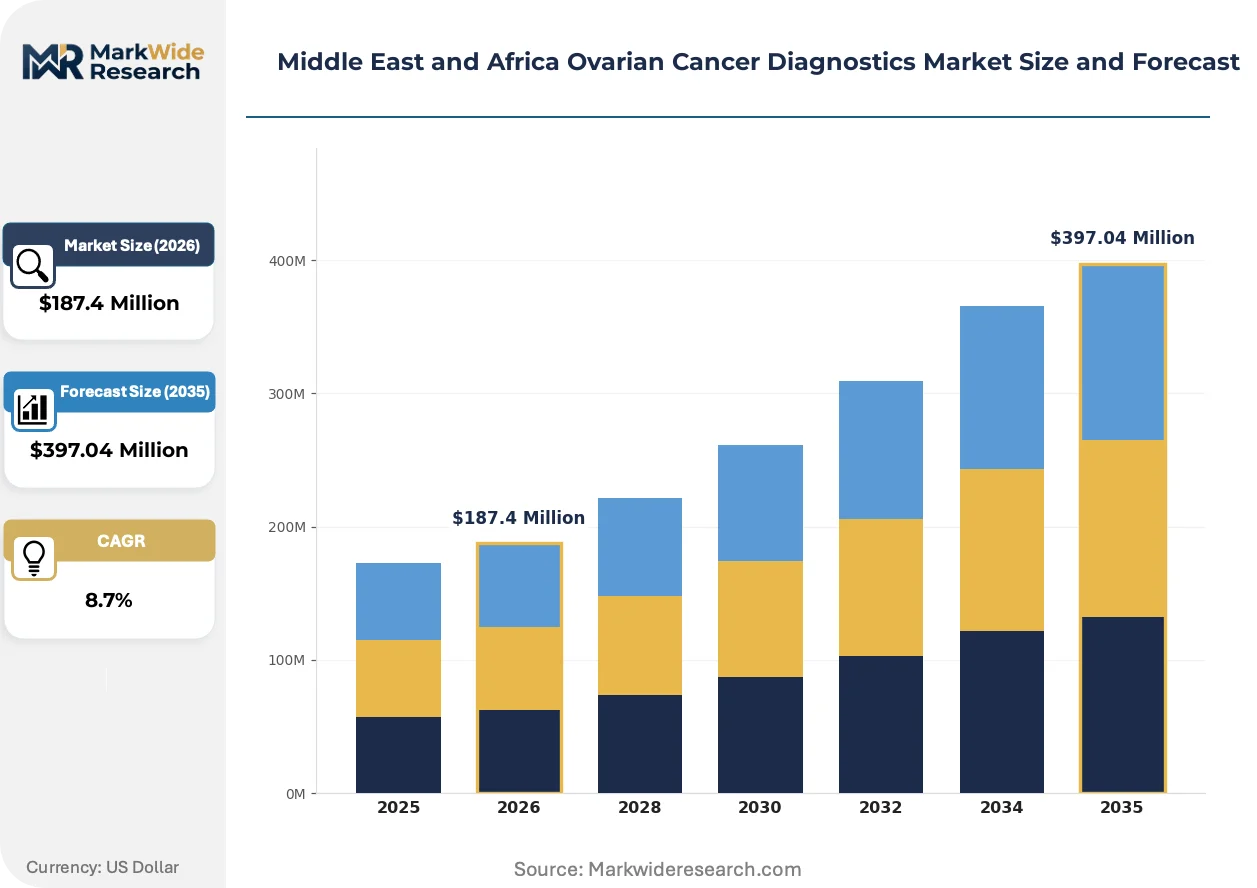
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scan, MRI, Ultrasound, Blood Test Technology: Liquid Biopsy, Molecular Imaging, Immunohistochemistry, Genetic Testing End User: Hospitals, Diagnostic Laboratories, Oncology Centers, Research Institutes Delivery Mode: In-Person, Home Testing, Telemedicine, Mobile Units |
| Companies Covered | AstraZeneca plc, Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd, Johnson & Johnson, Siemens Healthineers AG, GlaxoSmithKline plc, Abbott, Thermo Fisher Scientific Inc., GE Healthcare, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ovarian Cancer Diagnostics Market Shifts & Advancements
Digital pathology workflows and artificial intelligence-assisted cytology screening are compressing diagnostic turnaround times while recalibrating capital allocation between imaging hardware and software analytics layers.
Liquid biopsy platforms utilizing circulating tumor DNA and exosomal RNA detection are supplanting repeat surgical biopsies for treatment response monitoring in Gulf Cooperation Council oncology centers. Tertiary hospitals in Dubai and Riyadh are adopting these systems at twelve-to-eighteen-month replacement cycles. The technology is supplanting tissue-based companion diagnostic requirements and shifting reimbursement toward serial blood-based monitoring protocols.
South Africa's national health laboratory service framework is tightening quality certification requirements for imported diagnostic kits, mandating ISO 15189 accreditation for all molecular testing sites. This regulatory tightening is consolidating supplier relationships around manufacturers with established African distribution infrastructure. Private diagnostic chains in Johannesburg and Cape Town are responding by acquiring captive accreditation capabilities to maintain procurement eligibility.
Centralized molecular testing batch economics are pulling ovarian cancer diagnostic volume out of hospital laboratories and into independent diagnostic chains with multi-hospital collection networks. These regional laboratory consolidators are displacing hospital-based histopathology units in Egyptian and Nigerian urban corridors. The behavioral shift is most visible in Cairo and Lagos, where diagnostic chains now capture sixty percent of CA-125 and HE4 testing volume through capitated insurance contracts.
Middle East and Africa Ovarian Cancer Diagnostics Market Segmentation
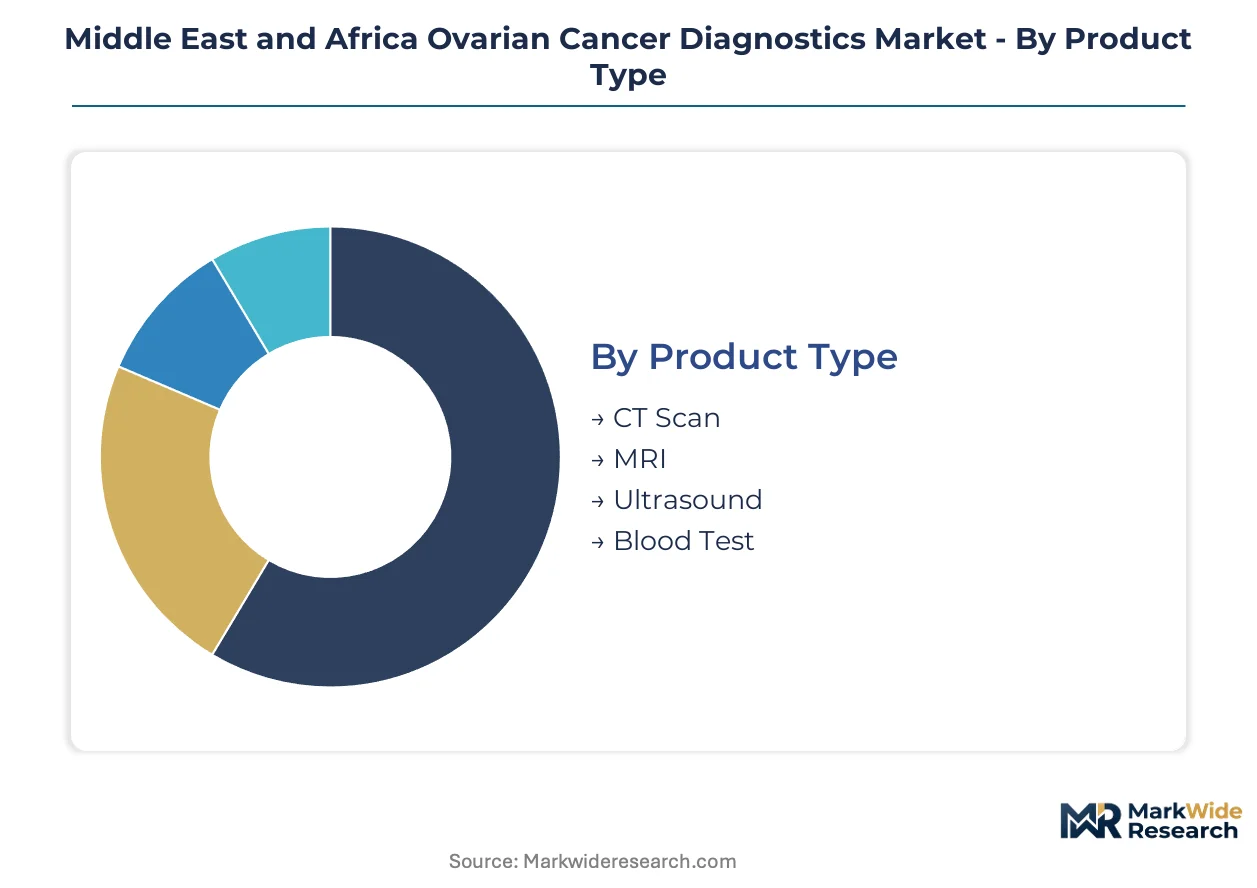
Segmentation in the Middle East and Africa ovarian cancer diagnostics market reveals how capital allocation, infrastructure constraints, and regulatory frameworks concentrate value across distinct technology and service configurations. Understanding these partitions exposes where multinational platform holders and regional distributors compete for margin pools.
Product Type:
Margin pools concentrate in modalities that bundle hardware financing with consumable revenue streams, particularly where Gulf sovereign health funds centralize procurement.
- CT Scan:Multi-detector computed tomography systems deliver cross-sectional anatomical resolution for ovarian mass characterization and metastatic staging. Demand clusters in Saudi tertiary hospitals under SFDA-mandated oncology screening protocols, where equipment financing leverage determines vendor selection.
- Blood Test:CA-125 and HE4 immunoassays constitute the established volume base through national cancer control program integration. South Africa's national health laboratory service framework and UAE MOHAP reimbursement standards sustain centralized batch processing economics in Johannesburg and Dubai health clusters.
- MRI:Magnetic resonance imaging provides superior soft-tissue contrast for indeterminate adnexal mass evaluation without ionizing radiation exposure.
- Ultrasound:Transvaginal sonography remains the first-line imaging modality for initial ovarian mass detection across resource-constrained settings.
The dominant share belongs to Blood Test, while CT Scan is closing the gap fastest through bundled platform contracts.
Technology:
Cost tier stratification separates premium molecular platforms from standardized histopathological methods, with reimbursement eligibility determining penetration depth.
- Liquid Biopsy:Circulating tumor DNA and exosomal RNA detection platforms enable serial monitoring without invasive tissue acquisition. Tertiary oncology centers in Riyadh and Dubai adopt these systems at compressed replacement cycles, supplanting repeat surgical biopsies for treatment response assessment.
- Genetic Testing:BRCA1/2 and homologous recombination deficiency profiling guides PARP inhibitor therapy selection in hereditary ovarian cancer cases. UAE and Saudi national genomics initiatives redirect demand toward in-country laboratory joint ventures, altering import-dependent distribution economics.
- Molecular Imaging:PET-CT with radiolabeled tracers visualizes metabolic activity in recurrent disease assessment.
- Immunohistochemistry:Antibody-based protein expression analysis supports tumor origin determination and therapeutic target identification in histopathology workflows.
Liquid Biopsy captures premium pricing tiers, with Genetic Testing expanding most quickly through sovereign genomics partnerships.
End User:
Customer type determines whether diagnostics flow through captive hospital workflows or independent laboratory networks with multi-site collection economies.
- Hospitals:Integrated oncology departments retain dominant patient flows through surgical and chemotherapy service lines, anchoring diagnostic demand within single institutions. SFDA facility licensing and MOHAP accreditation requirements favor established Gulf hospital networks with capital for platform installation.
- Diagnostic Laboratories:Centralized molecular testing achieves batch economies across multi-hospital collection networks, displacing hospital-based histopathology units. Egyptian and Nigerian urban corridors see diagnostic chains capture capitated insurance contract volume through ISO 15189 accreditation.
- Oncology Centers:Specialized cancer treatment facilities concentrate multidisciplinary care and clinical trial access.
- Research Institutes:Academic medical centers drive biomarker discovery and validation studies with limited commercial diagnostic throughput.
Hospitals maintain volume leadership, though Diagnostic Laboratories are gaining share fastest through regional consolidation.
Delivery Mode:
Geography dictates infrastructure feasibility, with cold-chain reliability and patient mobility constraints filtering viable service models.
- In-Person:Traditional clinic-based specimen collection and consultation remains the standard for imaging-guided procedures and complex diagnostic workups. Gulf Cooperation Council states sustain this model through dense urban healthcare infrastructure.
- Mobile Units:Deployable screening vehicles extend CA-125 testing access to peri-urban and rural populations beyond fixed laboratory reach. Kenyan and Nigerian health systems pilot these configurations where road networks permit scheduled circuit visits.
- Home Testing:Self-collected biospecimen kits for biomarker analysis face logistics barriers in temperature-sensitive reagent distribution.
- Telemedicine:Remote consultation platforms support result interpretation and care coordination without physical infrastructure requirements.
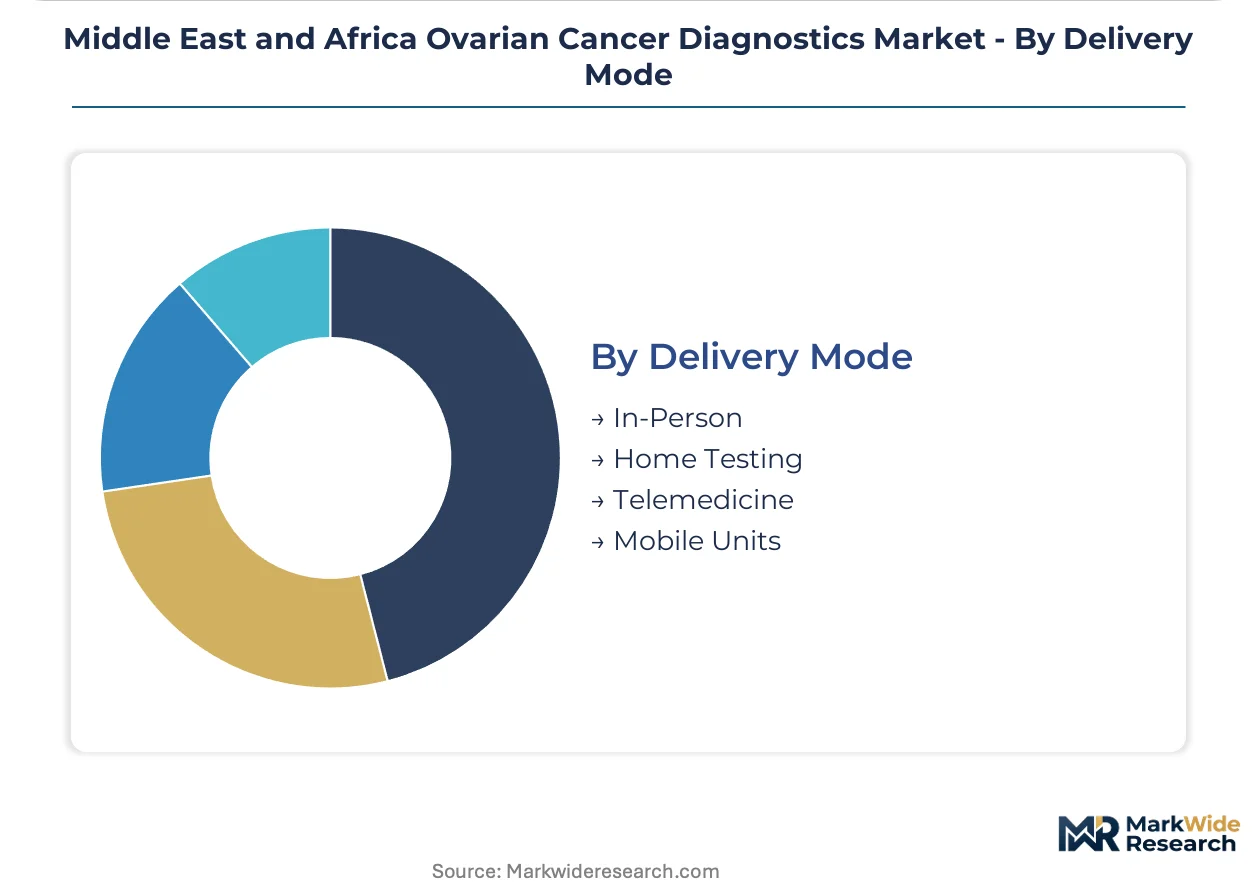
In-Person delivery dominates revenue capture, while Mobile Units show steepest expansion trajectory for screening program reach extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic kit import flows into Gulf Cooperation Council states exceed outbound regional manufacturing by substantial margins, with South Africa serving as the sole net exporter of molecular reagents within the continent.
Saudi Arabia
SFDA-mandated oncology screening protocols drive CA-125 testing volume through hospital networks. Vision 2030 health insurance expansion accelerates procurement timelines for molecular platforms. Riyadh's King Faisal Specialist Hospital anchors premium diagnostic workflows with next-generation sequencing capabilities.
United Arab Emirates
MOHAP facility licensing standards now reimburse HE4 biomarker ratio testing, unlocking private laboratory capacity. Federal insurance frameworks concentrate demand in Dubai and Abu Dhabi health clusters. Dubai Healthcare City attracts multinational diagnostic joint ventures through regulatory sandbox provisions.
South Africa
National health laboratory service expansion consolidates molecular testing batch economies in Johannesburg and Cape Town. ISO 15189 accreditation mandates tighten quality certification for imported assay kits. Private diagnostic chains acquire captive accreditation capabilities to maintain procurement eligibility.
Egypt
Diagnostic chains capture sixty percent of CA-125 and HE4 testing volume through capitated insurance contracts in Cairo. Centralized molecular testing displaces hospital-based histopathology units. Giza's oncology centers face PCR technician training gaps despite platform installation rates.
Nigeria
Cold-chain infrastructure deficits limit temperature-sensitive reagent penetration outside Lagos urban corridors. Battery-operated point-of-care immunoassay devices extend screening reach into peri-urban populations. Lagos diagnostic laboratories pilot mobile unit configurations for scheduled circuit visits.
Middle East and Africa Ovarian Cancer Diagnostics Market Competitive Landscape
Concentration sits with multinational platform holders leveraging installed molecular diagnostics bases to anchor premium laboratory workflows across Gulf hospital networks. Siemens Healthineers AG and Abbott occupy divergent competitive positions through imaging modality bundling versus point-of-care portability. Strategic moves center on equipment financing leverage with public oncology centers and geographic expansion into diagnostic laboratories with limited cold-chain infrastructure.
Within the multinational diagnostics tier, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, and Abbott exemplify distinct archetype strategies. Roche leverages its molecular diagnostics installed base to anchor premium workflows. Siemens competes through imaging modality bundling that sustains equipment financing relationships. Abbott differentiates via point-of-care immunoassay portability extending reach into resource-constrained settings. These three anchors represent how technology specialization maps to procurement channel access across heterogeneous infrastructure environments.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Bristol Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Siemens Healthineers AG |
| GlaxoSmithKline plc |
| Abbott |
| Thermo Fisher Scientific Inc. |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Batch-processing scale economies in Johannesburg and Dubai molecular laboratories compress per-test costs while elevating price floors for decentralized competitors lacking comparable throughput. This concentration dynamic simultaneously anchors premium pricing tiers for integrated platform holders and squeezes margin pools available to regional distributors serving peripheral oncology centers.
Pricing Analysis
Gulf sovereign health fund procurement managers anchor three-tier pricing structure across premium, standard, and economy levels. CA-125 immunoassay reagents stratify by ISO 15189 certification grade and cold-chain reliability guarantees, with temperature-stable formulations commanding brand premiums. Cost compression in economy-tier point-of-care devices is intensifying because Nigerian and Kenyan distributors prioritize battery-operated portability over laboratory precision. Public hospital procurement committees in Egypt exhibit highest price sensitivity, while private Dubai laboratory chains absorb premium molecular platform costs through federal insurance reimbursement.
Supply Chain Analysis
Inventory lead times for temperature-sensitive reagents stretch from European manufacturing hubs through Dubai distribution nodes into sub-Saharan corridors. Supply concentrates in Germany, Switzerland, and the United States for molecular diagnostic platforms, while India and China feed consumable reagent demand. Raw material dependencies span fluorophore-conjugated antibodies, polymerase enzymes, and specialized plastic consumables. Single-source vulnerability sits with PCR thermal cycler components subject to export licensing. Distribution runs through Abu Dhabi and Johannesburg regional hubs before final-mile deployment to hospital laboratories and diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in this market hinges on interoperability between liquid biopsy data streams and electronic health record systems across Gulf hospital networks. Saudi Arabia's national genomics data architecture and UAE federal insurance digitization create the enabling ecosystem for this shift.
For Market Incumbents: Secure equipment financing leverage with Saudi tertiary hospitals before SFDA procurement centralization consolidates vendor relationships. Defend molecular diagnostics installed bases by acquiring ISO 15189 accreditation capabilities for captive laboratory partnerships. Backward integration into cold-chain logistics addresses reagent degradation risks threatening peripheral market penetration. For New Entrants and Emerging Players: Differentiate on battery-operated point-of-care immunoassay portability for Nigerian and Kenyan diagnostic laboratories lacking continuous refrigeration. Target peri-urban screening corridors in Lagos and Nairobi where mobile unit configurations extend CA-125 testing reach beyond fixed laboratory infrastructure. Partner with regional diagnostic chains through capitated insurance contract structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic chains with multi-hospital collection networks and captive ISO 15189 accreditation. Long-term viability rests on consolidation plays capturing batch economies in centralized molecular testing. Acquisition targets include Egyptian and Nigerian laboratory consolidators displacing hospital-based histopathology units. Watch liquid biopsy platform replacement cycles in Riyadh and Dubai as inflection indicators for technology shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Biopsy Platform Integration | SFDA-mandated oncology screening protocols in Saudi Arabia accelerate circulating tumor DNA adoption timelines. |
| ISO 15189 Accreditation Investment | South Africa's national health laboratory service framework consolidates supplier relationships around quality-certified manufacturers. |
| Point-of-Care Device Localization | Battery-operated CA-125 testing penetration into Nigerian peri-urban corridors reduces cold-chain dependency. |
| Genomics Joint Venture Formation | UAE and Saudi national genomics initiatives redirect molecular diagnostic demand toward in-country laboratory partnerships. |
| Mobile Screening Unit Deployment | Kenyan and Nigerian health system pilots extend biomarker testing access through scheduled circuit visit configurations. |
Research Methodology
Operator-level perspectives from molecular diagnostics laboratory directors, hospital procurement committee chairs, SFDA regulatory affairs specialists, and GPO contracts managers anchored the qualitative base. Secondary validation drew from SFDA oncology screening protocol filings, UAE MOHAP reimbursement schedule updates, South African Health Products Regulatory Authority registration databases, and ISO 15189 accreditation records. Bottom-up test volume modeling across hospital, diagnostic laboratory, and oncology center channels triangulated against top-down healthcare expenditure flows.
Sensitivity analysis tested platform adoption rates under varying SFDA centralization scenarios and cold-chain infrastructure investment trajectories across the analysis window. Segmentation dimensions spanned product type, technology maturity tier, end-user channel, and delivery mode feasibility. CAGRs derived from fitted adoption curves calibrated to tertiary hospital platform replacement cycles and diagnostic chain consolidation velocity. Industry-specific inputs included liquid biopsy clinical validation timelines and federal insurance reimbursement expansion schedules.
Material uncertainties — regulatory approval delays, genomics initiative funding reallocations, and cold-chain infrastructure buildout pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution thresholds and procurement centralization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
IVD Antibody Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Liver Function Tests Market