
 Immunoassay Interference Blocker Market | 2026-2036
Immunoassay Interference Blocker Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoassay Interference Blocker Market Intelligence
Consolidation among hospital laboratory networks and large diagnostic service chains is repositioning procurement power toward fewer buyers with larger contract volumes. Roche Diagnostics GmbH leverages its installed base of analyzers to bundle blocker reagents into long-term supply agreements. Thermo Fisher Scientific sustains broad catalog breadth across monoclonal and recombinant protein formats. Scantibodies Laboratory anchors its position through specialized manufacturing of heterophilic antibody blockers for niche assay developers.
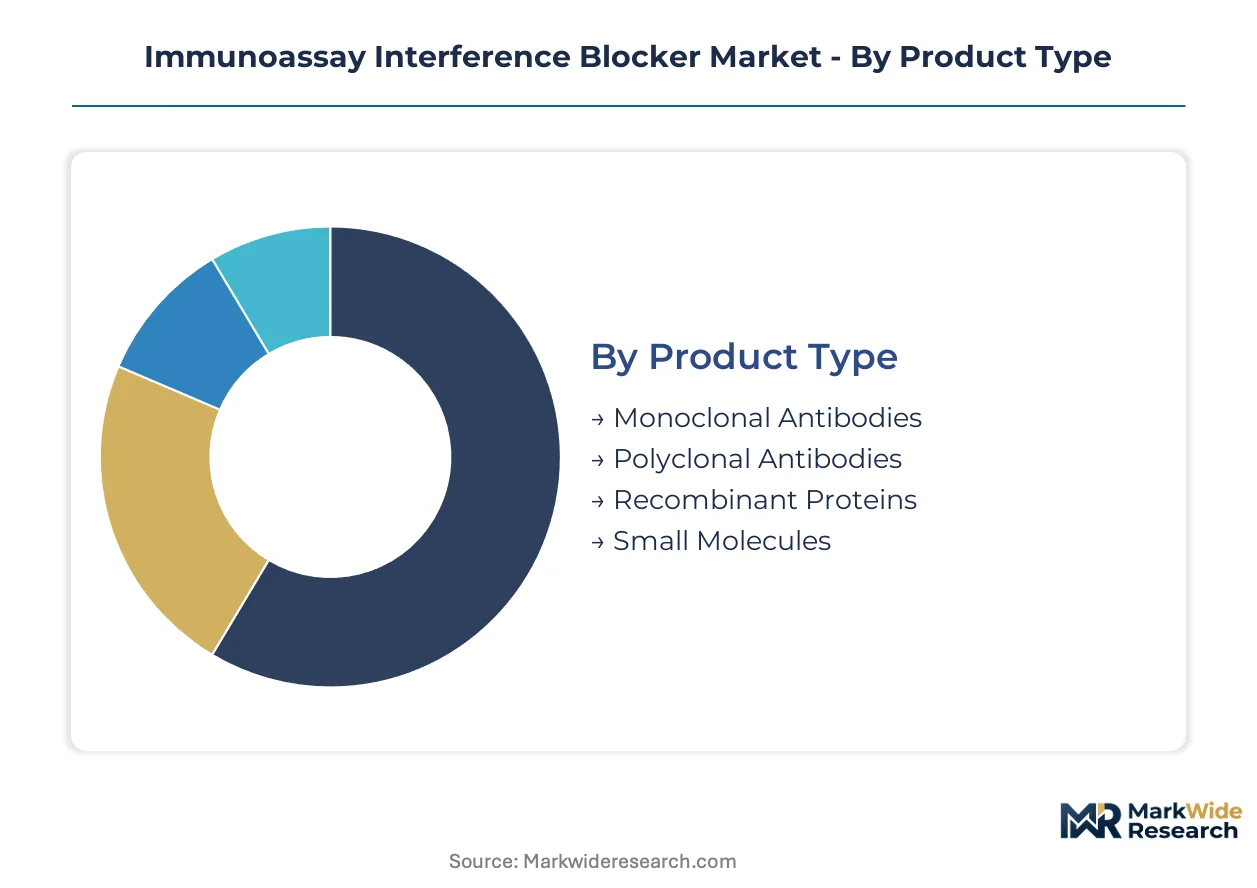
Immunoassay interference blockers comprise formulated reagents—typically immunoglobulin fragments, receptor proteins, or synthetic inhibitors—that neutralize endogenous interfering substances such as heterophilic antibodies, rheumatoid factor, and complement proteins during ligand-binding assays. These blockers function by competitive binding or steric hindrance to preserve analyte-specific signal integrity in sandwich and competitive immunoassay architectures. Monoclonal antibodies command the largest product-type revenue pool due to batch-to-batch consistency and defined epitope specificity, while recombinant proteins represent the fastest-expanding category as manufacturers seek animal-origin-free alternatives to mitigate regulatory scrutiny. Among applications, clinical diagnostics absorbs the majority of blocker volume, though research laboratories exhibit higher per-unit pricing tolerance for customized formulations.
FDA quality-system regulations and CLSI analytical performance guidelines shape validation protocols for new blocker introductions in the United States, while IVDR requirements in Europe extend conformity assessment burdens for reagent suppliers. The EPA and ISO 15189 standards further influence environmental testing and laboratory accreditation pathways that incorporate interference mitigation. Stakeholders must monitor evolving regulatory divergence between FDA and EMA post-market surveillance expectations when prioritizing regional product registration investments.
Market Dynamics
Centralized laboratory networks in the United States are consolidating procurement authority into fewer purchasing entities with larger contract volumes, fundamentally altering how interference blocker suppliers compete for shelf space and pricing leverage.
Growth Catalysts
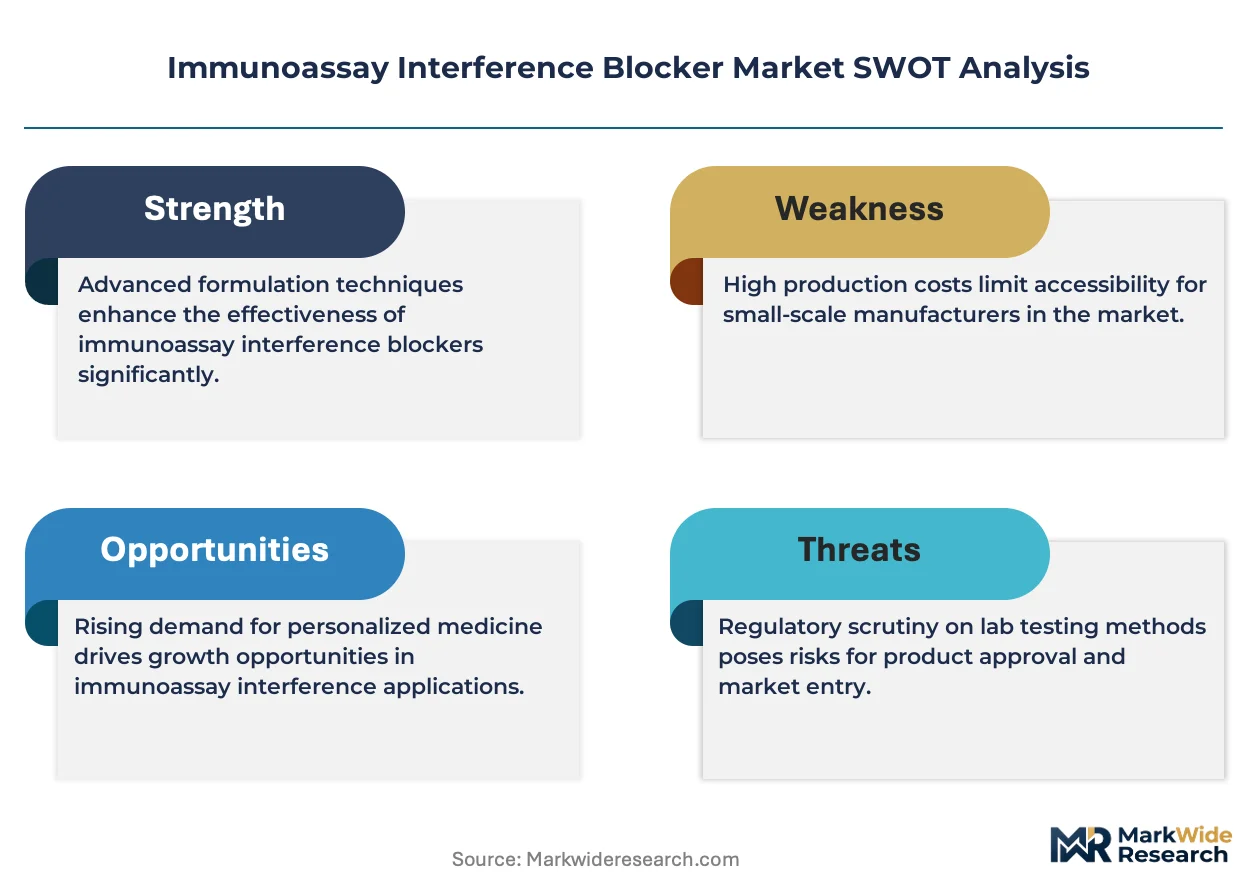
- IVDR Conformity Assessment:The European Union's In Vitro Diagnostic Regulation mandates enhanced performance documentation for reagent suppliers, creating structured demand for validated blocker formulations that meet elevated analytical standards.
- Hospital Laboratory Consolidation:Integrated delivery networks and multi-site health systems are standardizing reagent procurement across affiliated laboratories, driving volume commitments for interference mitigation products.
- Complement Protein Neutralization:Advances in synthetic inhibitor chemistry are expanding blocker efficacy against complement-mediated interference, opening assay design flexibility for autoimmune and infectious disease panels.
Market Restraints
- Serum-Derived Immunoglobulin Cost Volatility:Raw material sourcing from bovine and murine serum exposes manufacturers to agricultural commodity price swings and biosecurity-related supply interruptions.
- Single-Source Recombinant Protein Supply:Contract manufacturing organizations in Switzerland and Germany control critical capacity for animal-origin-free protein production, concentrating supplier risk.
- Heterophilic Antibody Specificity Limitations:Persistent assay failures from patient-specific antibody profiles that evade standard blocking formulations constrain universal product claims.
Strategic Opportunities
- Point-of-Care Device Integration:Miniaturized immunoassay platforms for emergency departments and physician offices lack embedded interference mitigation, creating demand for lyophilized blocker formats.
- Research-Use-Only Custom Formulations:Academic core facilities and biotechnology discovery groups tolerate extended lead times and premium pricing for project-specific blocking cocktails.
- ISO 15189 Laboratory Accreditation:Quality management mandates in diagnostic laboratories across Australia and South Korea are formalizing interference control as an auditable competency, embedding blocker procurement into compliance budgets.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Purification and formulation expertise for immunoglobulin-derived reagents concentrates in established biotechnology hubs, constraining manufacturing scale-up.
- Legacy Analyzer Compatibility Certification:Validating blocker performance across multiple instrument generations from dominant analyzer manufacturers extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoassay Interference Blocker Market |
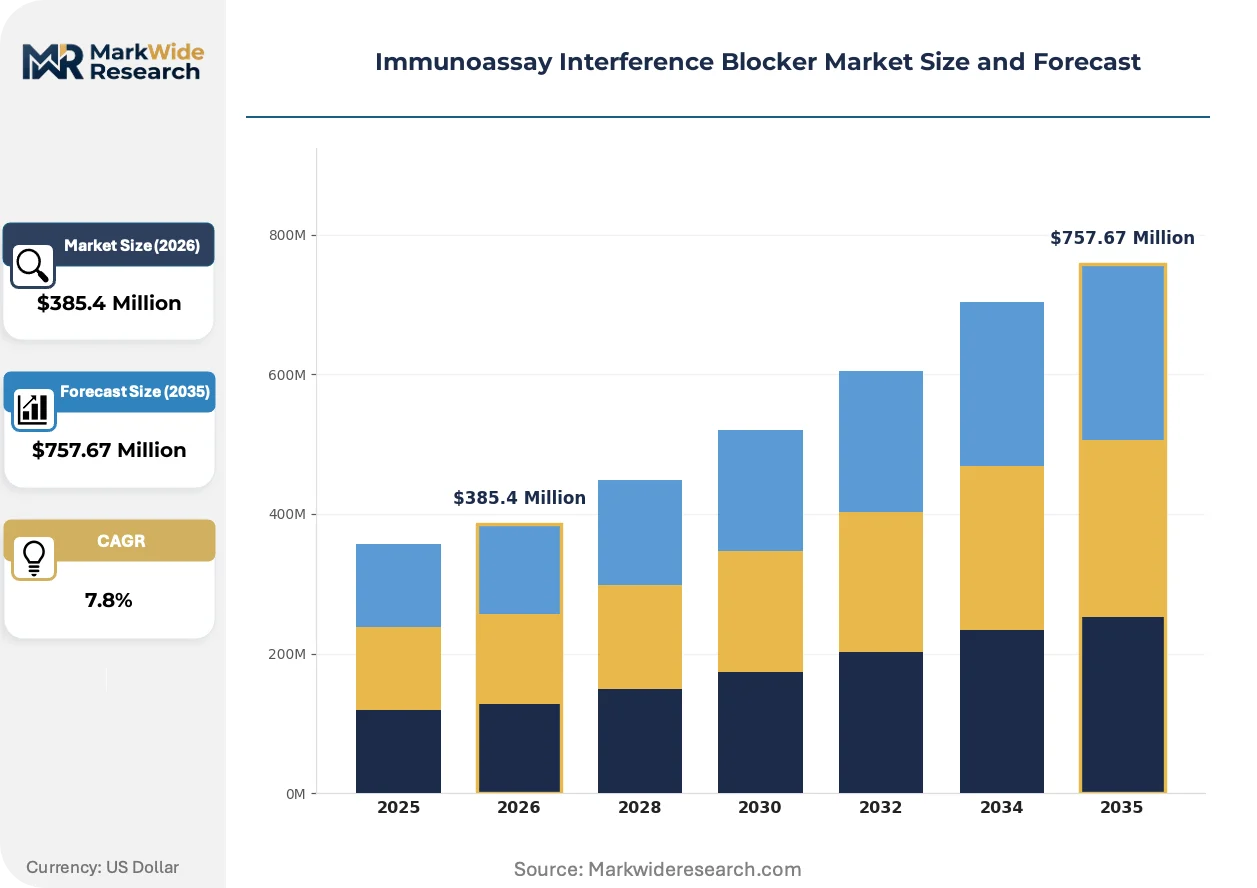
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Proteins, Small Molecules Application: Clinical Diagnostics, Research Laboratories, Environmental Testing, Food Safety Testing End User: Hospitals, Diagnostic Centers, Academic Institutions, Pharmaceutical Companies Technology: ELISA, Western Blotting, Lateral Flow Assay, Chemiluminescence |
| Companies Covered | Roche Diagnostics GmbH, Rockland Immunochemicals, Abcam, AMS Biotechnology (Europe) Limited, Meridian Bioscience, Thermo Fisher Scientific, Scantibodies Laboratory, Aviva Systems Biology, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoassay Interference Blocker Market Strategic Shifts & Innovations
Recombinant protein engineering and regulatory documentation requirements are converging to reshape product development priorities, while procurement centralization is compressing supplier margins and accelerating consolidation.
Engineered Fc receptor fragments are electrifying the competitive landscape for heterophilic antibody neutralization. Contract research organizations developing companion diagnostics are adopting these recombinant formats at twice the pace of hospital laboratories. The technology is electrifying displacement of serum-derived blocking reagents in applications where lot-to-lot consistency determines regulatory submission success.
CLSI EP37 guidelines for interference testing are tightening analytical performance documentation requirements for new diagnostic assays. Manufacturers must now characterize blocker efficacy across broader patient population matrices before commercial release. Clinical chemistry segments in the United States are responding by embedding interference mitigation validation earlier in product development cycles.
Consolidated purchasing agreements are replacing spot-buying for interference blockers among the fifteen largest diagnostic service chains. Distributor relationships that previously managed inventory for individual hospital laboratories are being disintermediated by direct manufacturer contracts with parent health systems. This pattern is most visible in the Southwest and Great Lakes regions of the United States where multi-hospital networks dominate outpatient laboratory services.
Immunoassay Interference Blocker Market Segmentation
Blocker formulation choices directly determine assay reliability and regulatory submission success. Procurement patterns across product types, applications, and end users reveal where supplier margins concentrate and where commodification threatens pricing power.
Product Type:
Supply concentration in animal-origin-free manufacturing capacity is reshaping competitive positioning across protein-based blocker categories.
- Monoclonal Antibodies:Defined epitope specificity and batch-to-batch consistency make these the default for FDA-validated diagnostic assays. Hospital laboratory networks in the United States negotiate multi-year supply agreements based on lot release documentation.
- Recombinant Proteins:Animal-origin-free production addresses IVDR documentation burdens and mitigates biosecurity supply risks. Academic core facilities and European contract manufacturers are absorbing capacity from Swiss and German CMOs at premium pricing.
- Polyclonal Antibodies:Heterogeneous binding profiles from immunized serum sources suit research-use-only applications where cost dominates consistency requirements.
- Small Molecules:Synthetic inhibitors target complement protein interference with defined chemical structures that simplify regulatory characterization.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: Recombinant Proteins.
Application:
Volume scale and per-unit pricing tolerance diverge sharply between regulated diagnostics and exploratory research environments.
- Clinical Diagnostics:Centralized laboratory networks drive procurement consolidation with stringent FDA and IVDR performance documentation. Automated analyzer compatibility requirements extend validation timelines.
- Research Laboratories:Project-specific blocking cocktails command premium pricing with extended lead times. Academic core facilities prioritize formulation flexibility over lot-to-lot consistency.
- Environmental Testing:EPA method compliance drives interference mitigation requirements for water and soil contaminant panels.
- Food Safety Testing:ISO 17025 laboratory accreditation mandates formalize blocker procurement into pathogen detection workflows.
Clinical Diagnostics absorbs the majority of unit volume. Research Laboratories capture the highest per-unit margins.
End User:
Purchasing authority migration from individual sites to parent health systems is compressing supplier margins and accelerating direct manufacturer contracts.
- Hospitals:Integrated delivery networks standardize reagent procurement across affiliated laboratories, disintermediating traditional distributors.
- Diagnostic Centers:Large diagnostic service chains in the Southwest and Great Lakes regions negotiate consolidated agreements with volume commitments.
- Academic Institutions:Tolerance for customized formulations and extended lead times supports premium pricing for specialized blocking cocktails.
- Pharmaceutical Companies:Companion diagnostic development programs demand validated blocker efficacy across broader patient population matrices per CLSI EP37 guidelines.
Diagnostic Centers dominate contract volume. Academic Institutions sustain pricing premiums.
Technology:
Platform-specific validation requirements create compatibility barriers that protect incumbent suppliers and extend product launch timelines.
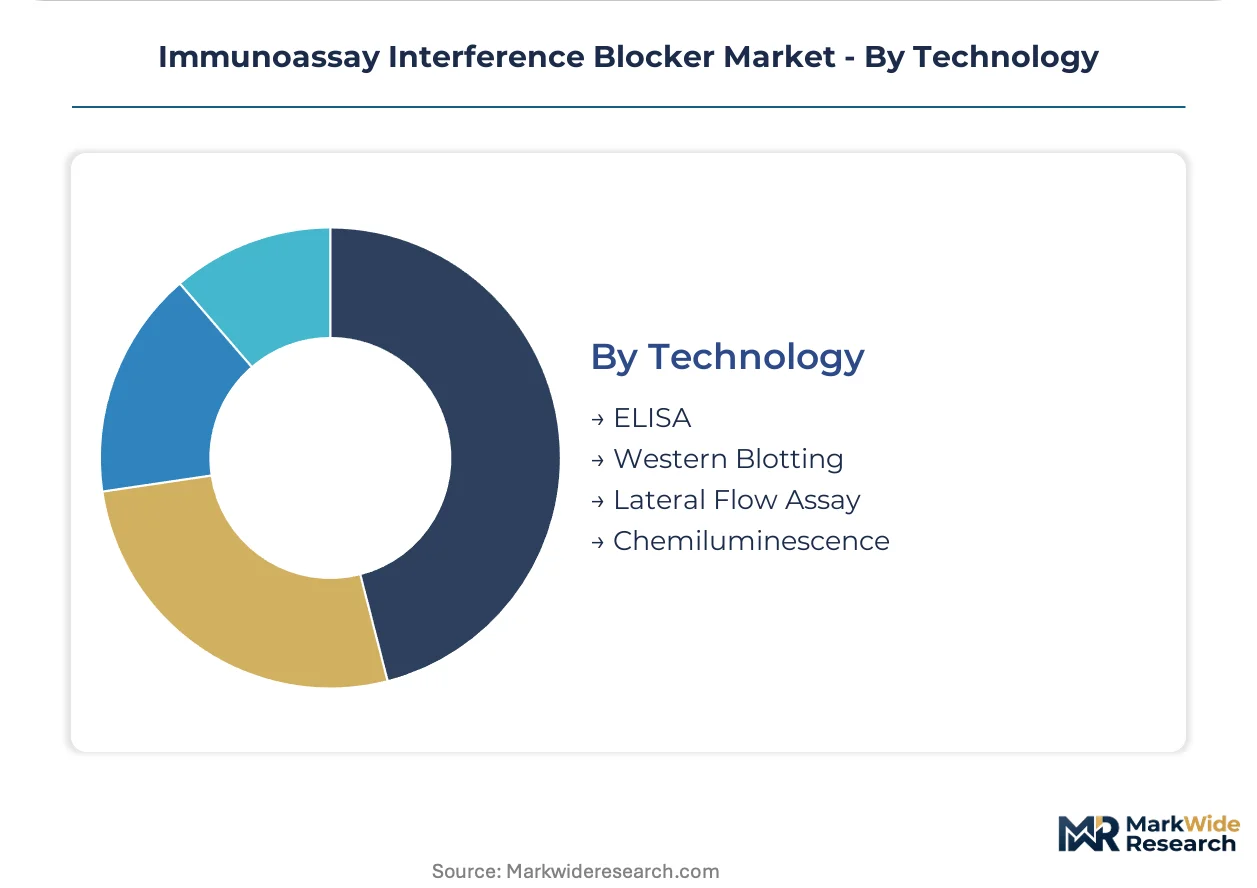
- ELISA:Mature platform with established interference mitigation protocols and extensive legacy analyzer installed base.
- Chemiluminescence:Signal amplification sensitivity demands rigorous blocker characterization to preserve analyte-specific integrity.
- Lateral Flow Assay:Point-of-care miniaturization creates demand for lyophilized blocker formats that lack embedded interference mitigation.
- Western Blotting:Research-dominated application with lower regulatory documentation burdens and higher tolerance for batch variability.
Chemiluminescence anchors high-value diagnostics. Lateral Flow Assay represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States approach interference blocker procurement through divergent regulatory lenses, with European IVDR conformity assessment creating documentation burdens that FDA quality-system regulations handle through post-market surveillance channels. Switzerland and German contract manufacturing organizations control critical animal-origin-free protein production capacity. Diagnostic laboratory consolidation in the American Southwest and Great Lakes regions contrasts with fragmented hospital networks in Southern Europe.
United States
Centralized laboratory networks in the Southwest and Great Lakes regions are consolidating procurement authority into fewer purchasing entities with larger contract volumes. FDA quality-system regulations and CLSI EP37 guidelines shape validation protocols for new blocker introductions, mandating characterization across broader patient population matrices. The Boston-Cambridge biotechnology corridor anchors companion diagnostic development programs that demand validated blocker efficacy.
Germany
Contract manufacturing organizations in Baden-Württemberg and Bavaria control critical capacity for animal-origin-free protein production, concentrating supplier risk for recombinant blocker formats. IVDR conformity assessment requirements extend documentation burdens for reagent suppliers entering the European market. The Rhine-Main cluster around Frankfurt hosts diagnostic service chains negotiating consolidated supply agreements with volume commitments.
Switzerland
Swissmedic regulatory oversight shapes performance documentation standards for blocker formulations distributed across European markets. Basel and Zurich anchor specialized manufacturing of heterophilic antibody blockers, with CMOs absorbing premium pricing from academic core facilities seeking animal-origin-free alternatives. The country's bioprocess engineering talent scarcity constrains manufacturing scale-up for immunoglobulin-derived reagents.
United Kingdom
London and Southeast England diagnostic laboratories respond to IVDR implementation by embedding interference mitigation validation earlier in product development cycles. The country's departure from EU regulatory alignment creates divergence in post-market surveillance expectations that manufacturers must monitor when prioritizing regional product registration investments. Cambridge-based contract research organizations adopt engineered Fc receptor fragments at accelerated pace.
Japan
PMDA oversight of in vitro diagnostics drives stringent performance documentation requirements for blocker efficacy in automated analyzer environments. The Kanto region around Tokyo hosts hospital laboratory networks standardizing reagent procurement across affiliated facilities. Osaka-based diagnostic manufacturers seek recombinant protein formats to mitigate biosecurity-related supply interruptions from serum-derived sources.
Immunoassay Interference Blocker Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the interference blocker supply base, creating a tiered structure where bundled analyzer-reagent agreements clash with customized formulation services. The market consolidates around three strategic archetypes: diversified life science conglomerates leveraging installed instrument bases, specialized reagent manufacturers concentrating on heterophilic antibody neutralization, and contract research organizations developing companion diagnostics. Dominant competitive moves include direct manufacturer contracts disintermediating traditional distributors and backward integration into animal-origin-free protein production capacity.
Among diversified life science conglomerates, Roche Diagnostics GmbH and Thermo Fisher Scientific occupy positions that exemplify the bundling strategy, leveraging broad catalog breadth and analyzer installed bases to secure long-term supply agreements. Scantibodies Laboratory represents the specialized manufacturing archetype, anchoring its competitive position through niche assay developer relationships. These three entities illustrate how supplier margins concentrate where regulatory documentation capabilities intersect with manufacturing scale.
| Leading Market Players |
|---|
| Roche Diagnostics GmbH |
| Rockland Immunochemicals |
| Abcam |
| AMS Biotechnology (Europe) Limited |
| Meridian Bioscience |
| Thermo Fisher Scientific |
| Scantibodies Laboratory |
| Aviva Systems Biology |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Purification and formulation expertise for immunoglobulin-derived reagents concentrates in established biotechnology hubs around Basel and Boston-Cambridge, with labor-cost differentials between Swiss CMOs and US contract manufacturers driving pricing-tier spreads across premium recombinant formats and standard serum-derived alternatives.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for animal-origin-free recombinant proteins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated monoclonal antibody blockers from research-grade polyclonals and bulk serum-derived formulations. Pricing pressure stems from consolidated procurement by hospital laboratory networks demanding volume discounts. Diagnostic service chains exhibit highest price sensitivity, while academic core facilities tolerate premium pricing for customized blocking cocktails.
Supply Chain Analysis
Domestic-content mandates under IVDR are reshaping sourcing patterns for European diagnostic manufacturers. Supply concentrates in Switzerland, Germany, and the United States for recombinant protein production. Raw material dependencies include bovine serum, murine immunoglobulin fractions, and engineered Fc receptor fragments. Single-source vulnerability from Swiss and German CMOs controlling animal-origin-free capacity creates supply risk. Distribution runs through direct manufacturer contracts with parent health systems, disintermediating traditional laboratory distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through backward integration into recombinant protein production capacity and premium-tier displacement of serum-derived blockers.
For Market Incumbents: Acquire captive animal-origin-free manufacturing capacity in Switzerland or Germany to secure recombinant protein supply. Invest in CLSI EP37-compliant validation documentation to defend against emerging recombinant specialists. Consolidate distributor relationships through direct contracts with integrated delivery networks. For New Entrants and Emerging Players: Begin with point-of-care lyophilized blocker formats where embedded interference mitigation remains underdeveloped. Target emergency department miniaturized platforms as the most penetrable application. Pursue research-use-only custom formulations for academic core facilities as the initial go-to-market angle. For Investors and Strategic Acquirers: Diagnostic conglomerates with analyzer installed bases are the most active acquirer in this space. Five-to-ten year viability hinges on IVDR documentation capabilities intersecting with manufacturing scale. Monitor IVDR conformity assessment timelines as the critical inflection signal for recombinant protein demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recombinant Production | Captive Swiss and German CMO capacity mitigates biosecurity supply interruptions. |
| IVDR Conformity Assessment Investment | Enhanced documentation capabilities unlock European diagnostic laboratory procurement. |
| Point-of-Care Lyophilized Format Development | Emergency department platforms lack embedded interference mitigation solutions. |
| Direct Health System Contracting | Disintermediation of distributors captures margin from consolidated purchasing authority. |
| CLSI EP37 Validation Expansion | Broad patient population matrix characterization satisfies FDA quality-system requirements. |
Research Approach
Multiple input streams — reagent procurement managers at hospital laboratory networks, regulatory affairs directors at IVD manufacturers, bioprocess engineers at contract manufacturing organizations, and companion diagnostic development leads — were reconciled against FDA 510(k) filings, IVDR technical documentation databases, CLSI guideline publications, and GPO contract award records. Bottom-up demand aggregation across end-user segments was triangulated with top-down supply-side capacity assessments.
Data-stream reconciliation anchored volume projections across product type, application, end user, and technology platform dimensions over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated IVDR implementation timelines, hospital consolidation patterns, and recombinant protein capacity expansion announcements.
Caveats apply where IVDR enforcement delays, biosecurity-related serum supply interruptions, or heterophilic antibody specificity breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about regulatory trajectory and manufacturing scale-up feasibility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Liver Function Tests Market
Diagnostics
Vision Screeners Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Cancer Tissue Diagnostics Market