
 Avian Flu Treatment Market | 2026-2036
Avian Flu Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Avian Flu Treatment Market Outlook
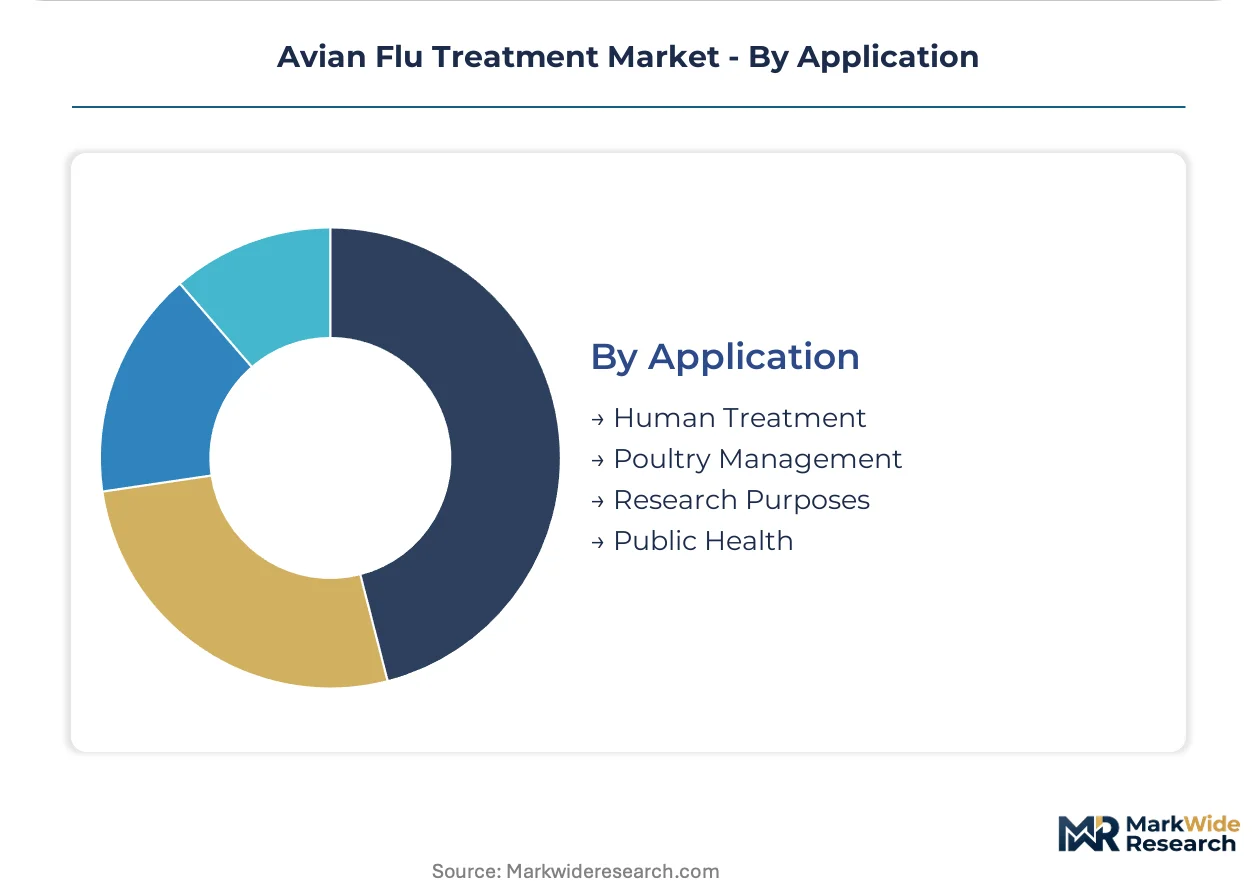
Modular vaccine-dose packaging is shifting procurement patterns among national stockpile managers and large veterinary networks. F. Hoffmann-La Roche Ltd leverages its influenza antiviral manufacturing infrastructure to sustain supply commitments across multiple geographies. Gilead Sciences anchors its position through specialized R&D in broad-spectrum antiviral platforms. Sanofi competes on manufacturing scale for pandemic-scale vaccine production.
Avian flu treatment encompasses pharmaceutical and biological interventions designed to inhibit viral replication, induce immunity, or manage symptoms in infected hosts, with formulations typically requiring cold-chain storage between two and eight degrees Celsius to preserve molecular integrity. The primary purpose spans therapeutic mitigation in human patients, prophylactic protection in poultry populations, and diagnostic containment of zoonotic transmission. Antiviral drugs and vaccines command the dominant share of product-type revenue, while injectable delivery modes capture the largest volume due to veterinary-scale administration requirements. Hospitals and veterinary facilities represent the most concentrated end-user segment, absorbing bulk procurement tied to outbreak response protocols.
The FDA, EMA, and WHO coordinate divergent approval and stockpiling standards that shape market access timelines and manufacturing compliance burdens across jurisdictions. National regulators increasingly mandate real-time adverse-event reporting and strain-specific efficacy documentation before emergency authorization release. Stakeholders must monitor antigenic drift surveillance data and regulatory harmonization negotiations to align production capacity with evolving pandemic threat profiles.
Market Dynamics
Emergency stockpile procurement protocols are restructuring demand patterns as national health agencies accelerate antiviral reserve commitments ahead of anticipated strain mutations. Cold-chain infrastructure investments now determine market access for vaccine manufacturers.
Growth Catalysts
- EMA Pandemic Preparedness Protocols:Accelerated review timelines compress product-to-market cycles for novel antiviral candidates targeting H5N1 variants.
- Intensive Poultry Farming Concentration:Brazil's vertically integrated broiler operations drive bulk vaccine procurement contracts with multi-year supply guarantees.
- mRNA Platform Adaptation:Rapid strain-matching capabilities enable seasonal reformulation cycles that align with antigenic drift surveillance data.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Oseltamivir phosphate synthesis depends on specialized intermediate suppliers concentrated in Zhejiang province.
- Cold-Chain Infrastructure Deficits:Last-mile temperature control failures in Southeast Asian distribution networks compromise vaccine potency.
- Regulatory Divergence:WHO prequalification standards and FDA emergency use authorization pathways impose conflicting stability testing requirements.
Strategic Opportunities
- Sub-Saharan Veterinary Networks:Backyard poultry vaccination programs remain underpenetrated across Nigeria and Kenya despite recurring outbreak clusters.
- Point-of-Care Diagnostic Integration:Rapid antigen test kits paired with antiviral dispensing protocols create bundled service models for rural veterinary clinics.
- US Strategic National Stockpile Expansion:BARDA funding mechanisms prioritize domestic manufacturing capacity for neuraminidase inhibitors.
Industry Challenges
- High-Containment Manufacturing Expertise:Biosafety Level 3 facility operators command premium wages that strain contract manufacturing economics.
- Strain-Specific Efficacy Documentation:EMA mandates real-world effectiveness data before emergency authorization renewal, extending clinical validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avian Flu Treatment Market |
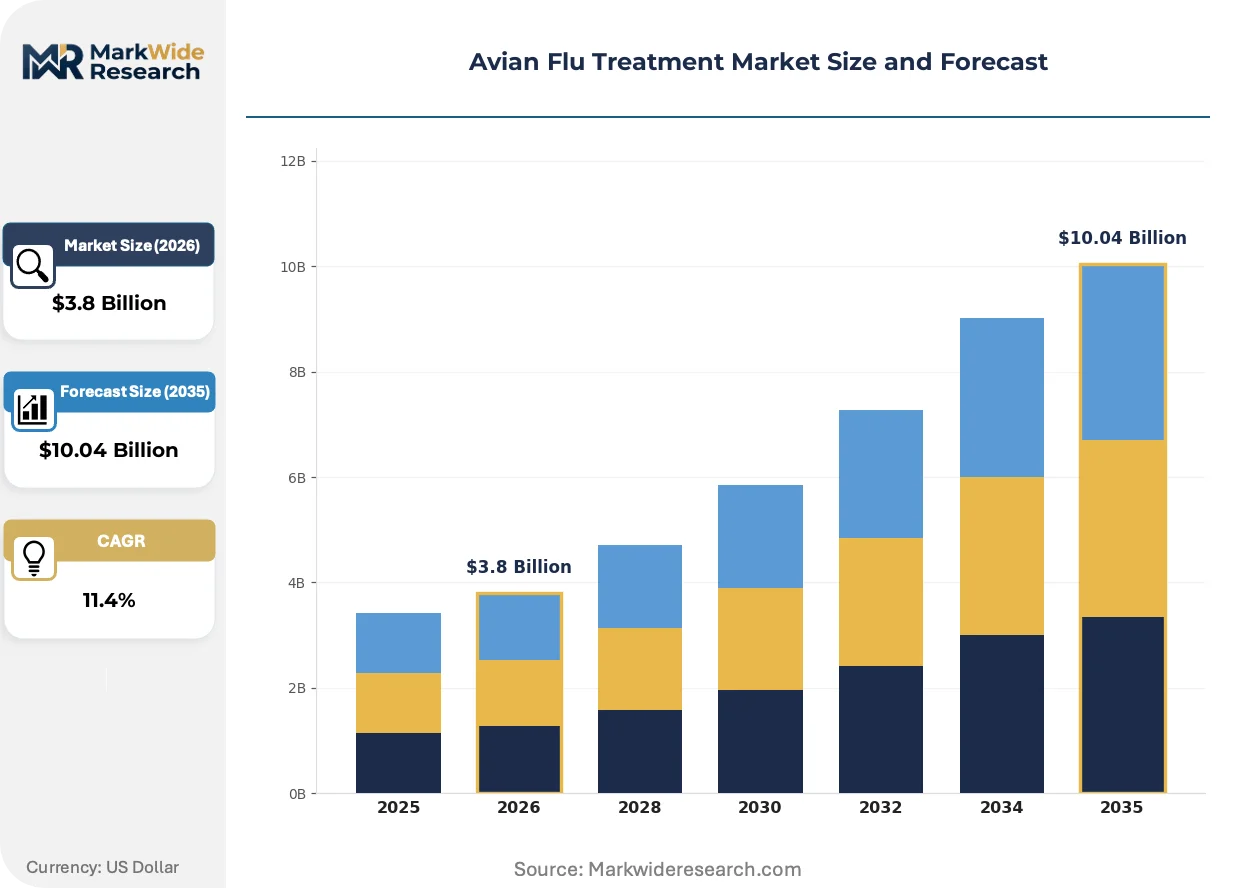
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Drugs, Vaccines, Diagnostic Tests, Supportive Care Delivery Mode: Oral, Injectable, Intranasal, Inhalation End User: Hospitals, Clinics, Research Labs, Veterinary Facilities Application: Human Treatment, Poultry Management, Research Purposes, Public Health |
| Companies Covered | F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Sanofi, Gilead Sciences, BioCryst Pharmaceuticals, Boehringer Ingelheim, Pfizer, Shionogi & Co., Ltd., GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avian Flu Treatment Market Strategic Shifts
Digital supply chain tracking and synthetic biology platforms are compressing development cycles while reshaping how national stockpile managers evaluate supplier reliability. Antigenic surveillance integration now determines manufacturing priorities.
Recombinant vector vaccine platforms are automating strain-adaptation workflows that previously required six-month lead times. Veterinary pharmaceutical distributors in the United States and China are adopting these systems for rapid pandemic-scale response. The technology is automating regulatory submission preparation by generating standardized stability documentation.
REACH registration requirements for novel adjuvant compounds are forcing reformulation strategies among European vaccine developers. Industrial consequence includes accelerated phase-transition studies for oil-in-water emulsion alternatives. Poultry vaccine manufacturers serving EMA jurisdictions are responding by establishing dedicated regulatory affairs teams in Frankfurt and Amsterdam.
Consolidated procurement through national stockpile tenders is displacing fragmented distributor networks across Southeast Asian markets. Government veterinary services in Vietnam and Thailand now negotiate directly with manufacturers for multi-year supply agreements. This concentration is most visible in Indonesia, where the Ministry of Agriculture centralizes all H5N1 vaccine purchases through a single contracting window.
Avian Flu Treatment Market Segmentation
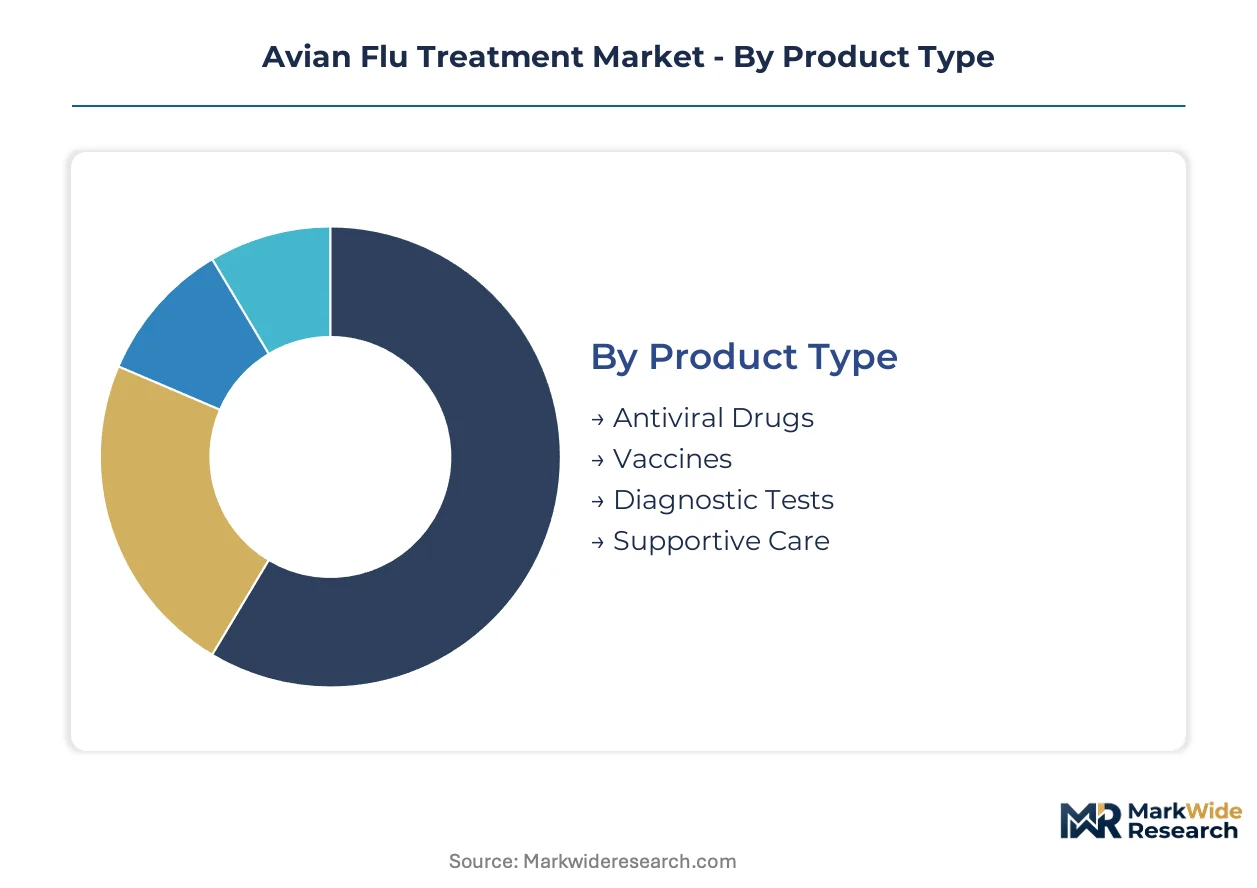
Segmentation in the avian flu treatment market reflects divergent technical requirements between human therapeutic protocols and veterinary-scale prophylaxis. Cold-chain specifications, dosing volumes, and regulatory pathways vary dramatically across product categories, forcing manufacturers to maintain parallel production infrastructures.
Product Type:
Formulation chemistry and biological stability requirements determine manufacturing investment thresholds and margin structures across the four product categories.
- Vaccines:Inactivated viral or recombinant protein formulations require Biosafety Level 3 containment and continuous cold-chain maintenance between two and eight degrees Celsius. Brazil's vertically integrated broiler operations drive multi-year procurement contracts with volume guarantees exceeding ten million doses annually.
- Antiviral Drugs:Small-molecule neuraminidase inhibitors and polymerase inhibitors function through enzymatic blockade of viral replication. API synthesis for oseltamivir phosphate concentrates in Zhejiang province intermediates, creating geographic supply vulnerability.
- Diagnostic Tests:Lateral flow immunoassays and RT-PCR platforms enable point-of-care detection in field veterinary settings.
- Supportive Care:Fluid replacement therapies and respiratory management adjuncts address secondary complications in severe human infections.
Vaccines lead on scale; antiviral drugs lead on momentum.
Delivery Mode:
Administrative route selection correlates with patient population scale, dosing frequency requirements, and infrastructure availability in target geographies.
- Injectable:Intramuscular and subcutaneous delivery dominates veterinary applications where mass administration protocols require rapid throughput. Southeast Asian distribution networks struggle with last-mile temperature control failures that compromise vaccine potency in rural poultry farming regions.
- Oral:Capsule and suspension formulations enable outpatient human treatment and prophylactic household contacts. US Strategic National Stockpile expansion prioritizes domestic manufacturing capacity for neuraminidase inhibitors in tablet form.
- Intranasal:Mucosal delivery platforms stimulate localized IgA antibody production.
- Inhalation:Dry powder and nebulized antiviral formulations target lower respiratory tract infections.
Injectable delivery leads on scale; oral formulations lead on momentum.
End User:
Procurement concentration and technical sophistication requirements fragment demand across institutional customer types.
- Veterinary Facilities:Commercial poultry operations and government veterinary services execute bulk procurement tied to outbreak response protocols. Indonesia's Ministry of Agriculture centralizes all H5N1 vaccine purchases through a single contracting window, consolidating previously fragmented distributor networks.
- Hospitals:Tertiary care centers manage severe human H5N1 cases requiring intensive respiratory support and combination antiviral therapy. EMA pandemic preparedness protocols accelerate emergency use authorization for novel therapeutic candidates targeting hospitalized patients.
- Clinics:Primary care and urgent care settings handle outpatient prophylaxis and early treatment.
- Research Labs:Academic and government institutions conduct strain surveillance and vaccine efficacy studies.
Veterinary facilities lead on scale; hospitals lead on momentum.
Application:
Functional purpose determines regulatory pathway, pricing structure, and manufacturing scale requirements.
- Poultry Management:Prophylactic vaccination and depopulation-adjacent treatment protocols protect commercial flock economics. Nigeria and Kenya backyard poultry vaccination programs remain underpenetrated despite recurring outbreak clusters, presenting expansion opportunity.
- Human Treatment:Therapeutic intervention in confirmed H5N1 infections requires rapid diagnostic confirmation and antiviral initiation within 48 hours of symptom onset. FDA emergency use authorization pathways compress product-to-market cycles for novel candidates.
- Public Health:National stockpile procurement and pandemic preparedness infrastructure investment.
- Research Purposes:Strain characterization and vaccine platform development activities.
Poultry management leads on scale; human treatment leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intensive poultry farming operations in the United States pioneered mass vaccination protocols during the 2015 H5N2 outbreak, establishing treatment infrastructure that now serves as the template for national stockpile systems worldwide. This historical foundation explains why procurement patterns and regulatory frameworks across major markets trace their lineage to American veterinary-scale deployment models.
United States
Commercial broiler operations in Georgia and Arkansas execute multi-million dose procurement contracts tied to USDA outbreak response protocols. The FDA's emergency use authorization pathways compress approval timelines for novel antiviral candidates. BARDA funding mechanisms prioritize domestic manufacturing capacity for neuraminidase inhibitors, concentrating production investment in Maryland and North Carolina biomanufacturing clusters.
China
Vertically integrated duck and goose farming in Shandong and Jiangsu provinces drives bulk vaccine consumption exceeding twenty million doses annually. The NMPA coordinates strain-specific efficacy documentation requirements with provincial agricultural authorities. Zhejiang province intermediates supply the specialized chemical precursors for oseltamivir phosphate synthesis, creating geographic concentration in API manufacturing.
Brazil
São Paulo and Paraná state poultry conglomerates operate closed-loop vaccination programs with multi-year supply guarantees. ANVISA aligns national stockpiling standards with MERCOSUR veterinary pharmaceutical protocols. Santa Catarina's integrated broiler processing corridor hosts the densest concentration of cold-chain distribution infrastructure for temperature-sensitive biologicals.
Germany
Bavarian veterinary pharmaceutical distributors serve as the logistics hub for EMA-coordinated pandemic preparedness procurement across Central Europe. The Paul-Ehrlich-Institut mandates real-time adverse-event reporting systems that strain smaller manufacturers' pharmacovigilance capabilities. Frankfurt and Amsterdam host dedicated regulatory affairs teams established by vaccine developers seeking streamlined REACH registration for novel adjuvant compounds.
Indonesia
Java-based backyard poultry networks generate fragmented demand that the Ministry of Agriculture has consolidated through centralized H5N1 vaccine purchasing windows. The national pharmaceutical regulator imposes cold-chain documentation requirements that exclude distributors lacking temperature-controlled last-mile capabilities. Surabaya and Bandung veterinary clinics increasingly adopt point-of-care diagnostic integration bundled with antiviral dispensing protocols.
Avian Flu Treatment Market Competitive Environment
Premium-margin players sit above commodity-margin players across manufacturing sophistication and regulatory compliance burden, with pandemic-scale vaccine producers commanding supply commitments that generic antiviral manufacturers cannot match. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with dedicated influenza divisions, mid-cap biotech specialists focused on broad-spectrum platforms, and regional veterinary pharmaceutical distributors serving national agricultural authorities. Dominant competitive moves include strategic partnerships for cold-chain infrastructure access and portfolio diversification into diagnostic test kit bundling.
Within the multinational conglomerate tier, F. Hoffmann-La Roche Ltd and Sanofi exemplify archetypes of manufacturing-scale commitment and pandemic-response infrastructure respectively. Gilead Sciences occupies a distinct position among biotech specialists pursuing platform-based antiviral development. These three entities collectively represent the competitive spectrum spanning established antiviral manufacturing, vaccine production at scale, and specialized R&D investment in next-generation therapeutic modalities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Sanofi |
| Gilead Sciences |
| BioCryst Pharmaceuticals |
| Boehringer Ingelheim |
| Pfizer |
| Shionogi & Co., Ltd. |
| GSK plc |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed veterinary pharmaceutical producers in Brazil and Indonesia anchor supply-side discipline through multi-year procurement contracts that lock in volume guarantees and compress margin volatility for cold-chain biologicals. These state-anchored purchasing windows create pricing power asymmetries where national stockpile managers extract favorable terms while specialized API manufacturers in Zhejiang province capture upstream rent.
Pricing Analysis
Three-tier pricing structure across premium branded antivirals, standard generic neuraminidase inhibitors, and economy-grade bulk vaccines governs transaction economics. Price differentiation hinges on EMA emergency use authorization tier and cold-chain certification grade, with FDA-approved formulations commanding substantial premiums over WHO-prequalified alternatives. Pricing pressure stems from consolidated national tendering in Southeast Asia, where Indonesia's Ministry of Agriculture centralizes H5N1 vaccine purchases through single contracting windows. Government veterinary services exhibit highest price sensitivity, while tertiary hospital systems in Germany and the United States absorb premium therapeutics with limited elasticity.
Supply Chain Analysis
Specialized refrigerated freight corridors between Zhejiang province API synthesis facilities and European formulation plants consume disproportionate logistics spend relative to product value. Active pharmaceutical ingredient manufacturing concentrates in China, vaccine formulation clusters in Germany and the United States, and distribution gravity centers on Brazil's Santa Catarina broiler processing corridor. Oseltamivir phosphate synthesis rests on shikimic acid and specialized intermediate feedstocks from Zhejiang chemical parks. Single-source vulnerability in BSL-3 manufacturing capacity creates chokepoint exposure. Distribution runs through vertically integrated poultry conglomerates executing direct manufacturer contracts, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The avian flu treatment market functions as a regulatory compounder where EMA pandemic preparedness protocol acceleration and FDA emergency use authorization pathway expansion mechanically expand addressable demand through compressed approval timelines.
For Market Incumbents: To counter mRNA platform specialists threatening strain-adaptation speed advantages, Roche and Sanofi should deepen captive supply of BSL-3 manufacturing capacity through dedicated facility investment in Maryland and North Carolina biomanufacturing clusters. Regulatory affairs team expansion in Frankfurt and Amsterdam secures streamlined REACH registration for novel adjuvant compounds, creating compliance moats that strain mid-cap competitors. For New Entrants and Emerging Players: Backyard poultry vaccination programs across Nigeria and Kenya present the most penetrable white-space opportunity, with government veterinary services in Sub-Saharan Africa lacking temperature-controlled last-mile infrastructure. Point-of-care diagnostic integration bundled with antiviral dispensing protocols offers a differentiated go-to-market angle for rural veterinary clinic penetration. For Investors and Strategic Acquirers: Animal health conglomerates with existing poultry vaccine portfolios are the most active acquirer in this space, seeking synthetic biology platforms that automate strain-adaptation workflows. Acquisition targets should display BSL-3 operational expertise and EMA regulatory submission track records. Antigenic drift surveillance data integration capabilities signal platform scalability and warrant valuation premium.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Secures last-mile temperature integrity for vaccine potency in Southeast Asian distribution networks. |
| Regulatory Affairs Team Expansion | Accelerates REACH registration timelines for novel adjuvant compounds in EMA jurisdictions. |
| mRNA Platform Technology Licensing | Enables seasonal reformulation cycles aligned with antigenic drift surveillance data. |
| Point-of-Care Diagnostic Integration | Creates bundled service models for rural veterinary clinics in underpenetrated African markets. |
| BSL-3 Manufacturing Capacity Buildout | Addresses high-containment expertise scarcity that strains contract manufacturing economics. |
Study Parameters
Bottom-up veterinary facility and hospital procurement modeling reconciled against top-down API manufacturing and vaccine production tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at EMA-coordinated developers, poultry conglomerate procurement officers in Brazil, national stockpile managers in Indonesia, BSL-3 facility operators, and cold-chain logistics specialists were validated against secondary sources including FDA emergency use authorization filings, EMA pandemic preparedness protocol documentation, ClinicalTrials.gov entries, USDA outbreak response records, and ANVISA veterinary pharmaceutical registrations.
Input-output matrices mapping antiviral API synthesis through formulation, cold-chain distribution, and end-user administration generated volume and value estimates across the analysis window. Segmentation dimensions encompassed product type, delivery mode, end-user institution, and application purpose, with regional regulatory cluster effects modeled separately. CAGRs were derived from trend extrapolation of stockpile procurement commitments, poultry flock vaccination intensity, and strain mutation surveillance frequency. Industry-specific forecast inputs included antigenic drift velocity indices and BSL-3 manufacturing capacity utilization rates.
Underlying measurement precision varies by segment; hospital and veterinary facility procurement data carry tighter precision than backyard poultry vaccination estimates. Forecasts reflect assumptions regarding regulatory harmonization progress, cold-chain infrastructure investment continuity, and strain mutation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Laser Therapy Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Skin Grafts Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market