
 Autoimmunity Immunoassay Market | 2026-2036
Autoimmunity Immunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Autoimmunity Immunoassay Market Outlook
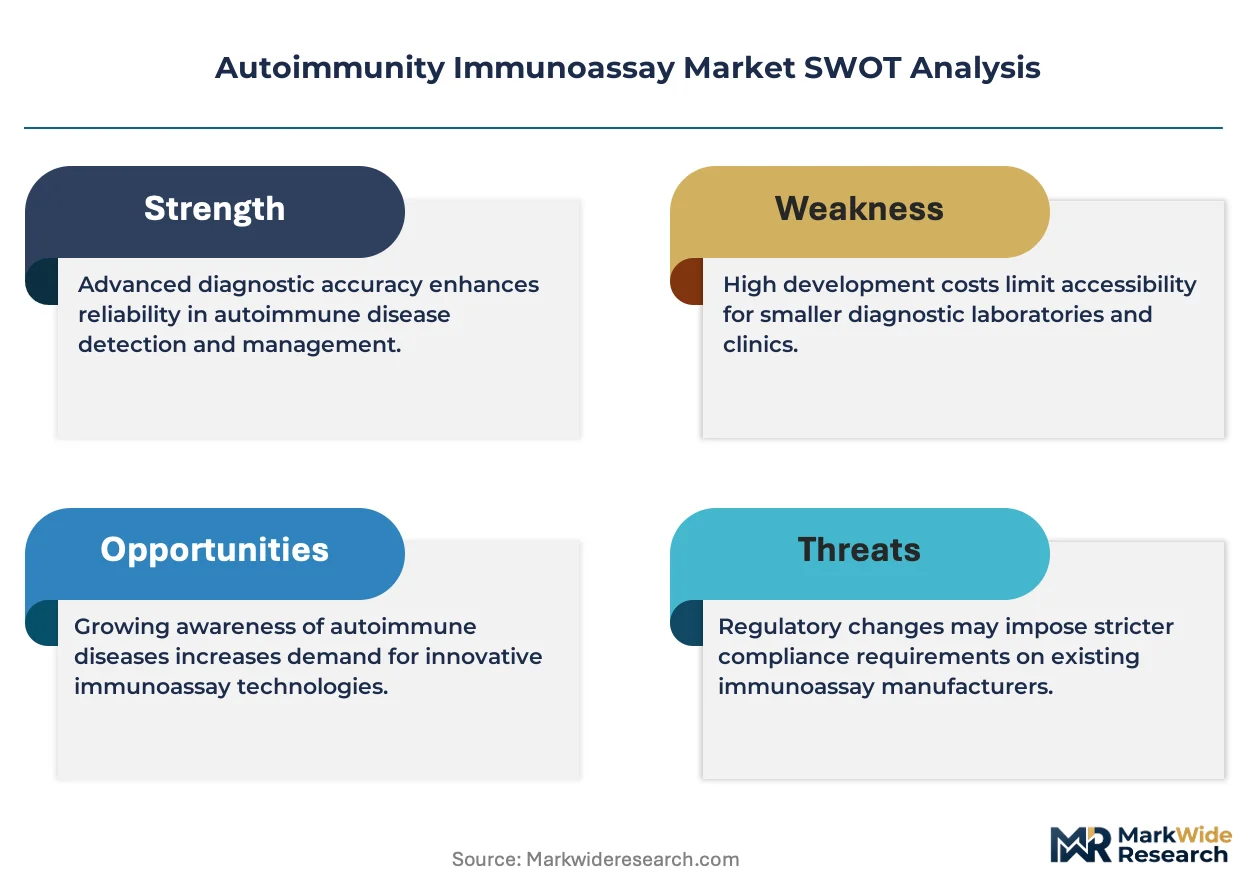
CE marking under the EU In Vitro Diagnostic Regulation is reorganizing competitive access for autoimmune assay suppliers seeking European market entry. Abbott Laboratories leverages its installed base of immunoanalyzers to sustain revenue continuity across hospital laboratories. Siemens Healthineers anchors its position through integrated diagnostic platforms that combine immunoassay with imaging workflows. Thermo Fisher Scientific differentiates via deep specialization in research-use autoimmune panels that bridge into clinical translation.
Autoimmunity immunoassay denotes quantitative and qualitative laboratory methods that detect autoantibodies against self-antigens, typically achieving sensitivity thresholds below 1 IU/mL through chemiluminescent or fluorescent signal amplification. These assays enable differential diagnosis of systemic autoimmune diseases and monitoring of immunosuppressive therapy response. Enzyme-linked immunosorbent assay remains the mature workhorse format with established reimbursement, while chemiluminescence technology captures the fastest expansion due to higher throughput and broader menu consolidation on automated platforms. Rheumatoid arthritis application volumes lead absolute demand, though systemic lupus erythematosus testing commands premium pricing through multiplexed biomarker panels.
The FDA oversees premarket notification pathways for autoimmune immunoassays, while the EU IVDR imposes stricter clinical evidence requirements that extend certification timelines for novel biomarkers. Health Canada and Japan's PMDA maintain parallel review frameworks that manufacturers must navigate for multi-region product registration. Stakeholders must monitor evolving regulatory divergence between decentralized laboratory-developed test permissions and centralized IVD kit approvals to align portfolio investment with accessible market channels.
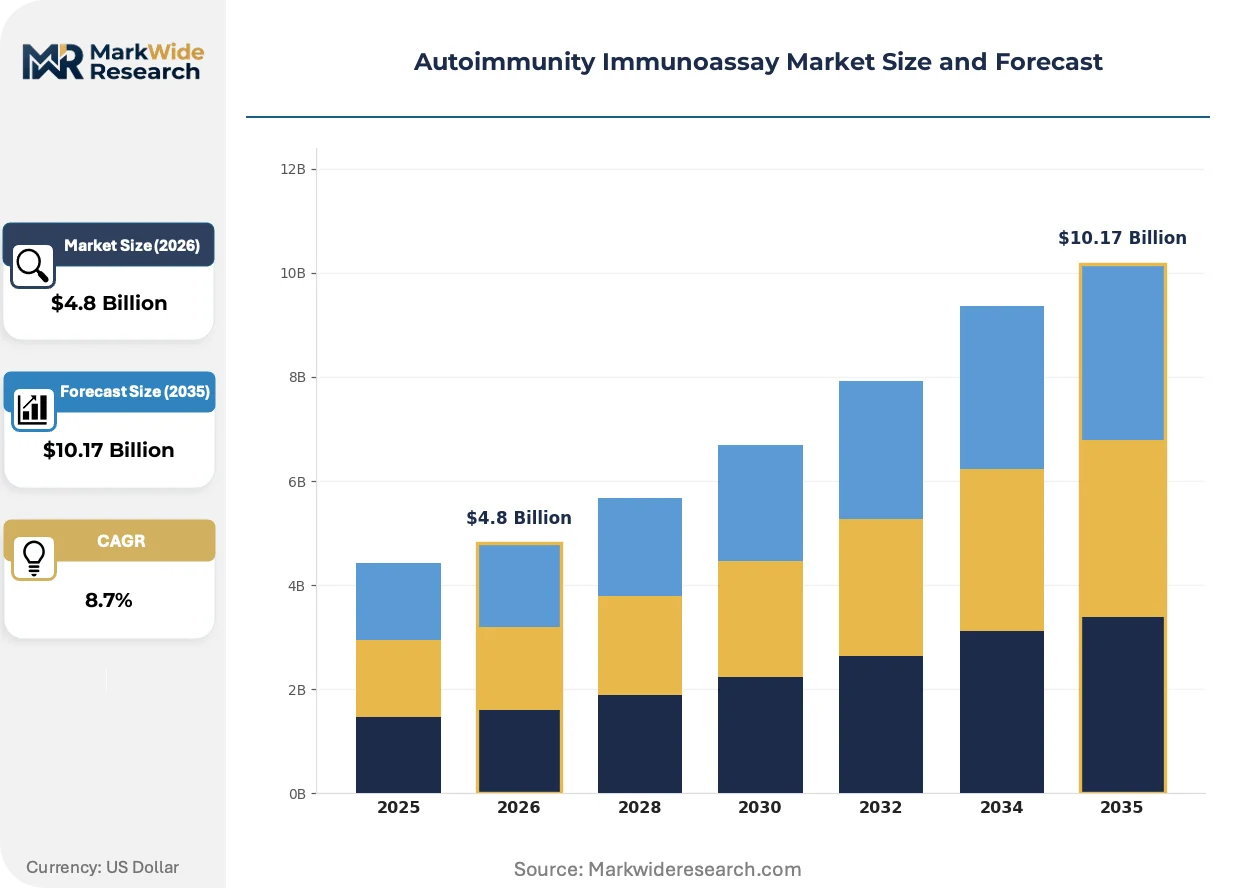
Market Dynamics
Automated chemiluminescence platforms are compressing turnaround times for autoimmune diagnostics while simultaneously raising capital barriers for mid-sized laboratories seeking menu expansion. This technological consolidation is redistributing test volumes toward integrated health systems with sufficient throughput to justify analyzer investments.
Growth Catalysts
- EU IVDR clinical evidence mandates:Stricter certification requirements under the European In Vitro Diagnostic Regulation are accelerating consolidation among assay developers with robust clinical data libraries, favoring established manufacturers over smaller entrants.
- Rheumatology referral networks:Hospital systems in the United States are centralizing complex autoimmune testing within flagship laboratories to capture downstream specialty revenue from community rheumatology practices.
- Multiplexed biomarker panels:Simultaneous detection of multiple autoantibodies on single platforms is reducing per-test costs while improving diagnostic specificity for systemic lupus erythematosus classification criteria.
Market Restraints
- Antigen sourcing concentration:Recombinant human autoantigen production remains concentrated among a limited set of specialized biotechnology suppliers, creating vulnerability to batch-to-batch variability and supply interruptions.
- FDA premarket notification pathways:Evolving guidance on substantial equivalence determinations for novel autoimmune biomarkers extends regulatory timelines and increases validation costs for assay developers.
- Laboratory-developed test substitution:Academic medical centers with sufficient analytical expertise continue to develop in-house alternatives to commercial IVD kits, compressing addressable market for standardized products.
Strategic Opportunities
- India diagnostic infrastructure expansion:The country's PLI scheme for medical device manufacturing is attracting autoimmune assay suppliers to establish localized production and distribution networks for tier-2 and tier-3 cities.
- Digital pathology integration:Convergence of immunoassay quantification with whole-slide imaging and artificial intelligence scoring is creating novel service models for lupus nephritis monitoring.
- Direct-to-consumer channel emergence:Regulatory frameworks in select jurisdictions are permitting physician-mediated direct access testing for celiac disease and thyroid autoimmunity screening, bypassing traditional hospital laboratory channels.
Industry Challenges
- Specialized immunoassay technologist scarcity:Hospital laboratories report persistent difficulty recruiting personnel with expertise in chemiluminescence platform troubleshooting and complex antibody interference resolution.
- Legacy analyzer integration complexity:Health systems seeking to consolidate autoimmune testing onto newer platforms face substantial middleware reconfiguration costs to maintain connectivity with existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoimmunity Immunoassay Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Western Blot, Radioimmunoassay, Lateral Flow Assay Technology: Fluorescence, Chemiluminescence, Colorimetric, Electrochemical End User: Hospital Laboratories, Independent Laboratories, Research Institutes, Diagnostic Centers Application: Rheumatoid Arthritis, Systemic Lupus Erythematosus, Celiac Disease, Hashimoto's Thyroiditis |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Siemens Healthineers, Thermo Fisher Scientific, Bio-Rad Laboratories, Danaher Corporation, Becton, Dickinson and Company, bioMérieux SA, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoimmunity Immunoassay Market Strategic Shifts
Signal amplification architectures and detection chemistries are undergoing rapid diversification as manufacturers seek differentiation beyond throughput metrics. This technical pluralism is creating both opportunity and complexity for laboratory procurement decisions.
Magnetic microparticle-based solid-phase separation is fragmenting the historical dominance of polystyrene microplate formats in autoimmune testing. Mid-sized hospital laboratories in Germany and France are adopting these platforms to achieve walk-away automation without the capital requirements of full random-access analyzers. The technology is fragmenting vendor lock-in patterns by enabling reagent compatibility across multiple instrument generations.
The FDA's evolving enforcement discretion framework for laboratory-developed tests is compressing the competitive window for commercial IVD manufacturers in the United States. Manufacturers are responding by accelerating 510(k) submissions for biomarker panels previously offered only as LDTs, particularly in connective tissue disease differentiation. This regulatory recalibration most directly affects rheumatology-focused reference laboratories that had built service models around proprietary assay development.
Consolidated procurement through integrated delivery networks is displacing decentralized purchasing by individual hospital laboratories across the United States. IDN supply chain committees now mandate interoperability with enterprise data warehouses and standardized reporting formats as preconditions for analyzer placement. This behavioral shift is most pronounced in the Southeast and Midwest regions where health system mergers have concentrated purchasing authority within regional headquarters.
Autoimmunity Immunoassay Market Segmentation
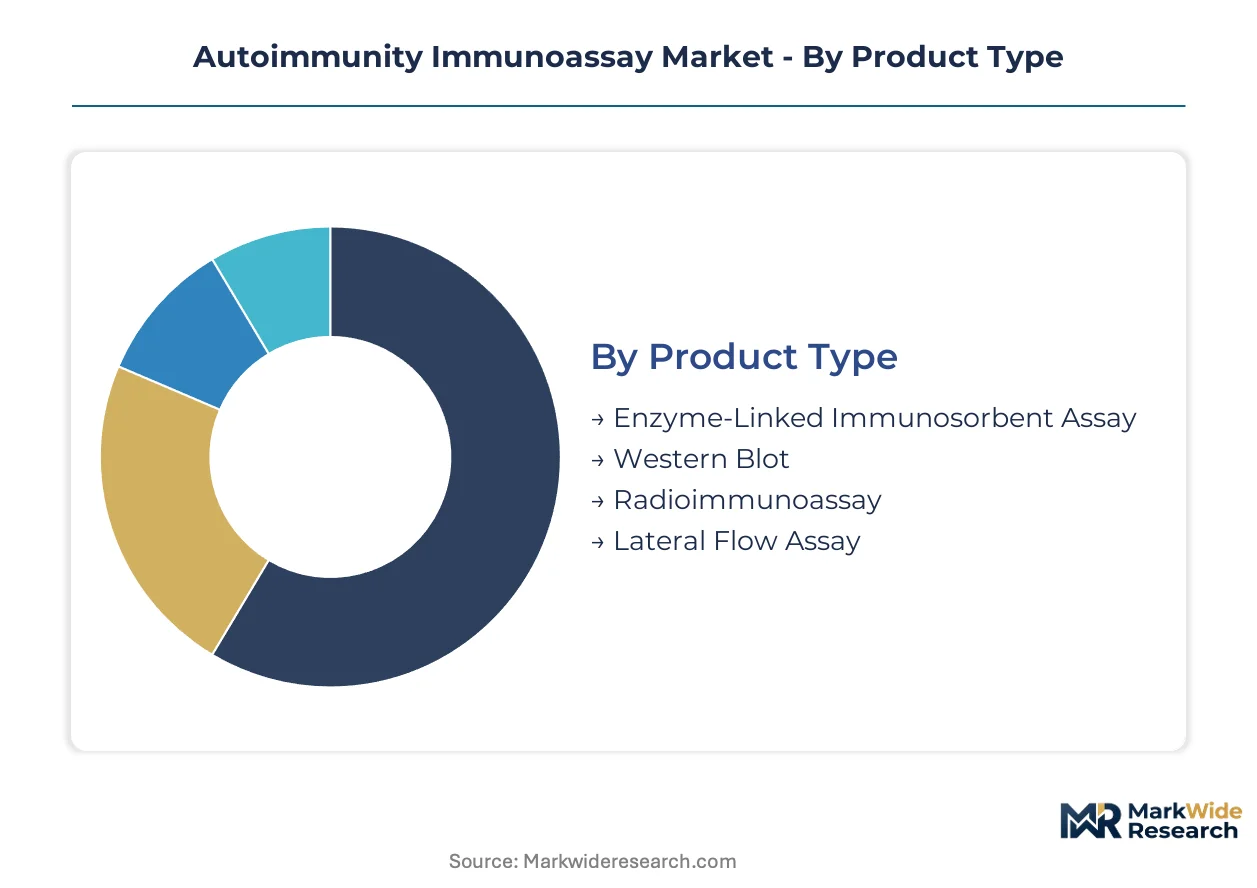
Segmentation in autoimmunity immunoassays reveals how technological formats and clinical applications create distinct competitive arenas with varying substitution vulnerabilities. Understanding these boundaries helps suppliers allocate R&D resources and anticipate where laboratory-developed tests or alternative platforms will erode commercial kit demand.
Product Type:
Substitution pressure from laboratory-developed alternatives and emerging point-of-care formats varies sharply across assay architectures, with legacy formats facing the most acute competitive displacement.
- Enzyme-Linked Immunosorbent Assay:The polystyrene microplate-based colorimetric detection system remains the reimbursement-validated workhorse for autoantibody quantification in hospital laboratories with established workflows. United States integrated delivery networks concentrate demand here due to favorable Medicare coverage determinations and extensive validation literature, though the format faces gradual displacement by chemiluminescent alternatives in high-throughput settings.
- Chemiluminescence Immunoassay:Magnetic microparticle-based signal amplification achieves sub-1 IU/mL sensitivity thresholds on random-access analyzers, compressing turnaround times for STAT autoimmune testing. German and French mid-sized laboratories are adopting these platforms to secure walk-away automation without full analyzer capital commitments, driving the steepest technology transition in the European market.
- Western Blot:Membrane-based protein separation confirms autoantibody specificity through molecular weight discrimination, retaining niche demand in reference laboratories for ambiguous ELISA results.
- Radioimmunoassay:Isotopic detection methods persist in specialized endocrinology applications for thyroid autoimmunity despite radiological handling burdens and declining reagent availability.
- Lateral Flow Assay:Immunochromatographic strips enable rapid point-of-care screening for celiac disease antibodies in physician office laboratories with limited equipment infrastructure.
Enzyme-Linked Immunosorbent Assay retains volume leadership across installed bases; Chemiluminescence Immunoassay holds the steepest expansion curve as laboratories consolidate menus onto automated platforms.
Technology:
Detection chemistry selection directly determines capital equipment compatibility and throughput economics, creating divergent cost tiers that stratify laboratory procurement decisions.
- Chemiluminescence:Acridinium ester or alkaline phosphatase-triggered light emission enables 10^6 dynamic range detection of anti-dsDNA and anti-CCP antibodies on integrated analyzer platforms. United States hospital laboratories with rheumatology referral networks prioritize this technology for its throughput scalability and reduced technologist hands-on time.
- Fluorescence:Europium chelate or fluorescein-based signal generation supports multiplexed bead arrays for simultaneous autoantibody profiling in systemic lupus erythematosus classification. Research institutes in Japan leverage fluorescence for biomarker discovery panels bridging toward clinical translation.
- Colorimetric:Tetramethylbenzidine substrate conversion produces absorbance readings proportional to autoantibody concentration, dominating cost-sensitive independent laboratory segments.
- Electrochemical:Amperometric detection of redox reactions at functionalized electrodes enables miniaturized biosensor formats for decentralized thyroid autoimmunity monitoring.
Colorimetric methods anchor the economy tier for independent laboratories; Chemiluminescence commands premium positioning in high-throughput hospital settings.
End User:
Customer concentration patterns reflect how testing complexity and reimbursement economics distribute autoimmunity diagnostics across institutional categories.
- Hospital Laboratories:Centralized immunology departments within academic medical centers perform complex connective tissue disease panels with full chemiluminescence automation. United States integrated delivery networks in the Southeast and Midwest regions have concentrated purchasing authority for these platforms following regional merger activity.
- Independent Laboratories:Commercial reference laboratories process high volumes of routine rheumatoid arthritis and thyroid autoimmunity testing under capitated contracts with payers.
- Research Institutes:Academic medical centers develop and validate novel autoantibody biomarkers through research-use-only panels prior to clinical assay commercialization.
- Diagnostic Centers:Outpatient-focused facilities in India's tier-2 and tier-3 cities are expanding autoimmune testing menus under PLI scheme infrastructure incentives.
Hospital Laboratories dominate complex panel volume; Diagnostic Centers in emerging markets are gaining share fastest as localized production reduces kit costs.
Application:
Disease-specific testing volumes correlate with prevalence, diagnostic algorithm complexity, and monitoring frequency requirements across autoimmune conditions.
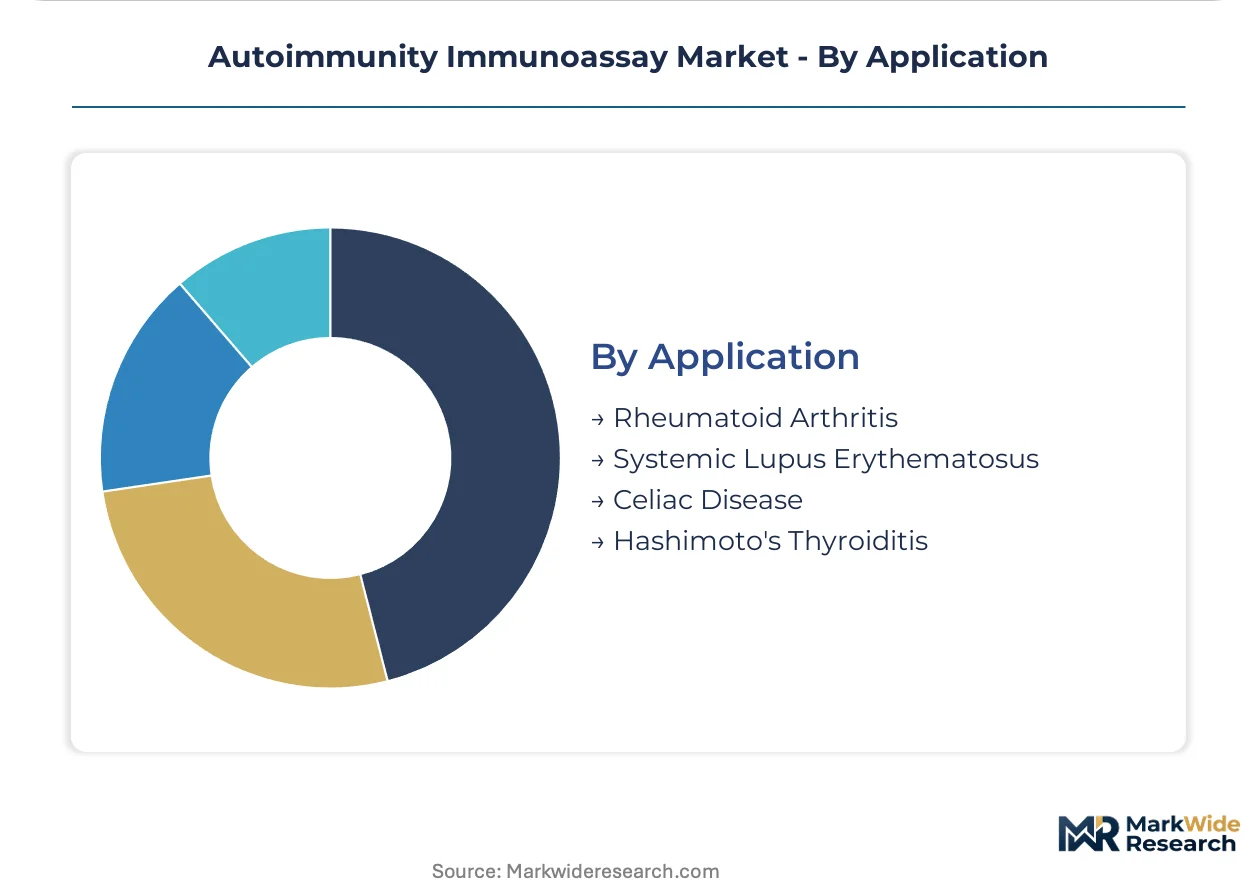
- Rheumatoid Arthritis:Anti-cyclic citrullinated peptide and rheumatoid factor testing constitutes the highest absolute volume application, driven by early diagnosis guidelines and biologic therapy monitoring protocols. United States rheumatology practices generate concentrated demand through centralized laboratory referral networks.
- Systemic Lupus Erythematosus:Multiplexed anti-dsDNA, anti-Smith, and antiphospholipid antibody panels command premium pricing due to classification criteria complexity and lupus nephritis monitoring requirements. European Union IVDR clinical evidence mandates particularly affect novel biomarker panel introductions in this segment.
- Celiac Disease:Tissue transglutaminase and deamidated gliadin peptide screening supports gluten-free diet initiation and compliance monitoring in gastroenterology practices.
- Hashimoto's Thyroiditis:Anti-thyroid peroxidase and anti-thyroglobulin assays enable autoimmune hypothyroidism diagnosis and levothyroxine therapy adjustment in endocrinology and primary care settings.
Rheumatoid Arthritis generates the largest test volume globally; Systemic Lupus Erythematosus delivers the highest revenue per test through multiplexed panel complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for diagnostic infrastructure expansion are redirecting autoimmune assay demand toward emerging manufacturing clusters. Regulatory divergence between centralized IVD frameworks and laboratory-developed test permissions creates distinct market access conditions across jurisdictions. Hospital consolidation patterns concentrate procurement authority within integrated health systems in mature markets.
United States
Integrated delivery networks in the Southeast and Midwest regions centralize high-complexity immunology testing within flagship laboratories. The FDA's evolving enforcement discretion framework for laboratory-developed tests compresses competitive windows for commercial kit manufacturers. Boston and San Diego biotech corridors host reference laboratories developing proprietary autoimmune biomarker panels.
Germany
Mid-sized hospital laboratories adopt magnetic microparticle-based chemiluminescence platforms to achieve walk-away automation without full capital commitments. The EU IVDR imposes stricter clinical evidence requirements that extend certification timelines for novel biomarkers. The Rhine-Ruhr industrial corridor concentrates reagent manufacturing and analyzer distribution infrastructure.
India
The PLI scheme for medical device manufacturing attracts autoimmune assay suppliers to establish localized production networks for tier-2 and tier-3 cities. CDSCO regulatory pathways govern import licensing and domestic manufacturing approvals for diagnostic kits. Maharashtra and Karnataka states expand diagnostic center infrastructure under public-private partnership models.
Japan
Research institutes leverage fluorescence-based multiplexed bead arrays for biomarker discovery panels bridging toward clinical translation. PMDA maintains parallel review frameworks that manufacturers navigate alongside FDA and EU IVDR processes for multi-region registration. The Kanto region around Tokyo concentrates academic medical centers with advanced immunology departments.
China
Domestic diagnostic infrastructure expansion supports localized autoimmune testing menu development for rheumatology and endocrinology applications. NMPA oversees premarket approval pathways for novel immunoassay platforms entering the domestic market. The Yangtze River Delta region hosts manufacturing clusters for magnetic microparticle and chemiluminescent reagent production.
Autoimmunity Immunoassay Market Competitive Environment
Player mix skews toward diversified diagnostics conglomerates with installed analyzer bases and specialized biotechnology suppliers with deep antigen production expertise. Consolidation pressure favors manufacturers with robust clinical data libraries capable of satisfying EU IVDR evidence mandates. Two strategic archetypes dominate: platform-integrated systems providers and research-use panel specialists. Competitive moves center on chemiluminescence menu expansion and strategic partnerships with academic medical centers for biomarker validation.
Among diversified diagnostics conglomerates, Abbott Laboratories, Siemens Healthineers, and Thermo Fisher Scientific occupy positions spanning hospital laboratory automation and research translation. Abbott represents the platform-integrated archetype through immunoanalyzer installed base leverage. Siemens exemplifies convergence between diagnostic imaging and immunoassay workflows. Thermo Fisher anchors the research-to-clinical bridge through specialized autoimmune panel development. These three entities collectively illustrate how scale and specialization vectors define competitive positioning in autoimmune diagnostics procurement.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Becton, Dickinson and Company |
| bioMérieux SA |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Magnetic microparticle substrate substitution for polystyrene microplates simultaneously redistributes reagent manufacturing toward Germany and China while compressing per-test pricing through automated platform consolidation. This input transition concentrates procurement leverage within integrated delivery networks capable of justifying analyzer capital commitments.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate high-volume agreements between hospital laboratories and autoimmune assay suppliers. Three-tier pricing structure across premium, standard, and economy levels separates chemiluminescence platforms from ELISA workflows and point-of-care strips. Cost compression in economy-tier ELISA reagents is intensifying because independent laboratories face capitated payer pressure. Independent reference laboratories exhibit highest price sensitivity; academic medical centers with research funding demonstrate lowest.
Supply Chain Analysis
China and Germany anchor recombinant autoantigen production and magnetic microparticle reagent manufacturing for autoimmune immunoassays. Recombinant human autoantigen supply draws from specialized biotechnology fermentation facilities; chemiluminescent substrate production rests on acridinium ester chemical synthesis. Single-source vulnerability concentrates in rare autoantigen cell lines held by limited biotechnology suppliers. Distribution runs through regional analyzer service hubs maintained by platform manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a regulatory-entrenchment defensive moat where EU IVDR clinical evidence mandates and FDA premarket notification pathways create structural barriers against unvalidated assay entrants.
For Market Incumbents: Compound installed base leverage through chemiluminescence menu expansion targeting connective tissue disease differentiation panels. Deepen backward integration into recombinant autoantigen production to neutralize batch-to-batch variability risks from concentrated biotechnology suppliers. Prioritize 510(k) submissions for biomarkers currently offered as laboratory-developed tests to compress competitive windows for reference laboratories. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 diagnostic center expansion under PLI scheme infrastructure incentives, where localized production cost advantages offset platform automation gaps. Target fluorescence-based multiplexed bead arrays for research-use panel development bridging toward clinical translation. Pursue academic medical center partnerships for biomarker validation data generation preceding regulatory submission. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with robust clinical data libraries capable of satisfying EU IVDR evidence mandates. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than pure technology differentiation. Target acquisition archetypes: specialized biotechnology suppliers with captive autoantigen production capabilities. Monitor FDA enforcement discretion framework evolution as inflection indicator for laboratory-developed test substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Certification Acceleration | Stricter clinical evidence mandates favor established manufacturers with existing data libraries over smaller entrants. |
| Chemiluminescence Menu Expansion | Broader autoimmune panels on automated platforms capture rheumatology referral volume from hospital networks. |
| Recombinant Autoantigen Backward Integration | In-house production of critical reagents reduces batch variability exposure from concentrated biotechnology suppliers. |
| India PLI Localization | Domestic manufacturing under production-linked incentives reduces kit costs for tier-2 and tier-3 diagnostic centers. |
| Digital Pathology Integration | Convergence with whole-slide imaging and AI scoring creates novel service models for lupus nephritis monitoring. |
Study Parameters
Desk research of FDA 510(k) filings, EU IVDR technical documentation, and hospital procurement databases preceded structured interviews with immunoassay platform engineers, rheumatology laboratory directors, and GPO contracts managers. Primary fieldwork with diagnostic reagent procurement specialists and regulatory affairs leads at autoimmune assay manufacturers was cross-validated against secondary sources including CDSCO import licensing records and CMS Medicare coverage determinations. Bottom-up test volume modeling and top-down market sizing were triangulated to produce segment-level outputs.
Variance decomposition across the projection horizon separates volume growth from pricing dynamics and technology mix shifts. Segmentation dimensions modeled include assay format, detection chemistry, end-user institution type, disease application, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and test volume intensity per rheumatology patient population. Forecast inputs incorporated chemiluminescence platform placement cycles and EU IVDR certification timeline assumptions.
Material uncertainties — regulatory enforcement discretion shifts, recombinant autoantigen supply interruptions, and laboratory-developed test substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about hospital consolidation trajectories and reimbursement stability that may require revision. Recalibration cycles align with material shifts in FDA guidance documents and EU IVDR implementing acts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Global Immunoassay Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
LDL Test Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
FISH Probe Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market