
 Point of Care (POC) CT Imaging Systems Market | 2026-2036
Point of Care (POC) CT Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care (POC) CT Imaging Systems Market Intelligence
The proliferation of decentralized care sites, including urgent care facilities and ambulatory surgical centers, is recalibrating the traditional buyer landscape once dominated by large hospital procurement departments. Samsung NeuroLogica specializes in mobile CT systems for neurological applications in intensive care units. Xoran Technologies focuses on compact cone beam CT systems for sinus and ear imaging in outpatient clinics. Carestream Health leverages its established brand in diagnostic imaging to offer portable solutions for diverse clinical settings.
Point of Care (POC) CT imaging systems are compact, often mobile devices designed for rapid diagnostic imaging at or near the patient's location. These systems typically feature a smaller gantry and utilize low-dose radiation protocols to provide immediate anatomical cross-sections, bypassing central radiology departments. Portable CT scanners and mobile systems constitute the largest product segments, driven by their flexibility. In terms of application, emergency care and surgical guidance represent the fastest-growing areas, demanding immediate, high-resolution imaging to inform critical decisions.
Market access depends on adherence to medical device regulations, such as 510(k) clearance from the US FDA and CE marking under the EU's MDR. In China, the NMPA enforces GB standards for radiation safety, shaping product design. Vendors must decide whether to pursue broad, multi-regional approvals or focus on dominating specific clinical applications within one jurisdiction.
Market Dynamics
The imperative to compress diagnostic timelines in acute care settings is the central force shaping the market. This pressure from emergency departments and intensive care units for immediate, on-site anatomical imaging is driving both technology development and regulatory fast-tracking for compact systems.
Growth Catalysts
- Regulatory Streamlining:Expedited device clearance pathways from regulators like the US FDA and the EU's Medical Device Regulation (MDR) are lowering barriers to entry and encouraging innovation in system design and low-dose protocols.
- Decentralized Care Expansion:The proliferation of ambulatory surgical centers and urgent care facilities creates new buyer segments outside of traditional large hospital procurement, particularly for specialized applications like sinus and ear imaging.
- Clinical Setting Specialization:Focused demand from high-volume clinical environments, such as sports medicine clinics in the United States and large hospital trauma centers in Germany, justifies the capital investment for dedicated POC systems.
Market Restraints
- High Acquisition Cost:The significant upfront capital expenditure for POC CT systems, compared to other portable imaging modalities like ultrasound, remains a substantial barrier for smaller clinics and facilities with constrained budgets.
- Image Resolution Trade-offs:While improving, the image quality and diagnostic scope of compact, low-dose systems can be inferior to that of full-size, fixed-gantry CT scanners, limiting their use for certain complex diagnostic assessments.
- Multi-Regional Regulatory Burden:Complying with disparate and stringent regulatory frameworks, such as the US FDA's 510(k) and China's NMPA GB standards for radiation safety, increases development costs and time-to-market.
Strategic Opportunities
- AI-Powered Diagnostics:Integrating artificial intelligence and machine learning algorithms directly onto the device for automated anomaly detection can enhance diagnostic speed and utility, creating a significant value-add for time-critical applications like mobile stroke units.
- Expansion into Veterinary Medicine:The growing sophistication of companion animal and equine medicine presents an underpenetrated market for specialized, portable CT systems designed for use in veterinary hospitals and mobile clinics.
- Targeted Geographic Expansion:Developing markets are building out modern healthcare infrastructure, offering opportunities for vendors to establish a foothold by providing systems tailored for new emergency care and outpatient facilities.
Industry Challenges
- Specialized Training Requirements:Effective operation requires clinicians and radiographers to be trained on new workflows outside of a central radiology department, creating a bottleneck related to workforce education and credentialing.
- Data Integration Complexity:Ensuring seamless connectivity and data transfer from POC CT scanners into diverse and often proprietary hospital Picture Archiving and Communication Systems (PACS) and EHR systems is a persistent technical hurdle.
- Radiation Dose Management:A key challenge is consistently ensuring and documenting adherence to low-dose radiation protocols across a distributed fleet of devices operated by various users, a focus of regulators like the NMPA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care (POC) CT Imaging Systems Market |
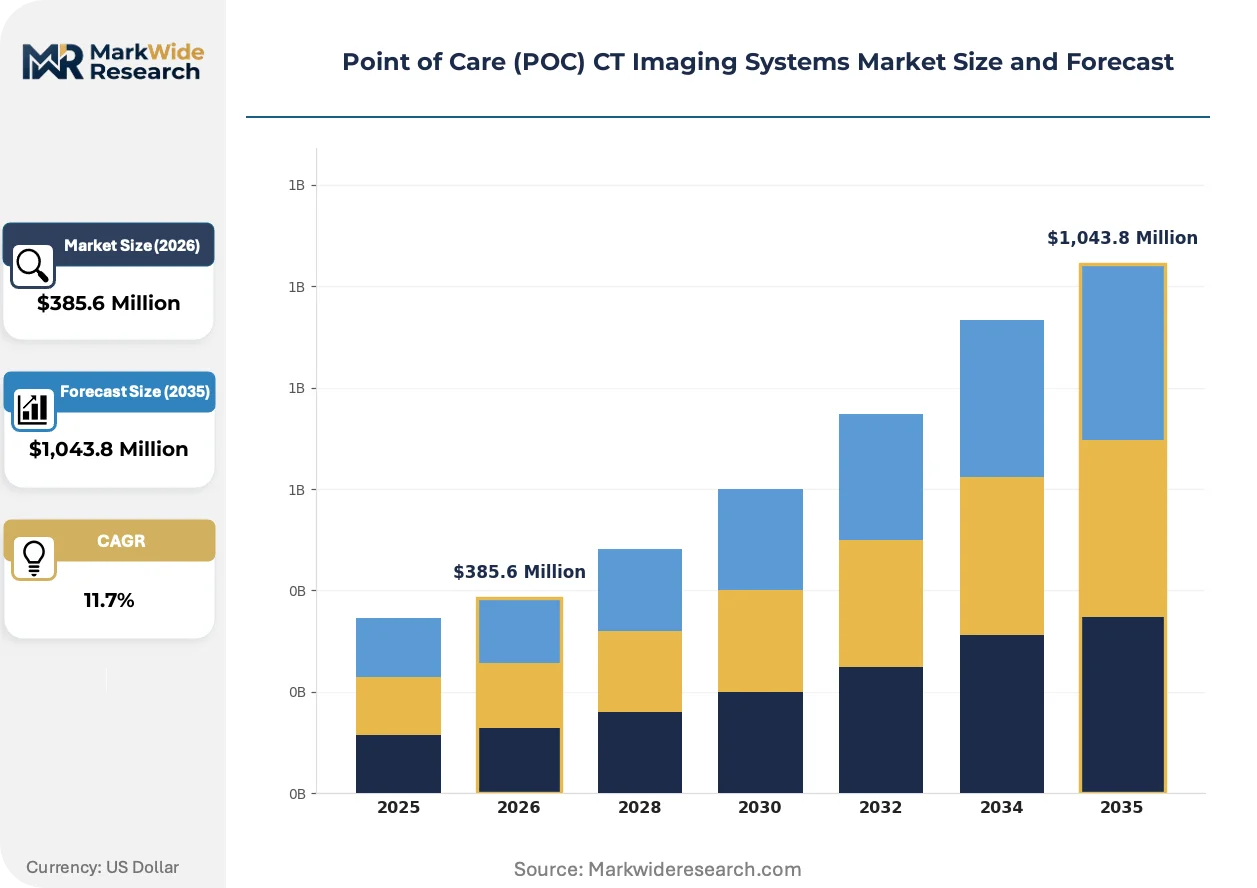
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,043.8 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable CT Scanners, Fixed CT Units, Mobile CT Systems, Compact CT Machines Technology: Helical CT, Cone Beam CT, Dual-Energy CT, Multislice CT Application: Emergency Care, Outpatient Clinics, Surgical Guidance, Trauma Assessment, Sports Injury Diagnosis End User: Ambulatory Surgical Centers, Diagnostic Imaging Centers, Urgent Care Facilities, Rehabilitation Centers |
| Companies Covered | Xoran Technologies, Samsung NeuroLogica, Carestream Health, CurveBeam, Planmed, Siemens Healthcare, Genoray, SCANCO Medical, KaVo Kerr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care (POC) CT Imaging Systems Market Strategic Shifts & Innovations
Intelligent automation and software-defined imaging are recalibrating the value proposition from hardware specifications to clinical workflow integration. This evolution prioritizes speed, diagnostic confidence at the point of care, and seamless data flow into hospital information systems.
Artificial intelligence-powered image reconstruction algorithms enhance clarity from low-dose radiation scans. Emergency departments and neurological ICUs are rapidly adopting this technology. This software-centric approach is absorbing traditional hardware limitations on image quality, allowing smaller systems to perform tasks once exclusive to high-end, fixed scanners.
Regulatory pathways like the US FDA’s 510(k) clearance process influence product development by prioritizing substantial equivalence. This framework encourages iterative enhancements, providing a faster route to market. Consequently, vendors focus on improving mobility and low-dose protocols for applications like sinus imaging to gain clearance.
Purchasing authority is decentralizing from hospital capital committees to department heads in emergency medicine and ICUs. This shift favors direct sales models over channels reliant on group purchasing organizations. This pattern is most visible within specialized sports medicine clinics in the United States, which have significant budget autonomy.
Point of Care (POC) CT Imaging Systems Market Segmentation
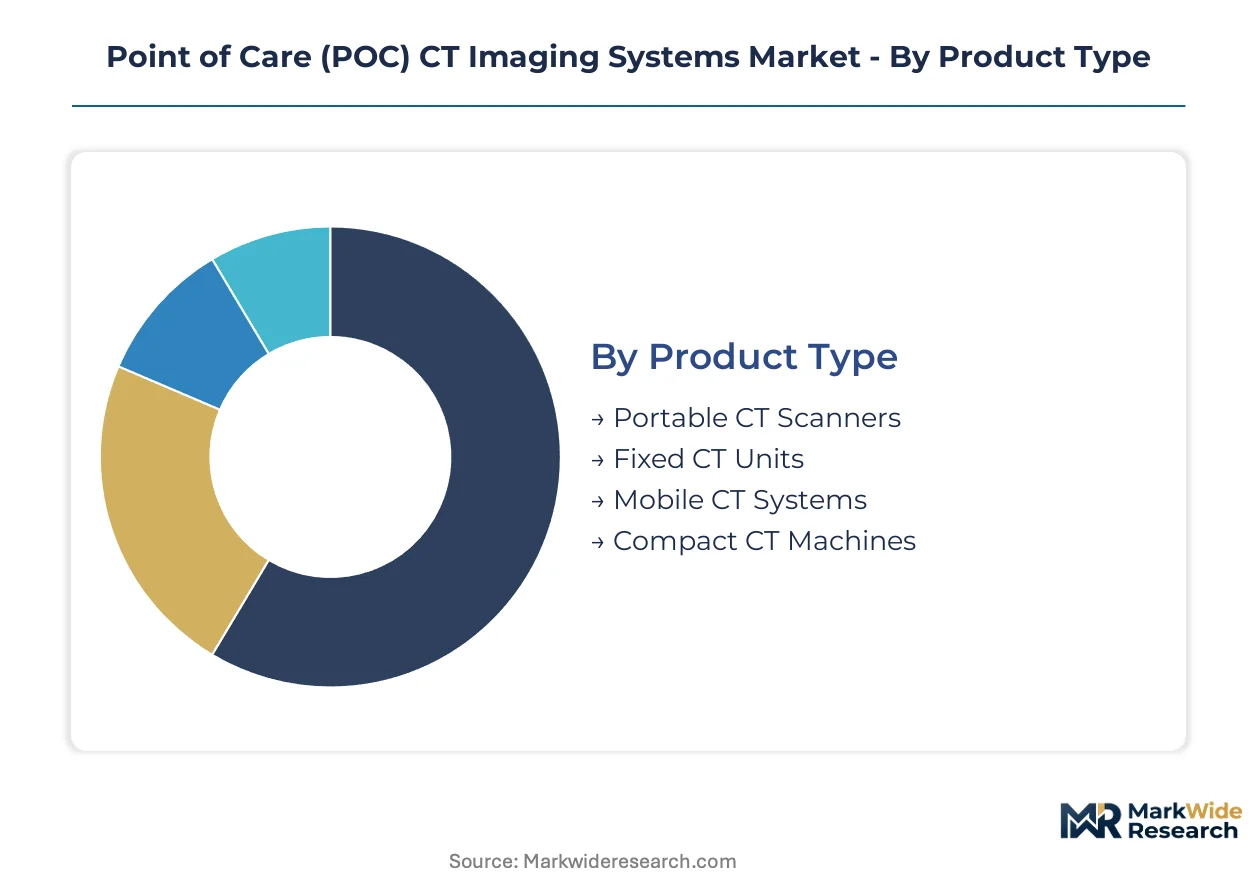
The Point of Care (POC) CT imaging systems market divides into distinct categories reflecting diverse operational needs and clinical requirements. Understanding these segments helps vendors tailor device specifications and market entry strategies. This segmentation highlights where innovation and demand currently concentrate within the diagnostic imaging landscape.
Product Type:
The product type segment spans highly standardized compact units to more customized mobile solutions, reflecting a spectrum from broad utility to specialized deployment.
- Portable CT Scanners:These compact, often wheeled devices are designed for easy movement within a facility, enabling imaging directly at the patient's bedside. Demand concentrates within intensive care units and emergency departments, driven by the imperative for immediate neurological assessment.
- Fixed CT Units:These systems are permanently installed in a dedicated imaging room, offering robust performance for high-volume diagnostic centers.
- Mobile CT Systems:These self-contained units are typically vehicle-mounted, bringing advanced imaging capabilities directly to remote locations or during inter-hospital transfers. Demand is concentrating within mobile stroke units and trauma response teams, driven by the need for on-scene diagnostic speed.
- Compact CT Machines:These smaller footprint devices are optimized for specific anatomical regions, often integrating into outpatient clinic workflows.
Leading the category by volume: Portable CT Scanners. Growing fastest: Mobile CT Systems.
Technology:
Technology segmentation reveals how different scanning methodologies are optimized for specific clinical applications, influencing image quality and radiation dose protocols.
- Helical CT:This established technology uses a continuous spiral acquisition path, generating detailed cross-sectional images for a wide range of diagnostic purposes. The technique finds widespread use in general radiology departments due to its versatility and established protocols.
- Cone Beam CT:This technology utilizes a cone-shaped X-ray beam to capture a large volume of data in a single rotation, providing high-resolution 3D images of small anatomical structures. Demand is concentrating within dental and ENT clinics in the United States, driven by precise imaging requirements for sinus and ear applications.
- Dual-Energy CT:This advanced method employs two different X-ray energies simultaneously, allowing for material differentiation and improved contrast resolution.
- Multislice CT:This technology uses multiple detector rows to acquire several slices simultaneously, significantly reducing scan times and improving throughput.
Primary demand driver for this segment is the need for enhanced diagnostic specificity across diverse clinical scenarios.
Application:
Application categories reflect the diverse clinical environments where immediate diagnostic imaging profoundly impacts patient management and treatment outcomes, varying by volume and criticality.
- Emergency Care:This segment encompasses rapid diagnostic imaging in emergency departments and trauma centers, where immediate assessment of acute conditions is paramount. Demand is concentrating within large hospital networks in Germany, driven by the need for quick decision-making in trauma assessment.
- Outpatient Clinics:These facilities utilize POC CT for routine diagnostics and follow-up, offering convenience and reducing patient wait times.
- Surgical Guidance:This application involves real-time imaging during surgical procedures to enhance precision and confirm device placement or resection margins. This segment is expanding rapidly in neurosurgery and orthopedic procedures, driven by the reduction in revision surgeries and improved patient safety.
- Trauma Assessment:Focused imaging for injuries resulting from accidents or impacts, requiring rapid and accurate identification of internal damage.
- Sports Injury Diagnosis:Specialized imaging for musculoskeletal injuries prevalent in athletes, aiding in precise diagnosis and rehabilitation planning.
The segment with the steepest expansion trajectory is Surgical Guidance, while Emergency Care accounts for significant established demand.
End User:
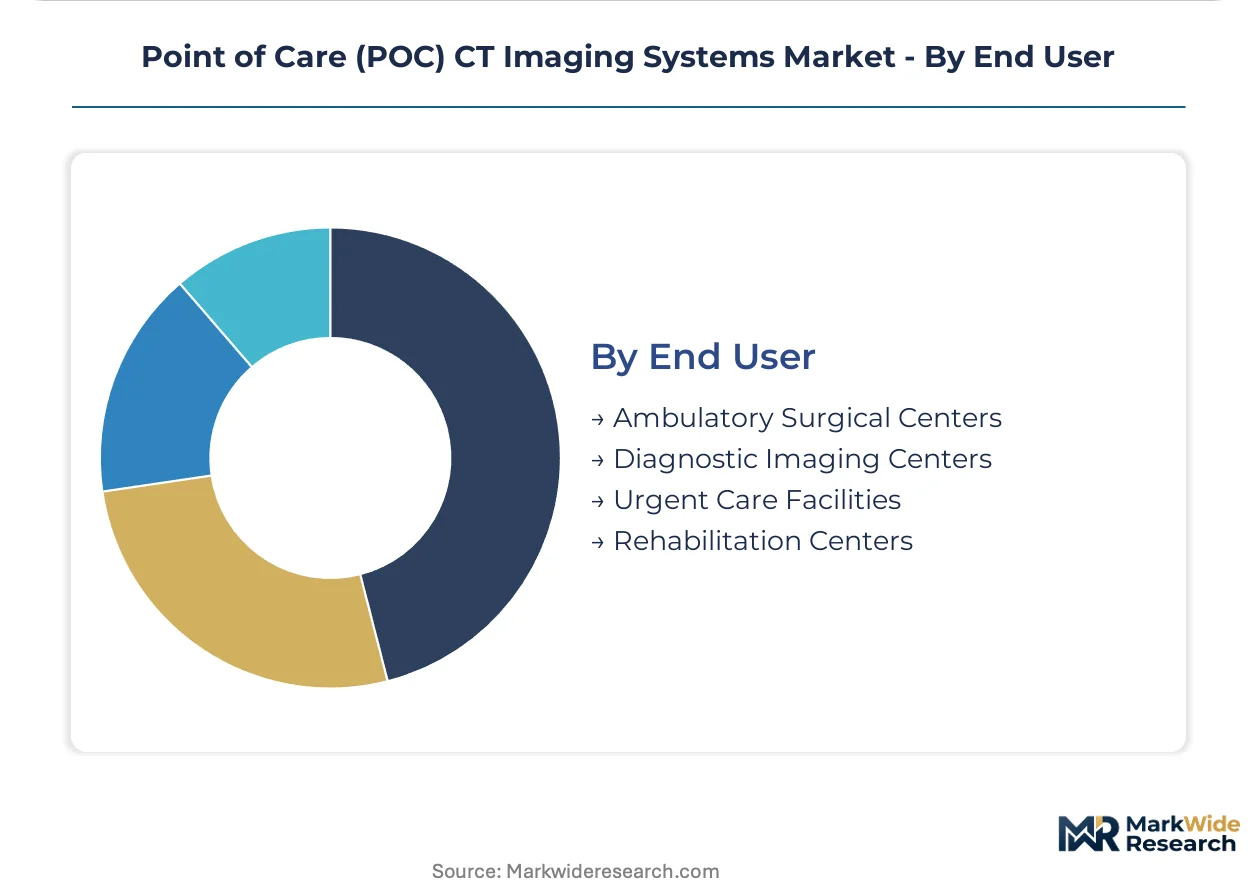
End user segmentation reveals evolving procurement patterns and facility-specific needs, moving beyond traditional hospital departments to a broader range of healthcare providers.
- Ambulatory Surgical Centers:These facilities perform same-day surgical procedures, requiring compact and efficient imaging solutions to support pre-operative planning and intra-operative guidance. This segment is expanding due to cost efficiencies and patient preference for specialized outpatient care.
- Diagnostic Imaging Centers:Dedicated facilities offering a full suite of imaging services, integrating POC CT for specific niche applications or patient comfort.
- Urgent Care Facilities:These clinics address immediate but non-life-threatening conditions, utilizing POC CT for rapid diagnosis of fractures or minor head injuries. Demand is concentrating in metropolitan areas of the United States, driven by patient convenience and reduced emergency room wait times.
- Rehabilitation Centers:These centers provide post-acute care, potentially using POC CT for monitoring recovery or assessing complications in specific cases.
New buyer segments are emerging within Ambulatory Surgical Centers and Urgent Care Facilities, diversifying the market beyond traditional hospital procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for Point of Care (POC) CT imaging systems is particularly strong within large hospital networks in Germany and specialized sports medicine clinics across the United States. This regional focus reflects specific clinical needs and established healthcare infrastructure. The drive for immediate diagnostic insights at the patient's location shapes procurement priorities across diverse geographies.
United States
The United States market exhibits significant demand from specialized sports medicine clinics and urgent care facilities, driven by the need for rapid musculoskeletal and minor trauma imaging. Regulatory pathways such as the US FDA's 510(k) clearance encourage innovation in compact, low-dose systems. Metropolitan areas, particularly those with high patient traffic for urgent care, are seeing increased deployment of these convenient diagnostic tools.
Germany
Germany represents a robust market for POC CT systems, primarily within large hospital networks and trauma centers requiring immediate assessment capabilities. Compliance with the EU's Medical Device Regulation (MDR) ensures high safety and performance standards for devices entering this market. Major urban centers like Munich and Berlin are focal points for advanced medical technology adoption in emergency departments.
China
China's expanding healthcare infrastructure is creating substantial opportunities for POC CT systems, especially in new emergency care and outpatient facilities. The NMPA enforces stringent GB standards for radiation safety, influencing product design and market entry strategies. The Yangtze River Delta region is witnessing significant investment in medical device manufacturing and the adoption of advanced diagnostic equipment.
Japan
Japan's healthcare sector demonstrates consistent demand for high-efficiency diagnostic tools, driven by an aging population and a focus on precision medicine. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical device approvals, emphasizing product quality and clinical utility. The Kanto region, including Tokyo, remains a hub for medical technology innovation and the early adoption of compact imaging solutions in clinics.
Point of Care (POC) CT Imaging Systems Market Key Industry Players
United States producers anchor one tier of the market, focusing on specialized applications and rapid regulatory navigation, while European specialists hold strong positions in established hospital networks. The market structure is characterized by a mix of large, diversified imaging companies and agile innovators targeting niche clinical applications. Competitive moves include strategic partnerships to integrate AI-powered diagnostics and portfolio diversification into new clinical settings.
Specialists in compact and mobile solutions, such as Samsung NeuroLogica and Xoran Technologies, exemplify focused innovation within specific clinical applications. Samsung NeuroLogica, for instance, occupies a position in mobile CT systems for neurological applications in intensive care units. Xoran Technologies represents the archetype of a company developing compact cone beam CT systems for sinus and ear imaging in outpatient clinics. Siemens Healthcare, a global medical technology leader, anchors the segment of large, diversified players offering comprehensive imaging portfolios that include portable options.
| Leading Market Players |
|---|
| Xoran Technologies |
| Samsung NeuroLogica |
| Carestream Health |
| CurveBeam |
| Planmed |
| Siemens Healthcare |
| Genoray |
| SCANCO Medical |
| KaVo Kerr |
Cost & Logistics Intelligence
Detector array component costs directly influence the manufacturing expense of Point of Care CT systems. This cost structure then cascades into differentiated pricing tiers for portable, mobile, and compact units.
Pricing Analysis
The market exhibits a volume-versus-margin split, with high-volume portable systems for emergency care often priced competitively to drive adoption. Pricing stratifies across premium, standard, and economy tiers, driven by factors like FDA/CE certification level and bundled after-sales service agreements. Pricing softness stems from increasing competition and the regulatory push for cost-effectiveness in healthcare procurement. Smaller clinics and urgent care facilities demonstrate the highest price sensitivity, while large hospital networks prioritize clinical utility over marginal cost savings for critical applications.
Supply Chain Analysis
Workforce availability for precision manufacturing in Germany and the United States underpins the supply chain for advanced POC CT systems. Key component dependencies include specialized X-ray tubes, high-resolution detector arrays, and proprietary software modules. Single-source vulnerability for advanced imaging components represents a structural risk within this market. Distribution runs through direct sales models, with manufacturers engaging directly with hospital departments and specialized outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for Point of Care CT systems is becoming a vertical-integration race. Companies are pursuing in-house software development for AI-powered diagnostics to control the value chain.
For Market Incumbents: To counter emerging agile innovators in niche applications, large players should consolidate market share through strategic acquisitions of specialized software firms. Investing heavily in R&D for low-dose protocols and AI integration enhances diagnostic capabilities. Leveraging expedited regulatory pathways, such as US FDA 510(k) clearance, accelerates market access for advanced systems. Expanding after-sales service networks reinforces customer loyalty and provides recurring revenue streams.
For New Entrants and Emerging Players: A price-point gap exists between high-end systems and cost-effective solutions for specialized outpatient clinics. Target underpenetrated segments like sports medicine clinics and ENT practices with compact, purpose-built systems. Developing markets, particularly in China's expanding healthcare infrastructure, offer opportunities for tailored, budget-conscious solutions. A go-to-market angle focusing on user-friendly interfaces and integrated workflow solutions can create differentiation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in the United States and Germany, particularly those with strong intellectual property in AI. Point of Care CT systems offer long-term value due to persistent demand for rapid, decentralized diagnostics. Acquisition targets should possess robust regulatory compliance records and established clinical adoption in specific applications. The signal to watch is regulatory fast-tracking for specific clinical indications, indicating market readiness for new technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Integration | Enhances diagnostic speed and reduces operator dependency for rapid clinical decisions. |
| Regulatory Pathway Acceleration | Expedites market access for innovative low-dose systems across key geographies. |
| Geographic Footprint Expansion | Captures demand from modernizing healthcare infrastructure in China and other developing regions. |
| Specialized Application Development | Addresses unmet needs in sports medicine and ENT clinics with tailored imaging solutions. |
| Direct Sales Channel Optimization | Improves customer engagement and after-sales support for end-users in diverse settings. |
Research Approach
US FDA 510(k) clearances, EU MDR compliance documents, and NMPA GB standards formed the secondary backbone of this analysis. Primary research involved in-depth interviews with radiologists, emergency physicians, medical device engineers, and hospital procurement managers. This approach ensured comprehensive data triangulation, combining bottom-up market sizing with top-down validation from industry experts.
A combined bottom-up and top-down analytical lens was applied to construct the forecast framework across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from historical trends, market drivers, and expert projections. Key industry-specific forecast inputs included healthcare infrastructure investment rates and medical device regulatory approval timelines.
Inputs from publicly available financial reports and regulatory databases were available through the study window; gaps in proprietary clinical trial data and specific pricing agreements introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and healthcare policy stability. Unforeseen technological breakthroughs or major shifts in healthcare reimbursement policies are risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Australia Mammography Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Gallium-68 Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
South America Digital X-Ray Devices Market