
 Diagnostic Imaging Markers Market | 2026-2036
Diagnostic Imaging Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Imaging Markers Market Outlook
Hospital procurement consolidation is shifting purchasing power toward integrated health networks and large IDNs that negotiate enterprise-wide imaging contracts. Siemens Healthineers leverages its installed base of MRI and CT platforms to bundle marker-compatible software and hardware solutions. GE Healthcare anchors its position through deep backward integration into contrast agent manufacturing and AI-enhanced reconstruction algorithms. Philips competes by specializing in hybrid imaging configurations that combine PET-CT and PET-MRI markers for oncology workflows.
Diagnostic imaging markers comprise contrast agents, radiotracers, and calibration phantoms formulated with specific atomic numbers, relaxation times, or radionuclide half-lives to enhance tissue differentiation and quantification accuracy in medical imaging systems. These markers function by altering local magnetic fields, attenuating X-ray beams, or emitting detectable gamma radiation to improve diagnostic specificity across modalities. Digital imaging technology leads the technology segment due to its integration with PACS and AI-assisted interpretation platforms, while 3D imaging represents the fastest-growing category as surgical planning and interventional radiology demand volumetric marker visualization. Among applications, oncology occupies the largest margin pool because tracer-based theranostics commands premium pricing and recurring consumption.
The FDA oversees marker safety through 510(k) clearance and PMA pathways for novel radiopharmaceuticals, while the EMA's MDR and REACH frameworks govern CE-marked products in Europe. ISO 13485 quality management standards and NMPA registration requirements in China further shape market access conditions for multinational suppliers. Stakeholders must monitor evolving regulatory divergence between FDA's Q-Sub pre-submission process and EMA's clinical evidence expectations for software-as-a-medical-device integrations.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and elevating enterprise contract value thresholds, forcing marker suppliers to bundle software, hardware, and consumables into multi-year service agreements rather than transactional sales.
Growth Catalysts
- FDA 510(k) Modernization:The FDA's tightened predicate device requirements are accelerating innovation cycles as manufacturers develop novel marker formulations rather than relying on historical clearances. Radiology departments in integrated delivery networks now prioritize markers with AI-compatible quantification features.
- Theranostics Expansion:Oncology workflows are consuming radiotracers at expanding volumes as precision medicine protocols mandate paired diagnostic and therapeutic isotope applications. Academic medical centers are building captive cyclotron facilities to secure supply.
- China NMPA Registration Streamlining:China's accelerated review pathways for innovative medical devices are shortening market access timelines for multinational contrast agent suppliers. Domestic imaging equipment manufacturers are specifying imported marker compatibility.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production concentrates in aging research reactors in Canada, the Netherlands, and South Africa, creating single-point-of-failure risks for technetium-based cardiac and bone imaging.
- Gadolinium Retention Liability:The EMA's PRAC restrictions on linear gadolinium-based contrast agents have forced formulation switches that elevate manufacturing costs and complicate inventory management for hospital pharmacies.
- Fluorine-18 Half-Life Constraints:The 110-minute radioactive decay window for PET tracers necessitates distributed cyclotron networks or expensive air freight logistics, limiting marker availability in rural and secondary markets.
Strategic Opportunities
- India Diagnostic Infrastructure:India's PLI scheme for medical devices is incentivizing local manufacturing of CT and MRI contrast media to substitute imports. Private hospital chains in Mumbai, Delhi, and Bangalore are upgrading to 3T MRI platforms requiring advanced markers.
- AI-Assisted Quantification:Machine learning algorithms trained on standardized phantom data are creating demand for calibration markers with embedded traceable reference values. PACS vendors are certifying specific marker brands for automated volumetric analysis.
- Hybrid Imaging Standardization:PET-CT and PET-MRI fusion protocols are driving adoption of dual-modality phantoms that validate spatial registration accuracy across combined systems. Equipment manufacturers are co-developing proprietary marker sets.
Industry Challenges
- Radiopharmaceutical Talent Scarcity:Cyclotron operation and radiochemistry synthesis require specialized certification that outpaces training program output. Nuclear medicine departments compete for licensed personnel against higher-paying therapeutic radiopharmaceutical manufacturers.
- Legacy PACS Integration Friction:New AI-enhanced marker quantification software requires DICOM standard updates that conflict with decade-old hospital archiving systems. IT departments face extended validation timelines for security patches.
- Supply Chain Cold Chain Integrity:Temperature excursions during radiotracer transport invalidate batch potency, yet real-time monitoring adoption remains uneven across third-party logistics providers serving regional hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Imaging Markers Market |
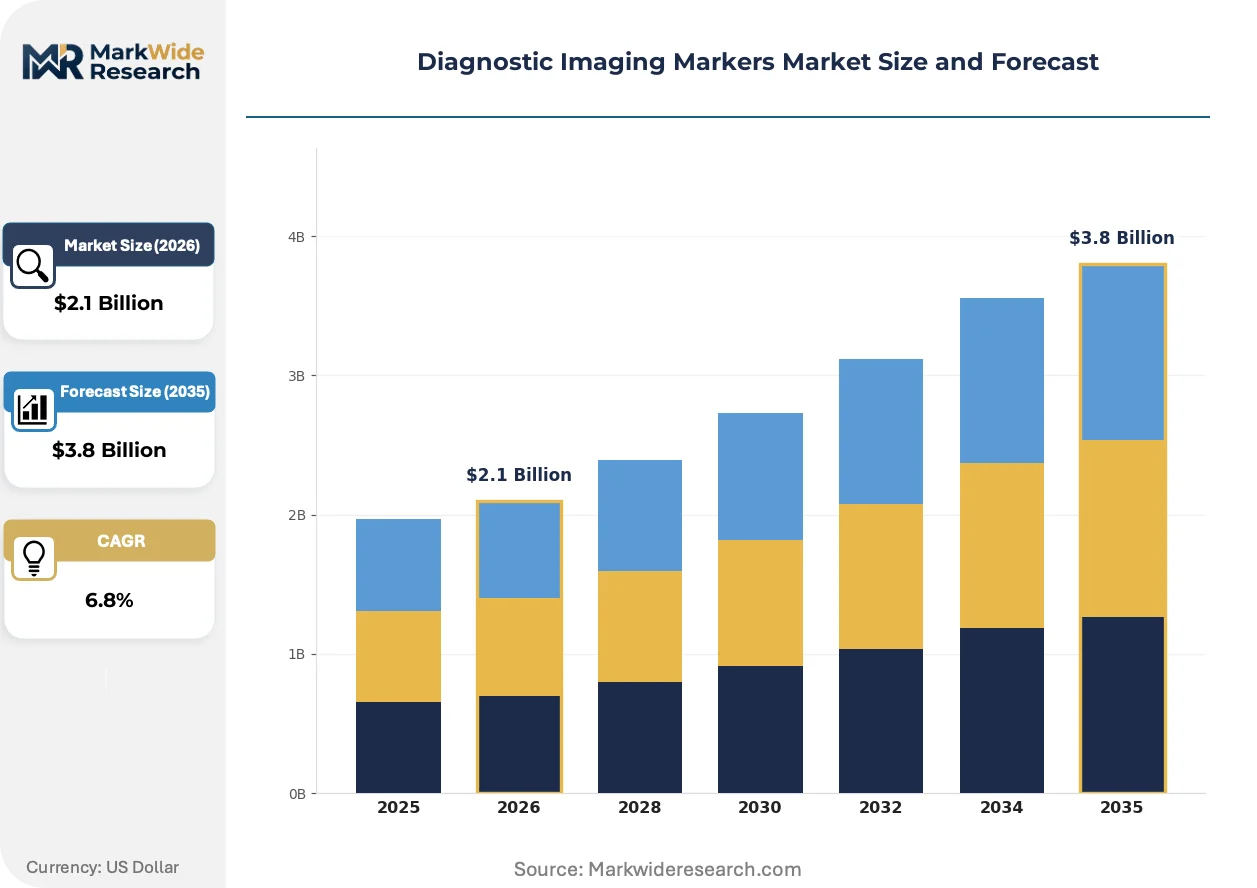
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, Ultrasound, CT Scan Technology: Digital Imaging, Analog Imaging, Hybrid Imaging, 3D Imaging End User: Hospitals, Imaging Centers, Diagnostic Laboratories, Research Institutions Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Fujifilm Holdings Corporation, Canon Medical Systems, Hologic, Shimadzu Corporation, Samsung Medison, Mindray Medical International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Imaging Markers Market Strategic Shifts
Artificial intelligence is penetrating marker development and deployment workflows, compressing validation cycles and enabling real-time quality assurance that was previously manual and retrospective.
Deep learning reconstruction algorithms are automating noise reduction in low-dose CT protocols, allowing reduced iodine contrast volumes without sacrificing image quality. Community hospitals with budget-constrained CT fleets are adopting these algorithms fastest, as they extend equipment service life and lower per-procedure pharmaceutical costs. The technology is automating technologist workflow standardization across shift changes and training levels.
The FDA's Q-Sub pre-submission process is formalizing software-as-a-medical-device boundaries for AI-integrated marker analysis tools, creating clearer regulatory pathways but lengthening initial consultation phases. Device manufacturers are restructuring quality management systems to accommodate continuous learning algorithm updates under ISO 13485 change control. Radiology groups in the United States are prioritizing 510(k) cleared AI tools over laboratory-developed algorithms to mitigate malpractice exposure.
Integrated health networks are consolidating contrast agent purchasing through pharmaceutical benefit managers rather than radiology department autonomy, compressing formulary diversity and elevating price transparency requirements. Hospital systems in Texas, Florida, and Ohio have moved to single-source contracts with rebate structures tied to volume commitments and outcome metrics. This consolidation is most visible in cardiology departments where stable coronary artery disease imaging protocols standardize across entire networks.
Diagnostic Imaging Markers Market Segmentation
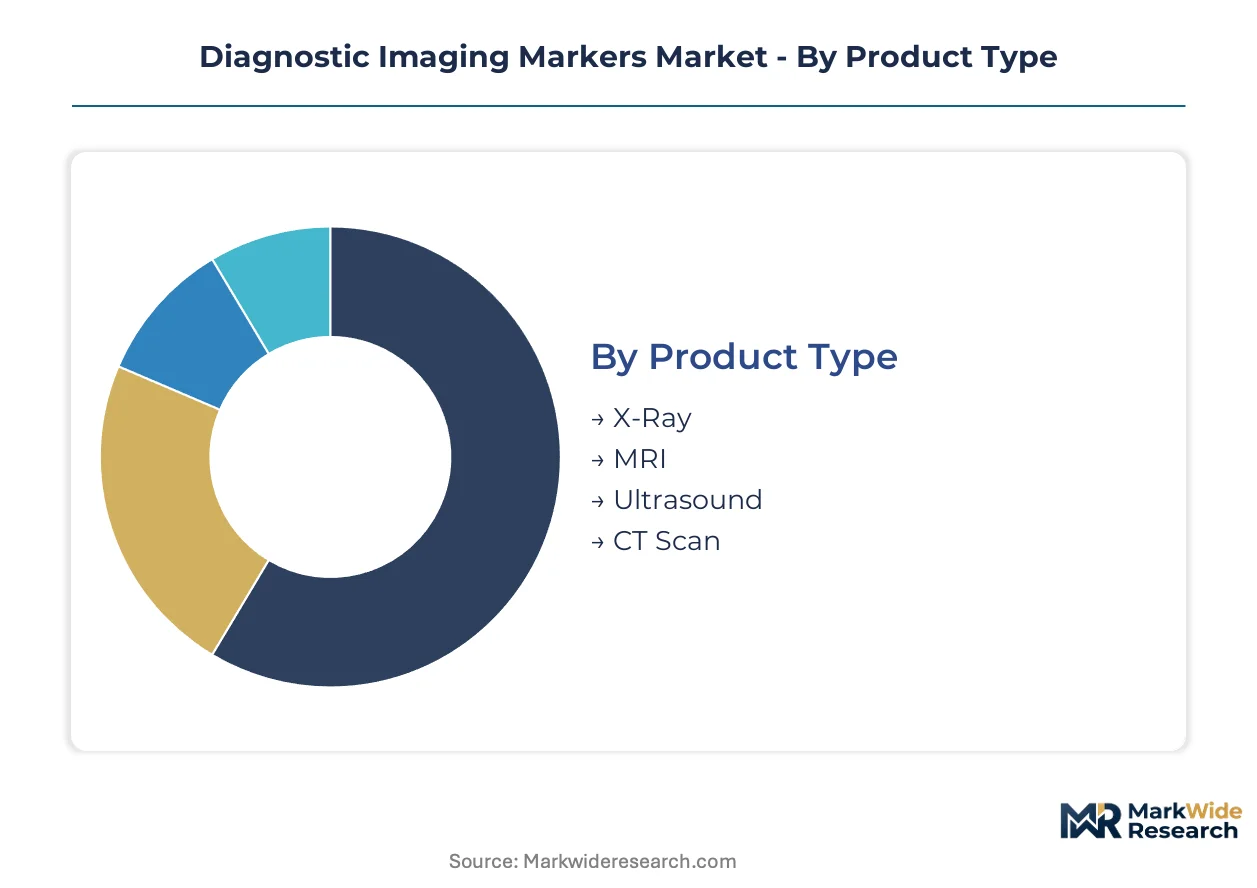
Imaging markers serve fundamentally different technical requirements across modalities, with capital requirements and regulatory pathways varying dramatically by product category. Technology choices determine integration complexity with PACS and AI platforms. End-user concentration shapes procurement dynamics and service contract structures.
Product Type:
Capital intensity peaks with MRI marker production, where superconducting magnet compatibility and specialized synthesis cleanrooms demand substantial upfront investment.
- MRI:Gadolinium-based and iron oxide formulations require GMP-certified facilities with controlled metal contamination protocols. Demand concentrates in academic medical centers and tertiary hospitals in the United States running 3T platforms, constrained by EMA PRAC retention liability rulings that forced formulation switches.
- CT Scan:Iodinated contrast agents dominate procedural volumes globally. High-volume iodine extraction and organic synthesis infrastructure create barriers to entry. Community hospital networks in Texas and Florida negotiate enterprise contracts through pharmaceutical benefit managers, compressing formulary diversity.
- X-Ray:Barium sulfate suspensions for gastrointestinal studies represent mature, cost-optimized manufacturing with minimal regulatory friction.
- Ultrasound:Microbubble contrast agents for echocardiography require specialized lipid shell engineering and controlled cavitation testing.
Most installed capacity flows through CT Scan. Expansion is steepest in MRI.
Technology:
Digital infrastructure requirements separate segments by IT integration costs and software validation burdens.
- Digital Imaging:PACS-native markers with embedded DICOM metadata enable automated workflow routing and AI-assisted interpretation. Radiology departments in integrated delivery networks prioritize FDA 510(k) cleared quantification tools to mitigate malpractice exposure.
- 3D Imaging:Volumetric visualization for surgical planning and interventional radiology demands phantom calibration with traceable reference geometries. Hybrid OR installations in Mumbai and Bangalore drive adoption as Indian hospital chains upgrade infrastructure.
- Hybrid Imaging:PET-CT and PET-MRI fusion protocols require dual-modality phantoms validating spatial registration accuracy.
- Analog Imaging:Legacy film-based systems persist in resource-constrained settings with minimal marker innovation.
Procurement volume concentrates in Digital Imaging. 3D Imaging climbs the fastest.
End User:
Customer scale determines contract structure, with large IDNs extracting multi-year service bundles versus transactional laboratory purchasing.
- Hospitals:Enterprise-wide imaging contracts bundle hardware, software, and consumables through centralized procurement. Consolidated networks in Ohio and Pennsylvania have moved to single-source agreements with rebate structures tied to volume commitments.
- Imaging Centers:Outpatient facilities prioritize throughput optimization and standardized protocols across shift changes. AI-enhanced reconstruction algorithms extend equipment service life for budget-constrained CT fleets.
- Diagnostic Laboratories:Reference labs concentrate on high-complexity send-out testing with specialized radiochemistry capabilities.
- Research Institutions:Academic medical centers build captive cyclotron facilities to secure isotope supply for theranostics development.
Contract value concentrates in Hospitals. Imaging Centers gain share fastest.
Application:
Clinical workflow complexity and reimbursement levels create tiered margin structures across therapeutic areas.
- Oncology:Radiotracer-based theranostics commands premium pricing with recurring consumption patterns. Paired diagnostic and therapeutic isotope applications mandate precision medicine protocols at academic centers.
- Cardiology:Stable coronary artery disease imaging protocols have standardized across entire networks, enabling volume aggregation. Technetium-99m dependency creates supply vulnerability from aging research reactors in Canada and the Netherlands.
- Neurology:Blood-brain barrier permeability markers require specialized formulation expertise with limited supplier base.
- Orthopedics:Joint imaging markers compete on cost efficiency with mature, commoditized supply chains.
Revenue concentration sits in Oncology. Neurology shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates contrast agent manufacturing infrastructure while the United States dominates theranostics consumption and cyclotron deployment. Japan maintains specialized MRI marker formulation capabilities. India's domestic production incentives are reshaping procurement patterns for iodinated agents.
United States
Academic medical centers in Boston and Houston are building captive cyclotron facilities to secure isotope supply chains for precision oncology protocols. Medicare reimbursement policies heavily influence adoption rates for advanced diagnostic modalities through coverage determinations. The FDA's 510(k) modernization initiative tightens predicate device requirements, accelerating innovation cycles in radiotracer development.
Germany
Specialized GMP-certified facilities in Bavaria and North Rhine-Westphalia produce gadolinium-based formulations under EMA PRAC retention liability frameworks. The EMA's MDR and REACH frameworks govern CE-marked product distribution across European markets. Siemens Healthineers leverages its Erlangen headquarters to bundle marker-compatible software with MRI platform sales.
China
Domestic imaging equipment manufacturers in Shenzhen and Beijing are specifying imported marker compatibility as hospital procurement scales. The NMPA's accelerated review pathways for innovative medical devices shorten market access timelines for multinational contrast agent suppliers. Shanghai's radiochemistry clusters are expanding fluorine-18 production capacity for PET tracer distribution.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are upgrading to 3T MRI platforms requiring advanced gadolinium formulations. The PLI scheme for medical devices incentivizes local manufacturing of CT and MRI contrast media to substitute imports. Domestic production of iodinated agents is concentrating in Gujarat and Maharashtra pharmaceutical corridors.
Japan
PMDA oversight maintains stringent quality standards for microbubble contrast agents used in echocardiography protocols. The country's aging demographic drives demand for cardiac and neurological imaging markers through expanded screening programs. Tokyo and Osaka academic centers specialize in blood-brain barrier permeability marker research for neurodegenerative disease applications.
Diagnostic Imaging Markers Market Competitive Environment
German and Dutch producers anchor one tier of integrated imaging systems; Japanese and South Korean specialists hold positions in component-level marker technologies. The vendor base organizes around three strategic archetypes: diversified healthcare conglomerates bundling hardware-software-consumable ecosystems, pure-play contrast agent manufacturers with GMP-certified synthesis infrastructure, and radiopharmaceutical specialists operating captive cyclotron networks. Consolidation pressures favor multi-year service agreements over transactional sales, while AI-enhanced quantification features differentiate premium offerings.
Within the diversified systems tier, Siemens Healthineers and GE Healthcare exemplify backward integration into contrast agent manufacturing and AI-enhanced reconstruction algorithms. Koninklijke Philips NV occupies a position specializing in hybrid imaging configurations. These three anchors represent contrasting geographic origins—German, American, and Dutch respectively—each leveraging distinct regulatory relationships with the FDA, EMA, and national competent authorities.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Fujifilm Holdings Corporation |
| Canon Medical Systems |
| Hologic |
| Shimadzu Corporation |
| Samsung Medison |
| Mindray Medical International |
| Others |
Value Chain & Pricing Dynamics
Gadolinium and iodine feedstock costs cascade through three pricing tiers before reaching hospital formularies, with EMA PRAC-mandated formulation switches compressing margins at the premium tier while volume aggregation through pharmaceutical benefit managers flattens price curves for standard CT agents.
Pricing Analysis
Capacity additions in India are reshaping price floors for iodinated contrast agents as PLI-subsidized domestic production undercuts imported standard-grade inventory. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified MRI formulations from hospital-label CT agents and commodity barium suspensions. Cost compression in the standard tier is intensifying because integrated health networks in Texas and Florida have consolidated to single-source contracts with rebate structures tied to volume commitments. Community hospital networks exhibit the highest price sensitivity, while academic medical centers running 3T MRI platforms prioritize AI-compatible quantification features over unit cost.
Supply Chain Analysis
ISO 13485 certification and FDA 510(k) clearance gates filter supplier participation, with GMP facility qualification timelines extending onboarding for new entrants. Manufacturing concentrates in Germany, the United States, and China, with Bavaria hosting specialized gadolinium synthesis infrastructure and Shanghai expanding fluorine-18 production capacity. Raw material supply draws from Canadian and Dutch research reactors for molybdenum-99, iodine extraction from Chilean caliche deposits, and gadolinium oxide from Chinese rare earth processing. Single-source vulnerability in the technetium-99m supply chain creates acute disruption risk from aging reactor maintenance schedules. Distribution runs through pharmaceutical benefit managers serving integrated delivery networks, with cold chain logistics providers managing radiotracer potency validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic imaging markers market functions as a regulatory compounder where FDA 510(k) modernization and EMA PRAC retention liability rulings continuously reset compliance baselines, forcing recurring reinvestment in formulation redevelopment and quality management system upgrades.
For Market Incumbents: Anchor market position through backward integration into cyclotron networks and GMP-certified synthesis infrastructure, securing isotope supply against production reactor vulnerabilities. Deepen software-hardware-consumable bundling to defend against pure-play contrast agent manufacturers gaining share through price aggression. Prioritize AI-enhanced quantification certification under FDA Q-Sub pathways to differentiate premium offerings as radiology departments seek malpractice exposure mitigation.
For New Entrants and Emerging Players: Contract research organizations and regional distributors offer partnership pathways to bypass incumbent-controlled hospital formulary gates. India's domestic production incentives under the PLI scheme present the most penetrable geography, with Gujarat and Maharashtra pharmaceutical corridors lacking sufficient GMP-certified MRI marker capacity. Pursue co-development agreements with domestic imaging equipment manufacturers in Shenzhen and Beijing seeking imported marker compatibility specifications.
For Investors and Strategic Acquirers: Consolidation pressure builds where radiopharmaceutical talent scarcity constrains cyclotron operation scaling and specialized radiochemistry synthesis capacity. Long-term viability favors vertically integrated platforms spanning contrast agent manufacturing, AI software certification, and captive isotope production rather than pure-play formulation specialists. Acquisition targets should demonstrate ISO 13485 quality management systems with validated change control processes for continuous learning algorithm updates. The signal to monitor is NMPA registration timeline compression for innovative medical devices, which would accelerate multinational market access and reshape competitive positioning in China's expanding hospital procurement market.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cyclotron Facility Buildout | Academic medical centers in Boston and Houston secure isotope supply chains against aging Canadian and Dutch reactor vulnerabilities. |
| FDA Q-Sub Pre-Submission Investment | Device manufacturers formalize software-as-a-medical-device boundaries for AI-integrated marker analysis tools under 510(k) modernization. |
| India PLI Scheme Manufacturing Entry | Domestic production of iodinated agents concentrates in Gujarat and Maharashtra corridors to substitute import dependency. |
| Hybrid Imaging Phantom Co-Development | Equipment manufacturers validate spatial registration accuracy across PET-CT and PET-MRI fusion protocols with proprietary marker sets. |
| AI-Enhanced Reconstruction Algorithm Certification | PACS vendors certify specific marker brands for automated volumetric analysis, creating workflow lock-in for radiology departments. |
Study Parameters
Multiple input streams — primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts directors; secondary validation through FDA 510(k) filings, EMA MDR submissions, and hospital procurement databases; and trade data from customs records — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Data-stream reconciliation applied across the projection horizon modeled technology adoption curves by product type, end-user concentration, and application workflow complexity. CAGRs were derived from installed base expansion rates, procedure volume growth, and reimbursement policy trajectories. Industry-specific forecast inputs incorporated Medicare coverage determination timelines, NMPA accelerated review pathway utilization, and cyclotron facility deployment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to isotope supply disruptions from research reactor decommissioning schedules and EMA regulatory divergence on gadolinium retention liability. Forecasts reflect assumptions regarding hospital procurement consolidation velocity and AI software certification adoption rates. A model refresh is warranted upon material change in FDA predicate device clearance requirements or NMPA innovative device pathway eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Portable MRI Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Ultrasound Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Global 3D Laparoscopy Imaging Market