
 Gallium-68 Market | 2026-2036
Gallium-68 Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium-68 Market Analysis
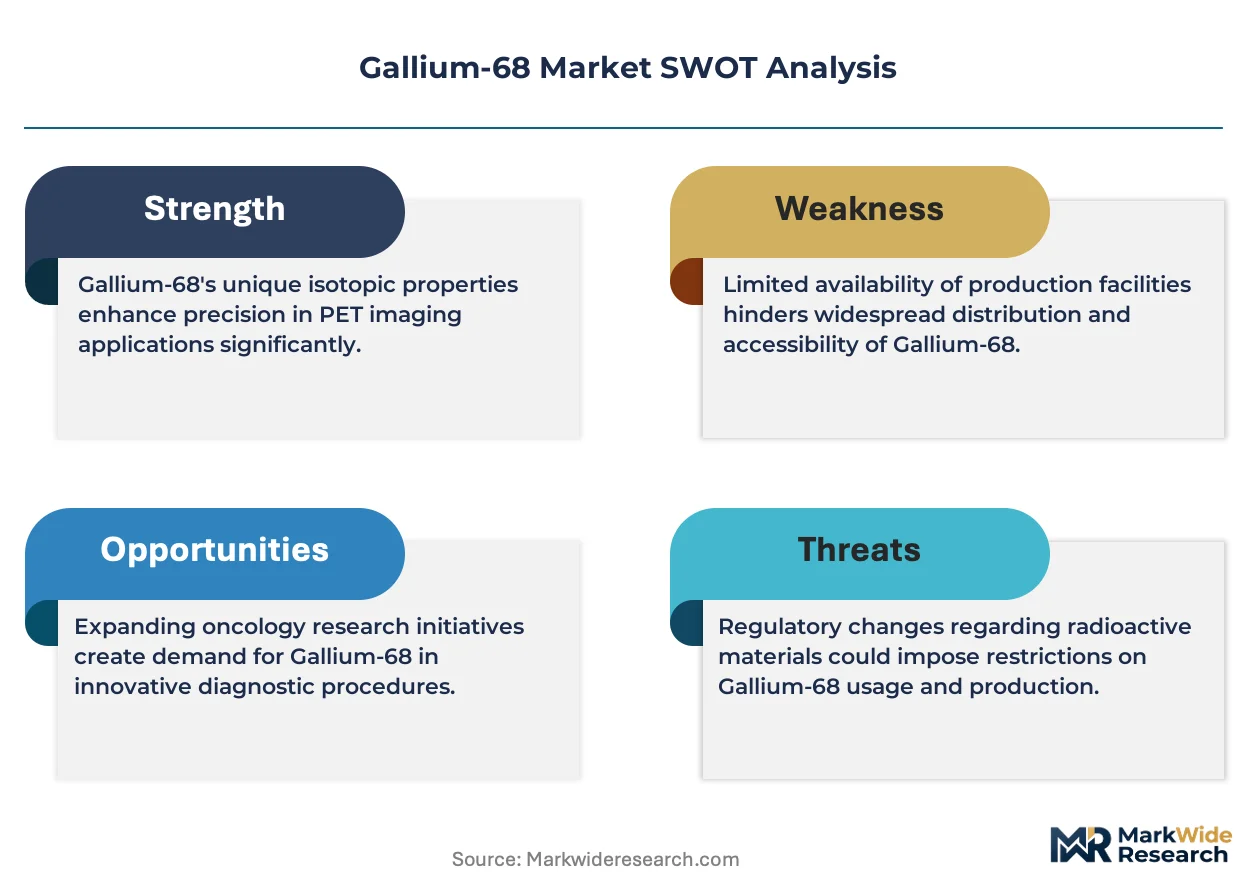
Technetium-99m is shifting toward Gallium-68 in prostate-specific membrane antigen (PSMA) imaging as generator-based production eliminates reactor dependency. Telix Pharmaceuticals leverages its geographically distributed manufacturing network to secure supply continuity across multiple continents. Eckert & Ziegler anchors European distribution through specialized radiopharmacy partnerships. Siemens Healthineers dominates imaging system placement, creating bundled demand for its proprietary Gallium-68 compatible PET scanners.
Gallium-68 is a positron-emitting radioisotope with a 68-minute half-life, produced from germanium-68/gallium-68 generators through elution with hydrochloric acid solution, serving primarily as a diagnostic label for peptide receptor-targeted PET imaging. The radiopharmaceuticals segment leads current revenue as PSMA-targeted agents command premium positioning in oncology workflows, while the therapeutics category shows fastest structural expansion through theranostic pairing with lutetium-177. Hospitals occupy the dominant end-user channel due to capital-intensive PET infrastructure requirements, though outpatient facilities represent an emerging margin pool as decentralized generator models reduce per-scan logistics costs.
The FDA regulates Gallium-68 radiopharmaceuticals under 21 CFR Part 212 current good manufacturing practice standards for PET drugs, while the EMA's centralized procedure governs marketing authorization across European member states. The EU's F-Gas Regulation indirectly shapes generator economics by controlling hydrofluorocarbon use in germanium-68 production cooling systems. Stakeholders must monitor reimbursement parity between Gallium-68 PSMA scans and established staging modalities, as payer acceptance determines whether production scale-up justifies capital deployment in generator manufacturing capacity.
Market Dynamics
The generator-based production model is displacing centralized cyclotron dependency, redistributing manufacturing capacity toward hospital radiopharmacies and enabling point-of-care elution workflows that compress logistics timelines from days to hours.
Growth Catalysts
- PSMA-targeted PET imaging:Prostate cancer staging protocols in major hospital networks now prioritize gallium-68 labeled tracers over conventional bone scintigraphy, creating pull-through demand for compatible generator systems.
- FDA 21 CFR Part 212 streamlining:The PET drug cGMP pathway accelerates IND-to-approval timelines, reducing regulatory friction for novel radiopharmaceutical candidates entering oncology workflows.
- German cyclotron infrastructure:Dense networks of production facilities in Bavaria and North Rhine-Westphalia anchor European supply security, supporting cross-border distribution to neighboring member states.
Market Restraints
- Germanium-68 decay chain volatility:Parent isotope availability constrains generator yield consistency, with batch-to-batch elution efficiency varying 15-25% depending on production source.
- EMA centralized procedure complexity:Marketing authorization timelines for radiopharmaceuticals extend 18-24 months, creating competitive lag versus FDA-approved equivalents entering European markets.
- Technetium-99m residual preference:Established reimbursement codes and familiar workflow integration slow substitution in cost-sensitive health systems, particularly in Eastern European markets.
Strategic Opportunities
- Outpatient imaging centers:Decentralized generator deployment models reduce per-scan logistics costs, opening margin pools outside hospital capital-intensive infrastructure.
- Theranostic pairing with lutetium-177:Diagnostic-to-therapeutic isotope coupling creates bundled service revenue streams in academic medical center nuclear medicine departments.
- Australian TGA reimbursement expansion:National Health Service coverage determinations for PSMA PET scans are extending beyond metropolitan Sydney and Melbourne into regional oncology networks.
Industry Challenges
- Radiochemist workforce scarcity:Specialized synthesis expertise for PET drug compounding remains concentrated in tertiary academic centers, constraining scale-up of decentralized production models.
- EU F-Gas Regulation compliance:Hydrofluorocarbon cooling system phase-down mandates force generator manufacturing facility retrofits, compressing capital deployment timelines.
- Cross-border shipping logistics:Isotope half-life decay curves impose hard delivery windows, requiring real-time coordination between production sites and imaging facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium-68 Market |
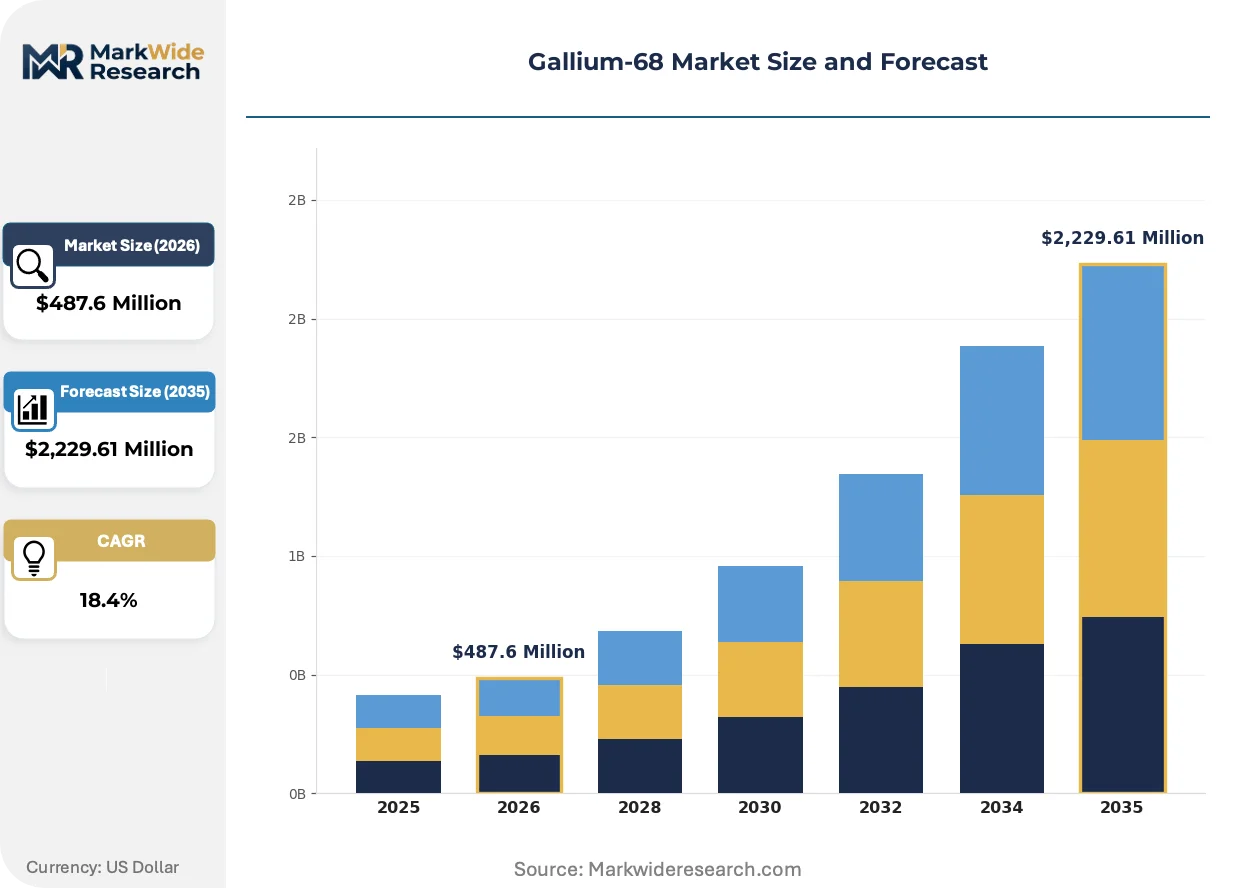
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Diagnostic Agents, Therapeutics, Contrast Agents Application: Oncology, Cardiovascular, Neurology, Infectious Diseases End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Delivery Mode: Intravenous, Intra-arterial, Subcutaneous, Oral |
| Companies Covered | Telix Pharmaceuticals, IRE-ELiT SA, Eckert & Ziegler, Rosatom, Cardinal Health, Siemens Healthineers, ITM Medical Isotopes GmbH, IBA Radiopharma Solutions, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium-68 Market Emerging Trajectories
Automation in radiopharmaceutical synthesis is compressing batch variability and enabling remote operation models that reduce personnel radiation exposure. These shifts are reshaping facility design standards and workforce skill requirements simultaneously.
Solid-phase extraction technology is consolidating purification workflows for gallium-68 labeled peptides, replacing manual column chromatography with cartridge-based systems. Hospital radiopharmacies in the United States and Germany are adopting these platforms at accelerating rates, compressing synthesis time from 90 minutes to under 30 minutes and enabling same-day patient scheduling that maximizes scanner utilization.
The EU F-Gas Regulation is forcing cooling system redesigns across germanium-68 production infrastructure, with manufacturers retrofitting thermal management to comply with hydrofluorocarbon phase-down mandates. European generator suppliers face 12-18 month facility certification timelines, creating temporary supply constraints that advantage competitors with compliant capacity already operational.
Hospital procurement departments are bundling generator supply contracts with PET scanner service agreements, consolidating vendor relationships and demanding volume-based pricing guarantees. Siemens Healthineers leverages this pattern through integrated equipment-financing-radiopharmaceutical packages, particularly visible in Australian private hospital networks seeking to minimize capital risk on new molecular imaging programs.
Gallium-68 Market Segmentation
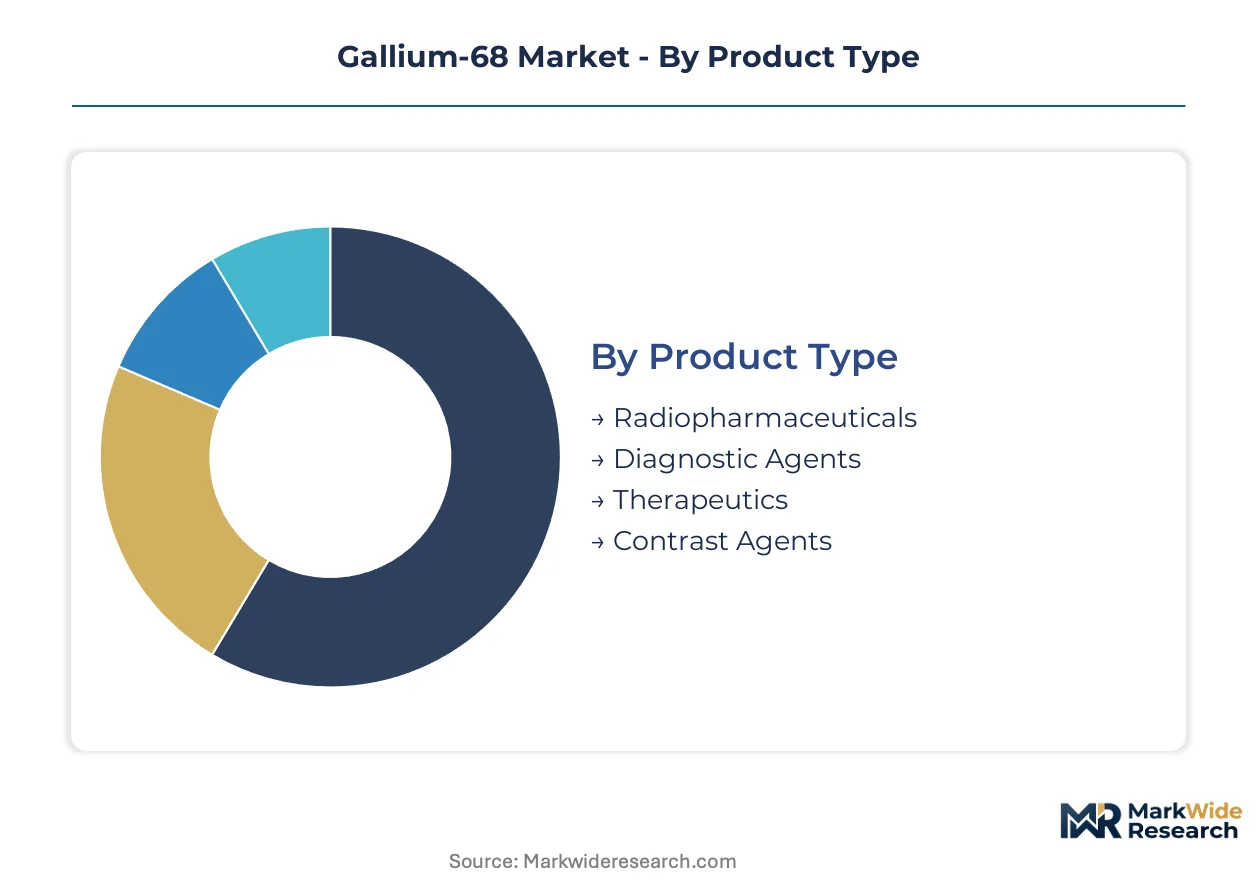
Gallium-68 market segmentation reveals distinct procurement patterns across product categories, with reimbursement codes and clinical workflow integration determining buyer priorities. Understanding these divides clarifies where capital deployment concentrates and where emerging margin pools sit.
Product Type:
Hospital pharmacy directors prioritize clinical validation depth and supply security when selecting among product categories, with FDA approval status and generator compatibility driving contract decisions.
- Radiopharmaceuticals:These comprise peptide-receptor targeted agents labeled with gallium-68 for PET imaging, with PSMA-targeted compounds commanding premium positioning in prostate cancer staging protocols. Demand concentrates in United States academic medical centers where bundled theranostic service lines justify higher per-dose costs.
- Therapeutics:Theranostic pairing with lutetium-177 creates diagnostic-to-therapeutic revenue streams, enabling nuclear medicine departments to capture full patient care cycles. German university hospitals are expanding these coupled service lines fastest, driven by EMA reimbursement harmonization across member states.
- Diagnostic Agents:General-purpose imaging compounds for receptor profiling across multiple cancer types.
- Contrast Agents:Adjunct compounds enhancing visualization clarity in specific tissue contexts.
Radiopharmaceuticals lead on scale; therapeutics lead on momentum.
Application:
Clinical adoption velocity varies sharply by disease area, with established screening infrastructure and specialist referral networks determining where gallium-68 displaces conventional modalities.
- Oncology:Prostate cancer staging dominates current utilization, with PSMA PET imaging displacing bone scintigraphy in major hospital networks. United States urology practices are driving fastest adoption, supported by CMS reimbursement determinations for biochemical recurrence evaluation.
- Neurology:Neuroendocrine tumor imaging represents established use, with somatostatin receptor targeting enabling precise lesion localization. Australian metropolitan centers are expanding these indications into regional networks following TGA coverage expansions.
- Cardiovascular:Emerging applications in atherosclerotic plaque characterization and myocardial perfusion assessment.
- Infectious Diseases:Experimental deployment for localized infection imaging using white blood cell labeling techniques.
Oncology leads on scale; neurology leads on momentum.
End User:
Capital intensity and regulatory licensing requirements create sharp segmentation in procurement behavior, with infrastructure ownership determining contract structure preferences.
- Hospitals:Integrated health systems with captive PET scanner fleets and in-house cyclotron or generator infrastructure dominate current volume. German hospital networks leverage dense Bavarian and North Rhine-Westphalia production clusters to secure supply continuity.
- Outpatient Facilities:Decentralized imaging centers are adopting generator-based models to reduce per-scan logistics costs and enable same-day patient scheduling. These facilities are gaining share fastest in Australian private healthcare networks seeking to minimize capital risk.
- Diagnostic Centers:Independent imaging providers without full hospital infrastructure.
- Research Institutions:Academic centers conducting clinical trials and novel tracer development.
Hospitals lead on scale; outpatient facilities lead on momentum.
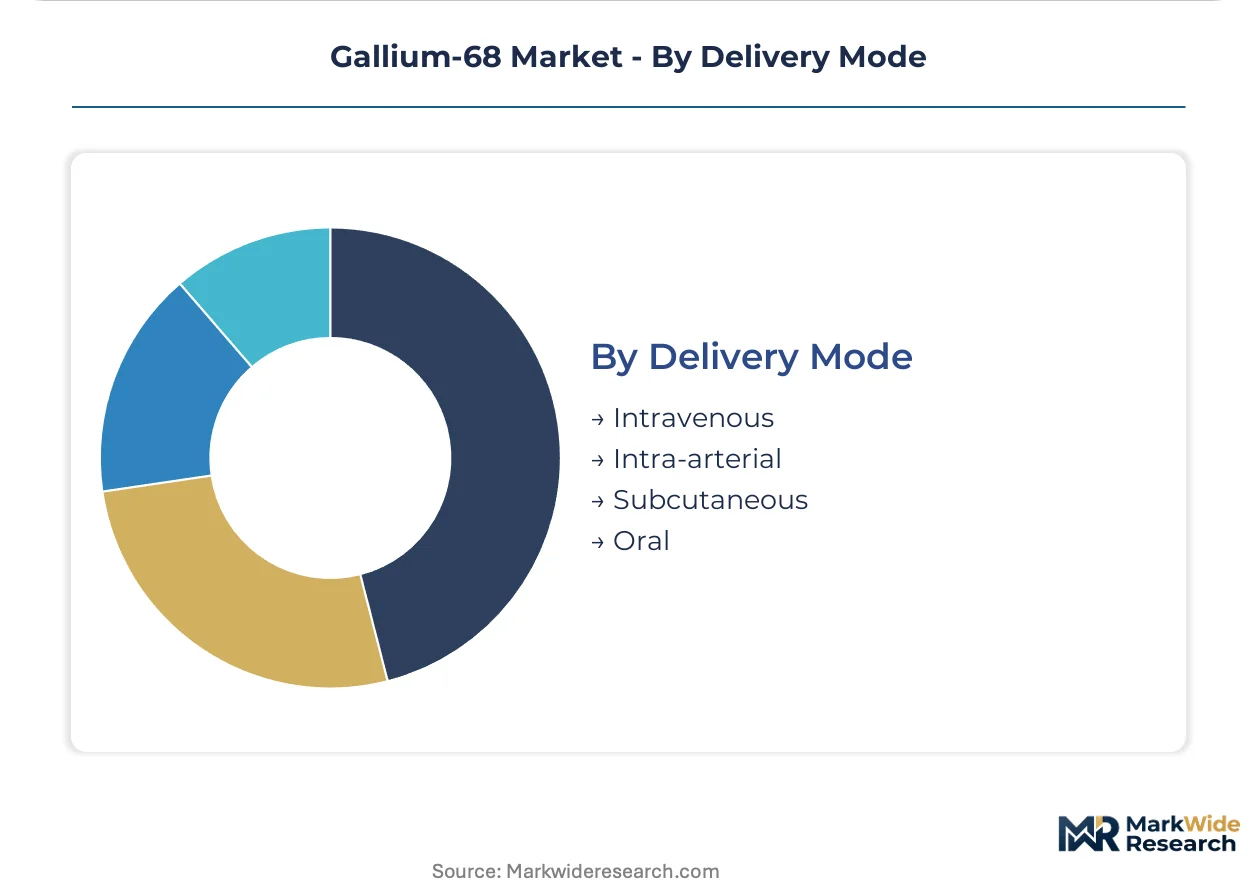
Delivery Mode:
Route selection ties directly to tracer pharmacokinetics and target tissue accessibility, with radiochemist expertise requirements varying by administration complexity.
- Intravenous:Standard administration for peptide-based agents with rapid systemic distribution, requiring standard nuclear medicine nursing protocols. This route dominates current clinical practice across United States, German, and Australian hospital networks.
- Intra-arterial:Selective delivery for hepatic neuroendocrine metastases, demanding interventional radiology collaboration and specialized catheterization suites.
- Subcutaneous:Limited applications in lymphatic mapping procedures.
- Oral:Experimental formulations for gastrointestinal receptor targeting.
Intravenous leads on scale; intra-arterial leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria anchors generator manufacturing capacity for the European market, with cyclotron clusters in North Rhine-Westphalia and Baden-Württemberg supporting cross-border distribution networks. Regulatory frameworks and reimbursement policies determine where clinical adoption outpaces supply infrastructure.
United States
CMS reimbursement determinations for PSMA PET imaging drive hospital procurement of generator systems, with urology practices in metropolitan markets accelerating substitution away from bone scintigraphy. FDA 21 CFR Part 212 standards govern PET drug cGMP compliance, streamlining IND-to-approval pathways for novel radiopharmaceutical candidates. Academic medical centers in Boston and Houston anchor theranostic service line expansion, bundling diagnostic and therapeutic isotope workflows.
Germany
Dense cyclotron infrastructure in Bavaria and North Rhine-Westphalia secures European supply continuity, with university hospitals in Munich and Cologne leading theranostic pairing adoption. EMA centralized procedures govern marketing authorization timelines, creating competitive lag versus FDA-approved equivalents. The EU F-Gas Regulation forces cooling system retrofits across germanium-68 production facilities, compressing capital deployment schedules for generator manufacturers.
Australia
TGA reimbursement expansions for PSMA PET scans extend beyond Sydney and Melbourne into regional oncology networks, opening margin pools in decentralized imaging markets. National Health Service coverage determinations prioritize biochemical recurrence evaluation protocols. Private hospital networks in Queensland and Western Australia adopt generator-based models to minimize capital risk on new molecular imaging programs.
France
ANSM oversight of radiopharmaceutical manufacturing standards shapes hospital procurement criteria, with academic centers in Paris and Lyon prioritizing FDA-approved tracer equivalents. The country's nuclear medicine infrastructure concentrates in Île-de-France and Auvergne-Rhône-Alpes, supporting cross-border distribution to neighboring Benelux markets. Reimbursement parity negotiations between public payers and generator suppliers determine clinical adoption velocity outside metropolitan clusters.
United Kingdom
NHS England specialized commissioning frameworks for molecular imaging create demand concentration in London and Manchester tertiary centers. MHRA post-Brexit regulatory autonomy enables faster adoption of EMA-approved radiopharmaceuticals versus historical timelines. Research institutions in Cambridge and Oxford anchor clinical trial networks for novel tracer development, bridging diagnostic validation toward therapeutic pairing protocols.
Gallium-68 Market Vendor Landscape
Global majors compete with regional champions across generator manufacturing and radiopharmaceutical distribution networks. Market structure tilts toward consolidated supply relationships, with hospital procurement departments bundling equipment, financing, and isotope contracts to minimize vendor complexity. Three archetypes dominate: vertically integrated imaging system manufacturers, specialized radiopharmacy distributors, and theranostic-focused biotechnology developers. Competitive moves concentrate on strategic partnerships with academic medical centers and capacity expansion in F-Gas-compliant production facilities.
Among theranostic-focused developers, Telix Pharmaceuticals exemplifies geographically distributed manufacturing strategies to secure supply continuity across multiple continents. Eckert & Ziegler anchors European distribution positioning through specialized radiopharmacy partnerships. Siemens Healthineers occupies a dominant position in imaging system placement, creating bundled demand for proprietary Gallium-68 compatible PET scanners through integrated equipment-financing-radiopharmaceutical packages.
| Leading Market Players |
|---|
| Telix Pharmaceuticals |
| IRE-ELiT SA |
| Eckert & Ziegler |
| Rosatom |
| Cardinal Health |
| Siemens Healthineers |
| ITM Medical Isotopes GmbH |
| IBA Radiopharma Solutions |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Hospital procurement departments bundling generator contracts with PET scanner service agreements are compressing vendor margins and forcing supply chain reconfigurations toward integrated equipment-radiopharmaceutical packages. German university hospitals and Australian private networks now demand volume-based pricing guarantees that shift pricing power toward buyers with captive scanner fleets.
Pricing Analysis
Input-cost pass-through from germanium-68 parent isotope volatility shapes generator pricing, with batch-to-batch elution efficiency swings of 15-25% forcing suppliers to absorb margin compression or risk contract loss. Three-tier pricing structure across FDA-approved premium tracers, EMA-authorized standard agents, and investigational economy compounds reflects certification-grade differentiation. Pricing pressure stems from outpatient imaging centers demanding same-day elution logistics at hospital-comparable rates. Academic medical centers show least price sensitivity due to bundled theranostic service line economics.
Supply Chain Analysis
Single-source vulnerability sits with germanium-68 production concentrated in Germany, Russia, and South Africa, where parent isotope irradiation capacity anchors global generator yield. Generator manufacturing draws from specialized germanium-68 stockpiles, hydrochloric acid elution chemistry, and solid-phase extraction cartridges. Tariff exposure on cross-border isotope shipments compounds decay-curve logistics constraints. Distribution runs through specialized radiopharmacy partnerships with hospital networks and academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement parity for PSMA PET imaging is shifting procurement criteria toward FDA-validated premium tracers over economy-grade alternatives.
For Market Incumbents: Deepen backward integration into germanium-68 production infrastructure to secure parent isotope supply against Russian and South African export volatility. Fortify radiochemist workforce pipelines through academic partnerships to constrain decentralized competitor scale-up. Anchor hospital procurement relationships through bundled scanner-generator-financing packages that raise switching costs for outpatient facility entrants. For New Entrants and Emerging Players: Australian regional oncology networks outside Sydney and Melbourne represent the most penetrable buyer archetype, where TGA reimbursement expansion and capital-light generator models reduce entry barriers. Target decentralized imaging centers in Queensland and Western Australia seeking to minimize PET infrastructure risk. Pursue theranostic service line partnerships with German university hospitals as a credibility-building beachhead. For Investors and Strategic Acquirers: Asymmetric upside sits with theranostic-focused biotechnology developers possessing geographically distributed manufacturing footprints and lutetium-177 pairing capabilities. Long-term viability centers on EMA-FDA regulatory convergence enabling cross-approval leverage. Watch for TGA reimbursement determinations in regional Australian markets as inflection indicators for decentralized model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 212 Compliance Investment | Accelerates IND-to-approval timelines for novel PSMA-targeted tracers entering oncology workflows. |
| Germanium-68 Production Capacity Expansion | Secures parent isotope supply continuity against decay chain volatility and cross-border shipping constraints. |
| Theranostic Service Line Bundling | Captures full patient care cycles through diagnostic-to-therapeutic isotope coupling in academic centers. |
| Outpatient Facility Generator Deployment | Reduces per-scan logistics costs and enables same-day scheduling outside hospital infrastructure. |
| EU F-Gas Regulation Retrofit Completion | Ensures cooling system compliance before mandated phase-down deadlines compress manufacturing capacity. |
Methodological Framework
Multiple input streams — primary interviews with nuclear medicine department heads, radiopharmacy operations directors, and hospital procurement managers; secondary validation against FDA 21 CFR Part 212 filings, EMA centralized procedure submissions, and TGA reimbursement determinations; plus CMS Medicare claims data — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectories.
Data-stream reconciliation across product type, application, end user, and regional regulatory cluster dimensions enabled segmented growth modeling across the projection horizon. CAGRs were derived from installed base expansion of PET scanner fleets, generator deployment rates, and PSMA PET scan reimbursement code adoption curves. Forecast inputs incorporated cyclotron infrastructure buildout timelines and radiochemist workforce pipeline constraints.
Underlying measurement precision varies by segment; radiopharmaceuticals and United States hospital networks carry tighter precision than therapeutics and emerging outpatient channels. Forecasts reflect assumptions on EMA-FDA approval timeline convergence and TGA regional reimbursement expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Brazil Digital X-Ray Market