
 AI-Assisted Digital Radiography Equipment Market | 2026-2036
AI-Assisted Digital Radiography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Assisted Digital Radiography Equipment Market Insights
Deep learning integration into detector hardware is reconfiguring how image acquisition pipelines process raw sensor data. GE Healthcare leverages captive semiconductor partnerships to control flat panel detector supply chains from wafer to system integration. Siemens Healthineers anchors European installed base expansion through service-contract bundling with AI software subscriptions.
AI-assisted digital radiography equipment combines solid-state flat panel detectors with real-time inference engines that apply convolutional neural networks to raw X-ray photon data, reducing noise and flagging pathological patterns before human radiologist review. The primary commercial purpose is to increase diagnostic throughput while lowering retake rates in high-volume screening environments. Flat panel detectors command the largest installed base but face margin compression as detector commoditization accelerates across Asian manufacturing clusters. Machine learning models represent the fastest-expanding revenue pool, particularly neural network architectures trained on multi-institutional chest imaging datasets that command premium licensing terms from hospital buyers.
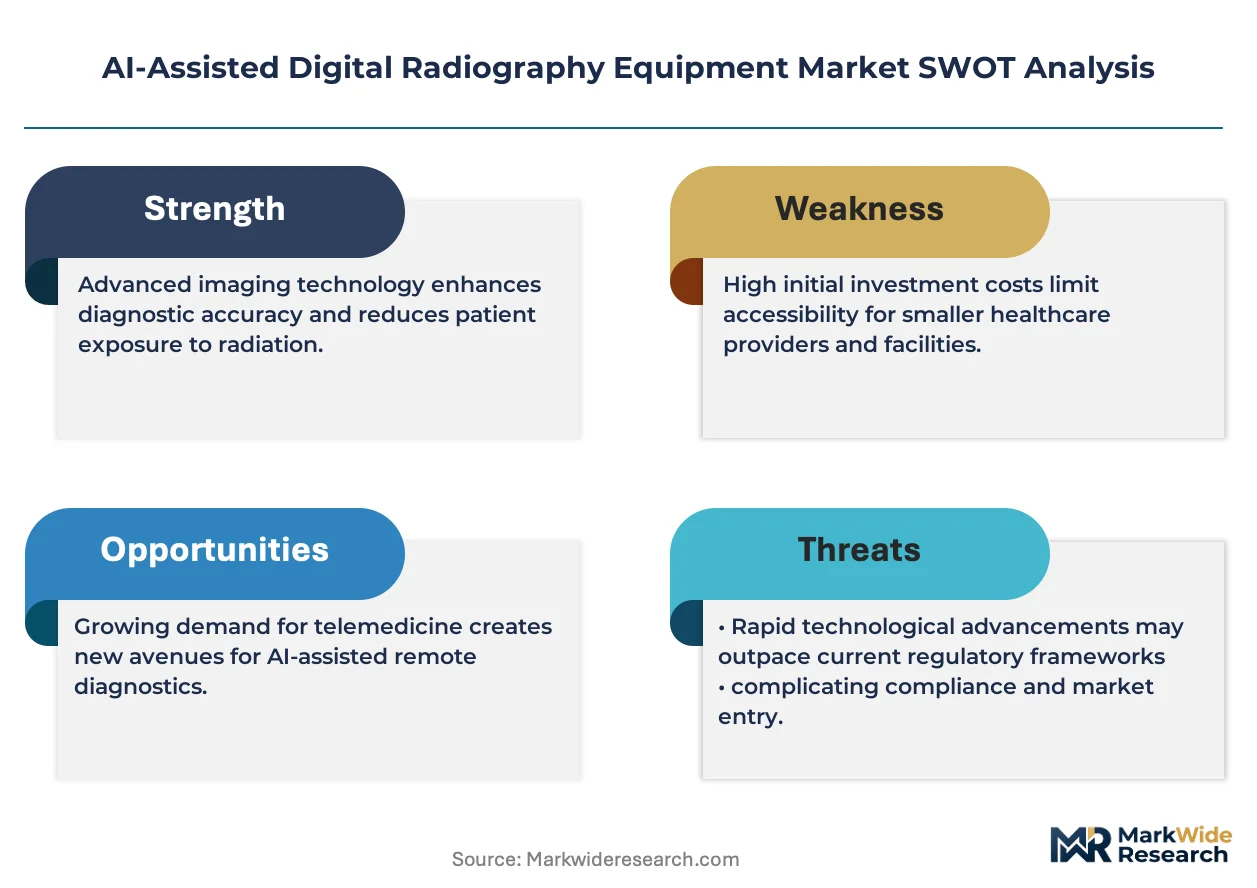
FDA premarket notification pathways under 21 CFR 892 shape how algorithm developers validate diagnostic accuracy claims before commercial deployment, while the EU Medical Device Regulation imposes post-market surveillance obligations that extend software update cycles. Japan's PMDA has issued specific guidance on adaptive AI systems that modify performance through continuous learning, creating a compliance template that other Asian regulators are studying. Stakeholders must weigh regulatory divergence against the cost of maintaining parallel validation datasets for each major jurisdiction's submission requirements.
Market Dynamics
Deep learning inference engines embedded at the detector level are compressing image processing pipelines and eliminating hardware redundancy across hospital radiology departments.
Growth Catalysts
- FDA 510(k) premarket notification streamlining:Machine learning-based radiological devices now face abbreviated review timelines for certain submission categories, accelerating commercial deployment timelines for algorithm developers.
- Hospital network consolidation in Germany:University hospital systems are centralizing imaging infrastructure procurement under unified purchasing frameworks, creating volume concentration that favors AI-augmented system vendors.
- Convolutional neural network architectures:Neural networks trained on multi-institutional chest imaging datasets are commanding premium licensing terms from buyers seeking diagnostic accuracy improvements.
Market Restraints
- Flat panel detector commoditization:Asian manufacturing clusters are accelerating margin compression in detector hardware as production scales and differentiation erodes.
- Regulatory divergence costs:Parallel validation datasets for FDA, EU MDR, and PMDA submission requirements impose redundant clinical trial burdens on algorithm developers.
- Retraining infrastructure limitations:Continuous learning AI systems require specialized hardware refresh cycles that strain capital budgets in mid-tier healthcare facilities.
Strategic Opportunities
- EU Medical Device Regulation post-market surveillance:Extended software update cycles mandated by MDR compliance create recurring service revenue streams for vendors with established European installed bases.
- Japan PMDA adaptive AI guidance:Regulatory templates for continuously learning systems are being studied by Asian regulators, creating first-mover advantages for vendors with Japanese market experience.
- Edge inference hardware convergence:Integration of solid-state detectors with on-chip neural processing units enables real-time pathology flagging without cloud dependency.
Industry Challenges
- Interoperability with legacy PACS infrastructure:AI-augmented systems must interface with decade-old picture archiving systems that lack standardized API frameworks.
- Radiologist workflow retraining requirements:Diagnostic confidence in AI-flagged findings requires substantial change management investment across clinical departments.
- Validation dataset bias mitigation:Multi-institutional training data must address demographic representation gaps to satisfy regulatory scrutiny across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Assisted Digital Radiography Equipment Market |
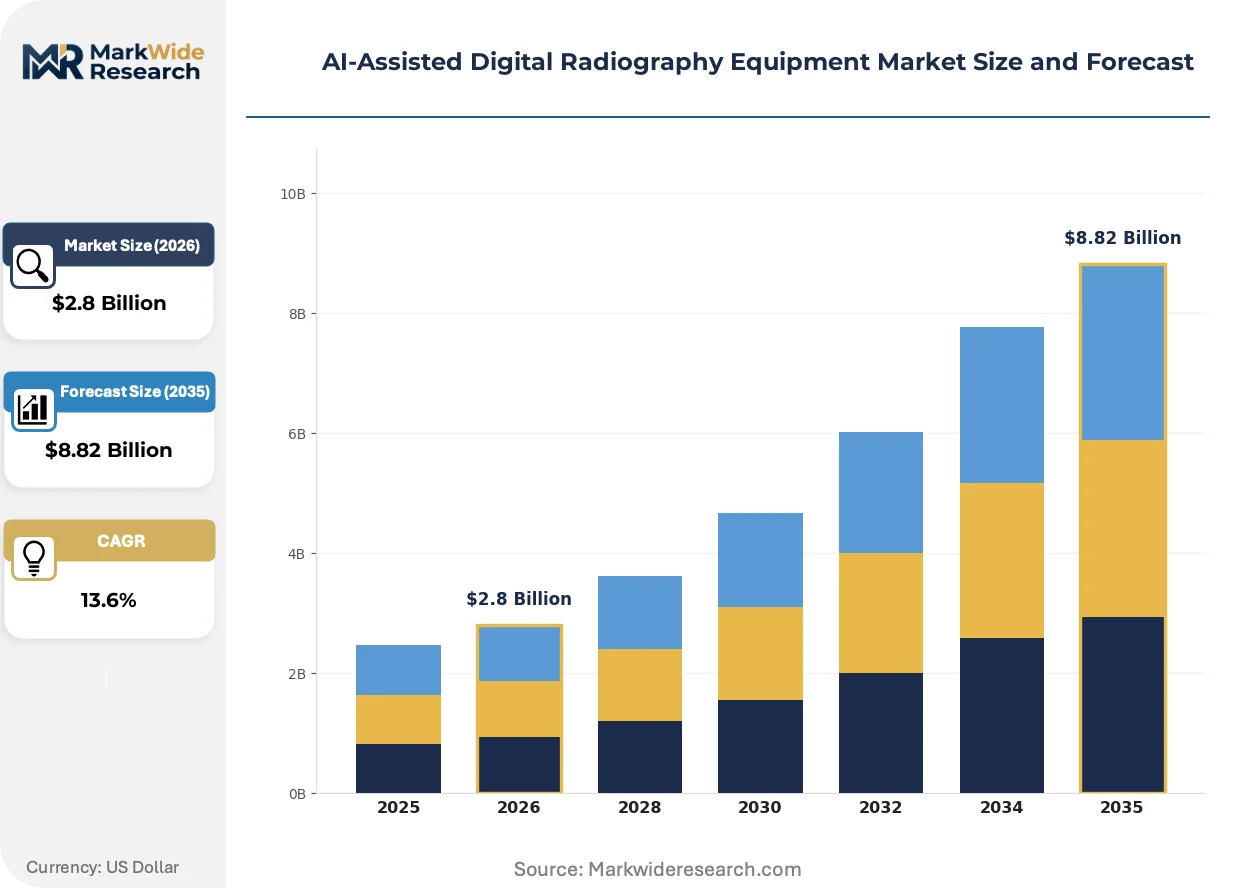
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography Systems, X-ray Imaging Systems, Mobile Radiography Units Technology: Image Processing Algorithms, Machine Learning Models, Neural Networks, Software Interfaces End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Application: Bone Imaging, Chest Imaging, Dental Imaging, Mammography |
| Companies Covered | GE Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Koninklijke Philips N.V., Canon Medical Systems, Carestream Health, Konica Minolta, Aidoc, Lunit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Assisted Digital Radiography Equipment Market Trends and Innovations
Real-time inference at the point of image acquisition is displacing post-processing workflows and redefining where diagnostic value is captured in the radiology value chain.
Photon-counting detector technology is migrating from research installations to commercial chest imaging suites. Academic medical centers in Switzerland and the Netherlands are piloting cadmium telluride sensor arrays that discriminate X-ray energy spectra. The technology is migrating from premium cardiovascular applications toward high-volume tuberculosis screening programs where material differentiation improves nodule detection specificity.
The EU AI Act risk classification framework is imposing conformity assessment obligations on diagnostic algorithms that influence patient treatment decisions. Developers must maintain technical documentation and quality management systems that extend beyond traditional medical device requirements. Chest pathology detection models face heightened scrutiny under Class IIa and IIb designations, prompting vendors to restructure European market entry strategies.
Service-contract bundling with software subscriptions is displacing perpetual licensing in European hospital procurement. Siemens Healthineers anchors installed base retention through multi-year agreements that embed algorithm updates within hardware maintenance fees. German university hospital networks demonstrate the strongest concentration of this model, where centralized purchasing offices prioritize predictable operational expenditure over capital outlays.
AI-Assisted Digital Radiography Equipment Market Segmentation
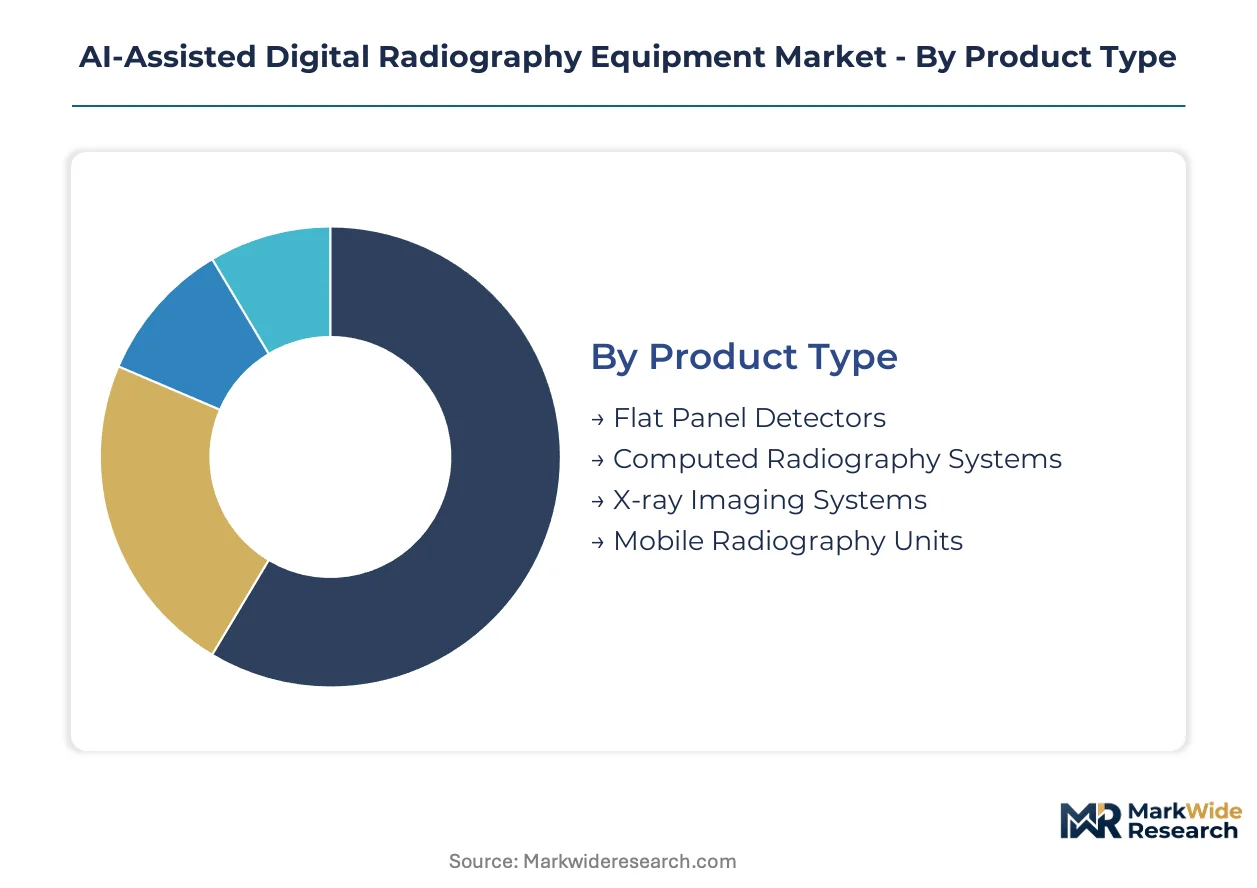
Segmentation reveals how AI-augmented radiography equipment distributes across hardware platforms, algorithmic architectures, and clinical deployment settings. Each dimension carries distinct procurement cycles, regulatory pathways, and margin structures that shape vendor strategy.
Product Type:
Hardware differentiation separates premium integrated systems from modular retrofit configurations, with cost tier determining hospital network purchasing behavior.
- Flat Panel Detectors:Solid-state amorphous silicon or selenium sensor arrays convert X-ray photons directly to digital signals with minimal noise amplification. German university hospital networks concentrate demand here under centralized procurement frameworks that prioritize detector longevity and service bundling.
- Computed Radiography Systems:Photostimulable phosphor plates require laser scanning digitization, creating intermediate processing steps that AI algorithms must accommodate. Mid-tier facilities in Japan leverage these systems for cost-controlled migration paths from analog workflows.
- X-ray Imaging Systems:Integrated tube-detector architectures with embedded inference engines.
- Mobile Radiography Units:Battery-powered systems with wireless detector pairing for bedside and emergency deployment.
Flat Panel Detectors hold installed capacity. Mobile Radiography Units are rotating up the share rankings.
Technology:
Algorithmic sophistication defines competitive differentiation, with application maturity separating regulatory-cleared deployments from experimental architectures.
- Machine Learning Models:Supervised classifiers trained on annotated pathology datasets deliver diagnostic confidence scores alongside processed images. FDA 510(k) premarket notifications for these models now face abbreviated review timelines for certain submission categories, accelerating hospital procurement decisions.
- Neural Networks:Deep convolutional architectures process raw detector data through multi-layer feature extraction pipelines. Research institutions in Switzerland pilot cadmium telluride sensor integration with these networks for energy-resolved photon counting.
- Image Processing Algorithms:Traditional denoising and enhancement routines without adaptive learning components.
- Software Interfaces:API layers bridging AI inference outputs to legacy PACS infrastructure.
Machine Learning Models dominate current revenue. Neural Networks are climbing the fastest as training datasets expand.
End User:
Customer type dictates capital intensity and software subscription appetite, with volume scale separating enterprise hospital networks from independent imaging operators.
- Hospitals:Acute care institutions with radiology departments processing thousands of studies weekly demand integrated AI-flagging workflows. North American hospital networks are expanding procurement of AI-augmented chest imaging systems as throughput pressure intensifies.
- Diagnostic Centers:Specialized outpatient facilities prioritize rapid turnaround and teleradiology compatibility.
- Imaging Clinics:Smaller independent operators seeking pay-per-study AI licensing models.
- Research Institutions:Academic medical centers validating novel algorithm architectures.
Hospitals anchor procurement volume. Diagnostic Centers are gaining share fastest as outpatient migration accelerates.
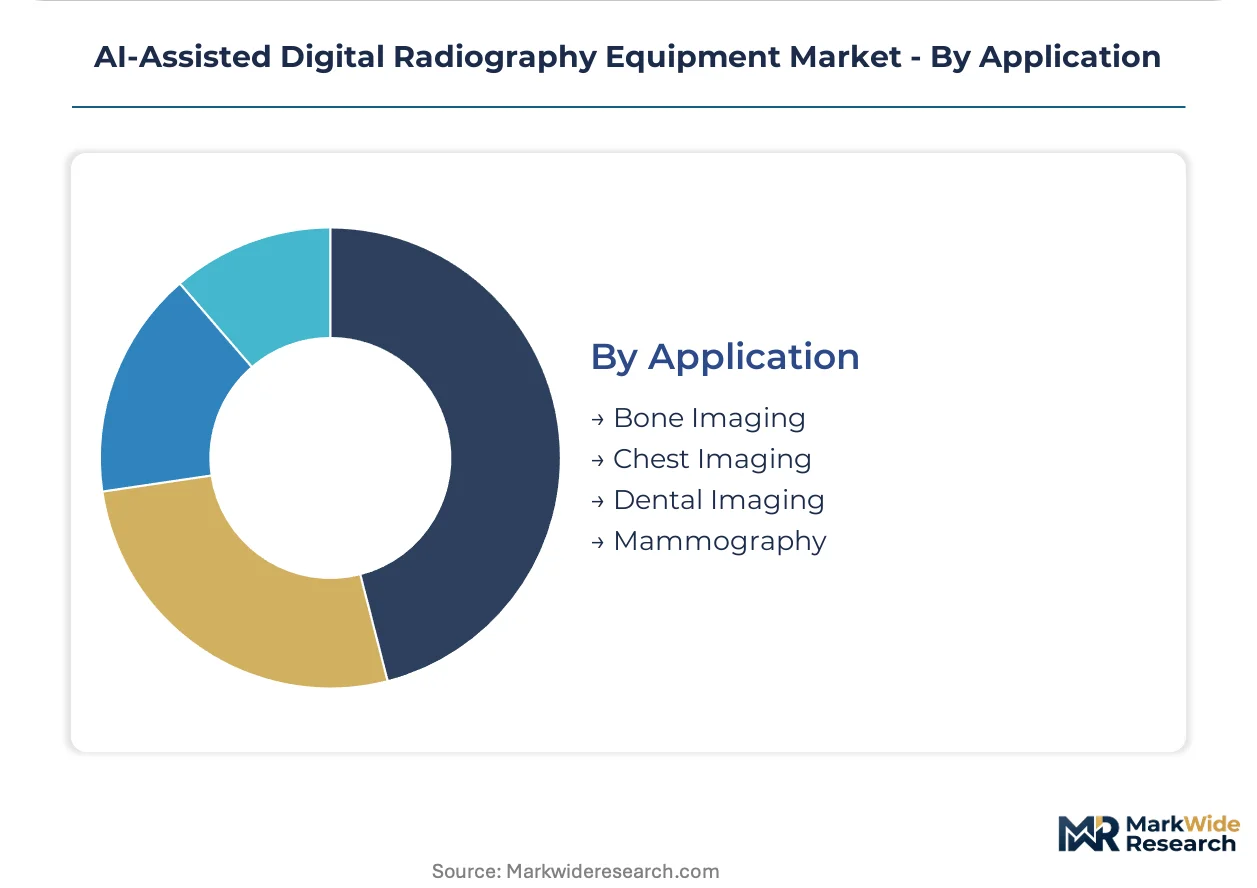
Application:
Clinical use case determines regulatory scrutiny intensity and reimbursement pathways, with screening volume separating high-throughput chest programs from specialized anatomical studies.
- Chest Imaging:Pulmonary and cardiac radiography generates the highest study volumes where AI nodule detection delivers measurable throughput gains. Tuberculosis screening programs in the Netherlands pilot photon-counting detector arrays to improve specificity through material differentiation.
- Mammography:Breast tissue imaging demands specialized low-dose optimization and dense tissue algorithms. EU AI Act Class IIb risk classification imposes heightened conformity assessment obligations here due to direct treatment influence.
- Bone Imaging:Orthopedic and trauma radiography with fracture detection priorities.
- Dental Imaging:Cone-beam and panoramic systems with specialized sensor formats.
Chest Imaging commands study volume leadership. Mammography is rotating up the share rankings as AI validation datasets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement offices in Germany command the largest concentration of centralized purchasing power for AI-augmented imaging systems. Academic medical centers in Switzerland and university networks in the Netherlands anchor European pilot programs for photon-counting detector arrays.
United States
Hospital networks across the Midwest and Southeast are expanding AI-augmented chest imaging procurement as throughput pressure intensifies. FDA 510(k) premarket notification pathways now offer abbreviated review timelines for certain machine learning submission categories. The Boston-Cambridge corridor hosts concentrated algorithm development activity alongside major radiology residency programs.
Germany
University hospital networks are consolidating imaging infrastructure under centralized purchasing frameworks that favor vendors offering service-contract bundling. EU Medical Device Regulation post-market surveillance obligations extend software update cycles and create recurring revenue opportunities. The Rhine-Ruhr metropolitan region demonstrates the strongest concentration of multi-year AI software subscription agreements.
Japan
Mid-tier healthcare facilities are pursuing cost-controlled migration paths from analog workflows through computed radiography retrofits. PMDA guidance on adaptive AI systems that modify performance through continuous learning establishes compliance templates for algorithm developers. Tokyo and Osaka anchor domestic detector manufacturing clusters serving regional export markets.
Switzerland
Academic medical centers in Zurich and Basel are piloting cadmium telluride sensor arrays for energy-resolved photon counting in tuberculosis screening programs. Swissmedic maintains alignment with EU MDR requirements while offering streamlined pathways for research-to-commercial transitions. The Swiss Innovation Park network supports detector hardware startups with proximity to CERN-derived sensor expertise.
Netherlands
National tuberculosis screening programs are driving demand for material differentiation capabilities that improve nodule detection specificity. The Dutch national healthcare procurement authority centralizes imaging equipment tenders under standardized technical specifications. Eindhoven's high-tech systems corridor supplies semiconductor components for detector readout electronics.
AI-Assisted Digital Radiography Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates among integrated imaging conglomerates and algorithm-focused software vendors. The competitive landscape divides into three strategic archetypes: captive detector manufacturers with semiconductor partnerships, AI-native algorithm developers with regulatory-cleared models, and service-integrated platform vendors bundling hardware with subscription software. Dominant competitive moves include strategic partnerships between detector fabricators and cloud inference providers, plus geographic expansion through localized regulatory submission capabilities.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions representing integrated system vendors with captive supply chain control from wafer fabrication through hospital installation. Fujifilm Holdings Corporation exemplifies the imaging-specialist archetype with concentrated expertise in detector chemistry and film-to-digital transition experience. These three entities anchor the premium tier where service-contract bundling with AI software subscriptions has displaced perpetual licensing in European hospital procurement.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Carestream Health |
| Konica Minolta |
| Aidoc |
| Lunit |
| Others |
Pricing and Supply Chain Analysis
Wafer fabrication concentration in Taiwan and South Korea feeds directly into margin capture at the flat panel detector tier, where semiconductor partnerships determine pricing power across hospital procurement negotiations. Detector commoditization in Asian manufacturing clusters is compressing hardware premiums while algorithm licensing fees concentrate value in software subscriptions.
Pricing Analysis
Cost-plus contracts with rare earth element indexation dominate long-term detector supply agreements, insulating vendors from cadmium telluride price volatility. Three-tier pricing structure across premium, standard, and economy levels separates integrated systems with embedded inference engines from modular retrofits and bare detector replacements. Pricing pressure stems from computed radiography system overcapacity in Japan as mid-tier facilities delay full digital migration. Independent imaging clinics exhibit highest price sensitivity, while German university hospital networks prioritize service-contract predictability over unit economics.
Supply Chain Analysis
Export control regimes limiting semiconductor manufacturing equipment flows to China are constraining amorphous silicon detector substrate expansion outside established fabrication bases. Supply draws from Taiwan, South Korea, and Japan for sensor wafers, with selenium deposition chemicals sourced from Germany and specialty gases from the United States. Single-source vulnerability concentrates in advanced node lithography for neural processing units. Distribution runs through regional imaging equipment distributors with hospital GPO affiliation in North America and direct vendor relationships in European centralized procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital capital expenditure cycles are recovering from pandemic-era deferrals, with radiology infrastructure refresh timelines compressing as diagnostic throughput pressure intensifies across health systems.
For Market Incumbents: Build switching-cost moats through multi-year AI software subscription lock-in with German university hospital networks. Deepen backward integration into semiconductor partnerships to secure flat panel detector supply amid export control tightening. Counter emerging algorithm-native vendors by embedding FDA-cleared models directly into detector firmware rather than bolt-on software layers. For New Entrants and Emerging Players: Build out teleradiology-compatible AI flagging tools for independent diagnostic centers in North America, where outpatient migration is accelerating faster than incumbent software roadmaps. Target mid-tier Japanese facilities with computed radiography retrofit packages that bridge analog workflows toward full digital inference. Lead with pay-per-study licensing to bypass capital budget approval cycles. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm developers with multi-jurisdictional regulatory clearances and hospital pilot data spanning three or more countries. Long-term viability hinges on adaptive AI architectures that satisfy Japan PMDA continuous learning guidance without triggering EU MDR re-certification cycles. Watch FDA 510(k) review timeline expansion for machine learning submissions as an inflection signal for algorithm developer funding windows.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year service contracts with German university networks anchor recurring revenue streams. |
| CE Marking Pathway | EU MDR post-market surveillance obligations extend software update monetization cycles. |
| Software Companion Development | AI inference engines embedded at detector level eliminate cloud dependency and latency. |
| FDA Submission | Abbreviated 510(k) timelines for certain ML categories accelerate commercial deployment. |
| Reimbursement Strategy | Chest screening program coding alignment drives hospital procurement justification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and radiology department heads. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement tender records, and semiconductor trade flow data. Bottom-up detector shipment estimates and top-down health system IT spending analysis were triangulated against algorithm licensing revenue disclosures.
Calibration against historical hospital capital expenditure cycles and regulatory approval velocity informed growth trajectory modeling across the projection horizon. Segmentation dimensions included hardware platform tier, algorithmic architecture maturity, end-user facility scale, and clinical application intensity. CAGRs were derived from fitted adoption curves weighted by procurement pipeline visibility. Forecast inputs incorporated FDA review timeline trends and EU AI Act risk classification implementation pacing.
Stress conditions across semiconductor supply disruption, hospital budget freeze scenarios, and regulatory submission rejection rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding detector commoditization velocity and algorithm reimbursement pathway stability. Material shifts in export control regime scope or EU MDR software update re-certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Specialty PACS Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
PSMA-PET Imaging Market