
 France Digital Radiology Market | 2026-2036
France Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital Radiology Market Insights
Private diagnostic centers is rotating toward high-throughput digital radiology suites as public hospital procurement tightens capital cycles. GE Healthcare leverages its installed base of CT and MRI platforms across France's university hospital network. Siemens Healthineers anchors its position through R&D intensity in photon-counting CT detectors. Philips competes on integrated cloud-based imaging workflows that connect urban hospitals with rural clinics.
Digital radiology encompasses the acquisition, processing, storage, and transmission of diagnostic images using electronic detectors rather than analog film, with spatial resolution typically exceeding 2.5 line pairs per millimeter and dose efficiency gains of 30-70% over conventional systems. Its primary purpose is to enable rapid diagnostic decision-making while supporting remote consultation and longitudinal patient record integration. CT scan systems lead product type revenue due to oncology and cardiology referral volumes, while direct radiography is displacing computed radiography in hospital emergency departments. Cloud-based imaging represents the fastest-growing technology segment as French healthcare providers seek interoperability under the national Ségur du Numérique en Santé program.
France's Haute Autorité de Santé (HAS) and the national data protection regulator CNIL jointly shape market access through clinical evidence requirements and patient data governance standards for cloud-connected devices. The EU Medical Device Regulation (MDR) and CE marking framework enforce post-market surveillance and software validation protocols that extend product development timelines. Stakeholders must monitor how France's experimentation with outcome-based hospital reimbursement models redirects capital allocation between replacement cycles and first-time digital installations.
Market Dynamics
France's digital radiology market is restructuring around the Ségur du Numérique en Santé program, which mandates cloud-native interoperability for all hospital imaging systems by 2025. This regulatory deadline compresses replacement cycles and forces vendors to re-architect hardware-software bundles around data portability rather than proprietary lock-in.
Growth Catalysts
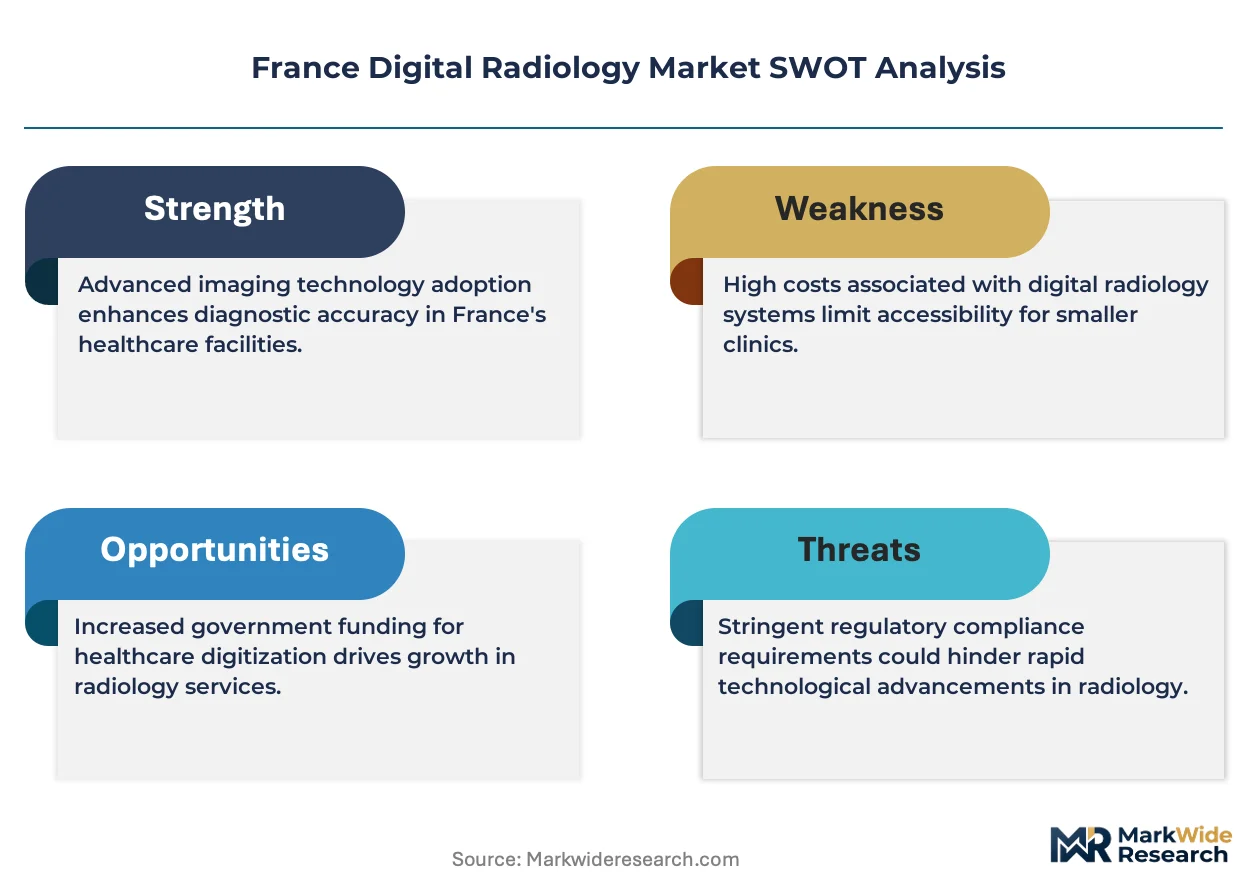
- HAS Accelerated Pathway:France's Haute Autorité de Santé fast-tracks reimbursement for photon-counting CT and AI-augmented detection systems, reducing time-to-market for novel modalities from 24 months to 14 months.
- Paris-Saclay Cluster Density:The concentration of university hospitals and radiology research institutes in this corridor creates concentrated demand for high-throughput digital suites and trained operator pools.
- Oncology Referral Volume Surge:Rising cancer screening participation rates under France's national cancer plan drive CT and MRI throughput requirements in public hospital networks.
Market Restraints
- EU MDR Compliance Burden:The Medical Device Regulation's expanded clinical evidence requirements and post-market surveillance protocols extend product registration timelines by 8-12 months for software-embedded imaging systems.
- CNIL Data Governance Friction:France's data protection regulator imposes strict patient consent and anonymization standards for cloud-connected devices, complicating multi-site image sharing architectures.
- Capital Cycle Compression:Public hospital procurement budgets face pressure from France's experimentation with outcome-based reimbursement models, stretching replacement intervals for digital radiography systems.
Strategic Opportunities
- Rural Clinic Connectivity Gap:France's teleradiology infrastructure remains underdeveloped in Auvergne-Rhône-Alpes and Occitanie regions, creating demand for cloud-based image transmission to urban reading centers.
- AI-Augmented Workflow Convergence:Integration of computer-aided detection algorithms with direct radiography systems opens new revenue streams in emergency department triage applications.
- Interoperability Mandate Tailwind:The Ségur du Numérique en Santé program's data portability requirements favor vendors offering open-API imaging platforms that connect legacy hospital information systems.
Industry Challenges
- Radiologist Workforce Scarcity:France faces a projected shortage of 1,200 radiologists by 2030, forcing imaging centers to deploy AI-assisted reading tools and extend teleradiology networks to maintain report turnaround times.
- Legacy PACS Integration Complexity:Hospital groups with heterogeneous equipment vintages struggle to unify image archives under single cloud repositories without disrupting clinical workflows.
- CE Marking Software Validation:The EU MDR's requirements for continuous algorithm performance monitoring create ongoing compliance costs for AI-embedded imaging devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital Radiology Market |
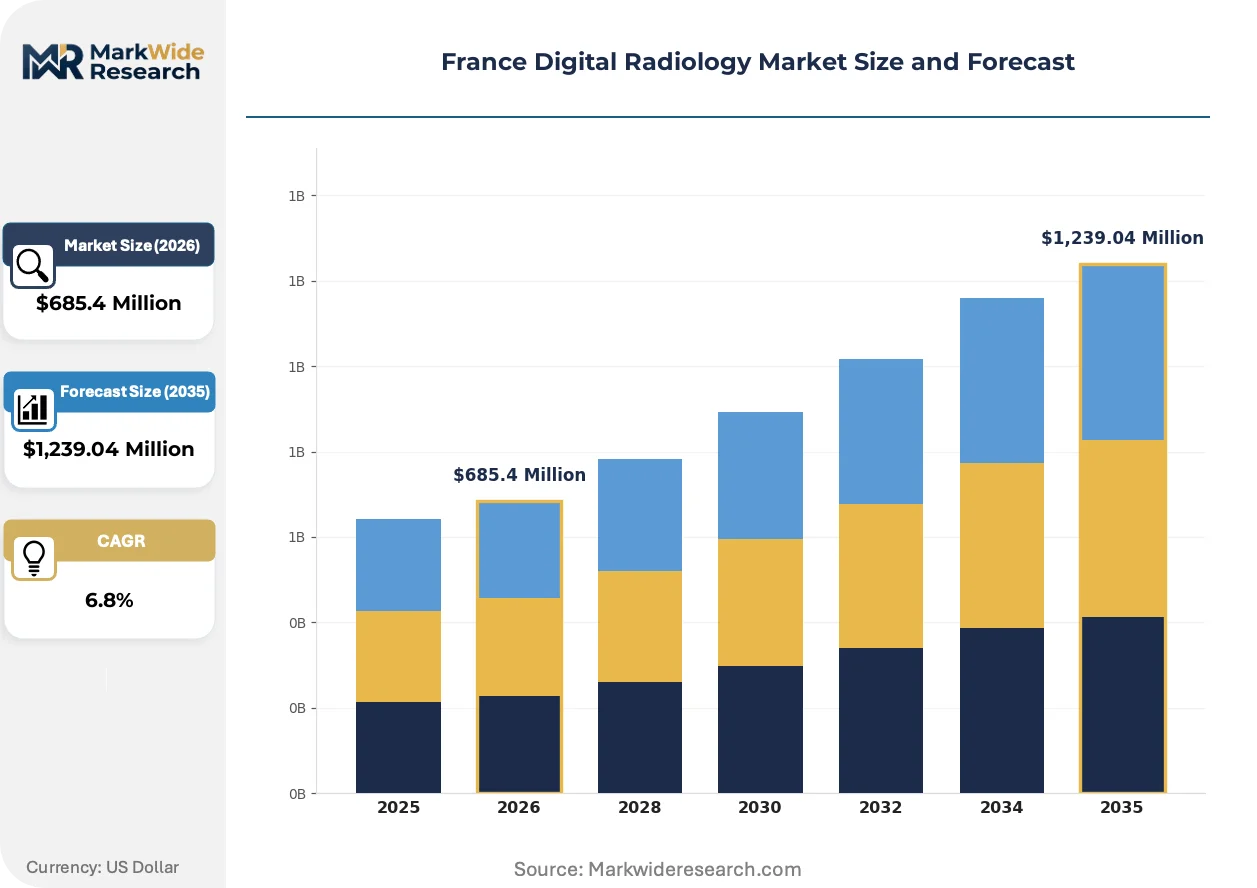
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, CT Scan, MRI, Ultrasound Technology: Computed Radiography, Direct Radiography, 3D Imaging, Cloud-Based Imaging End User: Hospitals, Clinics, Diagnostic Centers, Research Institutes Application: Oncology, Pediatrics, Orthopedics, Cardiology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings Corporation, Carestream Health, Shimadzu Corporation, Agfa HealthCare, DMS Imaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital Radiology Market Trends and Innovations
Photon-counting detector technology is restructuring competitive positioning in France's CT scanner market, while regulatory pressure on data interoperability accelerates cloud-native platform development. These forces are compressing traditional hardware-centric business models toward software-subscription architectures.
Photon-counting CT detectors is decomposing the conventional energy-integrating detector supply chain. University hospitals in Lyon and Paris-Saclay are piloting these systems for cardiac and pediatric applications where dose reduction is critical. The technology is decomposing vendor margins on contrast media by enabling spectral imaging that reduces iodine dosage requirements.
France's CNIL and HAS have jointly issued guidance on patient data governance for cloud-connected imaging devices, creating a dual-track compliance framework unique within Europe. This regulatory architecture favors vendors with established French data residency infrastructure over those relying on pan-European cloud hosting. Private diagnostic chains are responding by negotiating dedicated hosting agreements with domestic data center operators.
Public hospital procurement committees are consolidating vendor relationships around integrated service contracts that bundle equipment, software, and remote maintenance. This buying-pattern shift displaces the traditional capital-purchase model and favors vendors with French-based technical service networks. The transition is most visible in the Grand Est and Hauts-de-France regions where hospital group mergers have concentrated purchasing authority.
France Digital Radiology Market Segmentation
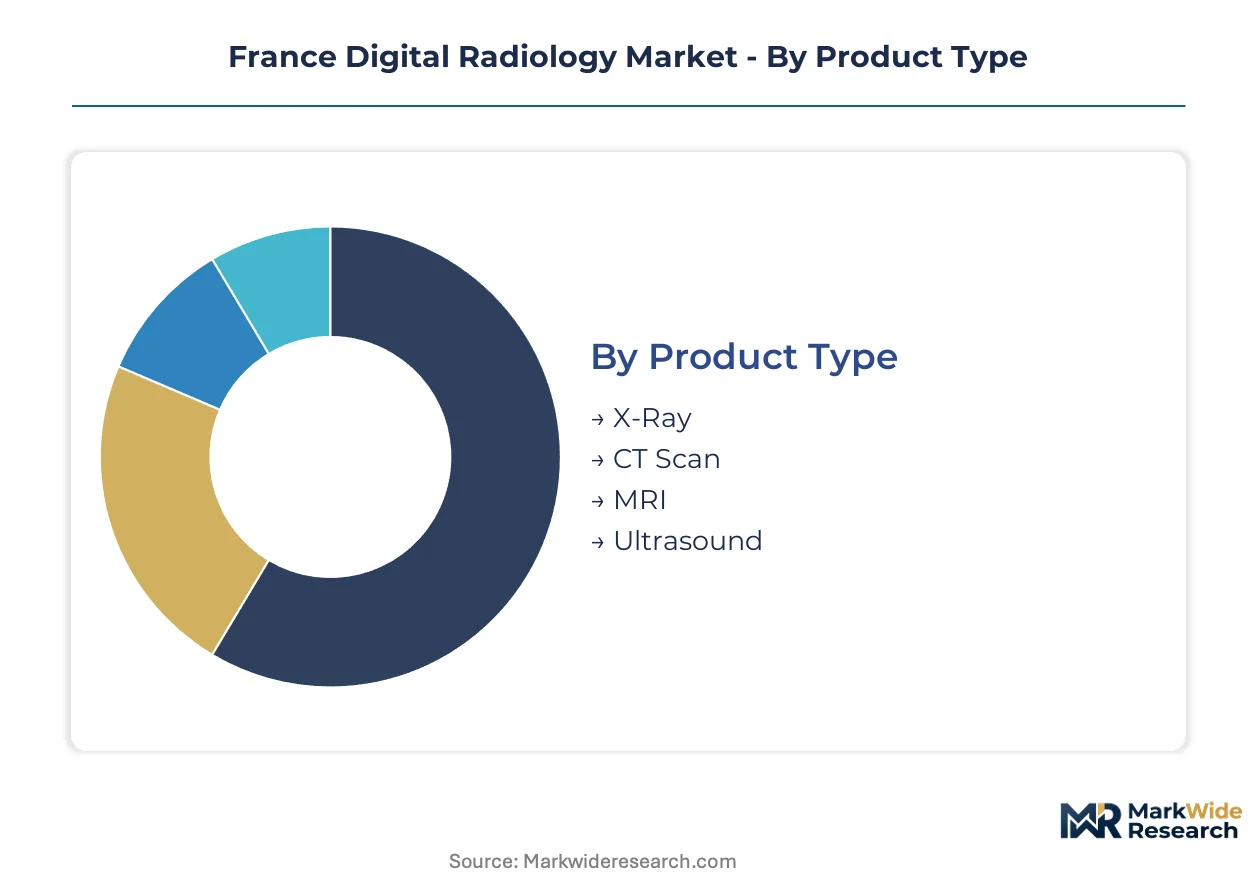
France's digital radiology market segments around regulatory compliance pathways and clinical throughput requirements. HAS reimbursement tiers and CNIL data governance standards create divergent commercial dynamics across product categories.
Product Type:
Regulatory differentiation under the EU MDR framework shapes competitive intensity across imaging modalities, with higher-risk classifications demanding extended clinical validation cycles.
- CT Scan:Photon-counting detector arrays deliver spectral imaging capabilities with dose efficiency gains exceeding 30% over energy-integrating predecessors. Paris-Saclay university hospitals anchor procurement volume for cardiac and oncology applications where HAS fast-tracks reimbursement alignment.
- X-Ray:Direct radiography panels with cesium iodide scintillators achieve spatial resolution above 3.5 line pairs per millimeter. Emergency departments in Lyon biomedical corridor drive replacement demand as computed radiography cassettes face interoperability deadlines under Ségur du Numérique en Santé.
- MRI:Superconducting systems with 1.5T and 3T field strengths serve neurovascular and musculoskeletal diagnostic protocols.
- Ultrasound:Portable systems with shear-wave elastography expand point-of-care deployment in rural clinic networks.
Established volume favors CT Scan; emerging adoption favors Ultrasound.
Technology:
Cost tier stratification separates capital-intensive detector upgrades from software-native platforms that leverage existing infrastructure.
- Cloud-Based Imaging:Vendor-neutral archives with DICOMweb APIs enable multi-site image sharing across hospital group mergers. Auvergne-Rhône-Alpes teleradiology networks adopt these platforms to address radiologist workforce scarcity while meeting CNIL data residency requirements.
- Direct Radiography:Amorphous selenium and silicon flat-panel detectors eliminate cassette handling delays. Public hospital procurement committees in Grand Est prioritize these systems for throughput gains in high-volume screening programs.
- Computed Radiography:Photostimulable phosphor plate systems face accelerated replacement cycles.
- 3D Imaging:Cone-beam CT and digital tomosynthesis extend diagnostic depth in orthopedic and dental applications.
Replacement urgency favors Direct Radiography; interoperability mandates favor Cloud-Based Imaging.
End User:
Customer type determines procurement authority concentration and service contract structures across France's healthcare delivery system.
- Hospitals:Public hospital networks consolidate purchasing through regional health agencies, negotiating integrated equipment-software-maintenance bundles. Outcome-based reimbursement pilots in Hauts-de-France compress capital cycles while favoring vendors with French-based technical service presence.
- Diagnostic Centers:Private chains rotate toward high-throughput suites as public procurement tightens. These operators negotiate dedicated CNIL-compliant hosting agreements with domestic data center operators to support multi-site image sharing.
- Clinics:Rural facilities in Occitanie depend on teleradiology connectivity to urban reading centers.
- Research Institutes:Paris-Saclay and Lyon clusters pilot photon-counting CT for dose-reduction validation studies.
Procurement scale favors Hospitals; margin expansion favors Diagnostic Centers.
Application:
Clinical volume concentration and screening program mandates create divergent technology requirements across therapeutic areas.
- Oncology:CT and MRI systems with perfusion and diffusion-weighted imaging protocols support tumor staging and treatment response monitoring. France's national cancer plan drives throughput requirements in public hospital networks with dedicated imaging suites for radiation therapy planning.
- Cardiology:Coronary CT angiography with photon-counting detectors reduces iodinated contrast dosage while maintaining diagnostic accuracy. Lyon university hospitals pilot these systems for pediatric congenital heart disease protocols where dose minimization is critical.
- Orthopedics:Weight-bearing CT and digital tomosynthesis advance musculoskeletal trauma assessment.
- Pediatrics:Low-dose protocols and child-appropriate positioning systems address specific safety requirements.
Screening program scale favors Oncology; technology upgrade intensity favors Cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's high-speed rail network and fiber-optic health data backbone underpin regional digital radiology deployment patterns. The Ségur du Numérique en Santé program mandates cloud interoperability standards that reshape capital allocation across metropolitan and peripheral healthcare systems.
Île-de-France
Paris-Saclay university hospitals anchor procurement volume for photon-counting CT systems. HAS fast-tracks reimbursement alignment for cardiac and pediatric applications where dose reduction protocols are critical. The Paris biomedical cluster concentrates vendor technical service networks and radiologist training pipelines.
Auvergne-Rhône-Alpes
Lyon university hospitals pilot spectral imaging for congenital heart disease protocols. CNIL data residency requirements complicate multi-site image sharing architectures across this cross-border region. Teleradiology networks connect rural clinics in Isère and Savoie to urban reading centers.
Hauts-de-France
Hospital group mergers in Lille and Amiens consolidate purchasing authority around integrated equipment-software-maintenance bundles. Outcome-based reimbursement pilots compress replacement cycles for digital radiography systems. The region's aging industrial infrastructure strains capital budgets for imaging suite upgrades.
Occitanie
Rural clinic networks in Languedoc-Roussillon depend on cloud-based image transmission to Montpellier and Toulouse reading centers. Ségur du Numérique en Santé interoperability deadlines force accelerated replacement of computed radiography cassettes. Private diagnostic chains negotiate dedicated hosting agreements with domestic data center operators.
Grand Est
Public hospital procurement committees prioritize throughput gains in high-volume screening programs across Strasbourg and Nancy. Direct radiography panels displace legacy systems in emergency departments. Regional health agencies centralize vendor relationship management for university hospital networks.
France Digital Radiology Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that bundle hardware, software, and service contracts. Three archetypes define competitive positioning: integrated imaging platform vendors, specialized detector technology developers, and cloud-native workflow providers. Dominant moves include portfolio diversification into AI-augmented detection algorithms and strategic partnerships with French data center operators for CNIL-compliant hosting infrastructure.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Koninklijke Philips occupy positions that exemplify the integrated platform archetype. These vendors leverage installed bases across France's university hospital network to anchor long-term service relationships. GE Healthcare represents the North American diversified model, Siemens Healthineers exemplifies German engineering-intensive positioning in photon-counting detector development, and Philips sits within the Dutch workflow integration tradition with cloud-native architectures connecting urban hospitals to rural clinics.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Agfa HealthCare |
| DMS Imaging |
| Others |
Pricing and Supply Chain Analysis
Photon-counting detector arrays replacing energy-integrating predecessors simultaneously concentrate supply geography in German and Japanese precision manufacturing corridors while compressing pricing economics for contrast media bundles. This substitution dynamic redirects procurement negotiations toward spectral imaging capabilities that reduce iodine dosage requirements.
Pricing Analysis
Volume-discount tiering structures separate premium photon-counting CT configurations from standard energy-integrating systems and economy-level computed radiography replacements. Price differentiation hinges on HAS fast-track certification status and bundled after-sales service contracts. Pricing pressure stems from public hospital outcome-based reimbursement pilots stretching capital cycles. Diagnostic centers exhibit highest price sensitivity due to squeezed margins, while research institutes prioritize performance over cost.
Supply Chain Analysis
Extended lead times for amorphous selenium flat-panel detectors strain inventory planning across French hospital procurement committees. Manufacturing concentrates in Germany, Japan, and the Netherlands for precision detector components. Supply chains draw from rare earth elements for scintillator crystals and specialized semiconductor substrates. Single-source vulnerability persists for photon-counting detector arrays. Distribution runs through authorized service networks with French-based technical presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's digital radiology market sits at a platform-economics inflection where Ségur du Numérique en Santé interoperability mandates transform hardware vendors into software-subscription platforms. This ecosystem shift favors vendors controlling cloud-native workflow architectures over proprietary PACS lock-in.
For Market Incumbents: Shield installed base relationships through accelerated API openness that preempts HAS interoperability deadlines. Consolidate French-based technical service networks to capture integrated equipment-software-maintenance bundles. Counter emerging cloud-native entrants by embedding AI-augmented detection algorithms into direct radiography systems. For New Entrants and Emerging Players: Rural teleradiology connectivity gaps in Auvergne-Rhône-Alpes and Occitanie offer white-space entry where incumbent service networks remain thin. Target cloud-native image transmission platforms for clinic-to-urban-reading-center workflows. Pursue CNIL-compliant hosting partnerships with domestic data center operators as primary go-to-market credential. For Investors and Strategic Acquirers: Ségur du Numérique en Santé's 2025 deadline reshapes the acquisition landscape toward interoperability-ready software assets over pure hardware plays. Long-term viability centers on recurring revenue models with sticky hospital system integrations. Target acquisition archetypes include AI-augmented workflow developers with HAS validation pathways. Watch radiologist workforce scarcity metrics as demand inflection signal for teleradiology infrastructure plays.| Strategic Initiative | Industry Significance |
|---|---|
| CNIL-Compliant Cloud Hosting Partnership | Domestic data residency infrastructure satisfies France's dual-track compliance framework for multi-site image sharing. |
| AI-Augmented Detection Algorithm Integration | Computer-aided triage tools address projected radiologist shortages while embedding into emergency department workflows. |
| HAS Fast-Track Certification Investment | Accelerated reimbursement alignment compresses time-to-market from 24 months to 14 months for novel modalities. |
| Open-API Platform Development | Data portability architectures capture procurement preference under Ségur du Numérique en Santé interoperability mandates. |
| French Technical Service Network Expansion | Localized maintenance presence wins integrated bundle contracts from consolidating hospital group mergers. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement committee chairs, biomedical engineering directors, radiology department heads, and GPO contracts managers and refined through secondary validation against HAS reimbursement databases, CNIL guidance documents, hospital equipment procurement records, and EU MDR registration filings. Bottom-up demand modeling triangulated against top-down market sizing across detector technology vintages.
Variance-decomposition framing isolated volume drivers across product type, technology architecture, end-user procurement authority, and clinical application segments. CAGRs were derived from replacement cycle compression effects and interoperability mandate deadlines. Forecast inputs incorporated radiologist workforce projections and Ségur du Numérique en Santé compliance timelines.
Underlying assumptions cover sustained public hospital capital allocation and HAS reimbursement pathway stability, with deviation risk concentrated in EU MDR registration timeline extensions and CNIL data governance enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Digital Radiology Market
Medical Imaging
South Korea Mammography Market