
 Medical Image Exchange System Market | 2026-2036
Medical Image Exchange System Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Image Exchange System Market Analytics
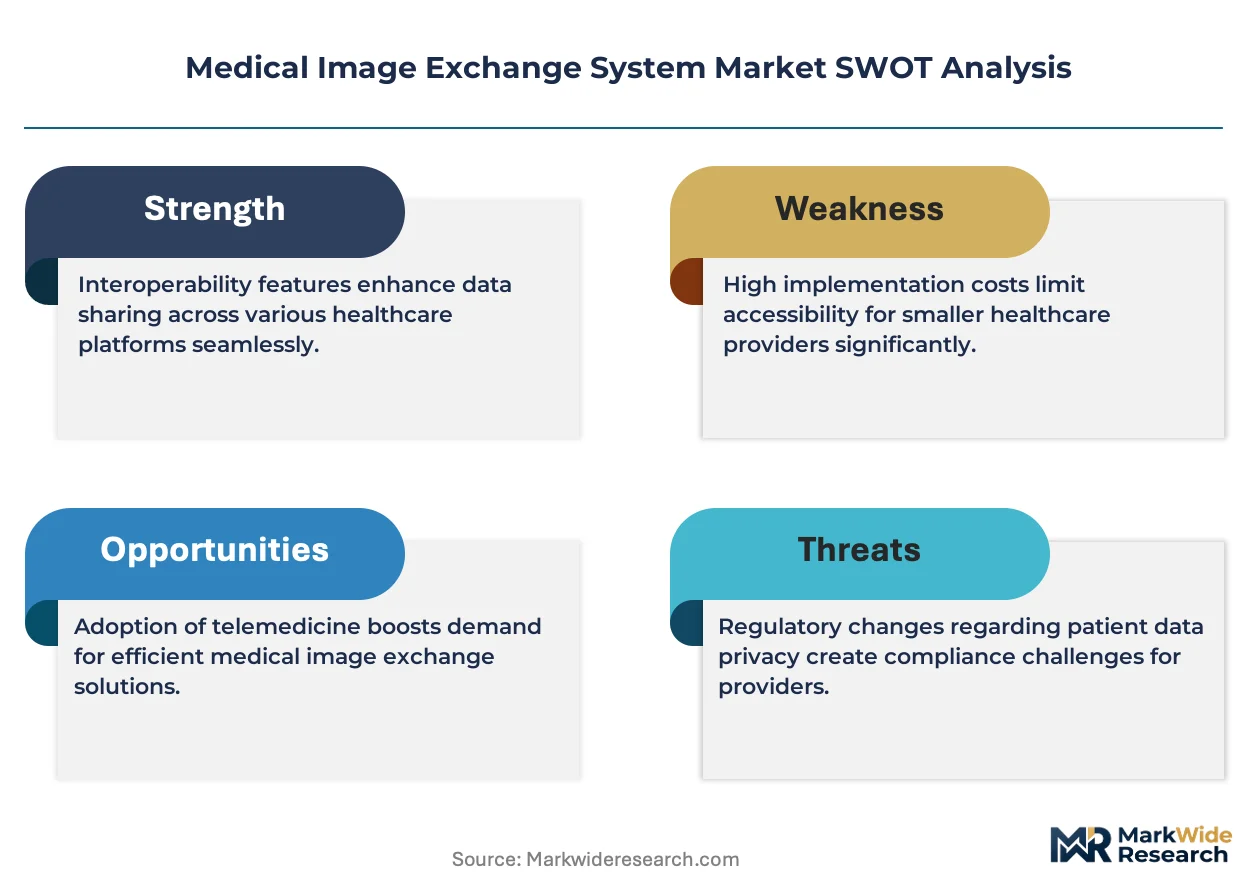
HIPAA interoperability enforcement is hardening data-exchange compliance costs for new entrants. GE HealthCare leverages its installed base of imaging modalities to anchor enterprise exchange contracts. Siemens Healthineers differentiates through embedded AI workflows that streamline radiology handoffs. Koninklijke Philips N.V. sustains channel control via deep integration with its diagnostic monitoring ecosystem.
A medical image exchange system is a networked software platform that transmits, stores, and retrieves diagnostic imaging files using DICOM, HL7, and FHIR protocols to enable clinical collaboration across disparate care settings. Cloud-based deployments now lead product type adoption as health systems offload capital-intensive PACS infrastructure. Diagnostic centers represent the fastest-growing end user segment, driven by teleradiology outsourcing and multi-site referral networks. FHIR-enabled technology layers are capturing margin pools by replacing legacy HL7 interfaces with modern, API-first architectures.
FDA 21st Century Cures Act mandates and HIPAA Security Rule requirements shape vendor roadmaps by penalizing information blocking and mandating audit-grade access controls. The Office of the National Coordinator for Health IT certifies compliant exchange frameworks, creating a de facto gatekeeping function for market access. Stakeholders must monitor whether emerging state-level privacy laws fragment compliance obligations beyond federal baselines.
Market Dynamics
Cloud migration is compressing capital cycles for diagnostic imaging infrastructure as health systems abandon on-premise PACS architectures in favor of subscription-based exchange platforms.
Growth Catalysts
- FHIR API mandates:The Office of the National Coordinator for Health IT certification requirements accelerate vendor consolidation toward interoperable frameworks. Hospitals face penalties for information blocking.
- Diagnostic center networks:Multi-site teleradiology outsourcing creates demand for centralized image repositories that span ambulatory, inpatient, and remote reading locations.
- AI-augmented workflows:Embedded machine learning for automated study routing and priority triage reduces radiologist turnaround times in high-volume settings.
Market Restraints
- HIPAA compliance costs:Audit-grade access controls and breach notification requirements impose disproportionate burdens on smaller exchange vendors entering the market.
- Legacy HL7 interface persistence:Technical debt from decades-old health information systems slows FHIR-native platform deployment in established health systems.
- Data localization requirements:Emerging state-level privacy laws fragment cloud hosting strategies beyond federal HIPAA baselines, complicating multi-tenant architectures.
Strategic Opportunities
- Rural health networks:Federally qualified health centers in underserved counties lack dedicated radiology staff and represent untapped demand for cloud-based exchange services.
- Integrated delivery network consolidation:Enterprise-wide image exchange deployments across acquired hospitals create vendor lock-in potential for platform providers.
- Edge computing convergence:On-premise inference engines combined with cloud storage architectures address latency-sensitive use cases in trauma and stroke care.
Industry Challenges
- DICOM standard evolution:Version migration complexities and vendor-specific extensions create integration friction during multi-modality deployments.
- Cybersecurity workforce scarcity:Health system security operations centers struggle to recruit talent capable of managing zero-trust architectures for imaging data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Image Exchange System Market |
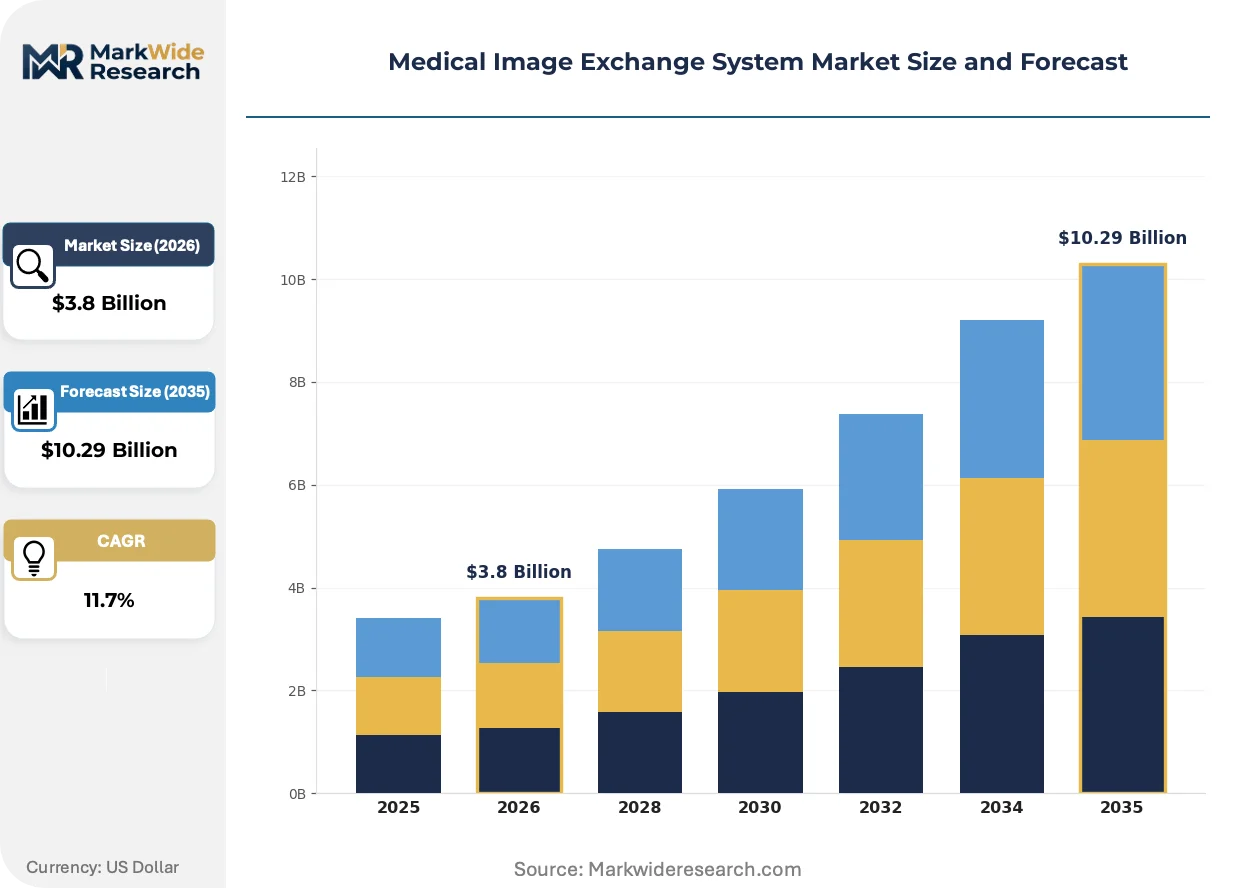
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Mobile End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: DICOM, HL7, PACS, FHIR Application: Telemedicine, Workflow Management, Data Storage, Image Sharing |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Siemens Healthineers, FUJIFILM, Sectra AB, eHealth Technologies, Intelerad, Merative, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Image Exchange System Market Evolving Landscape
Vendor roadmaps are converging on API-first architectures that displace point-to-point interface engines. This shift compresses implementation timelines and enables modular service consumption.
Fast Healthcare Interoperability Resources (FHIR) is unifying previously siloed imaging, clinical, and administrative data streams into single queryable resources. Health systems with mature digital strategies are adopting R4 and R5 specifications aggressively. This unification collapses the traditional separation between PACS, VNA, and EMR data models, forcing infrastructure vendors to reposition around platform rather than product boundaries.
The FDA's 21st Century Cures Act information blocking provisions are reshaping competitive dynamics by penalizing data withholding. Enforcement actions against non-compliant vendors have accelerated since 2023. Radiology groups and hospital IT departments now prioritize exchange platforms with certified compliance frameworks over feature-rich but proprietary alternatives.
Subscription pricing for cloud-native exchange services is displacing perpetual license models in procurement cycles. Hospital capital committees prefer operational expenditure treatment for infrastructure that scales with imaging volume. This preference is most pronounced among mid-size health systems with constrained IT depreciation budgets and unpredictable study growth patterns.
Medical Image Exchange System Market Segmentation
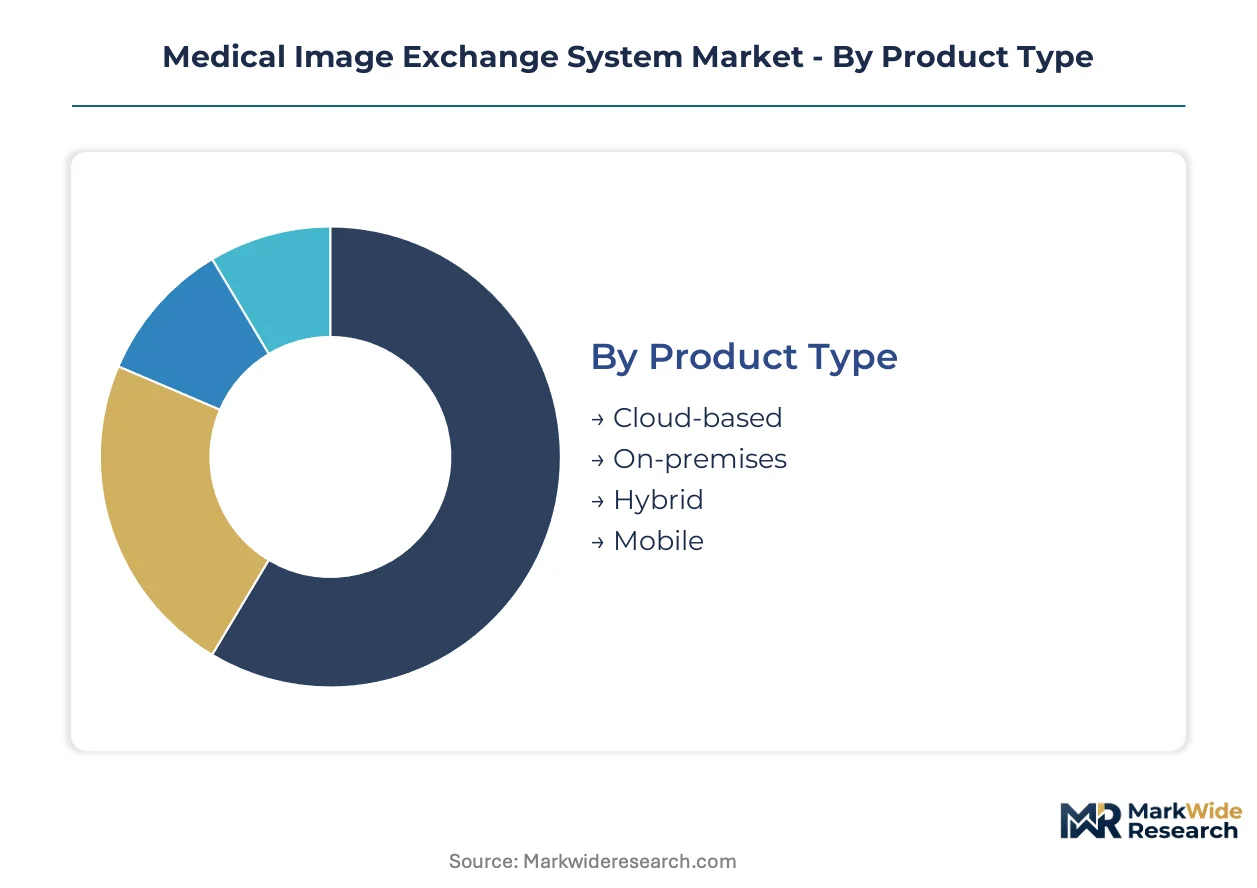
Segmentation in medical image exchange systems reveals how procurement priorities diverge across infrastructure maturity levels. Cloud-native platforms command premium positioning in integrated delivery networks, while legacy-dependent segments sustain entrenched vendor relationships through high switching costs.
Product Type:
Supply concentration favors vendors with hyperscale cloud infrastructure that can absorb compliance certification costs across multi-tenant deployments.
- Cloud-based:Multi-tenant architectures deliver diagnostic imaging via subscription models, eliminating capital-intensive PACS hardware procurement. United States health systems with constrained IT depreciation budgets concentrate demand here, driven by HIPAA Security Rule audit requirements that favor vendor-managed security operations centers.
- Hybrid:Combines on-premise inference engines with cloud storage tiers to address latency-sensitive trauma and stroke workflows while offloading archival capacity. Academic medical centers with mixed legacy-modern infrastructure drive adoption, constrained by fragmented data localization mandates across state boundaries.
- On-premises:Self-hosted PACS deployments retain relevance in defense and correctional health settings with air-gapped security requirements.
- Mobile:Smartphone-optimized viewers extend radiologist access to emergency consultations outside fixed reading rooms.
Today's leader: Cloud-based. Tomorrow's challenger: Hybrid.
End User:
Cost tier differentiation separates enterprise-wide deployments from point solutions, with procurement authority residing at health system headquarters rather than individual facilities.
- Diagnostic Centers:Multi-site teleradiology networks require centralized image repositories spanning ambulatory, inpatient, and remote reading locations. Outsourced radiology groups in the United States drive volume, constrained by HIPAA breach notification liabilities that favor vendor-provided cyber insurance.
- Hospitals:Enterprise image exchange deployments across acquired facilities create vendor lock-in potential through deep EMR integration. Integrated delivery networks prioritize platforms with FDA 21st Century Cures Act certification to avoid information blocking penalties.
- Clinics:Federally qualified health centers in underserved counties represent expanding demand for cloud-based exchange services without dedicated radiology staff.
- Research Institutions:Clinical trial imaging repositories require de-identification pipelines and multi-site data federation capabilities.
Diagnostic Centers are gaining share fastest. Hospitals retain the deepest contract values.
Technology:
Application architecture determines margin capture, with API-first protocols displacing legacy interface engines and collapsing implementation timelines.
- FHIR:Modern, API-first resource specifications unify imaging, clinical, and administrative data streams into single queryable endpoints. Health systems with mature digital strategies in the United States drive R4 and R5 adoption, accelerated by Office of the National Coordinator for Health IT certification mandates.
- DICOM:The foundational imaging protocol persists across all modalities but creates integration friction through version migration complexities and vendor-specific extensions.
- HL7:Decades-old interface engines sustain technical debt in established health systems, slowing FHIR-native platform deployment.
- PACS:Traditional picture archiving systems anchor radiology department workflows but face displacement by vendor-neutral archive architectures.
FHIR commands the steepest expansion trajectory. DICOM maintains protocol ubiquity.
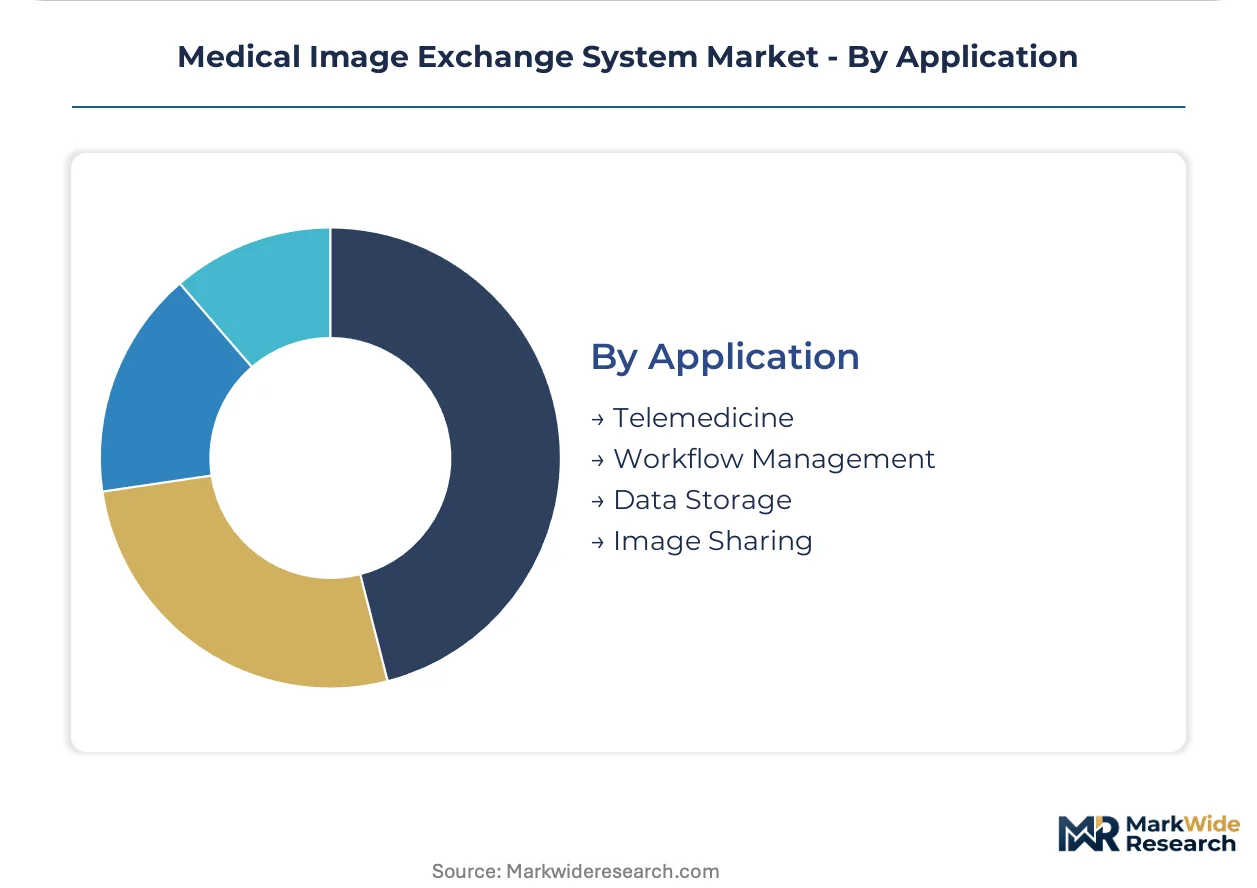
Application:
Customer type segmentation separates clinical workflow tools from infrastructure services, with procurement committees evaluating operational expenditure treatment against capital allocation flexibility.
- Workflow Management:Embedded AI for automated study routing and priority triage reduces radiologist turnaround times in high-volume settings. Large radiology groups in the United States concentrate demand, driven by malpractice risk mitigation through documented turnaround compliance.
- Telemedicine:Real-time image transmission enables remote specialist consultation for stroke and trauma cases. Rural health networks lacking on-site radiology coverage drive adoption, constrained by broadband infrastructure gaps in frontier counties.
- Image Sharing:Cross-enterprise exchange for multi-site referral networks requires patient-matching algorithms and consent management frameworks.
- Data Storage:Long-term archival with lifecycle policies addresses retention requirements for pediatric and oncology imaging.
Workflow Management dominates current procurement. Telemedicine shows the strongest forward momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologist workforce density and teleradiology network maturity anchor geographic demand patterns. Cloud infrastructure investment and regulatory certification timelines shape vendor prioritization across markets.
United States
Integrated delivery networks drive enterprise-wide FHIR-enabled deployments across acquired hospital systems. The FDA's 21st Century Cures Act information blocking penalties accelerate procurement of certified exchange platforms. The Greater Boston corridor concentrates AI-augmented workflow development for stroke and trauma triage.
Germany
Academic medical centers with mixed legacy-modern infrastructure anchor hybrid deployment demand for latency-sensitive workflows. The national implementation of the Electronic Health Act (E-Health-Gesetz) mandates interoperability standards for cross-facility image exchange. The Rhine-Ruhr metropolitan region sustains dense diagnostic center networks requiring centralized multi-site repositories.
United Kingdom
NHS England's imaging transformation programs consolidate PACS contracts toward cloud-native vendor-neutral archives. The National Institute for Health and Care Excellence (NICE) guidelines prioritize turnaround time metrics that favor automated routing platforms. London's digital health cluster incubates FHIR-native startups targeting radiology workflow optimization.
Japan
Aging demographics and rural hospital consolidation create demand for remote diagnostic consultation infrastructure. The Pharmaceuticals and Medical Devices Agency (PMDA) software-as-a-medical-device guidance shapes AI-embedded exchange platform approvals. The Kansai region's medical device manufacturing base supplies imaging modalities requiring integrated exchange connectivity.
India
Diagnostic center chains in tier-2 and tier-3 cities drive teleradiology outsourcing volume without on-site radiologist presence. The Digital Information Security in Healthcare Act (DISHA) pending implementation raises data localization compliance stakes for cloud-hosted platforms. Hyderabad's health technology corridor hosts development centers for DICOM-to-FHIR conversion middleware.
Medical Image Exchange System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment archetypes. Market structure tilts toward consolidation as certification burdens and cloud infrastructure scale requirements disadvantage smaller entrants. Three strategic archetypes dominate: imaging modality manufacturers extending into exchange software, independent software vendors with workflow-centric positioning, and cloud hyperscalers partnering for healthcare verticalization. M&A activity concentrates on FHIR-native platform acquisitions and regional teleradiology network consolidation.
Within the diversified medical technology tier, GE HealthCare and Koninklijke Philips N.V. occupy positions anchored by installed imaging modality bases. Siemens Healthineers exemplifies the AI-embedded workflow differentiation archetype. These three conglomerates represent the consolidation pressure facing standalone exchange vendors without captive hardware relationships.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| FUJIFILM |
| Sectra AB |
| eHealth Technologies |
| Intelerad |
| Merative |
| Agfa-Gevaert Group |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud infrastructure pricing indices cascade through medical image exchange supply chains, compressing SaaS subscription tiers as vendors absorb multi-tenant compliance certification costs across United States health systems and European academic medical centers.
Pricing Analysis
Bundled platform services versus unbundled modular components split procurement decisions across integrated delivery networks. Subscription-based SaaS tiers dominate, with price differentiation resting on FHIR certification grade and AI workflow depth. Cost compression in mid-market segments intensifies as cloud hyperscalers enter healthcare verticalization partnerships. Federally qualified health centers exhibit highest price sensitivity; enterprise IDNs prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Cybersecurity workforce scarcity in United States and German manufacturing geographies constrains vendor-managed security operations center scaling. Cloud infrastructure draws from hyperscale data center clusters in Virginia, Frankfurt, and Singapore. DICOM-to-FHIR conversion middleware and GPU compute for AI inference represent critical input dependencies. Single-source vulnerability concentrates in specialized health IT certification auditors. Distribution runs through direct enterprise sales with GPO channel partnerships for mid-size health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical image exchange markets function as geographic-arbitrage plays where HIPAA compliance cost differentials between United States and Indian development centers create margin expansion opportunities for vendors with distributed engineering footprints.
For Market Incumbents: Lock in enterprise-wide image exchange deployments across acquired hospital systems to anchor vendor relationships before FHIR-native competitors achieve ONC certification. Deepen EMR integration moats to defend against cloud hyperscaler verticalization. Prioritize AI-embedded workflow R&D to maintain radiologist productivity differentiation against pure-play specialists. For New Entrants and Emerging Players: FDA 21st Century Cures Act information blocking enforcement in the United States opens a window for certified compliance-first platforms to displace legacy HL7-dependent incumbents. Target rural health networks lacking dedicated radiology staff as the most penetrable segment. Pursue teleradiology outsourcing partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with FHIR-native workflow specialists possessing ONC certification and established diagnostic center channel relationships. Five-to-ten year viability favors platforms with demonstrated AI inference integration rather than archival storage pure-plays. Monitor FDA enforcement action frequency against information blocking as the critical inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Investment | ONC certification mandates from the Office of the National Coordinator for Health IT create de facto market access gates. |
| Diagnostic Center Network Partnership | Multi-site teleradiology outsourcing contracts concentrate procurement authority with radiology group headquarters. |
| AI Workflow Integration | Embedded machine learning for automated study routing reduces radiologist turnaround times in high-volume settings. |
| Cloud Infrastructure Partnership | Hyperscaler healthcare verticalization programs compress capital requirements for multi-tenant security operations. |
| Rural Health Network Expansion | Federally qualified health centers in underserved counties represent untapped demand without dedicated radiology staff. |
Research Methodology
Multiple input streams — structured interviews with hospital CIOs and radiology group practice administrators, GPO contract database analysis, and FDA 510(k) filing review — were reconciled against secondary validation from CMS Medicare imaging utilization data, ONC certification registries, and hyperscaler healthcare verticalization disclosures. Bottom-up health system procurement tracking and top-down vendor revenue triangulation anchored market sizing.
Historical deployment trajectories cross-referenced against panel input from biomedical engineers and teleradiology network operators shaped the analytical framework across the projection horizon. Segmentation modeling incorporated deployment architecture, end-user scale tier, technology protocol maturity, and application workflow type. CAGRs derived from fitted adoption curves weighted by HIPAA compliance cost escalation and cloud infrastructure price deflation trajectories.
Revisions become necessary when FDA information blocking enforcement intensity shifts, state-level data localization mandates proliferate beyond federal baselines, or radiologist workforce shortages accelerate teleradiology outsourcing concentration. Material deviation in these triggers warrants pause and re-evaluation of vendor consolidation timelines and cloud migration velocity assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
South America MRI Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Global Veterinary X-Ray Market