
 Australia Mammography Market | 2026-2036
Australia Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Mammography Market Analysis
The Australian Radiation Protection and Nuclear Safety Agency's mandatory accreditation standards for mammography equipment is consolidating procurement criteria toward higher-sensitivity digital systems. Hologic Inc. leverages its integrated density assessment software to anchor contracts with BreastScreen Australia screening programs. GE Healthcare competes through extended service agreements that sustain long-term equipment utilization rates across Queensland and Western Australia hospital networks.
Mammography encompasses X-ray imaging of breast tissue using low-dose ionizing radiation, with modern systems employing tungsten-rhodium target filters and selenium-based digital detectors to achieve spatial resolution below 100 micrometers for early lesion detection. Digital mammography dominates installed base value due to Medicare reimbursement alignment and radiologist workflow efficiency, while 3D mammography represents the fastest-growing product category as private diagnostic centers in Sydney and Melbourne pursue tomosynthesis capabilities to reduce callback rates. Screening technology occupies the largest volume share through population-based program mandates, though diagnostic technology commands premium pricing due to targeted biopsy guidance requirements.
TGA medical device classifications and the Royal Australian and New Zealand College of Radiologists' quality assurance protocols shape equipment specifications and facility accreditation requirements across all states. The Department of Health and Aged Care's periodic review of BreastScreen Australia program parameters directly influences national procurement timing and technology refresh budgets. Stakeholders must monitor state-level health infrastructure commitments and radiologist workforce distribution to align deployment strategies with actual service capacity expansion.
Market Dynamics
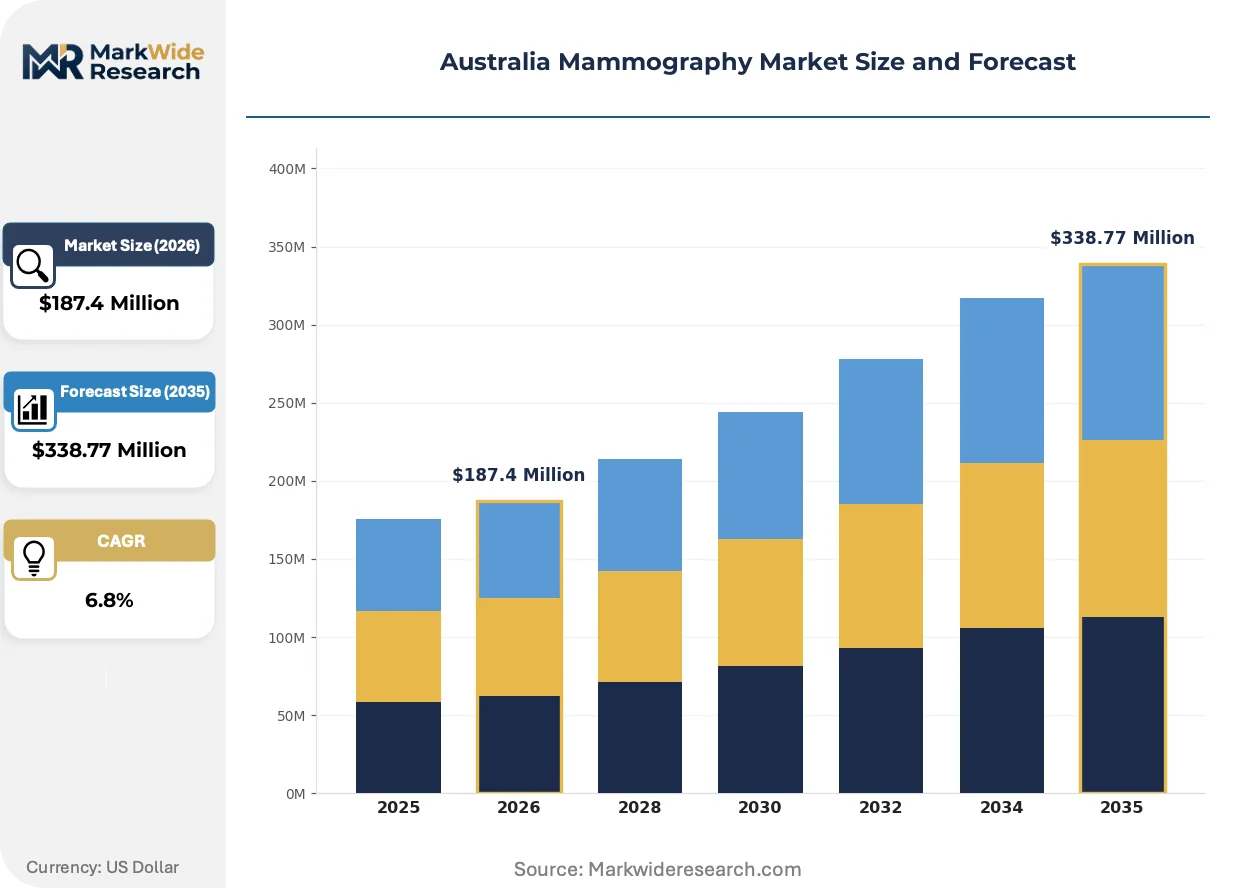
Digital breast tomosynthesis is consolidating procurement decisions across Australian diagnostic networks, compressing replacement cycles for analog and 2D systems while TGA registration pathways accelerate validation timelines for new entrants.
Growth Catalysts
- BreastScreen Australia age-eligibility expansions:Program parameter reviews by the Department of Health and Aged Care are extending screening invitations to broader demographic cohorts, stimulating equipment capacity additions across state hospital networks.
- TGA device registration pathways:Streamlined conformity assessment procedures for Class IIa medical devices are reducing time-to-market for digital mammography systems, enabling faster technology refresh cycles in metropolitan diagnostic centers.
- Selenium-based digital detectors:Advances in direct-conversion detector materials are improving dose efficiency and spatial resolution thresholds, aligning with ARPANSA mandatory accreditation standards for higher-sensitivity imaging.
Market Restraints
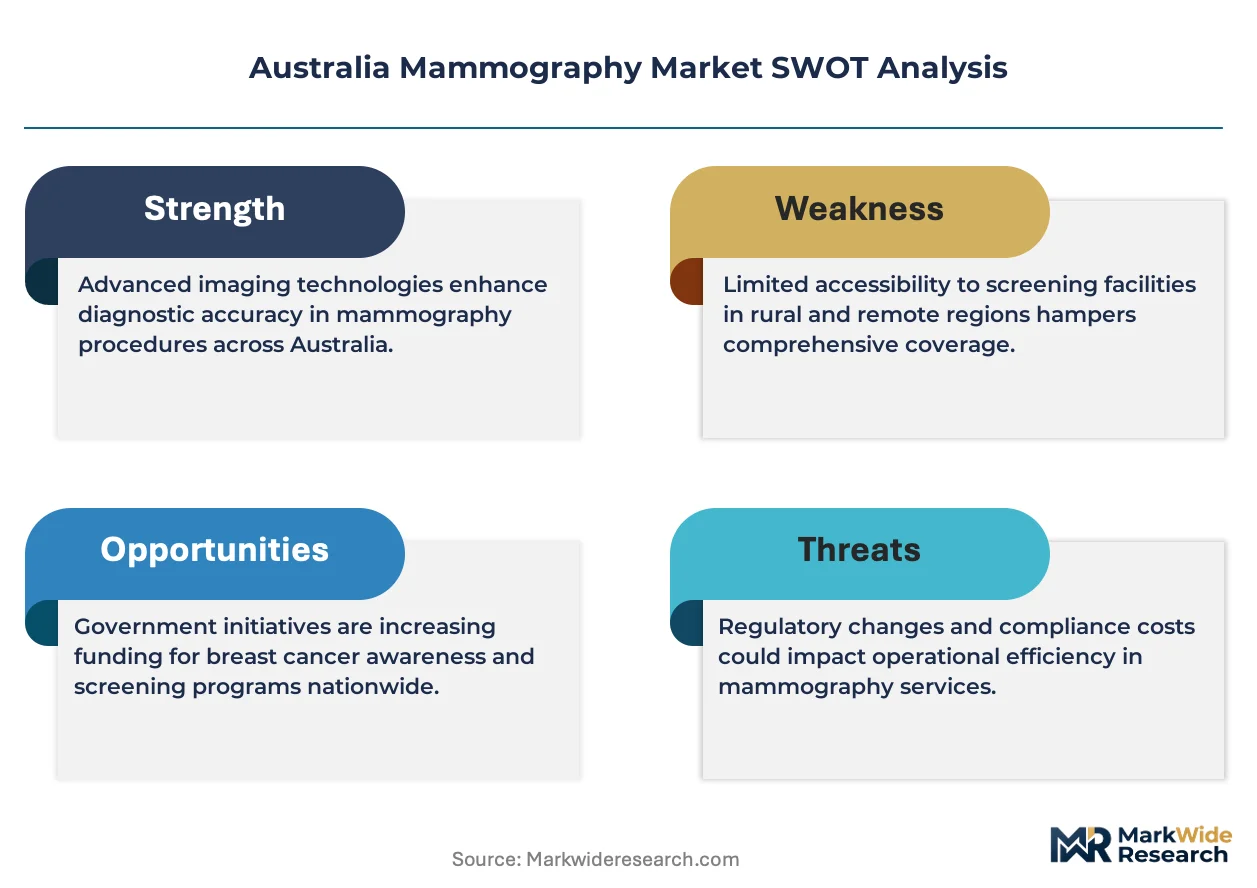
- Radiologist workforce concentration:Specialist distribution skews toward Sydney and Melbourne, creating service delivery constraints for regional Queensland and Western Australia expansion plans.
- Tungsten-rhodium target filter supply:Specialized X-ray tube component manufacturing concentrates among limited global suppliers, exposing procurement timelines to input availability volatility.
- Medicare reimbursement alignment:Fee schedule structures for 2D mammography create pricing friction against 3D tomosynthesis adoption in private diagnostic settings.
Strategic Opportunities
- Regional New South Wales network expansion:Public hospital infrastructure commitments in Wollongong, Newcastle, and Albury-Wodonga clusters present untapped deployment potential for mobile screening units.
- Integrated density assessment software convergence:Automated breast density classification combined with AI-assisted lesion detection is opening workflow efficiency gains for high-volume screening programs.
- Extended service agreement innovation:Performance-based maintenance contracts spanning 7-10 year horizons are emerging as differentiated procurement evaluation criteria across Queensland Health tenders.
Industry Challenges
- Royal Australian and New Zealand College of Radiologists quality assurance protocols:Facility accreditation requirements mandate continuous phantom imaging and dose auditing, creating ongoing compliance overhead for smaller diagnostic operators.
- Legacy analog system integration:Hybrid workflow environments during transition periods to full digital infrastructure complicate radiologist training and image archiving standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Mammography Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Mammography, Digital Mammography, 3D Mammography, Breast MRI Technology: Screening, Diagnostic, Contrast-Enhanced, Automated End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Delivery Mode: Telemammography, On-Site Services, Mobile Units, Stationary Units |
| Companies Covered | GE Healthcare, Hologic Inc., Siemens Healthineers, Fujifilm Holdings Corporation, Koninklijke Philips NV, Canon Medical Systems Corporation, Carestream Health Inc., Volpara Health Limited, Planmed Oy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Mammography Market Emerging Trajectories
Three interconnected developments are reshaping equipment specifications and procurement evaluation frameworks across Australian mammography networks. These shifts reflect technical maturation, regulatory refinement, and evolving service delivery models.
Digital breast tomosynthesis is consolidating market positioning as the reference standard for diagnostic workups, with its core function of reconstructing three-dimensional breast architecture from multiple projection angles. Private diagnostic centers in Sydney and Melbourne are adopting this capability at accelerated pace to reduce callback rates from screening recalls. This technology is consolidating procurement decisions toward integrated 2D-3D platforms and compressing standalone 2D system viability in premium metropolitan markets.
TGA medical device classification revisions for software-as-a-medical-device are tightening validation requirements for AI-assisted lesion detection algorithms. Industrial consequence flows through to extended clinical evidence submission timelines for density assessment and computer-aided detection modules. Screening program procurement in Victoria and South Australia is most affected, with tender evaluations now weighting regulatory approval status more heavily than feature differentiation.
Service unbundling from capital equipment contracts is altering buyer-supplier relationships across state health procurement frameworks. Traditional bundled sale-plus-maintenance structures are yielding to separated equipment acquisition and independent service provider arrangements, particularly visible in Western Australia hospital network tenders. This pattern concentrates service capability development among specialized third-party technical firms while equipment vendors focus on system sales and software licensing.
Australia Mammography Market Segmentation
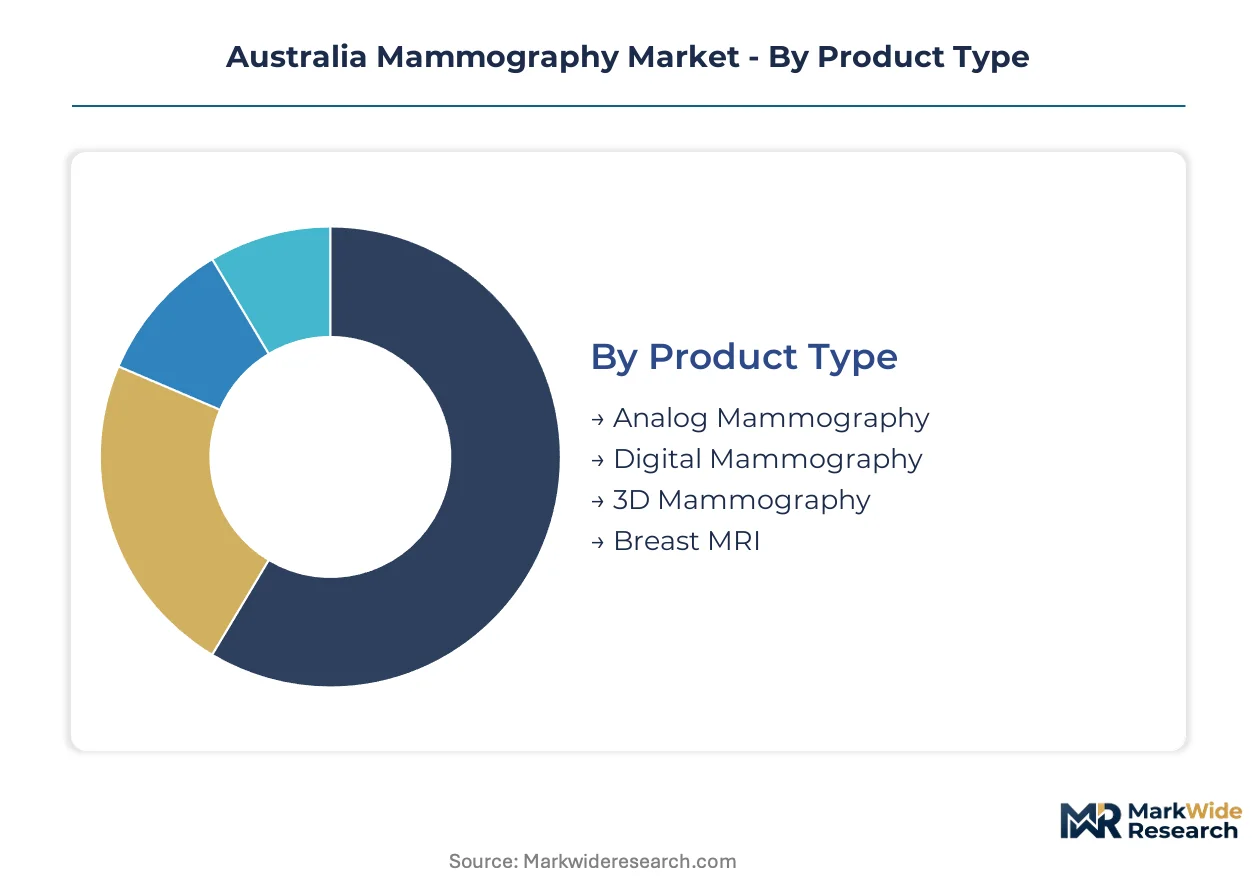
Mammography equipment procurement across Australia clusters around distinct technical specifications, clinical applications, and service delivery configurations. Understanding these segment boundaries clarifies how TGA registration pathways and BreastScreen Australia program mandates concentrate demand within specific product categories.
Product Type:
Supply concentration among detector manufacturers shapes procurement patterns across Australian diagnostic networks, with direct-conversion selenium arrays and indirect-conversion cesium iodide systems anchoring distinct performance tiers.
- Digital Mammography:Selenium-based direct-conversion detectors achieve spatial resolution below 100 micrometers with superior dose efficiency. Demand concentrates in metropolitan Sydney and Melbourne diagnostic centers replacing legacy analog infrastructure under Medicare reimbursement alignment.
- 3D Mammography:Digital breast tomosynthesis reconstructs three-dimensional breast architecture from multiple projection angles, reducing callback rates from screening recalls. Private diagnostic centers in New South Wales and Victoria pursue integrated 2D-3D platforms to differentiate service offerings.
- Analog Mammography:Legacy film-screen systems persist in regional Queensland and Western Australia facilities awaiting capital refresh cycles.
- Breast MRI:Supplementary imaging modality for high-risk patient stratification and dense breast tissue evaluation, deployed primarily in tertiary hospital networks.
Digital Mammography absorbs the bulk of installed capacity; 3D Mammography is expanding most quickly.
Technology:
Cost tier differentiation separates high-throughput screening workflows from premium diagnostic capabilities, with reimbursement structures determining viable technology deployment across public and private settings.
- Screening:Population-based program mandates drive volume deployment across BreastScreen Australia networks. Standardized protocols and centralized quality assurance enable economies of scale in equipment utilization.
- Diagnostic:Targeted biopsy guidance requirements command premium pricing, with stereotactic and ultrasound-guided capabilities essential for metropolitan referral centers.
- Contrast-Enhanced:Iodinated contrast protocols for lesion characterization in dense breast tissue, limited to specialized tertiary services.
- Automated:AI-assisted lesion detection and density classification software modules undergoing TGA software-as-a-medical-device validation.
Screening technology dominates procurement volume; Diagnostic applications capture premium value per procedure.
End User:
Customer type fragmentation across public hospital networks, private diagnostic chains, and research institutions creates divergent procurement evaluation criteria and contract structures.
- Hospitals:Public hospital networks in New South Wales and Victoria anchor BreastScreen Australia program delivery, with extended service agreements spanning 7-10 year horizons.
- Diagnostic Centers:Private operators in Sydney and Melbourne pursue tomosynthesis capabilities to reduce callback rates and attract insured patient volumes.
- Research Institutions:Clinical trial infrastructure and phantom imaging protocols for ARPANSA accreditation standards development.
- Outpatient Clinics:Community-based screening access points in regional Queensland and Western Australia.
Hospitals command the largest equipment deployment; Diagnostic Centers are gaining share fastest through private investment.
Delivery Mode:
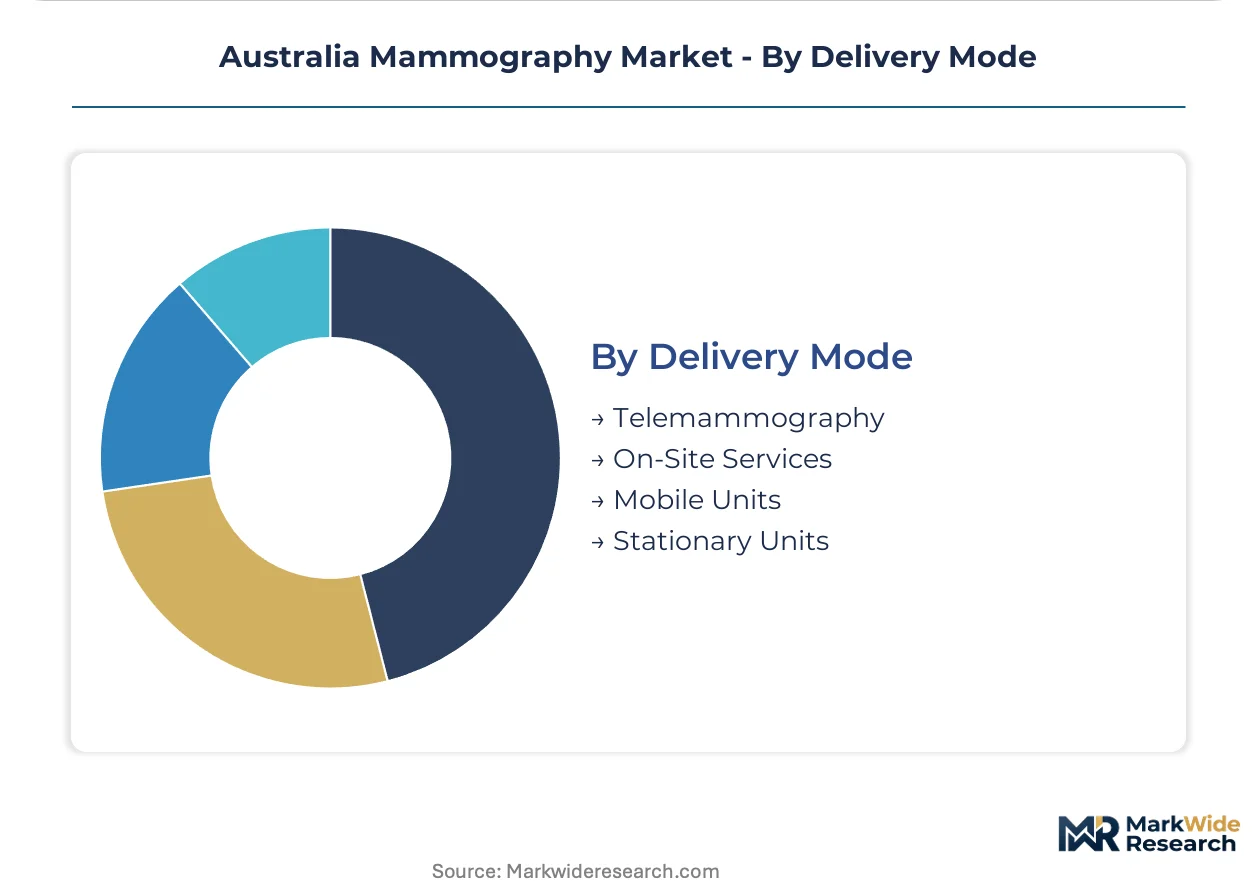
Geography-driven service configuration shapes mobile versus stationary deployment, with population dispersion across Australian states necessitating flexible screening access models.
- Mobile Units:Customized vehicles with self-contained power and climate systems extend screening access to regional New South Wales clusters including Wollongong, Newcastle, and Albury-Wodonga.
- Stationary Units:Fixed installations in metropolitan diagnostic centers and hospital radiology departments achieve highest throughput and image archiving standardization.
- Telemammography:Remote image transmission protocols enabling radiologist workforce concentration in Sydney and Melbourne to serve regional Queensland and Western Australia.
- On-Site Services:Equipment placement within integrated health campuses for immediate diagnostic workup and biopsy coordination.
Stationary Units absorb the bulk of capital investment; Mobile Units are expanding most quickly through regional network commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor mammography equipment procurement across Australia, with metropolitan diagnostic centers driving digital and 3D system upgrades while regional networks expand mobile screening access.
New South Wales
BreastScreen Australia program expansion targets Wollongong, Newcastle, and Albury-Wodonga clusters for mobile unit deployment. TGA device registration pathways accelerate validation timelines for new digital mammography systems entering Sydney hospital networks. Public hospital infrastructure commitments in these regional centers present untapped procurement potential for screening capacity additions.
Victoria
Melbourne diagnostic centers pursue integrated 2D-3D tomosynthesis platforms to reduce callback rates and attract insured patient volumes. The Royal Australian and New Zealand College of Radiologists' quality assurance protocols mandate continuous phantom imaging compliance across all accredited facilities. Private diagnostic chains in metropolitan Melbourne differentiate service offerings through premium diagnostic capabilities.
Queensland
Radiologist workforce concentration in Brisbane creates service delivery constraints for regional expansion plans across northern and western Queensland. Extended service agreements spanning 7-10 year horizons dominate Queensland Health tender evaluations for public hospital network procurement. Mobile screening units extend access to community-based outpatient clinics in dispersed regional populations.
Western Australia
Service unbundling from capital equipment contracts alters buyer-supplier relationships across Western Australia hospital network tenders. ARPANSA mandatory accreditation standards for mammography equipment consolidate procurement criteria toward higher-sensitivity digital systems. Perth anchors diagnostic service delivery while telemammography protocols enable remote image transmission to serve regional areas.
South Australia
TGA software-as-a-medical-device classification revisions tighten validation requirements for AI-assisted lesion detection algorithms in Victorian and South Australian screening program procurement. Adelaide diagnostic centers navigate extended clinical evidence submission timelines for density assessment modules. Tender evaluations in this state weight regulatory approval status heavily in equipment selection criteria.
Australia Mammography Market Vendor Landscape
The competitive structure tilts toward integrated diagnostic imaging conglomerates with established service infrastructure. Market concentration favors multinational medical technology firms possessing TGA registration expertise and extended service agreement capabilities. Three archetypes dominate: full-platform vendors with software-integrated hardware, specialized breast imaging pure-plays, and third-party service providers capitalizing on unbundled maintenance contracts. Competitive moves center on performance-based 7-10 year service contracts and AI-assisted workflow software licensing.
Among North American-based conglomerates, GE Healthcare and Hologic Inc. occupy positions reflecting divergent strategic anchors. Hologic Inc. exemplifies the breast imaging pure-play archetype through density assessment software integration. GE Healthcare represents the full-platform vendor model competing via long-term service sustainment across Queensland and Western Australia networks. Siemens Healthineers anchors the European multinational tier with established TGA pathway navigation. These three firms collectively illustrate how regulatory expertise, service infrastructure scale, and software-hardware integration define competitive positioning in Australian public health procurement.
| Leading Market Players |
|---|
| GE Healthcare |
| Hologic Inc. |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Carestream Health Inc. |
| Volpara Health Limited |
| Planmed Oy |
| Others |
Supply Flow & Price Mechanics
Digital breast tomosynthesis adoption across Australian diagnostic networks is compressing equipment replacement cycles while simultaneously concentrating procurement decisions toward integrated 2D-3D platforms, reshaping both capital cost structures and supplier consolidation dynamics. TGA medical device registration pathways and ARPANSA mandatory accreditation standards are filtering equipment vendors toward those with demonstrated regulatory navigation capability, tightening the supplier base eligible for state health tenders.
Pricing Analysis
Value-based pricing anchored to screening throughput and equipment uptime guarantees dominates Queensland Health and BreastScreen Australia procurement frameworks. Three-tier pricing structure across premium integrated 2D-3D systems, standard digital mammography platforms, and economy analog replacements separates metropolitan diagnostic centers from regional hospital networks. Pricing pressure stems from Medicare reimbursement misalignment between 2D and 3D tomosynthesis procedures, compressing margins for private diagnostic operators in Sydney and Melbourne. Public hospital networks exhibit lowest price sensitivity due to extended service agreement bundling, while regional outpatient clinics face acute capital constraint.
Supply Chain Analysis
TGA Class IIa medical device certification and ARPANSA radiation safety qualification gating restricts selenium-based direct-conversion detector sourcing to established multinational suppliers with Australian regulatory presence. Manufacturing concentrates in Germany, Japan, and the United States for tungsten-rhodium X-ray tube assemblies and precision detector arrays. Supply chain risk centers on single-source vulnerability for specialized target filter components, with limited qualified manufacturers exposing procurement timelines to input availability volatility. Distribution runs through authorized medical device distributors with TGA establishment registration, linking metropolitan service hubs to regional Queensland and Western Australia deployment points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is unfolding across the Australian mammography market, with equipment vendors pursuing backward integration into AI-assisted lesion detection software development to capture recurring revenue streams beyond hardware sales.
For Market Incumbents: Cement service infrastructure scale as the primary defensive moat by extending performance-based maintenance contracts spanning 7-10 year horizons across New South Wales and Victoria hospital networks. Deepen software-hardware integration through TGA-validated density assessment modules to counter emerging pure-play AI diagnostic entrants. Prioritize radiologist workflow efficiency gains as the lever to justify premium pricing against unbundled third-party service competitors. For New Entrants and Emerging Players: Launch via mobile screening unit deployment partnerships targeting regional New South Wales clusters including Wollongong, Newcastle, and Albury-Wodonga, where public hospital infrastructure commitments present white-space opportunity. Penetrate the telemammography service layer connecting Sydney and Melbourne radiologist concentration to underserved Queensland and Western Australia regional markets. Pursue software-as-a-medical-device TGA registration for AI-assisted lesion detection as the go-to-market angle to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-platform diagnostic imaging conglomerates seeking breast imaging pure-play capabilities. Long-term viability across the analysis window favors vendors with demonstrated TGA navigation expertise and installed base scale in state health procurement frameworks. Target acquisition archetype: specialized breast imaging firms with validated AI software modules and existing BreastScreen Australia contract relationships. Watch for Medicare reimbursement schedule revisions covering 3D tomosynthesis as the signal indicating inflection toward accelerated technology refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-a-Medical-Device Registration | Accelerates market entry for AI-assisted lesion detection algorithms in Victorian and South Australian screening programs. |
| Extended Service Agreement Innovation | Performance-based 7-10 year maintenance contracts differentiate procurement evaluation criteria across Queensland Health tenders. |
| Integrated Density Assessment Software Development | Automated breast density classification combined with AI detection opens workflow efficiency gains for high-volume BreastScreen Australia programs. |
| Regional Mobile Screening Unit Deployment | Customized vehicle platforms extend screening access to Wollongong, Newcastle, and Albury-Wodonga clusters in New South Wales. |
| Telemammography Infrastructure Investment | Remote image transmission protocols enable Sydney and Melbourne radiologist concentration to serve regional Queensland and Western Australia. |
Methodological Framework
Hospital procurement databases, TGA medical device registration records, and Medicare Benefits Schedule reimbursement data formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, BreastScreen Australia program coordinators, and GPO contracts managers validated equipment deployment timelines and procurement evaluation criteria. Bottom-up triangulation across state-level health infrastructure commitments and top-down reconciliation against national screening program parameters anchored market sizing.
Historical trendline analysis of equipment replacement cycles and technology adoption curves informed the projection framework across the modeling period. Segmentation dimensions modeled include product type, technology application, end-user category, and delivery mode, with particular attention to public versus private procurement pathway divergence. CAGRs were derived from equipment unit deployment trajectories and average selling price evolution through analog-to-digital and 2D-to-3D transition phases. Forecast inputs incorporated radiologist workforce distribution constraints and state health capital budget allocation patterns.
Regulatory pathway delays, reimbursement schedule revisions, and radiologist workforce migration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding TGA registration timeline continuity and BreastScreen Australia program parameter stability. A model refresh is warranted upon material change in Medicare tomosynthesis coverage policy or state health infrastructure commitment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Quantitative Pathology Imaging Market