
 United States Diagnostic Imaging Market | 2026-2036
United States Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Diagnostic Imaging Market Outlook
The gap between premium imaging systems and commodity refurbished equipment is repositioning capital allocation across the United States. GE Healthcare leverages in-house tube manufacturing and software ecosystems to sustain pricing power at the high end. Siemens Healthineers anchors its installed base through long-term service contracts and proprietary AI reconstruction protocols. Philips Healthcare differentiates via spectral CT and ambulatory MRI configurations that target outpatient migration trends.
Diagnostic imaging encompasses the generation of visual representations of internal body structures using ionizing radiation, magnetic fields, sound waves, or radioactive tracers, with spatial resolution reaching sub-millimeter precision in modern CT and MRI platforms. The primary purpose is to enable non-invasive disease detection, treatment planning, and therapeutic monitoring across acute and chronic care pathways. MRI and CT Scan segments command the deepest capital commitment from hospital buyers, while Ultrasound gains share in point-of-care settings where portability and lower per-procedure cost reshape procurement criteria. Digital Imaging technology leads replacement cycles as analog systems face parts scarcity and incompatible PACS integration, and 3D Imaging advances fastest in pre-surgical planning where volumetric rendering reduces operative time.
FDA premarket notification and premarket approval pathways govern device safety and efficacy, while CMS national coverage determinations and local contractor policies directly shape reimbursement and thus capital recovery timelines for imaging investments. NHTSA and OSHA standards intersect with mobile MRI and PET-CT transport safety, adding compliance layers to fleet logistics. State-level certificate-of-need regulations in approximately two-thirds of US jurisdictions constrain capacity expansion and protect incumbent imaging center margins. Stakeholders must weigh site-of-service policy shifts against equipment obsolescence curves when committing to decade-long capital cycles.
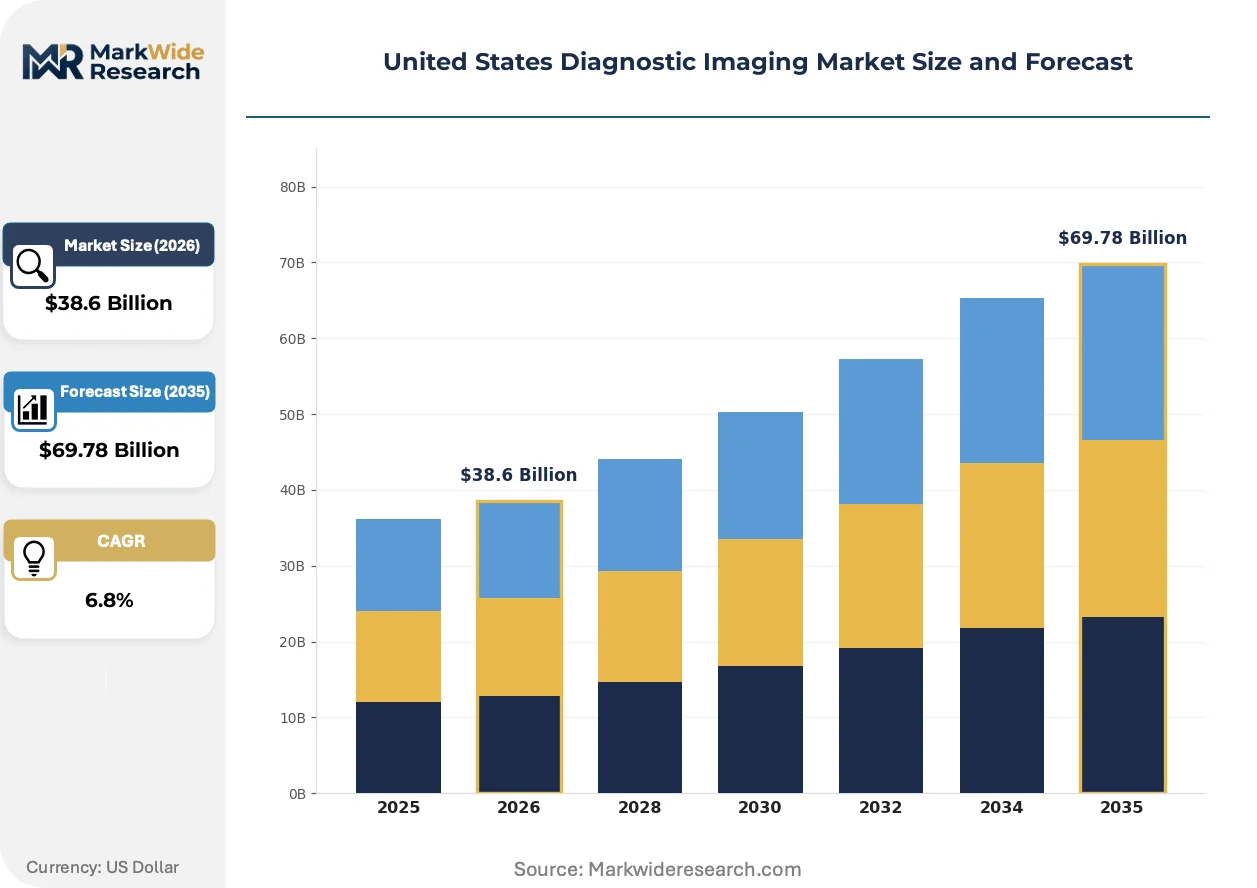
Market Dynamics
Hospital systems are consolidating imaging procurement under centralized value-based care contracts, compressing vendor negotiation cycles and favoring suppliers with integrated software-hardware-service bundles over standalone equipment sellers.
Growth Catalysts
- CMS site-of-service payment differentials:Medicare reimbursement rates for hospital outpatient departments exceed independent imaging centers, steering capital toward health system-affiliated facilities in Texas, California, and Florida.
- AI-enabled reconstruction algorithms:Deep learning protocols reduce MRI scan times by forty percent, allowing higher throughput without additional magnet installations.
- Freestanding emergency centers:Retail health clinics and micro-hospitals in suburban corridors deploy compact CT and ultrasound systems for rapid triage outside traditional hospital networks.
Market Restraints
- Helium supply concentration:Global helium refining clusters in Qatar and the United States, exposing MRI operators to price volatility and allocation rationing for magnet cooling systems.
- Certificate-of-need statutes:Thirty-six states and the District of Columbia require regulatory approval for new imaging capacity, entrenching incumbent providers and delaying market entry.
- CT dose optimization mandates:ALARA principles and Joint Commission accreditation standards constrain protocol flexibility, limiting throughput gains from hardware upgrades alone.
Strategic Opportunities
- Rural Health Clinic designation expansion:Federally qualified sites in underserved counties qualify for enhanced Medicare reimbursement, creating viable deployment zones for mobile MRI and PET-CT fleets.
- Photon-counting CT convergence:Solid-state detector technology merges spectral imaging with conventional helical acquisition, opening contrast-free coronary angiography applications.
- Direct-to-employer contracting:Self-insured corporations in manufacturing-heavy states negotiate bundled imaging rates, bypassing traditional payer intermediaries.
Industry Challenges
- Radioisotope logistics complexity:Molybdenum-99 decay chains require reactor-sourced parent isotopes, forcing PET-CT operators to coordinate daily generator deliveries within six-hour half-life windows.
- PACS interoperability fragmentation:Vendor-neutral archive migration demands custom HL7 interface engineering, extending deployment timelines and inflating IT integration budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Diagnostic Imaging Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, Ultrasound, CT Scan Technology: Digital Imaging, Analog Imaging, Hybrid Imaging, 3D Imaging End User: Hospitals, Imaging Centers, Clinics, Research Facilities Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | RadNet, Inc., Akumin, Inc., Rayus Radiology, GE Healthcare, Siemens Healthineers, Philips Healthcare, Radiology Partners, US Radiology Specialists, LucidHealth, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Diagnostic Imaging Market Strategic Shifts
Diagnostic imaging is pivoting from hardware-centric replacement cycles toward software-defined performance upgrades, with artificial intelligence reconstruction and cloud-native workflow tools extending the economic life of installed base equipment.
Photon-counting detector technology is expanding into cardiac and oncology imaging workflows. Academic medical centers in the Northeast and Midwest are adopting first-generation dual-source systems for coronary plaque characterization. The technology is expanding into community hospital procurement specifications as payers begin recognizing spectral data for prior authorization decisions.
FDA breakthrough device designation pathways are compressing premarket review timelines for AI-enabled diagnostic software. Radiology workflow vendors are embedding cleared algorithms directly into PACS viewers, bypassing standalone regulatory submissions. Freestanding imaging centers in certificate-of-need states are leveraging this pathway to differentiate against hospital-affiliated competitors with slower IT upgrade cycles.
Self-insured employers are unbundling imaging from traditional health plan contracts. Manufacturing and logistics corporations in the Southeast are negotiating direct agreements with regional radiology groups for musculoskeletal and occupational health screening. This channel disintermediation is most visible in Tennessee, Alabama, and Georgia, where large employer concentrations support dedicated imaging capacity commitments outside hospital systems.
United States Diagnostic Imaging Market Segmentation
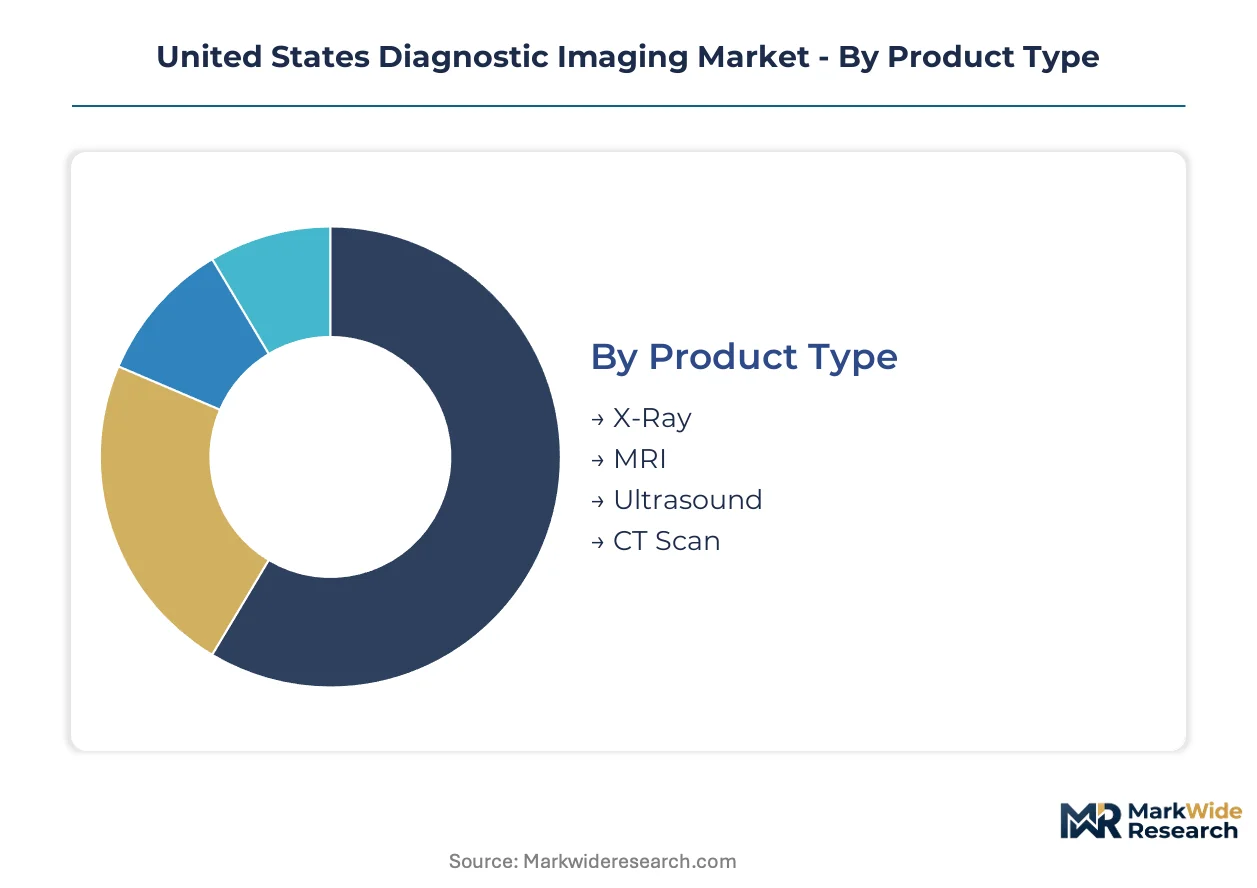
Segmentation in the United States diagnostic imaging market reveals how capital allocation, reimbursement patterns, and clinical workflow requirements diverge across equipment categories and care settings. Hospital procurement committees, imaging center operators, and outpatient clinic administrators each apply distinct criteria when committing to multi-million dollar capital cycles.
Product Type:
Technical specifications and magnet architecture define competitive positioning across the four core modalities.
- MRI:Superconducting systems utilizing liquid helium-cooled magnets achieve sub-millimeter soft tissue resolution for neurological and musculoskeletal applications. Texas and California hospital systems are expanding 3.0 Tesla installations to support value-based oncology contracts requiring precise tumor boundary delineation.
- CT Scan:Helical acquisition systems with photon-counting detector arrays deliver rapid volumetric imaging for emergency departments and trauma protocols. Freestanding emergency centers in Florida suburban corridors are procuring compact 64-slice configurations to bypass hospital-based certificate-of-need restrictions.
- X-Ray:Digital radiography panels with wireless data transmission dominate replacement cycles as analog film processors face parts obsolescence.
- Ultrasound:Portable cart-based and handheld systems enable point-of-care deployment in ambulatory settings where real-time guidance reduces referral delays.
CT Scan leads on scale; Ultrasound leads on momentum.
Technology:
Imaging performance now depends more on computational reconstruction than raw hardware specifications.
- Digital Imaging:Detector arrays with direct digital readout eliminate analog-to-digital conversion losses, enabling dose reduction protocols that satisfy Joint Commission ALARA mandates. Hospital systems in certificate-of-need states prioritize digital platforms for their compatibility with AI-enabled workflow tools that extend equipment economic life.
- 3D Imaging:Volumetric reconstruction algorithms generate multiplanar renderings for pre-surgical planning across orthopedic and maxillofacial specialties. Academic medical centers in the Northeast are deploying 3D printing integration for patient-specific implant fabrication.
- Hybrid Imaging:PET-CT and SPECT-CT fusion systems combine functional and anatomical data in single acquisition sessions.
- Analog Imaging:Legacy film-screen systems persist in rural health clinics with constrained capital budgets and low procedure volumes.
Digital Imaging commands the largest installed base; 3D Imaging is expanding most quickly.
End User:
Procurement authority and reimbursement mechanics shape equipment selection across facility types.
- Hospitals:Integrated delivery networks consolidate purchasing under centralized value-based care contracts, favoring vendors with bundled hardware-software-service offerings. CMS site-of-service payment differentials steer capital toward hospital outpatient departments in Texas, California, and Florida.
- Imaging Centers:Independent operators in non-certificate-of-need states compete on throughput and patient convenience, deploying extended-hour scheduling and direct-to-employer contracting.
- Clinics:Federally qualified rural health clinics access enhanced Medicare reimbursement for mobile MRI and PET-CT fleet deployments.
- Research Facilities:Academic medical centers pilot photon-counting CT and 7.0 Tesla MRI platforms for protocol development prior to community hospital adoption.
Hospitals lead on scale; Imaging Centers lead on momentum.
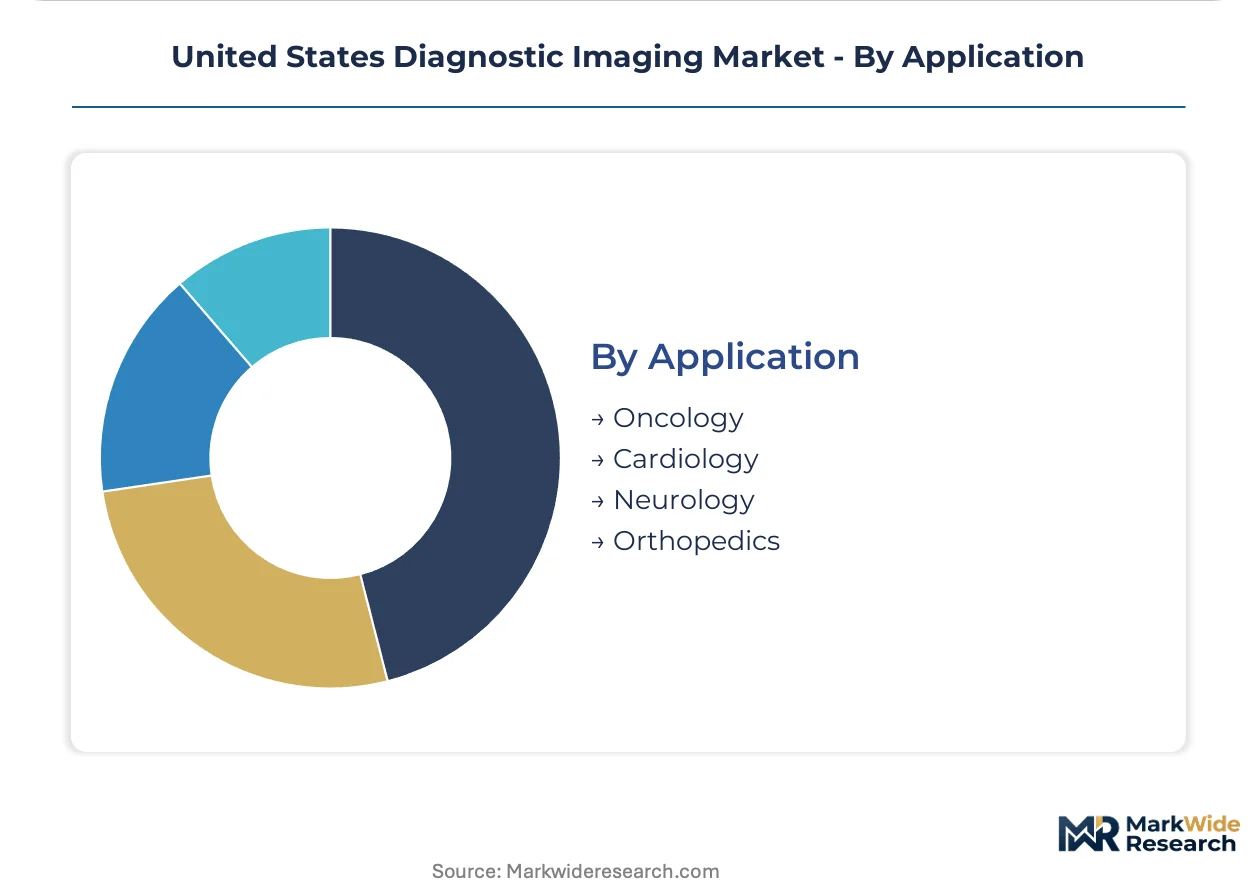
Application:
Clinical indication determines resolution requirements, contrast protocols, and reimbursement coding complexity.
- Oncology:Staging and treatment response monitoring demand precise quantification of tumor volume changes across serial examinations. Payer prior authorization requirements are expanding for PET-CT in lymphoma and lung cancer pathways.
- Cardiology:Coronary CT angiography and cardiac MRI viability studies require gating synchronization with electrocardiographic traces.
- Neurology:Diffusion-weighted MRI protocols for stroke triage mandate sub-30-minute door-to-needle imaging turnaround.
- Orthopedics:Weight-bearing CT and dynamic ultrasound guide injection therapies and post-surgical hardware assessment.
Oncology leads on scale; Cardiology leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California deploy imaging capacity at markedly different velocities, with the former expanding freestanding emergency centers while the latter concentrates academic medical center procurement. Florida's certificate-of-need restrictions create distinct competitive dynamics against these deregulated growth corridors.
Texas
Freestanding emergency centers and micro-hospitals in Houston and Dallas suburbs drive compact CT and ultrasound procurement outside hospital networks. CMS site-of-service payment differentials favor hospital outpatient departments, yet independent operators exploit regulatory gaps in non-CON counties. The Texas Medical Center anchors photon-counting CT pilot programs for coronary plaque characterization.
California
Academic medical centers in Los Angeles and San Francisco prioritize 3.0 Tesla MRI installations for value-based oncology contracts requiring precise tumor boundary delineation. FDA breakthrough device designations for AI-enabled reconstruction algorithms accelerate software deployment across integrated delivery networks. Silicon Valley health systems pilot cloud-native PACS integration for vendor-neutral archive migration.
Florida
Certificate-of-need statutes in thirty-six jurisdictions constrain capacity expansion, entrenching incumbent imaging center margins in Miami and Tampa corridors. Independent operators deploy extended-hour scheduling and direct-to-employer contracting to compete against hospital-affiliated facilities. CMS reimbursement differentials steer capital toward health system outpatient departments despite regulatory barriers.
Southeast Manufacturing Belt
Self-insured employers in Tennessee, Alabama, and Georgia negotiate direct imaging agreements for musculoskeletal and occupational health screening. Manufacturing and logistics corporations unbundle radiology from traditional health plan contracts, creating dedicated capacity commitments outside hospital systems. Nashville and Atlanta radiology groups capture this disintermediated demand channel.
Rural Health Clinic Zones
Federally qualified sites in underserved counties across Mississippi, Arkansas, and Oklahoma access enhanced Medicare reimbursement for mobile MRI and PET-CT fleet deployments. Radioisotope logistics complexity constrains PET-CT penetration, forcing operators to coordinate daily generator deliveries within six-hour half-life windows. Rural hospital districts consolidate procurement under state-level cooperative agreements.
United States Diagnostic Imaging Market Competitive Environment
Top-tier vendors anchor integrated hardware-software-service bundles, while mid-scale operators compete on throughput and geographic convenience. The vendor base stratifies between full-stack manufacturers with captive tube production and independent imaging center chains with direct-to-employer contracting capabilities. Strategic archetypes include academic medical center suppliers, freestanding emergency center specialists, and mobile fleet operators. Dominant competitive moves encompass long-term service contract anchoring and AI-enabled workflow tool integration.
Among full-stack manufacturers, GE Healthcare, Siemens Healthineers, and Philips Healthcare occupy positions representing distinct technical differentiation vectors. GE Healthcare exemplifies backward integration into critical component manufacturing. Siemens Healthineers anchors installed base retention through proprietary reconstruction protocols. Philips Healthcare sits within the spectral imaging and ambulatory configuration specialization tier. Independent imaging center chains including RadNet, Inc. and Akumin, Inc. represent the consolidation archetype, aggregating regional capacity to negotiate payer contracts at scale.
| Leading Market Players |
|---|
| RadNet, Inc. |
| Akumin, Inc. |
| Rayus Radiology |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Radiology Partners |
| US Radiology Specialists |
| LucidHealth, Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up imaging center chains anchor supply behavior through centralized procurement consortia, compressing vendor margins while extracting volume-based pricing concessions from full-stack manufacturers. This ownership pattern tightens pricing discipline across Texas and Florida markets where certificate-of-need regulations protect incumbent positions.
Pricing Analysis
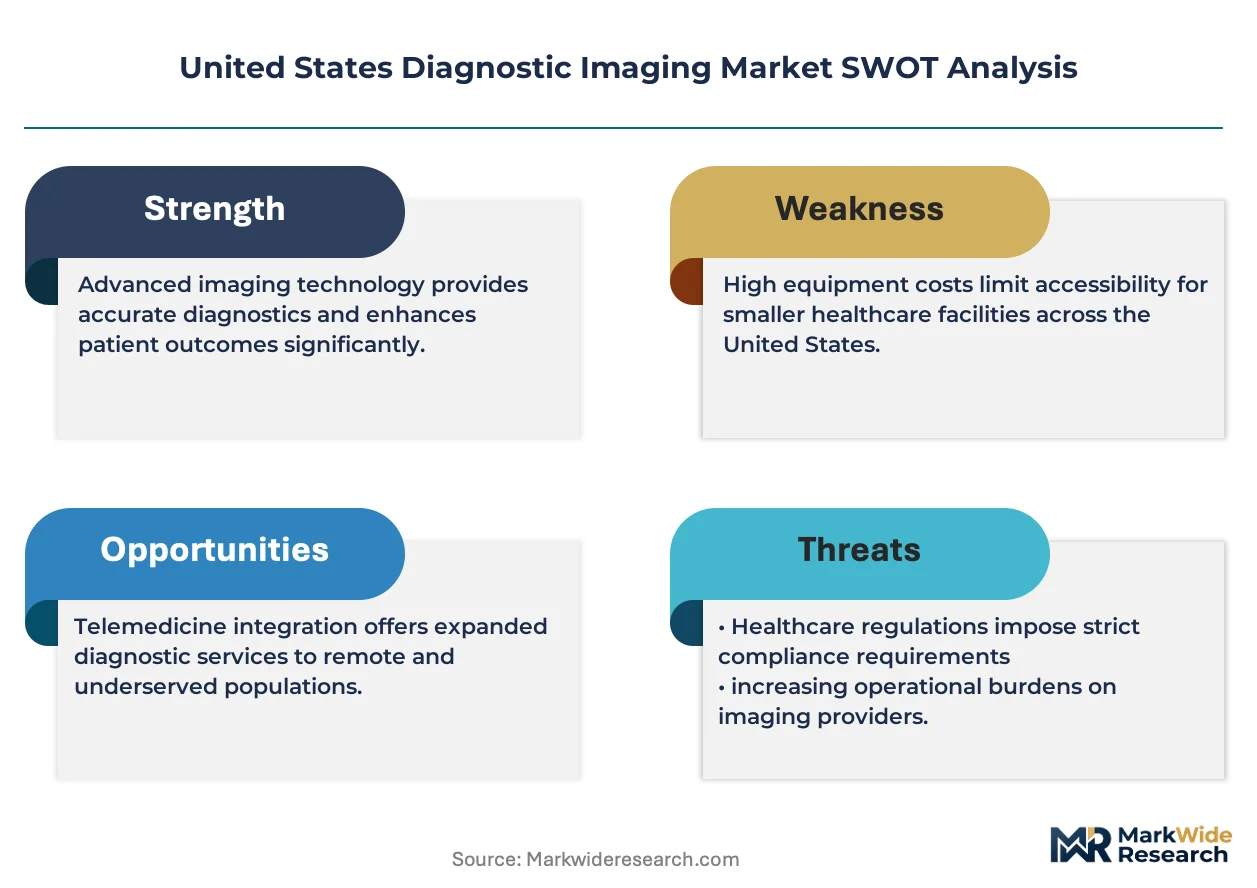
The bundled-vs-unbundled service split defines competitive positioning across the United States diagnostic imaging market. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled reconstruction protocols from basic hardware configurations and refurbished legacy systems. Price differentiation rests on helium supply security and proprietary software ecosystems as primary drivers. Cost compression in the economy tier is intensifying because refurbished CT and MRI platforms from secondary markets erode new equipment premiums. Federally qualified rural health clinics exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers in California demonstrate lowest sensitivity given research funding buffers.
Supply Chain Analysis
Dual-sourcing requirements for superconducting magnet components mandate multi-supplier qualification across United States hospital procurement committees. Geographic supply concentration centers on Germany, Japan, and the United States for precision detector arrays and gradient coil assemblies. Raw material dependencies include liquid helium for magnet cooling, rare-earth elements for gradient systems, and high-purity silicon for solid-state detectors. Single-source vulnerability persists in helium refining where Qatar and the United States control global output. Distribution runs through manufacturer-direct field service organizations with regional parts depots, bypassing traditional distributor networks for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the United States diagnostic imaging market hinges on AI-enabled reconstruction software that extends hardware economic life and commands recurring subscription revenue above depreciated equipment bases.
For Market Incumbents: Hedge helium supply exposure through long-term offtake contracts with Qatar-based refiners while anchoring installed base retention via proprietary reconstruction protocols. Consolidate service contract portfolios across Texas and Florida health systems to counter independent imaging center chains. Backward integration into tube manufacturing sustains pricing power against refurbished equipment encroachment. For New Entrants and Emerging Players: Photon-counting detector technology offers a technology-first wedge into cardiac imaging workflows where payers are recognizing spectral data for prior authorization decisions. Target freestanding emergency centers in Texas suburban corridors where certificate-of-need gaps permit rapid deployment outside hospital networks. Direct-to-employer contracting with Southeast manufacturing corporations provides a channel bypass strategy against entrenched hospital-affiliated competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among independent imaging center chains with concentrated Medicare exposure and aging equipment bases. Long-term viability over the projection horizon favors operators with software-defined upgrade pathways and mobile fleet logistics capabilities. Watch FDA breakthrough device designation velocity as the inflection indicator for AI-enabled diagnostic software revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| AI Reconstruction Algorithm Integration | FDA-cleared deep learning protocols reduce MRI scan times by forty percent, enabling throughput expansion without magnet installation. |
| Helium Supply Contracting | Long-term offtake agreements with Qatar and United States refiners mitigate price volatility for superconducting magnet cooling systems. |
| Mobile Fleet Deployment | Rural Health Clinic designation expansion creates viable deployment zones for MRI and PET-CT units in underserved Mississippi and Arkansas counties. |
| Direct-to-Employer Contracting | Self-insured manufacturing corporations in Tennessee and Georgia negotiate bundled imaging rates outside traditional payer intermediaries. |
| Photon-Counting CT Adoption | Solid-state detector technology opens contrast-free coronary angiography applications as payers recognize spectral data for prior authorization. |
Study Parameters
Coverage spans Texas, California, Florida, and the Southeast Manufacturing Belt, with primary inputs from each region's hospital procurement committees and independent imaging center operators. The analysis combines structured interviews with biomedical engineers, GPO contracts managers, radiology group administrators, and CMS reimbursement specialists with secondary validation from FDA 510(k) filings, CMS national coverage determinations, hospital procurement databases, and certificate-of-need regulatory filings. Bottom-up equipment shipment tracking and top-down health system capital expenditure analysis provide triangulation across the analysis window.
Granularity-level framing applies modality-specific modeling at the state level for Texas, California, and Florida, with technology-layer segmentation for digital versus analog platforms and end-user disaggregation across hospitals, imaging centers, clinics, and research facilities. CAGRs derive from installed base replacement curves, reimbursement trajectory assumptions, and AI adoption elasticity parameters. Forecast inputs incorporate helium supply allocation rationing scenarios and site-of-service payment differential policy shifts.
The model holds under stable Medicare reimbursement and certificate-of-need regulatory continuity; deviation in CMS site-of-service payment compression or CON statute repeal would shift the outlook materially. Deviation in FDA AI-enabled device clearance velocity or helium supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market