
 Molecular Breast Imaging Market | 2026-2036
Molecular Breast Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Breast Imaging Market Foresight
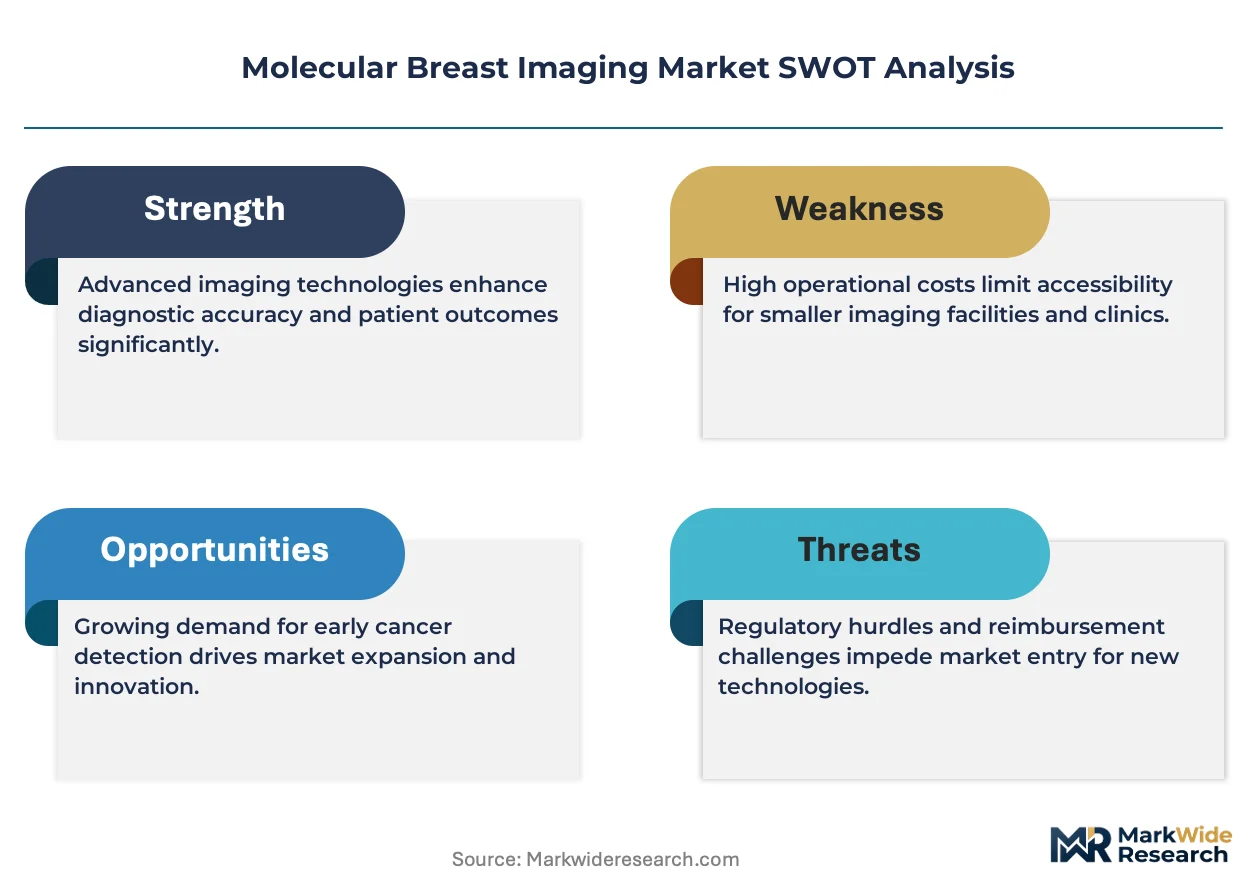
Equipment leasing and pay-per-scan service models is fragmenting capital barriers for mid-tier diagnostic imaging centers seeking molecular breast imaging capability. GE Healthcare leverages its installed base of nuclear medicine platforms to cross-sell dedicated breast gamma camera configurations. Siemens Healthineers sustains R&D intensity in cadmium zinc telluride detector arrays that improve spatial resolution for small lesion detection. Hologic, Inc. anchors its competitive position through integrated workflows that connect molecular breast imaging with digital mammography and tomosynthesis systems.
Molecular breast imaging denotes gamma-ray emission tomography of breast tissue using technetium-99m sestamibi radiotracer uptake, typically performed with dual-head cadmium zinc telluride detectors at compressed radiation doses below conventional nuclear medicine protocols. The technique primarily serves adjunctive screening in women with mammographically dense breast tissue where X-ray attenuation reduces sensitivity. Gamma cameras occupy the dominant revenue position given their established reimbursement codes and shorter procedure times compared to PET scanner alternatives. Software solutions represent the fastest-expanding margin pool as vendors embed AI-assisted quantification tools that standardize uptake ratio measurements across technologist skill levels.
The FDA regulates molecular breast imaging devices under 21 CFR 892 subpart B with specific performance standards for gamma camera spatial resolution and count sensitivity, while the Mammography Quality Standards Act extends quality assurance requirements to facilities offering adjunctive molecular imaging. State-level dense breast notification laws create heterogeneous demand patterns that manufacturers must navigate through region-specific clinical education programs. Stakeholders should monitor CMS national coverage determination proceedings for supplemental breast cancer screening technologies, as reimbursement clarity will dictate whether hospital systems accelerate capital deployment or defer molecular imaging expansion.
Market Dynamics
Dense breast notification laws across over 40 US states now mandate patient disclosure of mammographic density, creating immediate clinical demand for supplemental gamma-ray emission tomography. This regulatory cascade compresses decision timelines for imaging center capital allocation.
Growth Catalysts
- MQSA Reimbursement Pathways:The Mammography Quality Standards Act establishes quality benchmarks that validate molecular breast imaging as a covered supplemental screening modality, accelerating hospital system adoption.
- Cadmium Zinc Telluride Detectors:Solid-state detector arrays deliver superior spatial resolution for sub-centimeter lesion detection compared to conventional sodium iodide crystals, driving equipment refresh cycles.
- Diagnostic Imaging Centers:Freestanding imaging chains seek differentiated service lines to compete with hospital-affiliated networks, prioritizing gamma camera deployments for dense breast patient populations.
Market Restraints
- Technetium-99m Supply Volatility:Reactor production constraints for the sestamibi radiotracer create intermittent shortages that disrupt procedure scheduling and patient throughput.
- Radiation Dose Concerns:Effective doses approximately eight to ten times higher than digital mammography limit screening frequency and restrict use to adjunctive rather than primary screening protocols.
- Reimbursement Uncertainty:CMS national coverage determination proceedings for supplemental breast cancer screening technologies remain unresolved, causing capital deployment hesitation among risk-averse health systems.
Strategic Opportunities
- AI-Assisted Quantification:Machine learning algorithms standardize uptake ratio measurements across variable technologist skill levels, reducing inter-operator variability and expanding serviceable addressable market.
- Pay-Per-Scan Service Models:Equipment leasing arrangements eliminate upfront capital barriers for mid-tier diagnostic imaging centers, democratizing access to molecular breast imaging capability.
- State-Level Dense Breast Legislation:Heterogeneous notification law implementation creates region-specific clinical education windows where manufacturers can establish first-mover relationships with newly mandated facilities.
Industry Challenges
- Nuclear Medicine Technologist Shortage:Specialized radiopharmaceutical handling and gamma camera operation expertise remains scarce, constraining procedure volume expansion even where equipment is installed.
- Workflow Integration Complexity:Connecting molecular breast imaging outputs with digital mammography and tomosynthesis systems requires substantial PACS customization and staff retraining.
- Quality Assurance Compliance:FDA 21 CFR 892 subpart B performance standards demand continuous spatial resolution and count sensitivity monitoring, increasing operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Breast Imaging Market |
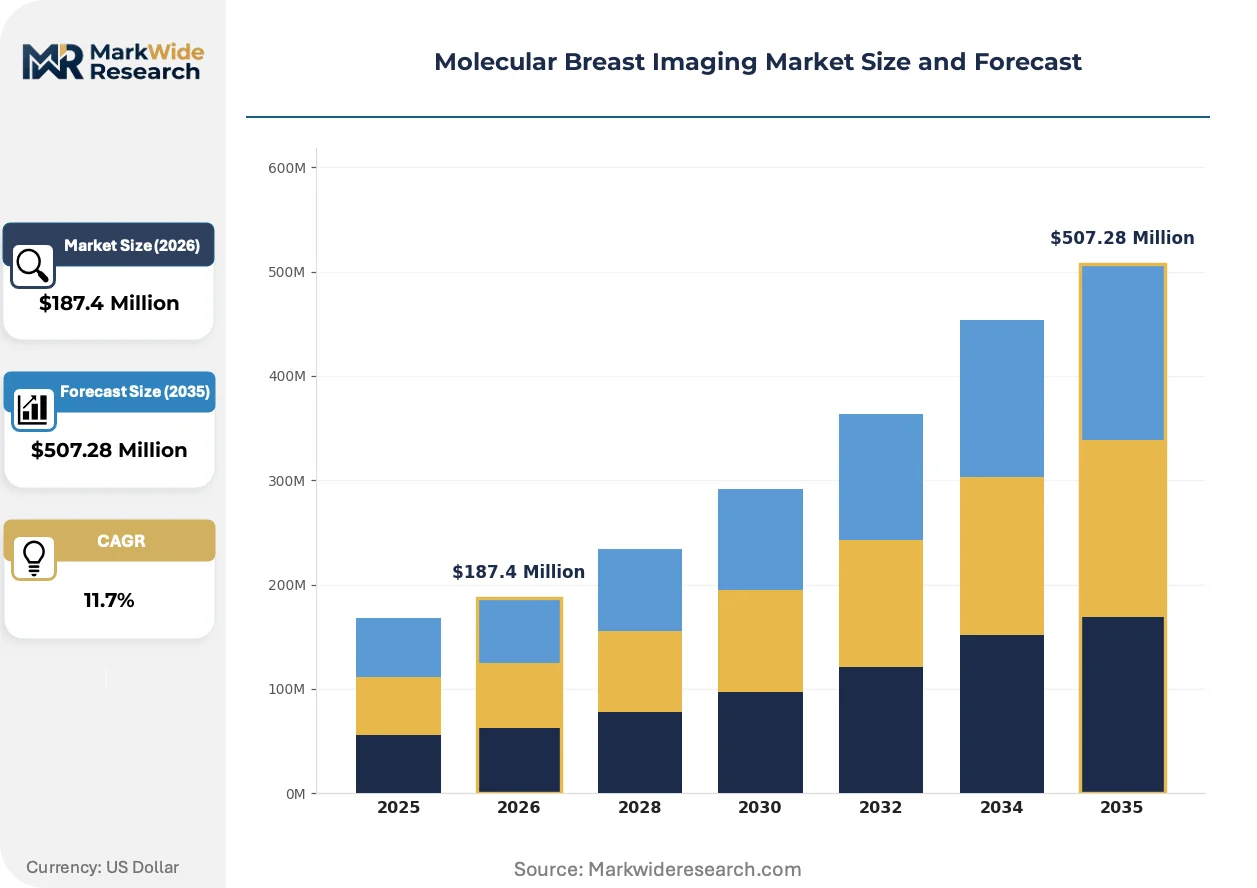
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, PET Scanners, Molecular Imaging Agents, Software Solutions Application: Early Detection, Diagnosis, Treatment Monitoring, Recurrence Assessment End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Clinics Technology: Planar Imaging, Tomography, Digital Acquisition, Image Reconstruction |
| Companies Covered | GE Healthcare, Siemens Healthineers, Hologic, Inc., Koninklijke Philips N.V., Canon Medical Systems Corporation, SmartBreast Corporation, CMR Naviscan Corporation, FUJIFILM Holdings Corporation, Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Breast Imaging Market Shifts & Advancements
Gamma camera architectures are undergoing fundamental redesign as detector materials and software intelligence converge. Three distinct vectors are compressing procedure times while expanding clinical utility.
Cadmium zinc telluride semiconductor detectors are migrating from experimental configurations to standard production specifications across major equipment platforms. Academic medical centers and large health systems now specify CZT arrays as baseline requirements in procurement tenders. This material transition is compressing the performance gap between dedicated breast gamma cameras and full-ring PET systems for lesion characterization.
The FDA's continued enforcement of 21 CFR 892 subpart B performance standards is tightening spatial resolution and count sensitivity benchmarks for new device approvals. Manufacturers must demonstrate improved small-lesion detectability to secure 510(k) clearances. European facilities operating under MDR conformity assessment procedures face parallel technical documentation requirements, slowing product introduction timelines.
Diagnostic imaging centers now unbundle equipment acquisition from service contracts, preferring operational expenditure models that align costs with procedure volume. Leasing structures with embedded maintenance and software updates displace traditional capital purchase arrangements. This preference shift concentrates most visibly in the United States, where dense breast notification laws have expanded addressable patient populations faster than capital budgets have grown.
Molecular Breast Imaging Market Segmentation
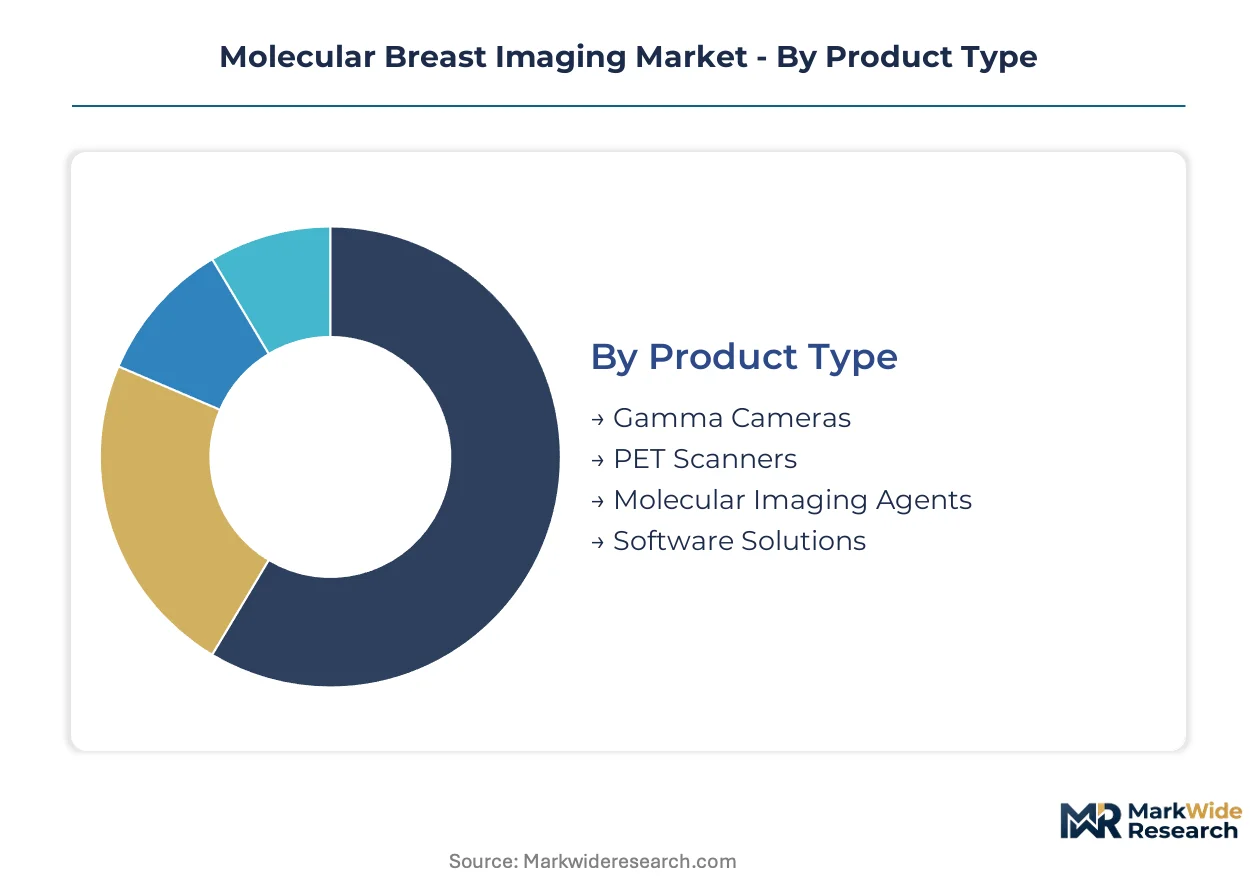
Segmentation in molecular breast imaging reveals divergent equipment utilization patterns across clinical settings. Product configurations and service models must align with specific workflow demands from screening programs versus diagnostic workups.
Product Type:
After-sales-service intensity varies sharply across product categories, with gamma cameras requiring continuous detector calibration and software platforms demanding quarterly algorithm updates.
- Gamma Cameras:Dual-head cadmium zinc telluride detector systems dominate hospital procurement for their sub-centimeter spatial resolution. Dense breast notification laws in over 40 US states concentrate demand at diagnostic imaging centers seeking dedicated breast configurations.
- PET Scanners:Full-ring positron emission systems serve academic medical centers requiring whole-body staging capability alongside breast-specific protocols. Capital constraints limit deployment to tertiary referral networks with established nuclear medicine departments.
- Molecular Imaging Agents:Technetium-99m sestamibi kits face supply volatility from reactor production constraints.
- Software Solutions:AI-assisted uptake quantification tools standardize measurements across variable technologist skill levels.
Gamma cameras hold the largest share; momentum sits with software solutions.
Application:
Cost tier differentiation separates screening applications from diagnostic workups, with early detection programs commanding premium pricing due to regulatory compliance burdens.
- Early Detection:Adjunctive screening for mammographically dense breast tissue drives procedure volume under state notification mandates. Reimbursement clarity from CMS national coverage determinations dictates whether health systems expand screening capacity.
- Diagnosis:Characterization of suspicious mammographic findings requires correlation with biopsy outcomes. Academic medical centers concentrate utilization for complex lesion workups.
- Treatment Monitoring:Neoadjuvant chemotherapy response assessment occupies a narrower clinical niche.
- Recurrence Assessment:Post-surgical surveillance applications face competition from contrast-enhanced mammography alternatives.
Early detection commands the largest share; diagnosis climbs the fastest.
End User:
Volume concentration patterns favor freestanding diagnostic chains over hospital systems for equipment refresh cycles.
- Hospitals:Integrated health systems anchor procurement for comprehensive breast centers requiring multimodality workflows. PACS integration complexity with digital mammography and tomosynthesis systems extends implementation timelines.
- Diagnostic Imaging Centers:Freestanding chains prioritize pay-per-scan service models to eliminate capital barriers. Equipment leasing arrangements align costs with procedure volume across mid-tier facilities.
- Research Institutions:Clinical trial endpoints drive specialized detector procurement.
- Outpatient Clinics:Limited radiopharmaceutical handling licenses constrain service expansion.
Diagnostic imaging centers hold the largest share; hospitals show steepest expansion trajectory.
Technology:
Maturity curves separate established planar techniques from emerging reconstruction algorithms requiring substantial computational infrastructure.
- Planar Imaging:Standard dual-head gamma camera acquisition protocols deliver shorter procedure times than tomographic alternatives. FDA 21 CFR 892 subpart B performance standards govern spatial resolution benchmarks for device clearances.
- Tomography:Three-dimensional sestamibi uptake mapping improves lesion localization for biopsy guidance. Academic centers specify tomographic capability in procurement tenders despite longer acquisition protocols.
- Digital Acquisition:Solid-state detector readout electronics enable reduced radiation dose protocols.
- Image Reconstruction:Iterative algorithms and AI-assisted processing reduce image noise.
Planar imaging holds the largest share; tomography gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in molecular breast imaging concentrates in the United States, where dense breast notification laws and established reimbursement codes sustain premium equipment valuations, while European markets operate under tighter procurement constraints and fragmented national coverage policies.
United States
Over 40 state-level dense breast notification laws mandate patient disclosure of mammographic density, creating immediate clinical demand for supplemental gamma-ray emission tomography. The FDA enforces 21 CFR 892 subpart B performance standards for gamma camera spatial resolution and count sensitivity, shaping device approval pathways. Major diagnostic imaging chains in Texas, Florida, and California prioritize pay-per-scan service models to eliminate capital barriers for mid-tier facilities.
Germany
Academic medical centers in Bavaria and Baden-Württemberg specify cadmium zinc telluride detector arrays as baseline procurement requirements, compressing the performance gap with PET systems. The EU Medical Device Regulation imposes parallel technical documentation requirements for spatial resolution benchmarks, slowing new product introductions. Siemens Healthineers anchors detector R&D intensity from its Erlangen headquarters.
Japan
PMDA clearance procedures for gamma camera devices emphasize radiation dose reduction protocols aligned with national breast cancer screening guidelines. METI funding for solid-state detector research accelerates domestic technology development. Tokyo and Osaka metropolitan areas concentrate hospital system procurement for integrated breast centers requiring multimodality workflows.
United Kingdom
NHS England's breast screening programme evaluates supplemental imaging modalities through technology appraisal processes that determine commissioning eligibility. The Medicines and Healthcare products Regulatory Agency applies CE marking conformity assessment procedures under retained EU law. London and Southeast England clusters drive early adoption of AI-assisted uptake quantification tools.
China
NMPA device registration requirements for gamma cameras emphasize clinical trial endpoints in dense breast populations, extending approval timelines for foreign manufacturers. Provincial health commissions in Guangdong and Jiangsu pilot supplemental screening reimbursement pilots. Yangtze River Delta medical centers concentrate demand for equipment leasing arrangements that align costs with procedure volume.
Molecular Breast Imaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector materials and radiopharmaceutical supply. The vendor base stratifies across three tiers: multinational conglomerates with nuclear medicine installed bases, dedicated breast imaging specialists, and regional equipment distributors. Two strategic archetypes dominate competitive positioning: cross-selling from established nuclear medicine platforms versus pure-play disruption through dedicated breast gamma camera configurations. Competitive moves concentrate on detector material transitions and pay-per-scan service model expansion.
Within the multinational conglomerate tier, GE Healthcare leverages its nuclear medicine installed base, Siemens Healthineers anchors R&D in cadmium zinc telluride detector arrays, and Hologic, Inc. occupies a position emphasizing integrated workflows with digital mammography systems. These three represent distinct strategic postures: cross-selling breadth, upstream component specialization, and vertical workflow integration.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Hologic, Inc. |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| SmartBreast Corporation |
| CMR Naviscan Corporation |
| FUJIFILM Holdings Corporation |
| Hitachi Ltd. |
| Others |
Supply & Pricing Matrix
Technetium-99m reactor production concentrated in Canada, the Netherlands, and South Africa feeds directly into radiotracer kit pricing volatility, pushing margin capture downstream toward detector array manufacturers and AI-assisted software platforms that command recurring revenue premiums.
Pricing Analysis
Configured-to-order gamma camera systems with CZT detector arrays command 40-60% premiums over standard sodium iodide configurations. Three-tier pricing structure across premium, standard, and economy levels reflects detector material grade, FDA 510(k) certification tier, and embedded software analytics bundles. Pricing pressure stems from pay-per-scan service models commoditizing hardware margins while expanding addressable reach. Diagnostic imaging centers exhibit highest price sensitivity, constrained by capital access; academic medical centers show lowest sensitivity, prioritizing spatial resolution specifications.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now standard among detector array suppliers reflect working capital pressure from raw material cost inflation. CZT semiconductor crystal growth draws from Germany, Japan, and the United States; technetium-99m extraction depends on aging research reactor infrastructure in Canada and Europe. Single-source vulnerability concentrates in molybdenum-99 parent isotope supply. Distribution runs through authorized nuclear medicine equipment distributors with radiopharmaceutical handling licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription layers for AI-assisted uptake quantification expand faster than hardware replacement cycles, transforming capital equipment markets into service-attach opportunities with recurring revenue profiles.
For Market Incumbents: Insulate installed base relationships through detector upgrade pathways that preserve gamma camera chassis investments while blocking PET scanner substitution. Threat from full-ring PET systems intensifies as academic centers consolidate multimodality procurement. Backward integration into CZT crystal supply secures margin control against semiconductor raw material volatility. For New Entrants and Emerging Players: Freestanding diagnostic imaging centers in Texas, Florida, and California represent underpenetrated white space where dense breast notification laws have expanded patient volumes faster than capital deployment. Pay-per-scan service models eliminate upfront barriers for mid-tier facilities. Go-to-market through GPO contracts with diagnostic imaging chains accelerates volume ramp without direct hospital sales force investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic imaging center rollups seeking equipment standardization across acquired platforms. Five-to-ten year viability hinges on CMS national coverage determination resolution for supplemental screening reimbursement. Signal to monitor: state dense breast notification law adoption velocity as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Quantification Platform Launch | Machine learning standardization reduces technologist skill dependency across variable staffing environments. |
| CZT Detector Array Backward Integration | In-house semiconductor crystal growth secures supply continuity against reactor production constraints. |
| Pay-Per-Scan Service Model Expansion | Operational expenditure alignment removes capital barriers for mid-tier diagnostic imaging center adoption. |
| CMS Reimbursement Strategy Investment | National coverage determination advocacy shapes hospital system capital deployment timelines. |
| State-Level Clinical Education Program | Region-specific training builds first-mover relationships with newly mandated dense breast notification facilities. |
Research Methodology
The analysis maps gamma camera hardware, PET scanner alternatives, radiopharmaceutical supply, and AI software layers, each validated through nuclear medicine technologists, hospital purchasing committees, GPO contracts managers, and diagnostic imaging center operators. Primary interview data triangulates against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and state dense breast notification legislation tracking. Bottom-up equipment unit economics and top-down market sizing converge across segmentation dimensions.
Assumptions held fixed include current FDA 21 CFR 892 subpart B performance standards and existing state notification law coverage; variables tested include CMS national coverage determination outcomes and technetium-99m supply disruption scenarios. Modeled segments span product type, application, end user, and technology across the projection horizon. CAGRs derive from equipment replacement cycle analysis, procedure volume elasticity to reimbursement clarity, and software attach rate expansion curves.
Practitioners should monitor CMS national coverage determination proceedings, technetium-99m reactor maintenance schedules, and state dense breast notification law adoption for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
France Digital Radiology Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Medical Holography Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market