
 Asia-Pacific CT Market | 2026-2036
Asia-Pacific CT Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific CT Market Outlook
The capital-intensity divergence between high-end spectral CT developers and budget fixed-detector manufacturers is unwinding as healthcare systems demand tiered performance at controlled cost. Siemens Healthineers leverages its photon-counting platform to anchor premium positioning in Japanese and Australian tertiary hospitals. Neusoft Medical Systems Co Ltd competes on localized manufacturing scale and government procurement access across China's provincial health networks.
Computed tomography (CT) generates cross-sectional anatomical images through rotating X-ray tube-detector assemblies, with modern multi-slice systems acquiring sub-millimeter isotropic voxels at sub-second gantry rotation speeds for cardiac and perfusion imaging. Multi-slice CT occupies the dominant revenue position as healthcare systems replace aging single-slice infrastructure across India and Indonesia. Photon counting represents the fastest-expanding technology segment, though its installed base remains concentrated in premium Japanese and South Korean hospitals where reimbursement supports capital recovery.
Japan's PMDA enforces stringent device quality standards that filter lower-tier manufacturers from its reimbursed procurement channels, while China's NMPA accelerates domestic innovation through streamlined Class III registration for locally developed CT platforms. India's CDSCO has aligned medical device rules with ASEAN harmonization frameworks, reducing import barriers for certified manufacturers. Stakeholders must weigh localization requirements against technology transfer costs when configuring regional supply and service architectures.
Market Dynamics
Photon-counting detector technology is compressing the traditional price-performance hierarchy across Asia-Pacific imaging infrastructure, forcing manufacturers to reposition mid-tier systems against spectral capabilities previously reserved for premium installations.
Growth Catalysts
- Tertiary hospital expansion:China's provincial health networks are procuring 256-slice CT systems under the 14th Five-Year Plan healthcare infrastructure mandates, displacing aging 16-slice installed bases.
- Japan's PMDA quality enforcement:Stringent post-market surveillance requirements for CT device software updates are filtering non-compliant manufacturers from reimbursed procurement channels, concentrating demand among certified suppliers.
- Dual-energy reconstruction algorithms:Software-based spectral imaging capabilities are extending hardware lifecycles across Indian diagnostic chains, deferring capital replacement while expanding clinical applications.
Market Restraints
- Xenon detector supply concentration:High-purity scintillator crystal production concentrates in Japanese and German specialty material suppliers, creating input cost volatility for CT detector module assemblers.
- Import tariff cascades:India's CDSCO medical device rules impose layered duties on non-ASEAN certified components, inflating landed costs for European and North American imaging platforms.
- Helium cooling dependency:Superconducting magnet thermal management requires liquid helium supply chains vulnerable to South African and Qatar export disruptions, constraining MRI-CT hybrid system deployment timelines.
Strategic Opportunities
- Indonesia's archipelago connectivity gap:Mobile CT screening units serving remote island provinces lack fixed-site competition, creating first-mover advantage for service-lease operators.
- AI-assisted low-dose reconstruction:Deep learning denoising algorithms are converging with photon-counting hardware to enable lung cancer screening at sub-mSv exposures, opening outpatient clinic channels.
- Australia's TGA streamlined registration:Priority review pathways for software-as-medical-device CT applications accelerate time-to-revenue for algorithm developers targeting radiology workflow automation.
Industry Challenges
- Clinical application specialist scarcity:Cardiac CT perfusion protocol optimization requires trained technologists concentrated in Seoul, Tokyo, and Shanghai tertiary centers, limiting protocol standardization across secondary hospitals.
- Legacy PACS integration friction:DICOM-RT connectivity gaps between 2010-era hospital information systems and modern iterative reconstruction workstations delay deployment acceptance testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific CT Market |
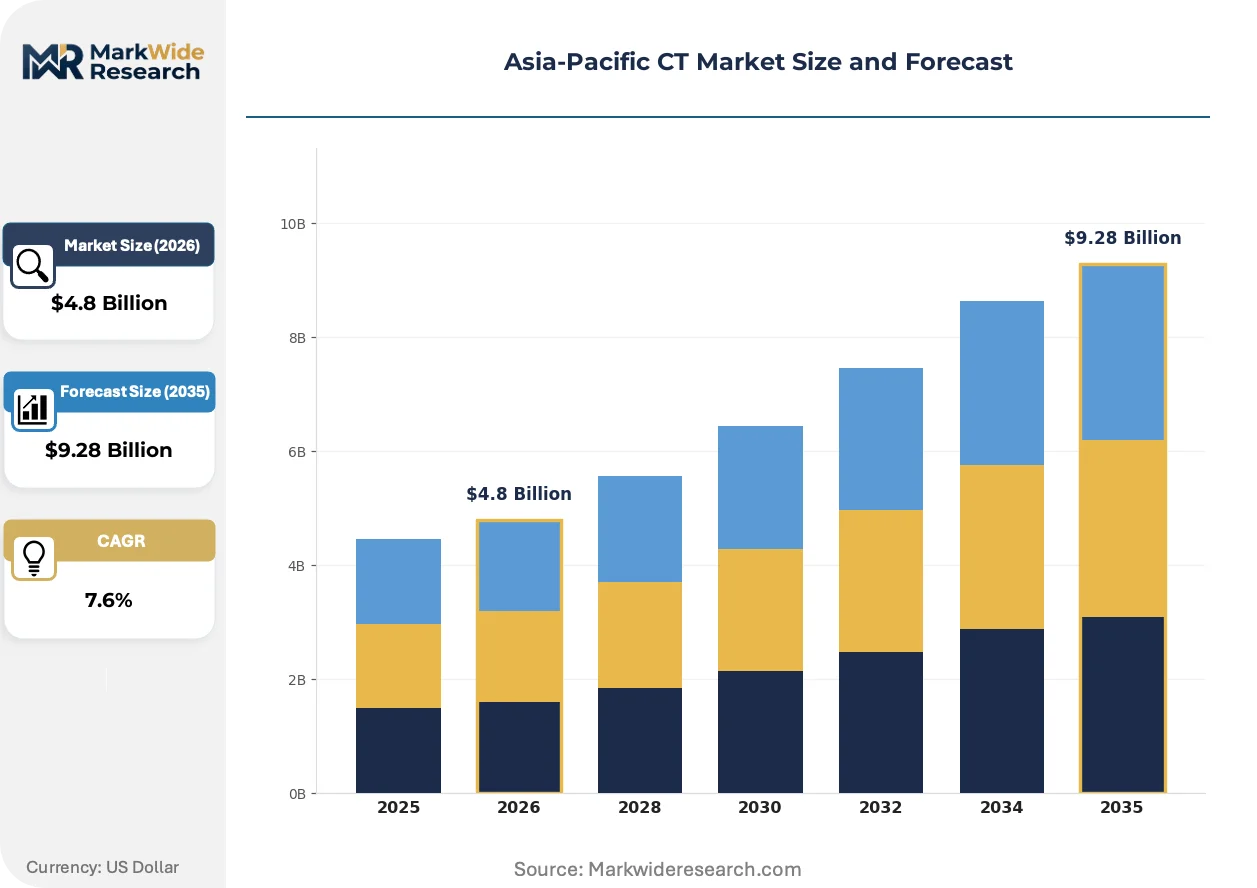
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical CT, Cone Beam CT, Positron Emission Tomography, Multi-Slice CT End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Ambulatory Surgical Centers Technology: Digital Radiography, Photon Counting, Image Reconstruction, Motion Correction Application: Oncology, Cardiovascular, Neurology, Trauma |
| Companies Covered | Canon Medical Systems Corporation, GE Healthcare, Koninklijke Philips NV, Siemens Healthineers, Neusoft Medical Systems Co Ltd, Shenzhen Anke High-Tech Co Ltd, Shanghai United Imaging Healthcare Co Ltd, Hitachi Medical Corporation, Fujifilm Holdings Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific CT Market Strategic Shifts
Artificial intelligence inference engines are embedding directly into CT reconstruction pipelines, shifting competitive differentiation from hardware slice-count to software-enabled clinical decision support.
Photon-counting CT is decomposing the conventional detector-material hierarchy by replacing energy-integrating scintillators with cadmium telluride semiconductors that register individual X-ray photon energies. Japanese quaternary hospitals in Osaka and Yokohama are adopting these platforms for coronary plaque characterization at triple the acquisition speed of conventional systems. The technology is decomposing premium-tier pricing power by enabling spectral tissue differentiation on hardware with lower gantry rotation specifications.
China's NMPA has implemented expedited Class III registration tracks for CT platforms incorporating domestic deep learning algorithms, compressing approval timelines for locally developed reconstruction software. This regulatory architecture favors joint ventures between multinational hardware manufacturers and Chinese AI developers seeking hospital procurement eligibility. Provincial tender documents in Sichuan and Guangdong now weight NMPA-certified software integration above raw detector specifications.
Diagnostic chains across Vietnam and Thailand are unbundling equipment ownership from service contracts, preferring per-scan reimbursement models that transfer utilization risk to manufacturers. This consumption-pattern shift favors vendors with remote monitoring infrastructure capable of predicting tube replacement cycles and detector calibration drift. Malaysian private hospital groups are piloting these arrangements for cardiac calcium scoring programs targeting executive health screening demand.
Asia-Pacific CT Market Segmentation
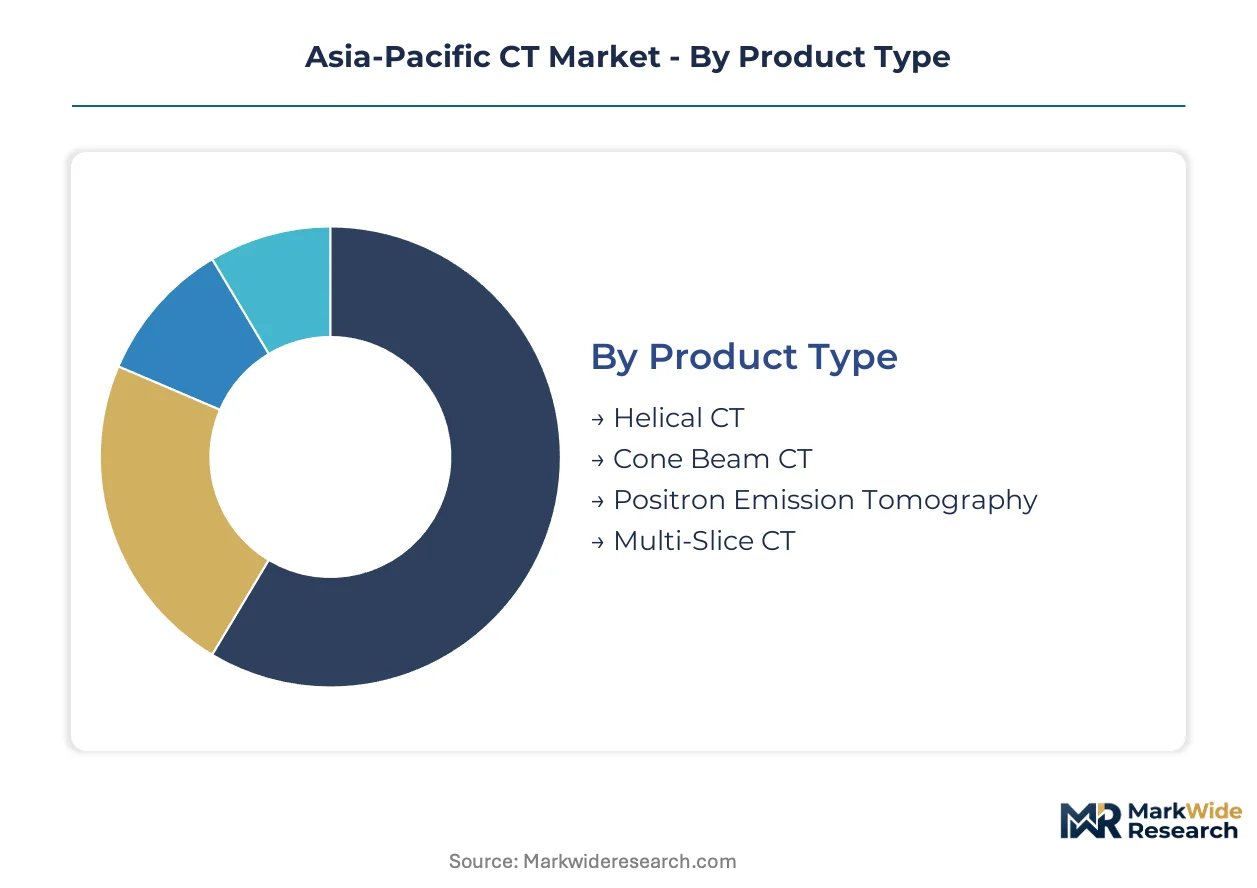
CT procurement channels in Asia-Pacific diverge sharply between government-funded hospital networks and private diagnostic chains, with each channel favoring distinct performance tiers and service contract structures. Understanding these segment-channel mappings determines vendor positioning and pricing architecture across the region's heterogeneous healthcare systems.
Product Type:
Channel mix varies by slice count and mobility: fixed-site multi-slice systems flow through provincial government tenders, while mobile helical units serve Indonesia's archipelago screening programs and Australian rural outreach.
- Multi-Slice CT:Rotating X-ray tube-detector assemblies acquire sub-millimeter isotropic voxels at sub-second gantry rotation speeds. China's provincial health networks under the 14th Five-Year Plan are replacing aging 16-slice installed bases with 256-slice systems, concentrating demand in tertiary hospitals.
- Helical CT:Continuous patient table translation during gantry rotation enables volumetric acquisition without inter-scan delays. India's diagnostic chains deploy these systems for high-throughput outpatient screening in Delhi and Mumbai, where patient volumes justify continuous operation.
- Cone Beam CT:Flat-panel detectors capture volumetric dental and maxillofacial images at lower radiation doses than conventional CT. Southeast Asian dental clinic chains in Bangkok and Kuala Lumpur favor these for orthodontic planning.
- Positron Emission Tomography:Hybrid PET-CT platforms combine metabolic radiotracer imaging with anatomical CT for oncology staging. South Korean cancer centers in Seoul and Busan anchor demand for these capital-intensive systems.
By volume, multi-slice CT leads. By growth pace, photon-counting-equipped helical systems are climbing the fastest.
End User:
Cost tier stratification separates premium tertiary hospital procurement from mid-tier diagnostic center leasing arrangements, with research institutes occupying a specialized high-performance niche.
- Hospitals:Tertiary institutions in Japan's Osaka and Yokohama corridors deploy photon-counting platforms for coronary plaque characterization, while China's county-level hospitals upgrade from single-slice legacy systems under infrastructure mandates.
- Diagnostic Imaging Centers:Unbundled equipment ownership from per-scan service contracts transfers utilization risk to manufacturers. Vietnamese and Thai diagnostic chains prefer this model, requiring vendors with predictive remote monitoring infrastructure.
- Research Institutes:Quaternary medical centers in Tokyo and Shanghai operate experimental CT platforms for spectral tissue characterization studies, often preceding commercial adoption by three to five years.
- Ambulatory Surgical Centers:Compact 64-slice systems serve same-day discharge protocols in Australian metropolitan outpatient facilities, where TGA streamlined registration accelerates deployment timelines.
By installed base, hospitals dominate. By contract innovation, diagnostic imaging centers are gaining share fastest.
Technology:
Application maturity separates established digital radiography infrastructure from emerging photon-counting platforms still concentrated in premium Japanese and South Korean installations.
- Photon Counting:Cadmium telluride semiconductors register individual X-ray photon energies, replacing energy-integrating scintillators. Japanese quaternary hospitals adopt these for triple-speed coronary imaging, decomposing conventional detector-material hierarchies.
- Digital Radiography:Flat-panel detector technology dominates installed bases across India's secondary hospitals and Indonesia's provincial networks, where cost constraints defer premium upgrades.
- Image Reconstruction:Deep learning algorithms embedded in reconstruction pipelines enable low-dose lung cancer screening at sub-mSv exposures, opening outpatient clinic channels across China's screening programs.
- Motion Correction:Real-time cardiac gating and respiratory tracking algorithms reduce artifact in pediatric and trauma imaging. Australian pediatric hospitals in Sydney and Melbourne pilot these for uncooperative patient protocols.
By deployment breadth, digital radiography leads. By capability expansion, photon-counting platforms show the steepest trajectory.
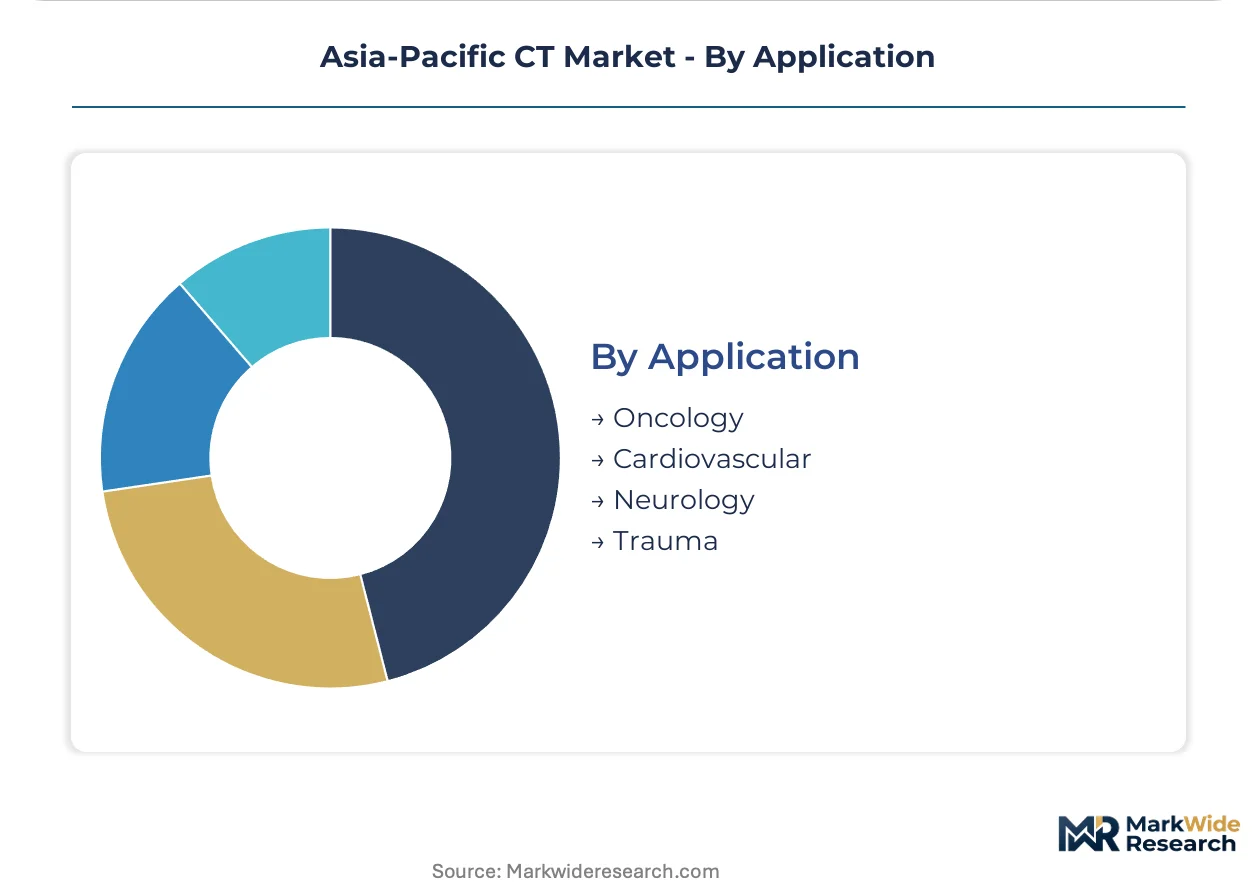
Application:
Geography concentrates demand: oncology screening scales through China's provincial networks, while cardiovascular protocols concentrate in Japan's aging-population tertiary centers.
- Oncology:Lung cancer screening programs drive 256-slice CT procurement across China's Sichuan and Guangdong provinces, with NMPA-certified AI reconstruction software weighted above raw detector specifications in tender documents.
- Cardiovascular:Cardiac CT perfusion protocols require trained technologists concentrated in Seoul, Tokyo, and Shanghai tertiary centers, limiting standardization across secondary hospitals.
- Neurology:Stroke triage protocols in South Korea's MFDS-regulated emergency networks favor rapid acquisition systems with automated hemorrhage detection algorithms.
- Trauma:Whole-body polytrauma scanning in India's accident and emergency departments demands robust tube thermal capacity for continuous high-kVp operation.
By procedure volume, oncology leads. By reimbursement expansion, cardiovascular applications are advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium pricing for photon-counting CT systems while Indonesia's archipelago geography forces cost-absorbing mobile deployment models. This asymmetry shapes vendor portfolio allocation across the region.
China
Provincial health networks under the 14th Five-Year Plan are replacing aging 16-slice CT bases with 256-slice systems. NMPA's expedited Class III registration for domestic AI-integrated platforms compresses approval timelines for local developers. Sichuan and Guangdong provinces weight NMPA-certified software integration above raw detector specifications in tender documents.
Japan
Quaternary hospitals in Osaka and Yokohama deploy photon-counting platforms for coronary plaque characterization at triple conventional acquisition speeds. PMDA enforces stringent post-market surveillance for CT software updates, filtering non-compliant manufacturers from reimbursed procurement channels. Tokyo's tertiary corridor concentrates demand for spectral tissue differentiation capabilities.
India
Diagnostic chains in Delhi and Mumbai deploy helical CT systems for high-throughput outpatient screening where patient volumes justify continuous operation. CDSCO medical device rules impose layered duties on non-ASEAN certified components, inflating landed costs for European and North American platforms. Secondary hospitals across Maharashtra and Karnataka upgrade from single-slice legacy infrastructure.
South Korea
Cancer centers in Seoul and Busan anchor demand for capital-intensive PET-CT hybrid systems. MFDS-regulated emergency networks favor rapid acquisition systems with automated hemorrhage detection algorithms for stroke triage protocols. The Seoul Capital Area concentrates cardiac CT perfusion technologist training, limiting protocol standardization beyond tertiary centers.
Australia
Metropolitan outpatient facilities deploy compact 64-slice systems for same-day discharge protocols. TGA streamlined registration accelerates deployment timelines for software-as-medical-device CT applications. Sydney and Melbourne pediatric hospitals pilot motion correction algorithms for uncooperative patient protocols.
Asia-Pacific CT Market Competitive Environment
Concentration sits with multinational imaging conglomerates and state-backed domestic manufacturers. The vendor base stratifies across premium photon-counting specialists, mid-tier volume suppliers, and government-procurement-focused local fabricators. Three archetypes dominate: technology licensors with proprietary detector platforms, scale-driven assemblers with provincial tender access, and hybrid-service operators unbundling equipment from per-scan contracts. Competitive moves center on joint ventures for NMPA certification and predictive remote monitoring infrastructure for risk-transfer leasing models.
Among Japan-based conglomerates, Canon Medical Systems Corporation and Fujifilm Holdings Corporation occupy positions within the premium-tier imaging segment. Siemens Healthineers, a German-based entity, exemplifies the technology licensor archetype through its photon-counting platform positioning. Neusoft Medical Systems Co Ltd represents the state-protected domestic manufacturer model with provincial health network procurement access. These three anchors illustrate the competitive tension between multinational premium positioning and localized manufacturing scale.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| GE Healthcare |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Neusoft Medical Systems Co Ltd |
| Shenzhen Anke High-Tech Co Ltd |
| Shanghai United Imaging Healthcare Co Ltd |
| Hitachi Medical Corporation |
| Fujifilm Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Japan's PMDA quality enforcement gates both supplier qualification and price differentiation simultaneously, concentrating procurement among certified manufacturers while compressing margins for non-compliant entrants attempting premium positioning.
Pricing Analysis
Configured-to-order pricing for photon-counting CT platforms commands spreads of 40-60% above standard multi-slice systems. Three-tier pricing structure across premium, standard, and economy levels reflects detector sophistication, NMPA certification status, and bundled service intensity. Cost compression in mid-tier helical systems intensifies because Chinese provincial tenders weight software integration above hardware specifications. Government hospital networks exhibit highest price sensitivity, while Japanese quaternary centers prioritize acquisition speed over unit economics.
Supply Chain Analysis
Xenon detector crystal production concentrates in Japanese and German specialty material suppliers, creating single-source vulnerability for CT detector module assemblers. High-purity cadmium telluride semiconductors and scintillator crystals draw from concentrated upstream refining capacity. Tariff exposure runs through India's CDSCO layered duties on non-ASEAN certified components. Distribution runs through provincial government tender channels in China and private diagnostic chain leasing arrangements across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with service-lease operators unbundling equipment ownership from per-scan reimbursement, as diagnostic chains across Vietnam and Thailand transfer utilization risk to manufacturers.
For Market Incumbents: Compound installed base advantages by embedding predictive remote monitoring infrastructure that locks in multi-year service contracts. Deepen backward integration into detector module assembly to offset xenon crystal supply concentration. Defend against Neusoft and United Imaging by accelerating NMPA joint ventures for AI-integrated platform certification. For New Entrants and Emerging Players: Differentiate on mobile CT deployment models serving Indonesia's archipelago connectivity gaps where fixed-site competition is absent. Target Australia's TGA streamlined registration pathway for software-as-medical-device applications. Penetrate through per-scan leasing arrangements that transfer utilization risk and require minimal capital commitment from diagnostic chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic imaging center operators in Southeast Asia seeking consolidation capital. Long-term viability favors vendors with captive AI reconstruction software development and provincial tender access in China. Watch NMPA Class III registration timeline compression as inflection indicator for domestic platform competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Joint Venture Formation | Accelerates Class III registration timelines for AI-integrated CT platforms in Sichuan and Guangdong procurement channels. |
| Photon-Counting Detector Backward Integration | Captures cadmium telluride semiconductor supply chain margin and reduces Japanese-German crystal supplier dependency. |
| Mobile CT Service-Lease Expansion | Exploits Indonesia's archipelago geography gap where fixed-site infrastructure cannot reach remote island provinces. |
| Predictive Remote Monitoring Infrastructure | Enables per-scan reimbursement models transferring utilization risk to manufacturers across Vietnamese diagnostic chains. |
| TGA Software-as-Medical-Device Registration | Opens priority review pathways for AI reconstruction algorithms targeting Australian radiology workflow automation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and CT system service technicians. Secondary validation drew from NMPA Class III registration filings, PMDA post-market surveillance databases, provincial health network tender documents, and customs import records for CT detector components. Bottom-up installed base enumeration triangulated against top-down healthcare infrastructure expenditure tracking.
Across the analysis window, the forecast framework modeled revenue trajectories by slice-count tier, mobility configuration, end-user channel, and technology generation. CAGRs were derived from replacement cycle analysis of aging 16-slice installed bases and penetration assumptions for photon-counting platforms. Key inputs included provincial Five-Year Plan procurement mandates, reimbursement rate adjustments by Japan's Ministry of Health, and AI software certification timelines.
Material uncertainties — NMPA regulatory acceleration, xenon crystal supply disruptions, and provincial budget reallocation — sit outside the modeled envelope. Forecasts reflect assumptions about technology adoption curves and procurement continuity that practitioners should keep alternative scenarios live as China's domestic platform competitiveness evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital X Ray Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
United Kingdom Computed Tomography Market