
 Germany Mammography Market | 2026-2036
Germany Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Mammography Market Analysis
Equipment leasing and pay-per-scan service contracts is tilting competitive dynamics toward vendors with strong balance sheets and service infrastructure. Siemens Healthineers anchors its position through captive financing arms that bundle hardware, software, and maintenance into multi-year agreements. Hologic competes by leveraging dense field service networks across German metropolitan clusters. Fujifilm Holdings Corporation differentiates through flexible asset-light arrangements that reduce capital barriers for mid-sized breast clinics.
Mammography denotes X-ray imaging of breast tissue using low-dose ionizing radiation, typically operating at 25–35 kVp with molybdenum or rhodium target-filter combinations to optimize soft-tissue contrast for lesion detection. Its primary commercial purpose centers on population-scale breast cancer screening and diagnostic workup of palpable abnormalities. Digital mammography systems command the dominant installed base, though 3D mammography segments built on tomosynthesis architecture are capturing disproportionate capital allocation as clinics seek resolution advantages in dense breast tissue. Full-field digital tomosynthesis leads technology deployment, while contrast-enhanced mammography remains confined to research institutions and tertiary referral centers where vascular kinetics study justifies higher per-exam costs.
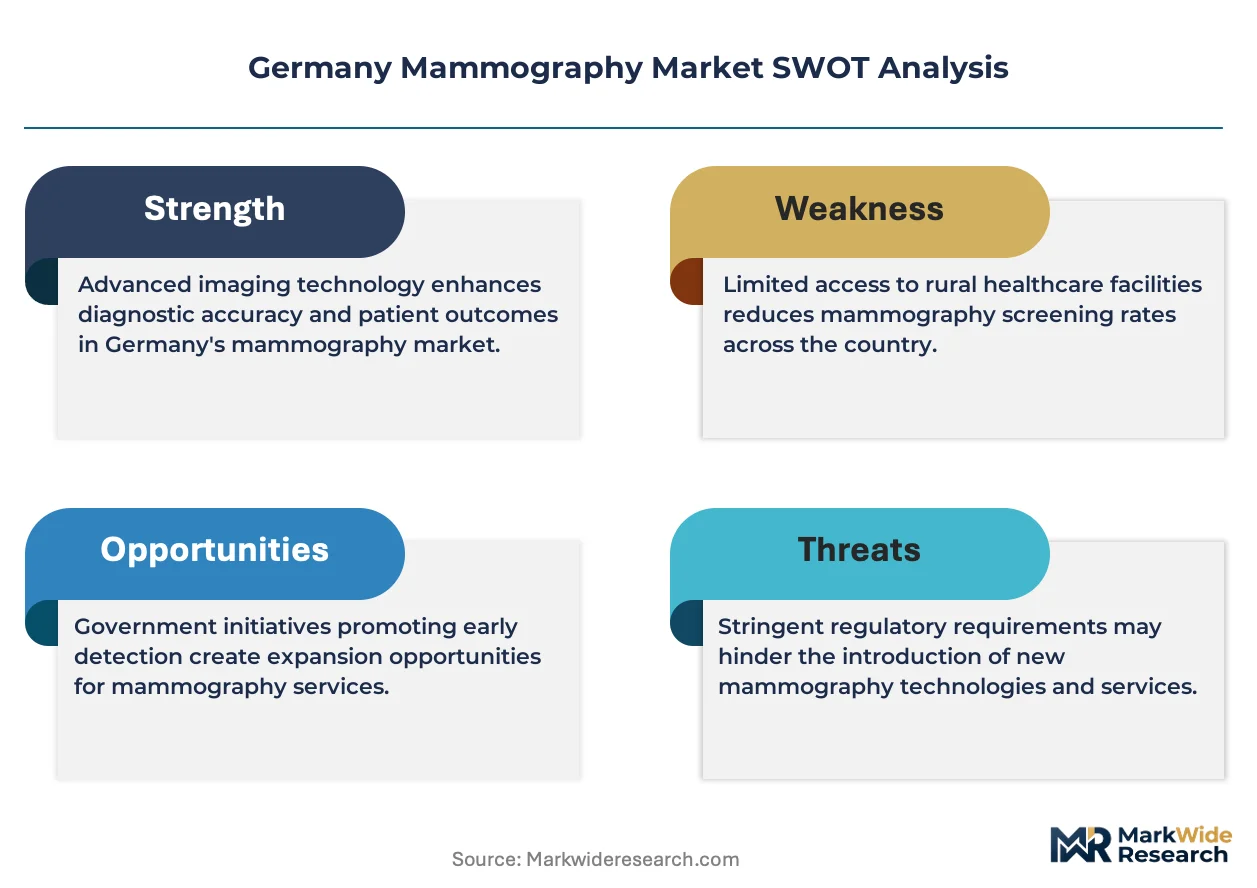
The EU Medical Device Regulation and Germany's Federal Institute for Drugs and Medical Devices enforce escalating clinical evidence and post-market surveillance obligations on mammography system manufacturers. KBA-equivalent notified body capacity constraints are lengthening conformity assessment timelines, advantaging incumbents with established quality management systems over new entrants. Stakeholders must monitor reimbursement parity negotiations between statutory health insurers and outpatient breast imaging providers, as fee schedule adjustments will determine whether tomosynthesis premium pricing sustains against budget-conscious screening program administrators.
Market Dynamics
The transition from 2D digital mammography to 3D tomosynthesis systems is compressing replacement cycles and forcing capital reallocation across Germany's breast imaging infrastructure. This technology shift concentrates purchasing power within hospital networks that can amortize equipment costs across high-volume screening programs.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter quality management system requirements are accelerating consolidation among imaging providers, favoring accredited facilities with established clinical evidence portfolios.
- Bavaria's university hospital network:Dense breast cancer screening populations in southern Germany generate sustained demand for high-resolution diagnostic capacity and specialized radiologist expertise.
- Digital breast tomosynthesis:Superior lesion detection in dense breast tissue is driving replacement demand from full-field digital mammography systems installed during the 2010s upgrade wave.
Market Restraints
- Notified body capacity constraints:KBA-equivalent conformity assessment timelines have lengthened substantially, delaying product approvals and freezing capital deployment for equipment vendors.
- Radiologist workforce limitations:Specialized breast imaging expertise concentrates in metropolitan clusters, creating service access gaps in rural eastern German states.
- Statutory health insurance reimbursement parity:Fee schedule negotiations between insurers and outpatient providers threaten tomosynthesis premium pricing sustainability against budget-conscious screening administrators.
Strategic Opportunities
- Contrast-enhanced mammography:Vascular kinetics applications at tertiary referral centers offer expansion paths beyond standard screening into diagnostic oncology workflows.
- Pay-per-scan service contracts:Asset-light arrangements reduce capital barriers for mid-sized breast clinics in North Rhine-Westphalia and Baden-Württemberg.
- Artificial intelligence integration:Computer-aided detection algorithms paired with tomosynthesis systems promise workflow compression and radiologist productivity gains.
Industry Challenges
- Post-market surveillance obligations:MDR-mandated clinical follow-up and vigilance reporting impose operational burdens on imaging departments with limited quality management resources.
- Legacy system integration:PACS connectivity and data migration from older digital mammography platforms complicate upgrade timelines and disrupt screening program continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Mammography Market |
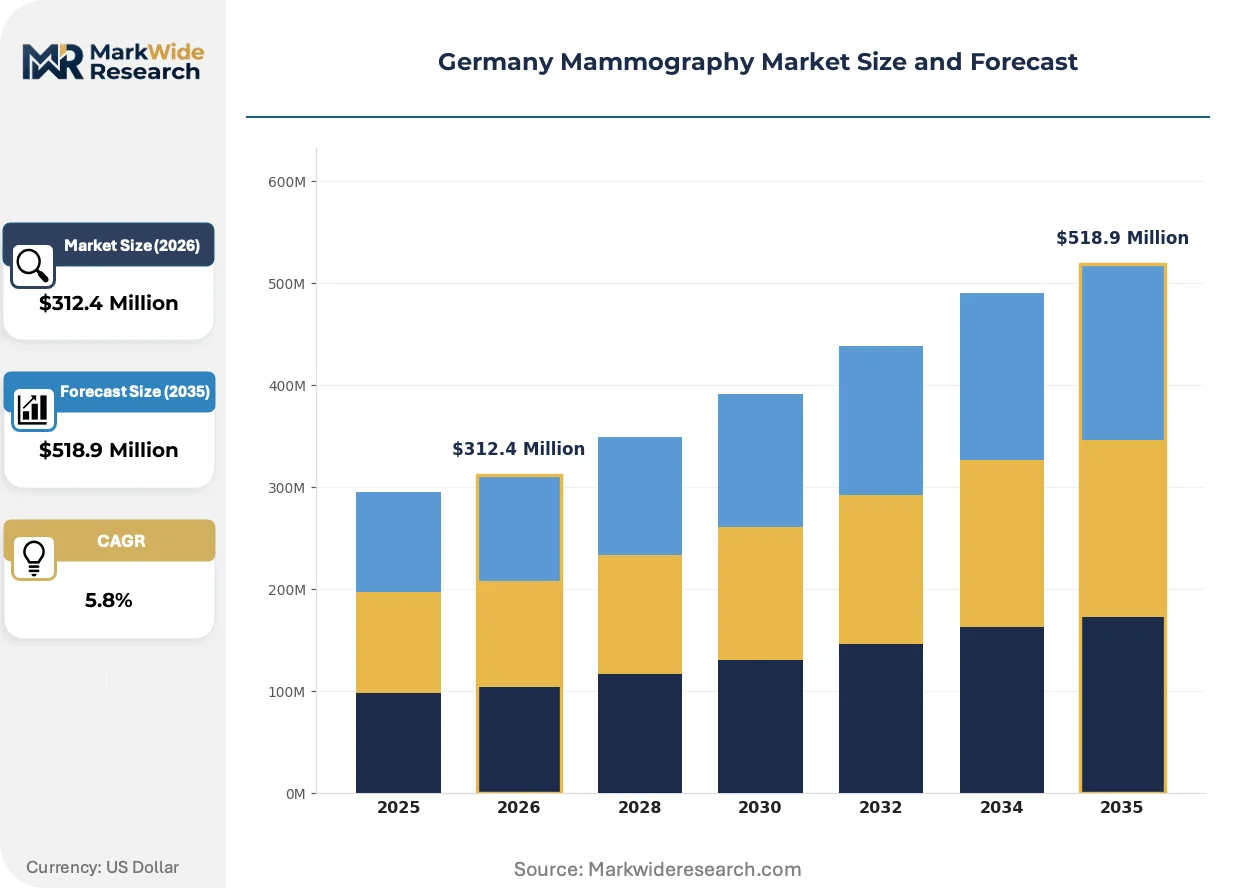
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, 3D Mammography, Analog Mammography, Portable Mammography Technology: Tomosynthesis, Contrast-Enhanced Mammography, Full-Field Digital Tomosynthesis, Screen-Film End User: Hospitals, Diagnostic Centers, Breast Clinics, Research Institutions Delivery Mode: Mobile Units, Fixed Units, Home Care Services, Remote Consultations |
| Companies Covered | Koninklijke Philips NV, Fujifilm Holdings Corporation, Siemens Healthineers AG, Planmed Oy, Carestream Health Inc., Hologic Inc., Canon Inc. (Canon Medical Systems Corporation), Metaltronica S.p.A., GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Mammography Market Emerging Trajectories
Artificial intelligence and advanced visualization software are virtualizing traditional radiologist workflows, while regulatory pressure and procurement model evolution reshape how breast imaging capacity reaches patients.
Tomosynthesis reconstruction software is virtualizing the diagnostic reading environment by enabling remote interpretation and centralized quality assurance. University hospital networks in Bavaria and Baden-Württemberg are deploying cloud-based workstations to pool specialist radiologist capacity across dispersed screening sites. This virtualization is compressing the geographic radius within which specialized expertise must physically locate.
Germany's Federal Institute for Drugs and Medical Devices is enforcing escalated clinical evidence requirements under the EU Medical Device Regulation for software-as-medical-device classifications. AI-based detection algorithms now face substantive equivalence hurdles that extend development timelines and increase validation costs. Tertiary referral centers with established research infrastructure are absorbing these compliance burdens faster than community breast clinics.
Hospital radiology departments are consolidating equipment procurement through multi-year managed service agreements that bundle hardware, software, maintenance, and financing. Traditional capital purchase models are retreating to smaller private breast clinics with constrained balance sheets. This transition concentrates vendor relationships within purchasing cooperatives operating across North Rhine-Westphalia's hospital network.
Germany Mammography Market Segmentation
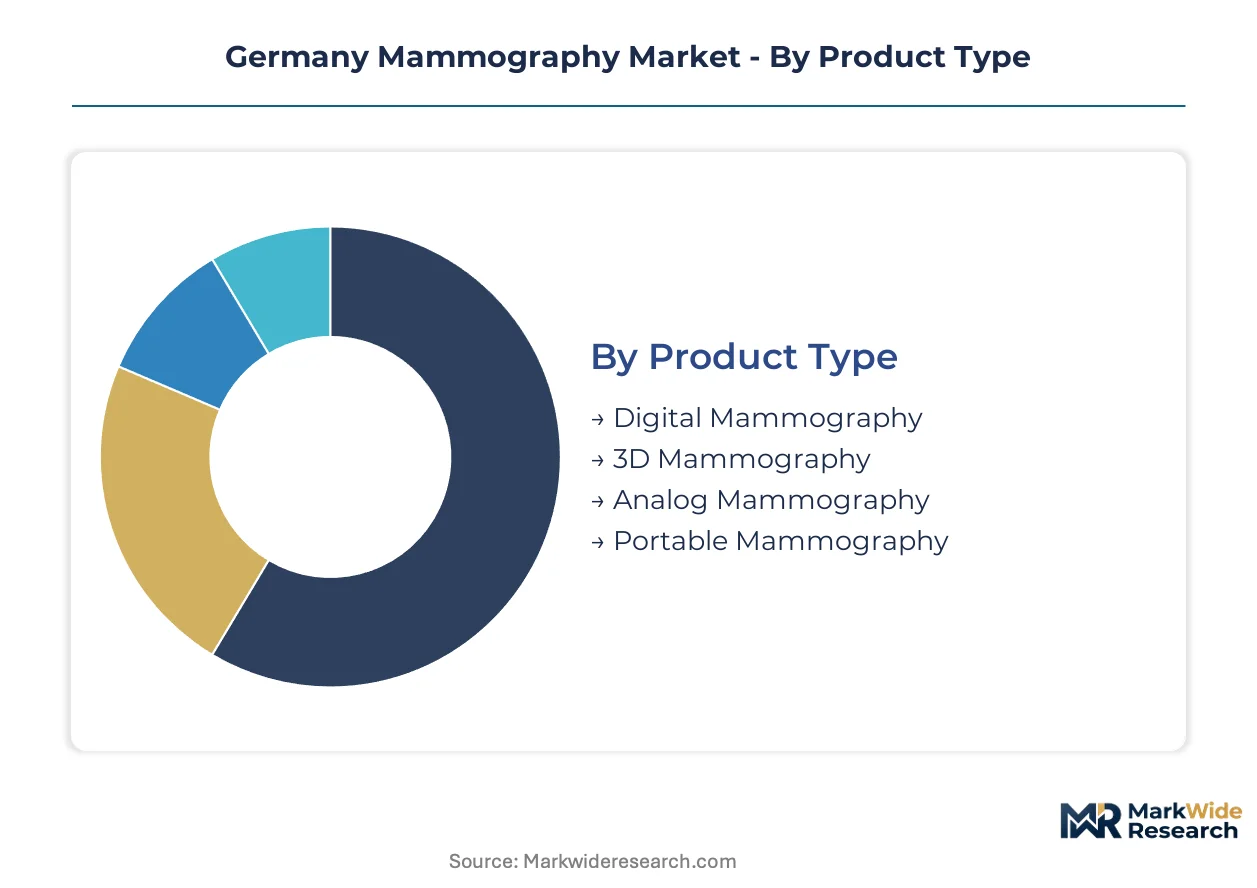
Segmentation in the Germany Mammography Market reveals how technology maturity, reimbursement structures, and service delivery models fragment purchasing power across distinct customer profiles. Each dimension carries specific regulatory and operational constraints that reshape vendor go-to-market strategies.
Product Type:
Maturity divides the product spectrum sharply, with digital platforms dominating installed base economics while 3D systems capture disproportionate capital allocation.
- Digital Mammography:Full-field digital systems utilizing amorphous selenium or cesium iodide detectors generate the bulk of screening program throughput. Bavaria's university hospital network maintains the densest concentration of these systems, though replacement demand is accelerating as units installed during the 2010s upgrade cycle reach end-of-life.
- 3D Mammography:Tomosynthesis-based architectures reconstruct multiple low-dose projection angles into pseudo-3D datasets, improving lesion detection in dense breast tissue. North Rhine-Westphalia's hospital purchasing cooperatives are channeling capital toward these systems as statutory health insurers negotiate reimbursement parity for tomosynthesis exams.
- Analog Mammography:Screen-film systems persist in legacy screening sites with constrained capital budgets, primarily in rural eastern German states where replacement cycles lag metropolitan clusters.
- Portable Mammography:Compact systems mounted on mobile chassis serve decentralized screening programs and temporary diagnostic deployments across Baden-Württemberg's dispersed population centers.
Digital Mammography retains volume leadership; 3D Mammography holds the steepest expansion curve.
Technology:
Cost tier stratification separates research-grade innovations from screening-scale workhorse platforms, with reimbursement codes determining viable deployment economics.
- Tomosynthesis:Multi-angle X-ray acquisition with iterative reconstruction algorithms enables thin-slice visualization through breast tissue. KBA-equivalent notified bodies are extending conformity assessment timelines for these systems under MDR requirements.
- Contrast-Enhanced Mammography:Iodinated contrast injection paired with dual-energy subtraction imaging isolates vascular kinetics of suspicious lesions. Tertiary referral centers in Berlin and Munich absorb the higher per-exam costs for diagnostic oncology workflows.
- Full-Field Digital Tomosynthesis:Integrated 2D synthetic mammogram generation from tomosynthesis datasets eliminates separate compression exposures, streamlining screening throughput in high-volume programs.
- Screen-Film:Analog capture on single-emulsion films with dedicated cassettes survives only where digital infrastructure investment remains economically prohibitive.
Full-Field Digital Tomosynthesis commands the broadest installed base; Contrast-Enhanced Mammography is gaining share fastest among academic medical centers.
End User:
Customer type determines procurement modality, with hospital networks favoring managed service agreements and independent clinics seeking asset-light arrangements.
- Hospitals:Radiology departments within Germany's statutory hospital system aggregate screening volume across multi-site networks, amortizing equipment costs through centralized quality management systems that satisfy MDR post-market surveillance obligations.
- Diagnostic Centers:Specialized outpatient imaging facilities compete for referrals from gynecology practices, with fee schedule negotiations between statutory health insurers and regional medical associations determining service line viability.
- Breast Clinics:Dedicated facilities concentrate mammography with ultrasound and biopsy capabilities, often operating under pay-per-scan service contracts that reduce capital barriers.
- Research Institutions:University hospitals and academic medical centers pilot AI-integrated detection algorithms and contrast-enhanced protocols, absorbing validation costs that community sites cannot sustain.
Hospitals retain volume leadership; Breast Clinics hold the steepest expansion curve.
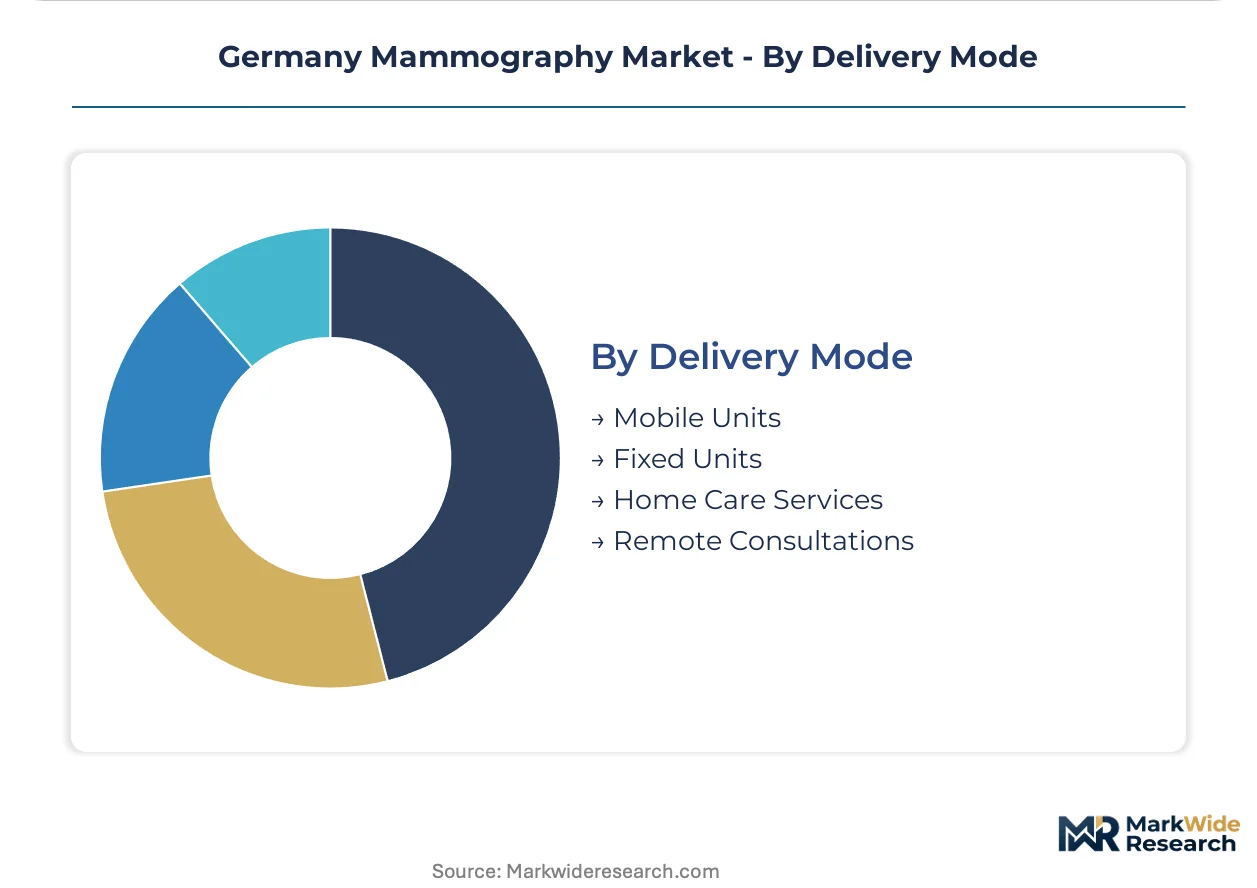
Delivery Mode:
Geography shapes deployment architecture, with population density and infrastructure access determining fixed versus mobile service economics.
- Mobile Units:Truck-mounted mammography systems rotate through rural communities and workplace screening programs, extending access beyond permanent imaging infrastructure. Eastern German states with radiologist workforce shortages depend heavily on these deployments.
- Fixed Units:Permanent installations within hospital radiology departments or dedicated breast centers anchor high-volume screening programs and complex diagnostic workups requiring immediate biopsy correlation.
- Home Care Services:Limited deployment for bedbound patients or post-surgical monitoring, constrained by radiation safety protocols and equipment transport logistics.
- Remote Consultations:Cloud-based image transmission enables centralized radiologist interpretation of screening studies acquired at dispersed sites, compressing the geographic radius of specialized expertise.
Fixed Units retain volume leadership; Mobile Units hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Institute for Drugs and Medical Devices enforces EU Medical Device Regulation compliance timelines that reshape capital deployment across mammography infrastructure. Bavaria's university hospital network drives premium-system demand while eastern states depend on mobile screening deployments.
Bavaria
Munich and Erlangen anchor the densest concentration of digital breast tomosynthesis installations serving high-volume screening populations. KBA-equivalent notified bodies process conformity assessments for new system approvals from manufacturers headquartered in this southern cluster. University hospitals in Nuremberg and Würzburg pilot AI-integrated detection algorithms alongside standard screening programs.
North Rhine-Westphalia
Hospital purchasing cooperatives in Cologne and Düsseldorf aggregate equipment procurement through multi-year managed service agreements bundling hardware and maintenance. The region's statutory health insurers negotiate reimbursement parity for tomosynthesis exams with outpatient breast imaging providers. Essen and Dortmund host specialized breast clinics operating under pay-per-scan contracts that reduce capital barriers.
Baden-Württemberg
Stuttgart and Karlsruhe radiology departments expand cloud-based workstation networks enabling centralized radiologist interpretation across dispersed screening sites. The state's manufacturing heritage supports precision-engineering suppliers for mammography system components. Heidelberg and Freiburg university medical centers absorb MDR-mandated clinical follow-up burdens faster than community sites.
Berlin-Brandenburg
Charité and other tertiary referral centers in Berlin concentrate contrast-enhanced mammography for diagnostic oncology workflows requiring vascular kinetics study. The capital's research infrastructure validates software-as-medical-device classifications under escalated EU regulatory requirements. Potsdam and surrounding areas face radiologist workforce limitations that extend mobile unit deployment schedules.
Lower Saxony
Hanover and Braunschweig hospital networks amortize equipment costs across medium-volume screening programs with mixed urban-rural catchment areas. The region's eastern districts depend heavily on truck-mounted mammography systems rotating through communities beyond permanent imaging infrastructure. Wolfsburg's industrial health programs supplement statutory screening with workplace-based breast imaging deployments.
Germany Mammography Market Vendor Landscape
On the supply side, the industry is consolidating around vendors with captive financing capacity and established quality management systems. Three strategic archetypes dominate: diversified medical technology conglomerates with integrated service arms, specialized breast imaging manufacturers with dense field networks, and precision imaging specialists leveraging flexible contract structures. Competitive positioning hinges on multi-year managed service agreements and pay-per-scan arrangements that displace traditional capital purchase models.
Among diversified healthcare technology groups, Siemens Healthineers AG and Koninklijke Philips NV exemplify archetypes with integrated financing and maintenance bundling. Hologic Inc. represents the specialized breast imaging tier with field service density across German metropolitan clusters. Fujifilm Holdings Corporation occupies a position within flexible asset-light arrangement providers serving mid-sized clinics with reduced capital barriers.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Fujifilm Holdings Corporation |
| Siemens Healthineers AG |
| Planmed Oy |
| Carestream Health Inc. |
| Hologic Inc. |
| Canon Inc. (Canon Medical Systems Corporation) |
| Metaltronica S.p.A. |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Detector manufacturing concentrates in Japan and the Netherlands, anchoring margin capture for amorphous selenium and cesium iodide sensor substrates that feed into German system integrators. MDR certification tiers then stratify downstream pricing power, with KBA-equivalent notified body approvals commanding substantial premiums over baseline CE-marked configurations.
Pricing Analysis
Certification level creates the primary spread between MDR-compliant systems and legacy MDD-transitioned inventory still circulating in secondary markets. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity: premium tiers fold multi-year service contracts and AI software licenses into per-system rates, while economy configurations target cash-constrained breast clinics with stripped hardware-only offerings. Pricing pressure stems from statutory health insurance reimbursement negotiations that threaten tomosynthesis premium sustainability. Mid-sized outpatient diagnostic centers exhibit highest price sensitivity, whereas Bavaria's university hospital networks prioritize clinical evidence portfolios over acquisition cost.
Supply Chain Analysis
X-ray tube feedstock draws from Japanese and US precision manufacturing clusters, with rotating anode assemblies and molybdenum-rhodium target-filter combinations sourced from concentrated specialty metalworking facilities. Cesium iodide scintillator crystals and amorphous selenium photoconductor layers constitute critical material dependencies with limited qualified suppliers. Single-source vulnerability runs through high-voltage generator subassemblies, where German system integrators maintain sole-source relationships with Austrian and Swiss power electronics specialists. Distribution runs through hospital purchasing cooperatives in North Rhine-Westphalia and direct manufacturer relationships with large academic medical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's mammography market is recovering from MDR transition disruption, with replacement cycles now accelerating as notified body capacity normalizes and screening programs resume capital deployment.
For Market Incumbents: Entrench service infrastructure density as the primary defensive moat against emerging AI-native competitors. Expand captive financing arms to match Siemens Healthineers' bundled hardware-software-maintenance offerings, while deepening field engineering presence in Baden-Württemberg's dispersed screening sites. MDR post-market surveillance obligations favor incumbents with established quality management systems over new entrants lacking clinical evidence portfolios.
For New Entrants and Emerging Players: Establish a beachhead in pay-per-scan service contracts for mid-sized breast clinics in North Rhine-Westphalia and Lower Saxony's eastern districts. Mobile screening deployments in rural eastern German states present the most penetrable geography, given radiologist workforce shortages that constrain incumbent service coverage. Lead with AI-integrated detection algorithms as the go-to-market differentiator, positioning software-as-medical-device offerings alongside legacy hardware partnerships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized breast imaging manufacturers with dense German field service networks and established KBA-equivalent notified body relationships. Long-term viability hinges on MDR compliance infrastructure that smaller competitors cannot replicate. Watch statutory health insurance reimbursement parity negotiations as the critical inflection signal—positive tomosynthesis fee schedule adjustments would accelerate replacement demand and expand addressable market value.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Quality Management System Certification | KBA-equivalent notified body approval accelerates product market access versus competitor timelines. |
| Hospital System Partnership | Multi-year managed service agreements with Bavaria's university hospital network lock in replacement volume. |
| AI Detection Algorithm Development | Software-as-medical-device classification under EU MDR creates recurring revenue attachment to hardware. |
| Pay-per-Scan Service Contract Expansion | Asset-light arrangements reduce capital barriers for mid-sized breast clinics in Baden-Württemberg. |
| Reimbursement Strategy Engagement | Statutory health insurer negotiations determine tomosynthesis premium pricing sustainability. |
Methodological Framework
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary sources including BfArM device registrations, hospital procurement databases, and statutory health insurer fee schedule filings. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators and healthcare expenditure trends. Primary fieldwork concentrated on radiology department heads within Germany's statutory hospital system and specialized breast clinic operators.
Calibration against historical equipment replacement cycles and MDR implementation timelines shapes the projection framework across product type, technology tier, end-user category, and delivery mode dimensions. CAGRs derive from segmented growth rate assumptions weighted by installed base economics and reimbursement trajectory scenarios. Forecast inputs incorporate notified body capacity constraints, radiologist workforce distribution patterns, and screening program administrator budget elasticity.
Sensitivities concentrate around MDR conformity assessment timeline extensions and statutory health insurance reimbursement parity outcomes. Forecasts reflect assumptions regarding technology transition velocity and capital deployment recovery post-regulatory disruption. Cross-checking against BfArM medical device market surveillance reports and regional hospital association capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
France Mammography Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Radiology Services Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
Mexico Computed Tomography Market