
 Europe Veterinary Healthcare Market | 2026-2036
Europe Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Veterinary Healthcare Market Analysis
Subscription-based preventive care plans is recalibrating how veterinary services are monetized across European practices. Boehringer Ingelheim leverages its biologics manufacturing footprint to supply vaccine portfolios at scale. Zoetis anchors its position through diagnostic-platform integration with in-clinic laboratory workflows. Virbac specializes in parasiticide formulations tailored to regional vector-borne disease profiles.
Europe veterinary healthcare encompasses pharmaceuticals, biologicals, diagnostic instruments, and clinical services administered to companion and production animals, with vaccines requiring cold-chain distribution at two-to-eight degrees Celsius to maintain immunological potency. Its primary purpose centers on disease prevention, therapeutic intervention, and herd health management across food-producing and pet animal populations. Vaccines and antiparasitics command the largest revenue pools given recurring administration schedules and regulatory mandates for core immunization protocols. Diagnostic procedures within the application dimension are expanding fastest as point-of-care analyzers displace reference-lab dependency in mid-sized clinics.
The European Medicines Agency coordinates centralized marketing authorization for veterinary medicinal products, while national competent authorities in Germany, France, and Italy enforce pharmacovigilance and residue monitoring under EU Regulation 2019/6. The EU Green Deal agricultural sustainability targets are redirecting R&D investment toward reduced-antibiotic husbandry systems and alternative protein-compatible health protocols. Stakeholders must monitor divergence between EMA centralized pathways and member-state reimbursement policies as pricing authority fragments toward national health technology assessment bodies.
Market Dynamics
The EU Veterinary Medicines Regulation is restructuring authorization pathways while cold-chain vaccine distribution concentrates manufacturing capacity among biologics specialists with validated two-to-eight-degree Celsius infrastructure.
Growth Catalysts
- EMA Centralized Pathways:The European Medicines Agency's unified marketing authorization reduces regulatory duplication across member states, accelerating product launch timelines for multispecies vaccines.
- Pet Insurance Ecosystems:France, Germany, and the United Kingdom maintain mature reimbursement structures that normalize preventive care expenditure and reduce price sensitivity among companion animal owners.
- Point-of-Care Diagnostics:In-clinic laboratory analyzers are compressing turnaround times for hematology and biochemistry panels, enabling same-day therapeutic decisions in mid-sized practices.
Market Restraints
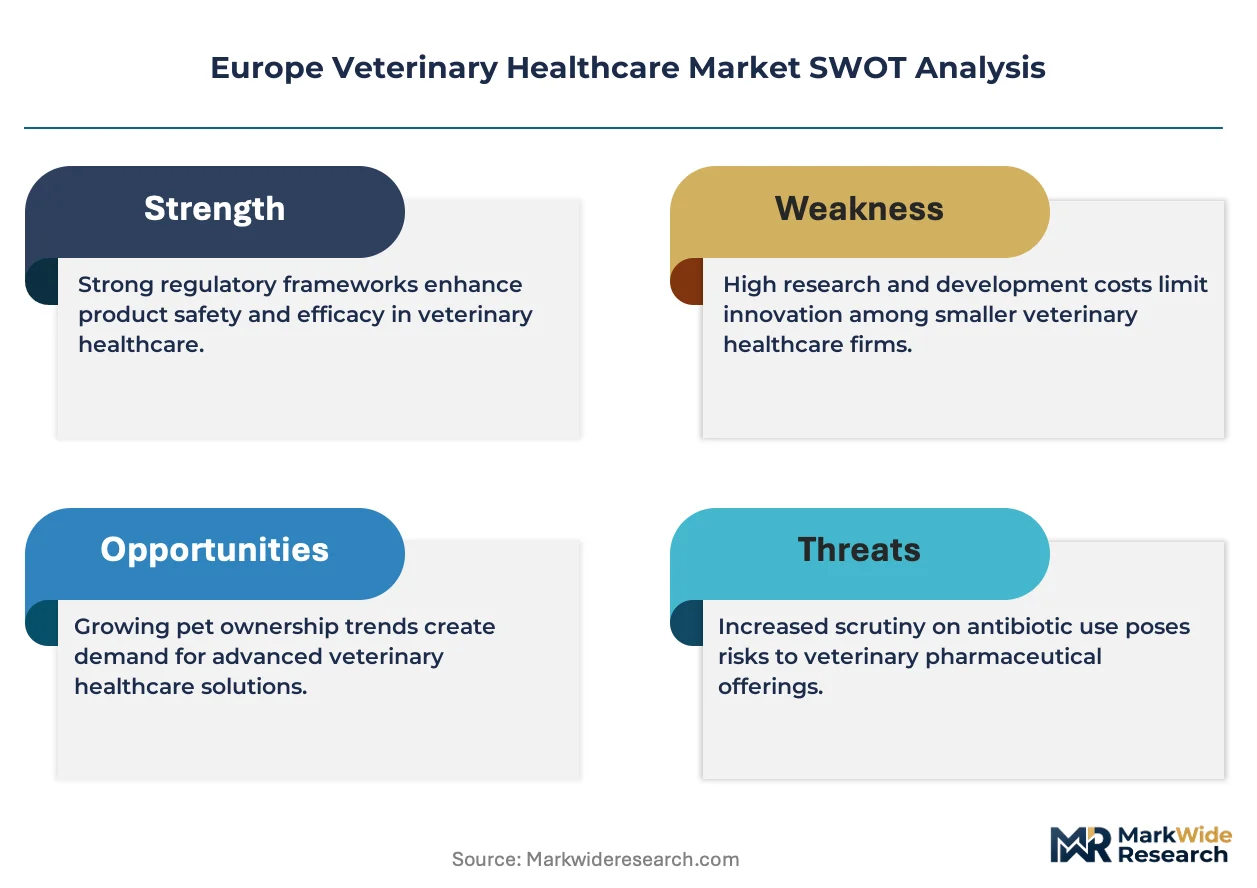
- Antibiotic Stewardship Mandates:EU Green Deal agricultural sustainability targets restrict antimicrobial use in food-producing animals, eliminating historical revenue streams for pharmaceutical manufacturers.
- Cold-Chain Infrastructure Costs:mRNA and vector vaccine platforms require validated continuous refrigeration, creating capital barriers for regional distributors without captive logistics networks.
- Reference Laboratory Concentration:Diagnostic testing volume concentrates in centralized IDEXX and Mars laboratory networks, marginalizing independent clinic laboratory economics.
Strategic Opportunities
- Digital Therapeutics Integration:Remote monitoring wearables for chronic conditions in companion animals converge with telemedicine platforms, creating subscription revenue models beyond pharmaceutical sales.
- Alternative Protein-Compatible Health Protocols:Insect farming and cultivated meat production systems require novel parasiticide and vaccine formulations adapted to non-traditional species physiology.
- Eastern European Clinic Consolidation:Poland, Romania, and Hungary present acquisition targets for corporate veterinary groups seeking to replicate Western European service-portfolio expansion.
Industry Challenges
- Veterinary Specialist Shortage:Board-certified surgeons and internal medicine practitioners concentrate in urban France, Germany, and the United Kingdom, leaving rural and Eastern European markets underserved.
- Legacy Practice Management System Integration:Independent clinics operate fragmented software stacks that resist interoperability with diagnostic-platform ecosystems, complicating workflow standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Veterinary Healthcare Market |
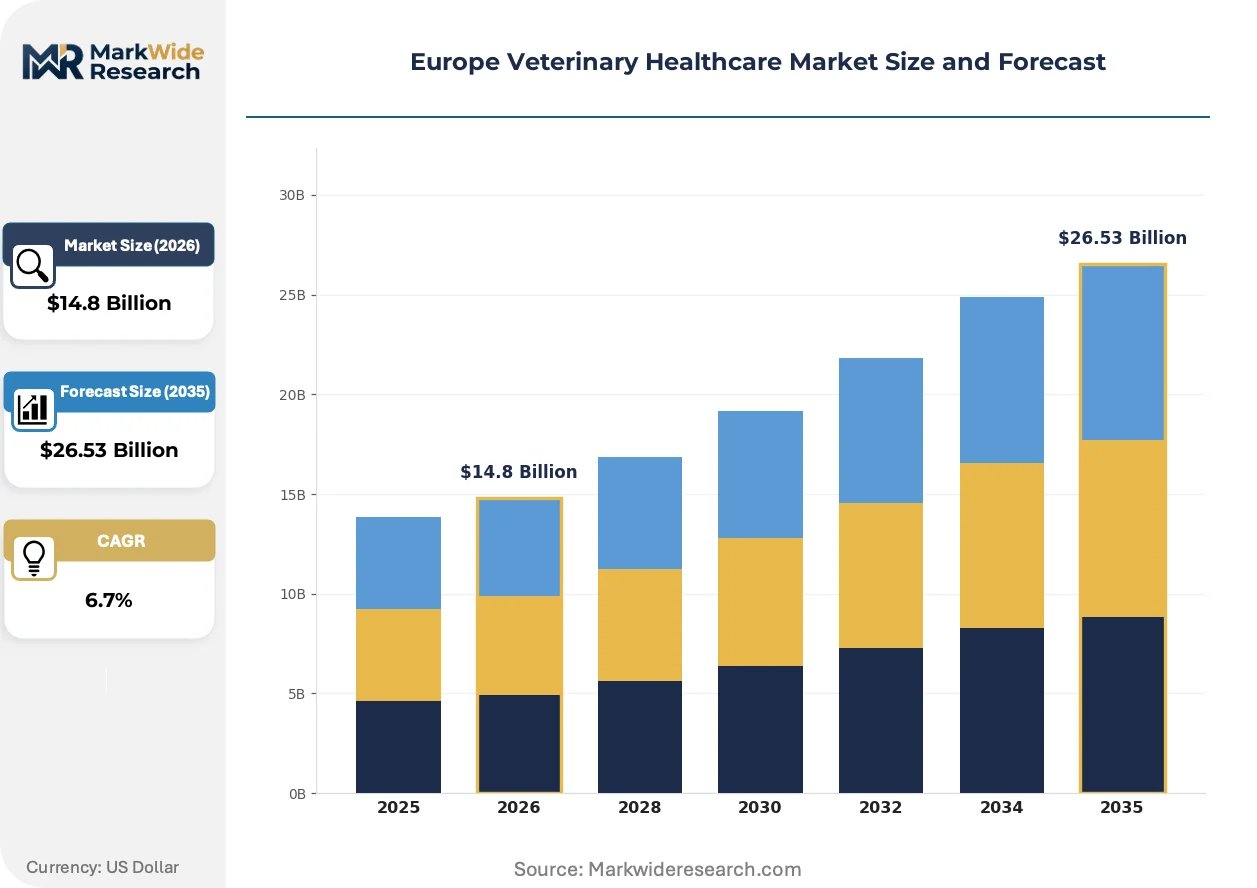
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antiparasitics, Antibiotics, Pain Management End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Pet Owners Application: Preventive Care, Treatment, Diagnostic Procedures, Emergency Care Service Type: Consultation, Surgical Services, Laboratory Services, Rehabilitation |
| Companies Covered | Boehringer Ingelheim, Zoetis, Ceva Santé Animale, MSD Animal Health, Elanco, Virbac, IDEXX Laboratories, Vetoquinol, Dechra Pharmaceuticals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Veterinary Healthcare Market Emerging Trajectories
Artificial intelligence diagnostic algorithms and subscription-based preventive care models are restructuring how veterinary services are delivered and monetized across European markets.
Digital pathology platforms are absorbing image analysis workloads from histopathology reference laboratories. Mid-sized companion animal clinics in the United Kingdom and Germany are adopting whole-slide scanning systems at accelerating pace. This technology is absorbing routine case screening volume while preserving specialist pathologist capacity for complex oncology diagnoses.
The EU Green Deal's Farm to Fork strategy mandates measurable reductions in antimicrobial use across food-producing animal populations. Pharmaceutical manufacturers are reallocating research expenditure toward vaccines and immunomodulators as therapeutic alternatives. Production animal health portfolios face the most acute reformulation pressure, with swine and poultry segments leading antibiotic displacement timelines.
Subscription preventive care plans are replacing transactional service billing in companion animal practices. Corporate veterinary groups in France and the Netherlands bundle vaccinations, parasiticides, and wellness examinations into monthly recurring revenue structures. This behavioral shift is most visible among millennial pet owners in urban markets, where predictable expenditure smoothing outweighs upfront cost minimization preferences.
Europe Veterinary Healthcare Market Segmentation
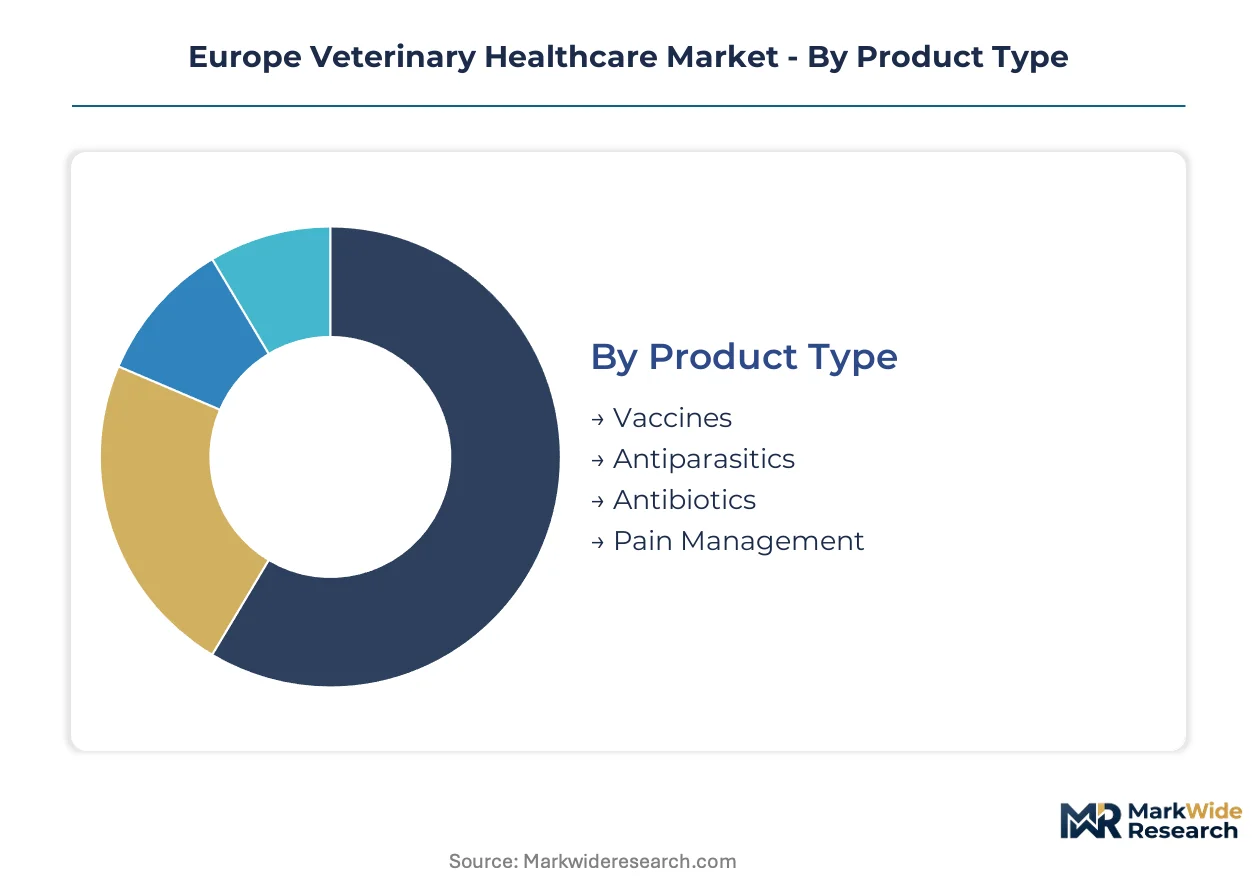
Segmentation reveals how revenue pools concentrate across therapeutic categories and service delivery models. Understanding these divisions exposes where cold-chain infrastructure, diagnostic platform integration, and subscription monetization create divergent margin structures.
Product Type:
Volume leadership rests with mass-administered prophylactics, while premium pricing attaches to specialized therapeutics requiring veterinary prescription authority.
- Vaccines:Multispecies formulations for core immunization protocols require validated two-to-eight-degree Celsius distribution networks. Companion animal clinics in France and Germany absorb the highest per-capita volumes given mandatory rabies protocols and mature pet insurance reimbursement. Cold-chain infrastructure costs create barriers for regional distributors without captive logistics.
- Antiparasitics:Spot-on formulations and oral chewables target regional vector-borne disease profiles varying between Mediterranean tick belts and Nordic heartworm zones. Seasonal administration schedules in Southern Europe generate recurring revenue concentrated in Q2-Q3 purchasing windows.
- Antibiotics:Therapeutic use faces EU Green Deal antimicrobial reduction mandates, shifting demand toward narrow-spectrum alternatives for food-producing animals.
- Pain Management:NSAIDs and opioids for post-surgical recovery and osteoarthritis management command prescription-tier pricing in specialist referral hospitals.
Mature deployment sits with vaccines. Newer deployment is concentrated in pain management.
End User:
Service intensity and procurement sophistication separate institutional buyers from dispersed consumer decision-making.
- Veterinary Clinics:Mid-sized practices in the United Kingdom and Netherlands are consolidating diagnostic platform investments, compressing reference laboratory dependency through in-clinic hematology and biochemistry analyzers. Subscription preventive care plans normalize recurring revenue structures.
- Animal Hospitals:Specialist referral centers concentrate board-certified surgeons and internal medicine practitioners in urban France, Germany, and the United Kingdom. Emergency and critical care capabilities justify premium fee structures.
- Research Institutions:Academic veterinary schools and contract research organizations drive demand for experimental biologics and pharmacokinetic study services.
- Pet Owners:Direct-to-consumer channels remain limited by prescription requirements, though telemedicine platforms are expanding remote consultation access in Nordic markets.
Procurement sophistication peaks at animal hospitals. Volume expansion is climbing fastest at veterinary clinics.
Application:
Recurring revenue potential versus episodic intervention economics shapes portfolio allocation across the care continuum.
- Preventive Care:Vaccination schedules and parasiticide administration generate predictable demand anchored by regulatory mandates and insurance reimbursement normalization in Western European markets.
- Treatment:Therapeutic intervention for infectious and chronic diseases faces margin pressure from generic substitution and antibiotic stewardship restrictions.
- Diagnostic Procedures:Point-of-care testing and advanced imaging are gaining share fastest as mid-sized clinics invest in same-day result capabilities.
- Emergency Care:After-hours trauma and toxicology cases concentrate in specialist hospitals with 24-hour staffing infrastructure.
Recurring revenue concentration favors preventive care. Capital investment intensity is highest in diagnostic procedures.
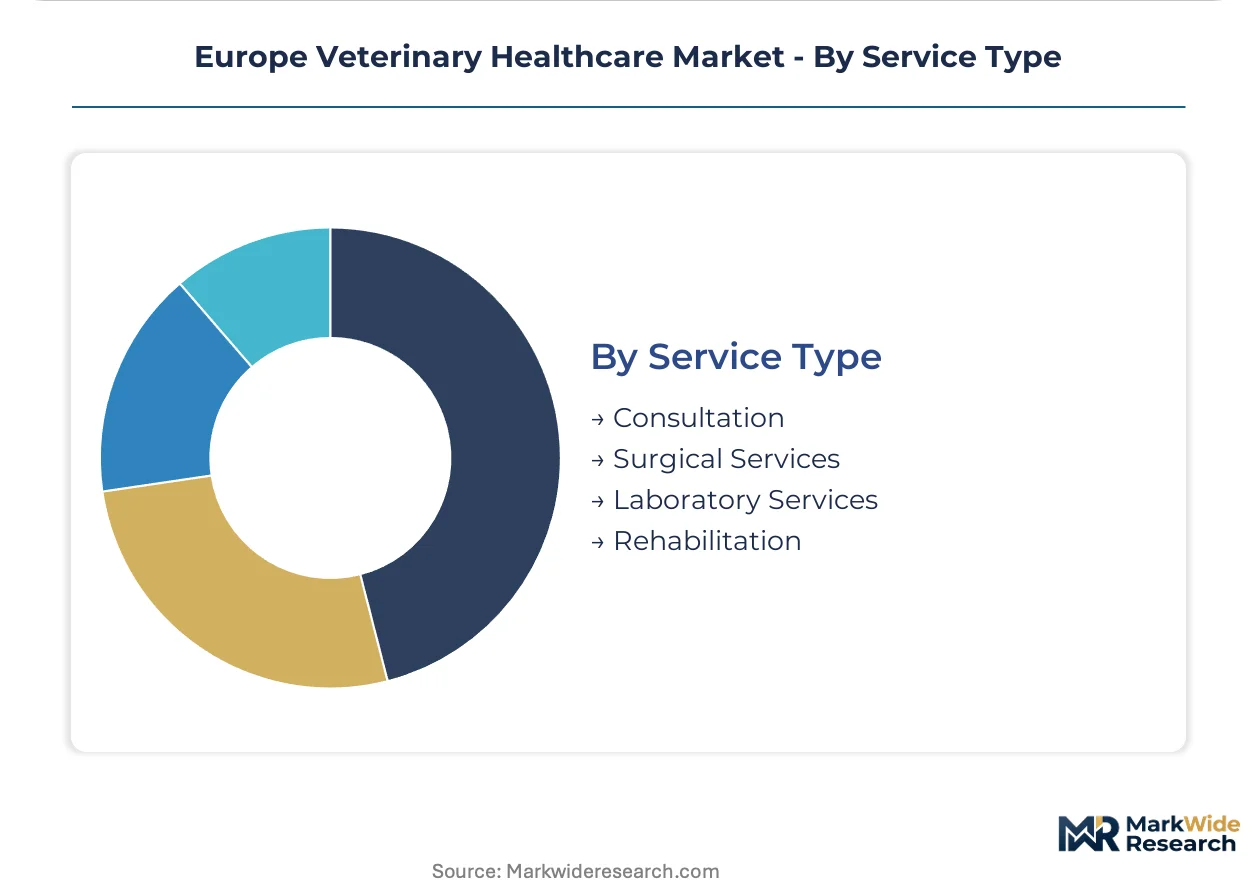
Service Type:
Labor intensity and technology leverage create divergent scalability profiles across service delivery models.
- Consultation:Routine wellness examinations form the entry point for subscription plan enrollment and preventive care compliance monitoring.
- Surgical Services:Soft-tissue and orthopedic procedures require specialist certification concentrated in urban France, Germany, and the United Kingdom referral networks.
- Laboratory Services:In-clinic analyzers and reference laboratory partnerships compete for diagnostic volume, with corporate groups favoring captive laboratory economics.
- Rehabilitation:Post-surgical physiotherapy and hydrotherapy services are expanding in Netherlands and Scandinavian markets with high companion animal spending.
Technology leverage is highest in laboratory services. Specialist labor scarcity constrains surgical services expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of veterinary biologics concentrates in Germany and France, while consumption spreads across Western European markets with mature pet insurance ecosystems. Cold-chain distribution networks radiate from these production hubs toward clinics in the United Kingdom, Netherlands, and Nordic countries. Eastern European markets remain underpenetrated by specialist services despite rising companion animal ownership.
Germany
Companion animal clinics in Munich and Hamburg drive diagnostic platform adoption, with mid-sized practices investing in in-clinic hematology analyzers. The Federal Institute for Drugs and Medical Devices enforces pharmacovigilance under EU Regulation 2019/6. The Baden-Württemberg biologics corridor hosts vaccine manufacturing facilities with validated two-to-eight-degree Celsius distribution infrastructure.
United Kingdom
Corporate veterinary groups in London and Southeast England expand subscription preventive care plans among millennial pet owners. The Veterinary Medicines Directorate operates national residue monitoring programs aligned with EU Green Deal antimicrobial reduction targets. The Cambridge-Oxford research triangle anchors demand for experimental biologics in academic veterinary schools.
France
Specialist referral hospitals in Paris and Lyon concentrate board-certified surgeons and internal medicine practitioners. ANSM coordinates national pharmacovigilance reporting alongside EMA centralized authorization pathways. The Lyon veterinary cluster supports parasiticide formulation R&D tailored to Mediterranean tick-borne disease profiles.
Netherlands
Mid-sized companion animal practices in Amsterdam and Rotterdam lead rehabilitation service expansion including hydrotherapy and post-surgical physiotherapy. The Dutch Medicines Evaluation Board implements health technology assessment for veterinary product reimbursement. The Utrecht veterinary school generates contract research demand for pharmacokinetic study services.
Poland
Independent clinics in Warsaw and Krakow present acquisition targets for corporate groups seeking Western European service-portfolio replication. The Office for Registration of Medicinal Products enforces national marketing authorization procedures pending full EMA centralized pathway alignment. The Wrocław veterinary cluster shows rising demand for point-of-care diagnostics as clinic consolidation accelerates.
Europe Veterinary Healthcare Market Vendor Landscape
Capital-heavy biologics manufacturers compete with asset-light diagnostic platform developers for veterinary practice procurement budgets. The market structure shows tiered consolidation: multinational pharmaceutical conglomerates dominate vaccine and therapeutic categories, while specialized diagnostic instrument makers capture in-clinic laboratory workflows. Three archetypes define competitive positioning: integrated biologics manufacturers with captive cold-chain networks, diagnostic-platform ecosystem orchestrators, and regional parasiticide specialists with vector-borne disease expertise. M&A activity concentrates on Eastern European clinic consolidation, while portfolio diversification moves target alternative protein-compatible health protocols for insect farming systems.
Within the integrated biologics tier, Boehringer Ingelheim and MSD Animal Health exemplify manufacturers with validated vaccine distribution infrastructure. Among diagnostic-platform specialists, IDEXX Laboratories occupies a position as an ecosystem orchestrator for in-clinic laboratory workflows. Virbac represents the regional specialization archetype, with parasiticide formulation expertise anchored in Mediterranean market presence.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Zoetis |
| Ceva Santé Animale |
| MSD Animal Health |
| Elanco |
| Virbac |
| IDEXX Laboratories |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up corporate veterinary groups in France, Germany, and the United Kingdom anchor pricing discipline through subscription preventive care models, while their consolidated procurement power compresses margins for pharmaceutical suppliers without captive cold-chain infrastructure.
Pricing Analysis
Margin tightening in mid-sized companion animal practices reflects generic substitution pressure on antibiotics and the EU Green Deal antimicrobial reduction mandates. Three-tier pricing structure across premium specialist referral, standard corporate clinic, and economy independent practice levels stratifies service access. Price differentiation hinges on after-hours emergency capabilities and diagnostic platform integration depth. Millennial pet owners in insured Western European markets show lowest price sensitivity, while uninsured Eastern European direct-pay clients face highest cost consciousness.
Supply Chain Analysis
Single-source vulnerability sits with mRNA and viral vector vaccine active pharmaceutical ingredients concentrated in Germany and France biologics corridors. Distribution runs through validated two-to-eight-degree Celsius logistics networks radiating from Baden-Württemberg and Lyon manufacturing clusters. Cold-chain infrastructure draws from specialized refrigerant equipment and continuous temperature monitoring systems. Tariff exposure on diagnostic instrument imports from the United States threatens in-clinic analyzer deployment economics in Netherlands and Nordic markets. Regional distributors without captive logistics partnerships face capital barriers to vaccine portfolio participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate consolidation across European veterinary healthcare functions as a forced exit mechanism for independent practices lacking diagnostic platform capital or subscription plan infrastructure.
For Market Incumbents: Extend cold-chain vaccine manufacturing capacity in Germany and France to capture EMA centralized pathway volume, while integrating point-of-care diagnostic platforms into corporate group workflows to displace reference laboratory dependency. Antibiotic stewardship mandates threaten legacy therapeutic revenue streams, requiring accelerated immunomodulator and vaccine R&D allocation. For New Entrants and Emerging Players: Launch via telemedicine-enabled remote consultation platforms targeting underserved rural and Eastern European markets, where specialist practitioner scarcity creates white-space opportunity. Poland and Romania present acquisition-ready independent clinic networks lacking corporate service-portfolio standardization. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized diagnostic platform developers in the United Kingdom and Netherlands with software interoperability capabilities, as legacy practice management system fragmentation forces workflow modernization spend. Watch EMA centralized authorization timeline acceleration as inflection signal for biologics manufacturing capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Integration | IDEXX and Zoetis ecosystems compress reference laboratory economics for mid-sized clinics. |
| Cold-Chain Infrastructure Expansion | Boehringer Ingelheim and MSD Animal Health validate two-to-eight-degree Celsius networks for vaccine distribution. |
| Subscription Preventive Care Rollout | Corporate groups in France and Netherlands bundle services into monthly recurring revenue structures. |
| Eastern European Clinic Consolidation | Poland and Hungary independent practices present acquisition targets for Western European service replication. |
| Alternative Protein Health Protocol Development | Insect farming and cultivated meat systems require novel parasiticide formulations from Virbac and Ceva. |
Methodological Framework
Multi-period observation of veterinary clinic consolidation velocity, diagnostic platform adoption rates, and EMA authorization timelines anchored the trend analysis, supplemented by interviews with pharmaceutical regulatory affairs directors, corporate veterinary group procurement officers, independent practice owners, and biologics manufacturing supply chain managers. Secondary validation drew from EMA centralized procedure databases, EU Veterinary Medicines Regulation implementation tracking, national competent authority pharmacovigilance reports, and pet insurance reimbursement pattern disclosures. Bottom-up clinic-level service revenue modeling triangulated against top-down pharmaceutical manufacturer shipment data.
Segment-weighting across product type, end user, application, and service type dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from historical growth rate regression analysis adjusted for regulatory intervention impacts and technology displacement effects. Modeled inputs incorporated EU Green Deal antimicrobial reduction compliance timelines and point-of-care analyzer capital expenditure cycles in mid-sized practices.
EMA authorization pathway delays, veterinary specialist labor supply constraints, and cold-chain logistics cost inflation are the dominant revision risks to forecast assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Veterinary Software Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Veterinary Scales Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Companion Animal Drugs Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Veterinary Excipients Market
Veterinary
Animal Microchip Implant Market