
 Ophthalmic Ultrasound Devices Market | 2026-2036
Ophthalmic Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Ultrasound Devices Market Intelligence
Trained ophthalmic ultrasonographers is bifurcating the competitive landscape into equipment vendors who bundle training ecosystems and those who rely on third-party certification. Carl Zeiss Meditec AG leverages its installed base of diagnostic platforms to cross-sell ultrasound modules into premium eye care networks. NIDEK Co., Ltd. anchors its position through backward integration into transducer manufacturing, controlling critical component supply. Sonomed Escalon specializes in portable B-Scan systems that occupy the mobile diagnostics segment where hospital capital budgets constrain fixed-device purchases.
Ophthalmic ultrasound devices generate acoustic images of ocular structures using frequencies between 10 MHz and 50 MHz, with axial resolution improving as frequency rises and penetration depth declining proportionally. These instruments serve primary clinical purposes including biometric measurement for intraocular lens calculation, posterior segment visualization through opaque media, and anterior segment angle assessment for glaucoma management. A-Scan and B-Scan product types dominate installed bases across mature markets, while ultrasound biomicroscopy technology commands premium positioning in anterior segment subspecialties where uveitis and angle-closure diagnostics drive replacement cycles. High-frequency ultrasound platforms represent the fastest-growing technology segment as corneal assessment applications expand beyond traditional glaucoma measurement workflows.
The FDA governs device classification and 510(k) clearance pathways for ophthalmic ultrasound systems in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for CE marking of Class IIa and IIb imaging equipment. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility requirements shape manufacturing compliance costs and OEM qualification timelines across all major supply jurisdictions. Stakeholders must monitor how regulatory divergence between FDA streamlined review and EMA MDR transition timelines will reshape geographic launch sequencing and certification investment priorities.
Market Dynamics
Hospital-based ophthalmology departments are consolidating diagnostic workflows around compact point-of-care ultrasound systems, compressing capital deployment cycles and reshaping vendor qualification criteria toward integrated training ecosystems.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated premarket review pathways for digital ophthalmic imaging platforms are reducing clearance timelines and enabling faster commercialization of next-generation ultrasound systems.
- Ambulatory Surgical Center Expansion:United States outpatient facilities are upgrading high-frequency ultrasound capabilities to support glaucoma and retinal procedure volumes.
- Biometric Measurement Demand:Intraocular lens calculation requirements for cataract surgery are driving replacement cycles in mature diagnostic installed bases.
Market Restraints
- Transducer Supply Concentration:Backward-integrated Japanese and German component manufacturers control critical high-frequency transducer supply, creating qualification bottlenecks for second-tier equipment vendors.
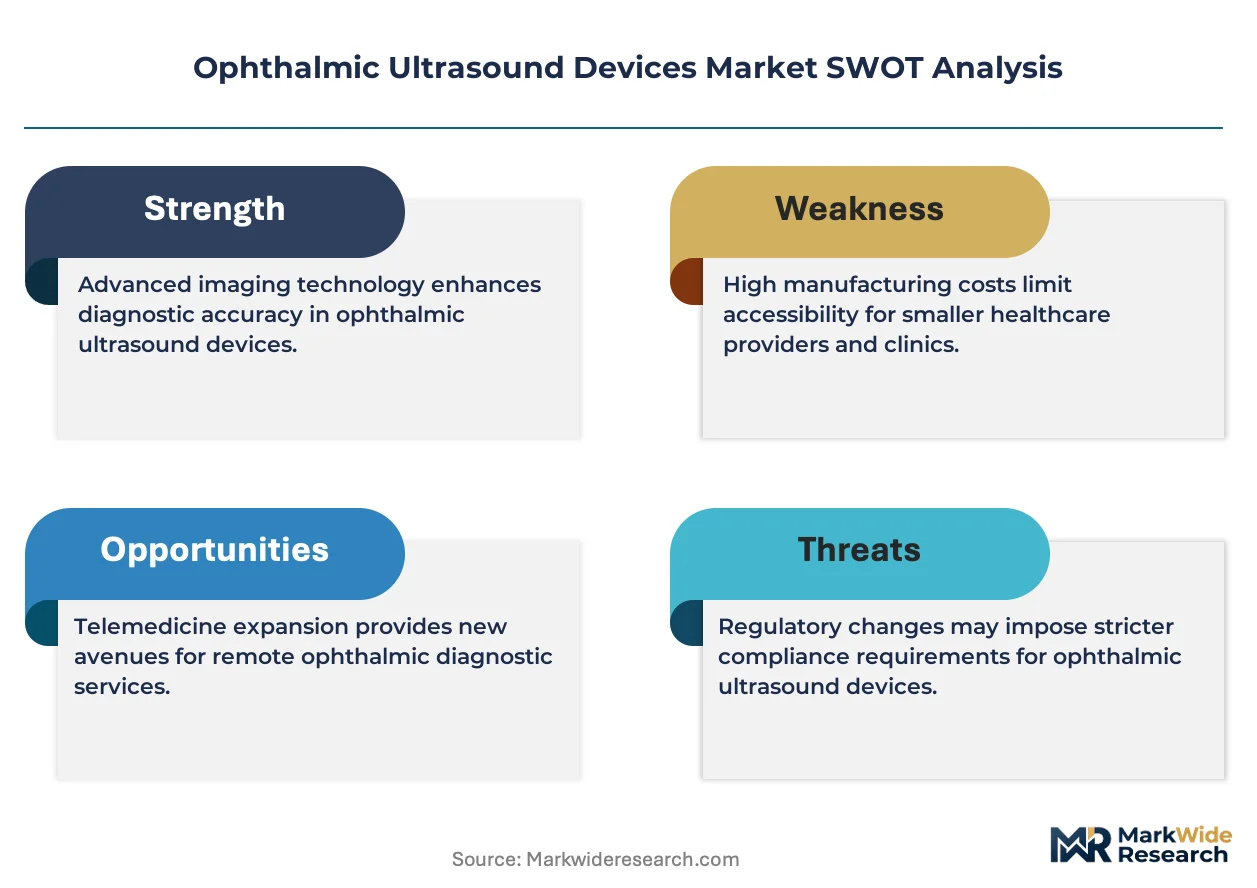
- EU MDR Clinical Evidence Burden:Strengthened CE marking requirements for Class IIa and IIb imaging equipment under the Medical Device Regulation are extending certification timelines and inflating compliance costs.
- Penetration-Resolution Tradeoff:High-frequency ultrasound platforms above 35 MHz deliver superior axial resolution for corneal assessment but sacrifice posterior segment visualization depth.
Strategic Opportunities
- Mobile Diagnostics White Space:Portable B-Scan systems are capturing hospital capital budget constraints that prevent fixed-device procurement in community eye care networks.
- Anterior Segment Subspecialty Expansion:Ultrasound biomicroscopy technology is penetrating uveitis and angle-closure diagnostic workflows beyond traditional glaucoma management.
- Training Ecosystem Bundling:Equipment vendors who integrate certified ultrasonographer education programs are differentiating against competitors reliant on third-party certification pathways.
Industry Challenges
- Certified Ultrasonographer Scarcity:Trained operator availability is bifurcating competitive positioning between vendors with captive training infrastructure and those without.
- Legacy System Integration Complexity:Digital imaging platforms face interoperability friction with existing hospital information systems and PACS architectures.
- Electromagnetic Compliance Certification:IEC 60601-1-2 testing requirements for electromagnetic compatibility are elongating OEM qualification timelines across manufacturing jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Ultrasound Devices Market |
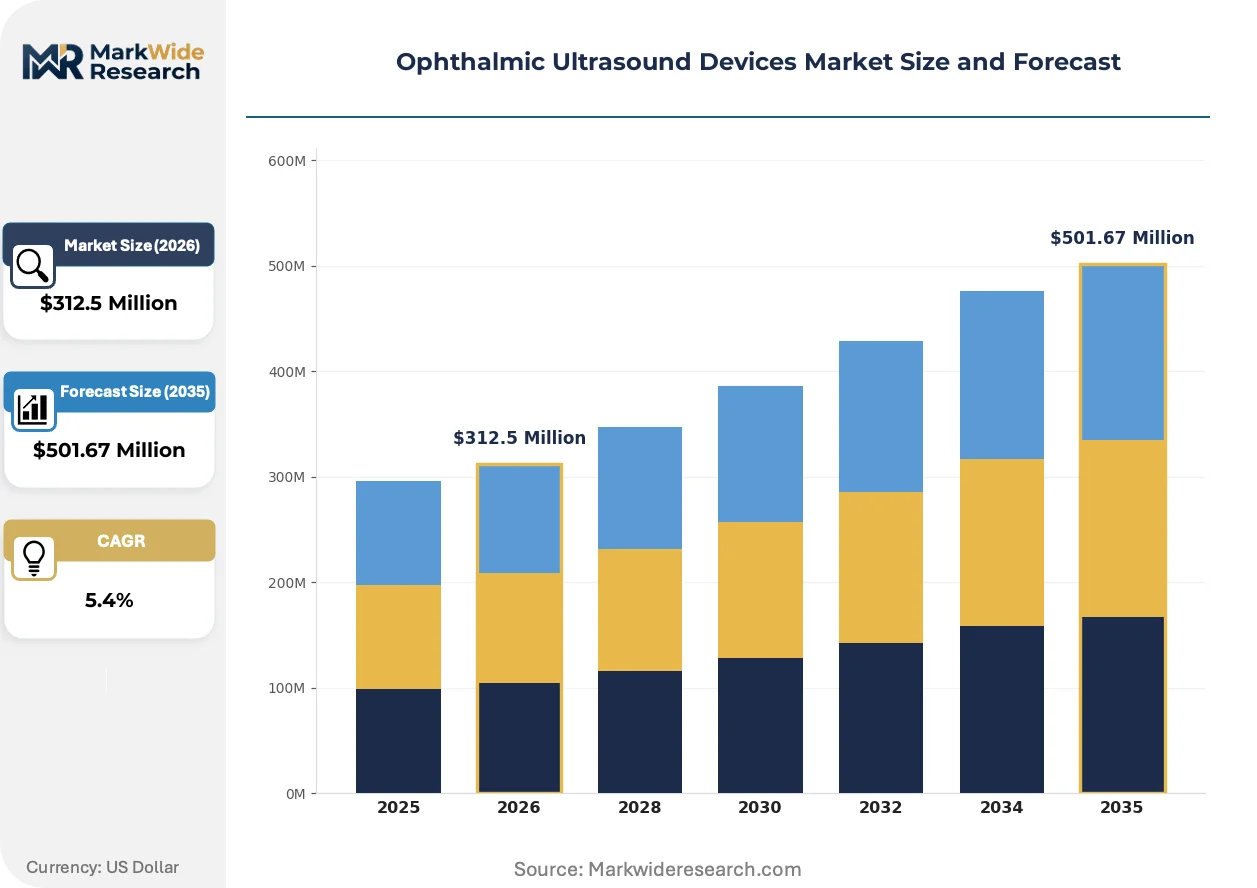
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: A-Scan, B-Scan, Doppler, UBM End User: Ophthalmology Clinics, Hospitals, Surgical Centers, Research Institutions Technology: Ultrasound Biomicroscopy, High-Frequency Ultrasound, Compact Ultrasound, Digital Imaging Application: Corneal Assessment, Vitreous Examination, Glaucoma Measurement, Retinal Imaging |
| Companies Covered | Carl Zeiss Meditec AG, NIDEK Co., Ltd., Sonomed Escalon, Lumibird Medical, DGH Technology, Inc., Topcon Corporation, Accutome Inc., Appasamy Associates Private Limited, Halma plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Ultrasound Devices Market Strategic Shifts & Innovations
Diagnostic platform convergence and regulatory pathway evolution are compressing product lifecycles while redistributing competitive advantage toward integrated solution providers.
High-frequency ultrasound technology is miniaturizing into handheld form factors for anterior segment assessment. Ambulatory surgical centers in the United States are adopting these compact systems at accelerated replacement cycles. The shift is compressing traditional capital equipment procurement timelines and enabling point-of-care diagnostic workflows outside hospital radiology departments.
The EU Medical Device Regulation is imposing strengthened clinical evidence requirements for CE marking of Class IIa and IIb ophthalmic imaging equipment. Manufacturers must now generate prospective clinical data rather than relying on predicate device equivalence. High-frequency ultrasound platforms with novel transducer designs face the most significant documentation burden, prompting some vendors to sequence European launches behind FDA clearances.
After-sales service unbundling is disrupting traditional equipment procurement contracts in United States eye care networks. Buyers are separating hardware acquisition from maintenance agreements and training subscriptions, forcing vendors to price components transparently. This pattern is most visible in multi-site ophthalmology practice management organizations negotiating enterprise-wide ultrasound platform standardization.
Ophthalmic Ultrasound Devices Market Segmentation
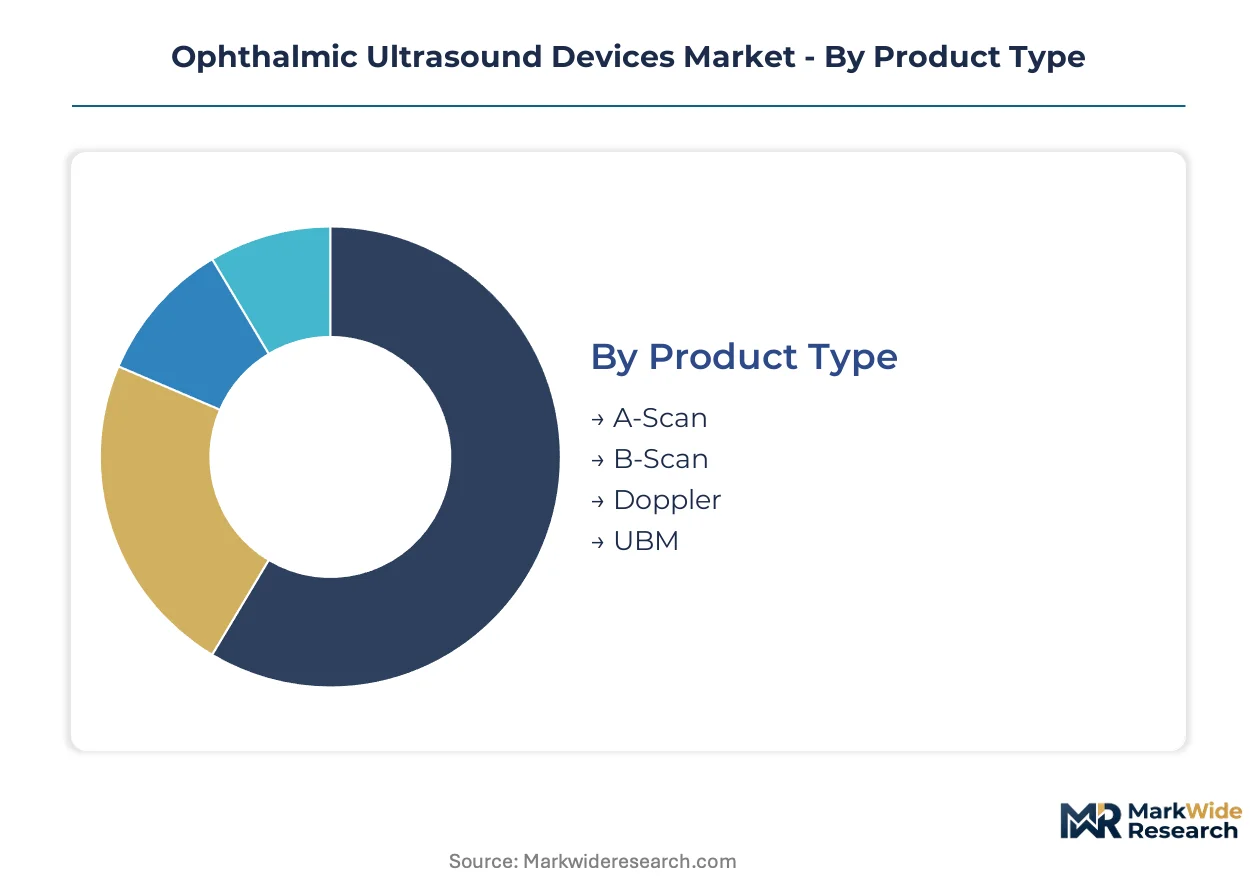
Segmentation in ophthalmic ultrasound devices reveals distinct procurement patterns across clinical settings and technology tiers. Product configuration, end-user workflow requirements, and application specificity drive vendor positioning and pricing architecture differently in each slice.
Product Type:
Domestic demand in the United States concentrates in A-Scan and B-Scan systems for routine cataract workflows, while export markets in Europe and Asia-Pacific absorb specialized configurations for subspecialty practices.
- A-Scan:Delivers one-dimensional axial length measurement through single-beam echo detection for intraocular lens power calculation. United States ambulatory surgical centers are replacing legacy units with digital interfaces that integrate directly into surgical planning software, compressing replacement cycles.
- B-Scan:Generates two-dimensional cross-sectional images of posterior segment structures when optical media opacity blocks direct visualization. Hospital-based ophthalmology departments in Germany and Japan are standardizing on portable B-Scan units for bedside diagnostics, bypassing fixed radiology suite dependencies.
- Doppler:Measures blood flow velocity in ophthalmic arteries using frequency shift analysis.
- UBM:Provides high-resolution imaging of anterior segment angle structures using 35-50 MHz frequencies.
B-Scan holds the largest share; momentum sits with UBM as anterior segment subspecialties expand diagnostic protocols.
End User:
Cost tier stratification separates premium integrated systems for hospital networks from economy configurations serving independent practice budgets.
- Ophthalmology Clinics:Independent and group practices prioritize compact, multi-modal platforms that consolidate A-Scan, B-Scan, and pachymetry into single footprints. Capital constraints in United States community eye care networks are extending equipment financing terms and elevating total-cost-of-ownership evaluations over acquisition price.
- Hospitals:Academic medical centers and community hospital systems demand PACS-integrated digital imaging platforms with centralized quality assurance and remote diagnostic capabilities. FDA 510(k) clearance timelines directly influence procurement committee scheduling for these capital-intensive deployments.
- Surgical Centers:Outpatient facilities require portable, high-frequency systems for immediate preoperative verification.
- Research Institutions:University laboratories and contract research organizations drive prototype validation and clinical evidence generation.
Hospitals hold the largest share; surgical centers are expanding most quickly as outpatient migration accelerates.
Technology:
Application specificity determines which frequency ranges and form factors penetrate each diagnostic workflow.
- Ultrasound Biomicroscopy:Employs 35-50 MHz transducers to resolve ciliary body and iridocorneal angle anatomy at 50-micron resolution. EU MDR clinical evidence requirements are extending CE marking timelines for novel UBM transducer designs, prompting some manufacturers to sequence European launches behind FDA clearances.
- High-Frequency Ultrasound:Platforms operating above 35 MHz deliver superior corneal layer discrimination but sacrifice penetration depth for posterior segment assessment. Corneal subspecialists in the United States are adopting handheld 50 MHz units for intraoperative pachymetry and post-graft evaluation.
- Compact Ultrasound:Miniaturized systems reduce footprint and capital outlay for space-constrained settings.
- Digital Imaging:Software-defined acquisition and cloud-archived storage replace analog film workflows.
Digital imaging holds the largest share; high-frequency ultrasound is gaining share fastest as corneal applications multiply.
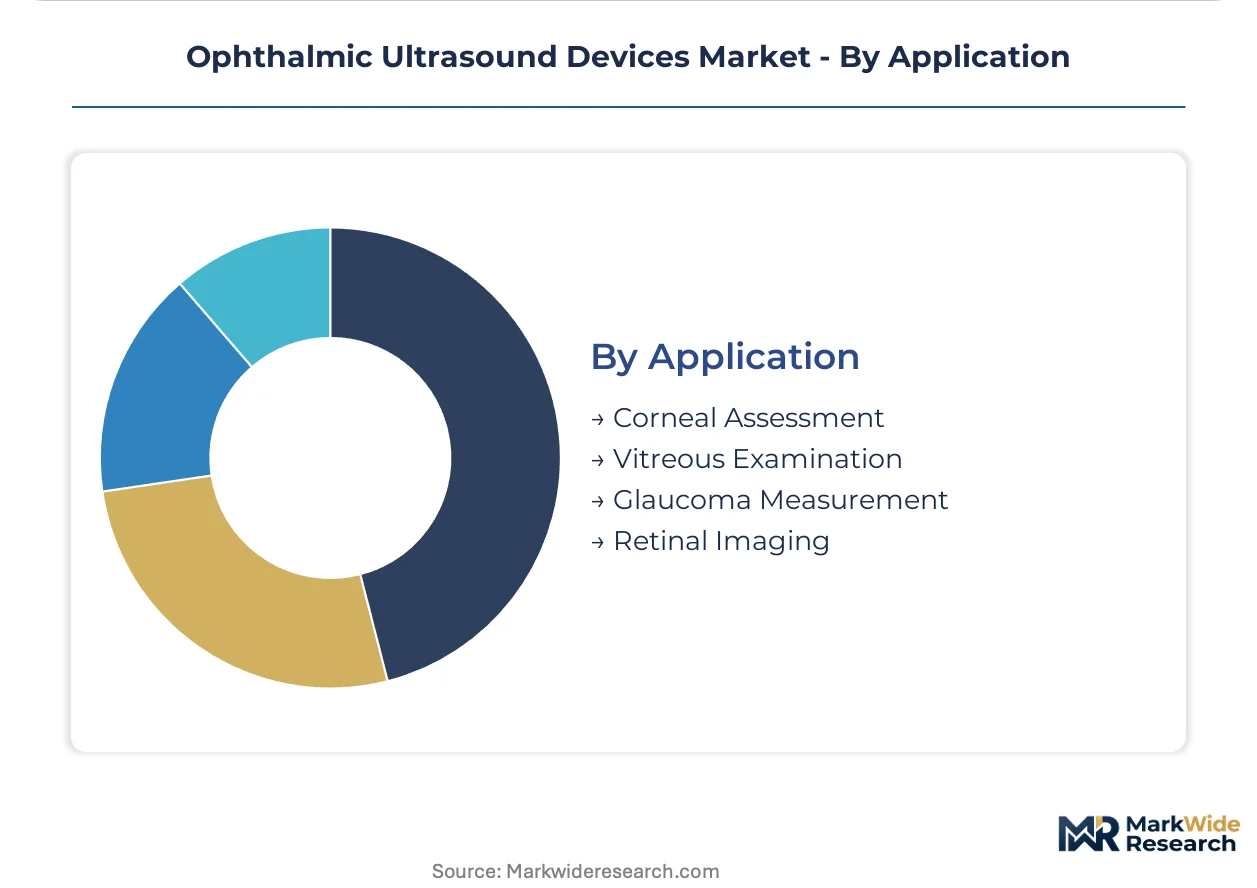
Application:
Volume concentration in cataract-related biometric measurement contrasts with margin concentration in complex posterior segment diagnostics.
- Corneal Assessment:Pachymetry, endothelial cell analysis, and graft evaluation drive 50 MHz platform adoption. Refractive surgery centers in the United States are integrating corneal ultrasound with optical coherence tomography for complementary structural validation, creating dual-modality procurement patterns.
- Glaucoma Measurement:Anterior segment angle evaluation and axial length monitoring for progression tracking sustain A-Scan and UBM demand. Hospital glaucoma services in Germany are upgrading to combined ultrasound-biometry platforms that unify diagnostic and surgical planning workflows.
- Vitreous Examination:B-Scan visualization through dense vitreous hemorrhage or cataract.
- Retinal Imaging:Posterior segment assessment when optical coherence tomography is precluded by media opacity.
Glaucoma measurement holds the largest share; corneal assessment shows the steepest expansion trajectory as refractive surgery volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumption tilts toward ambulatory surgical centers and portable diagnostics, while Germany and Japan concentrate procurement in hospital-based ophthalmology departments with integrated PACS workflows.
United States
Ambulatory surgical centers in Texas and Florida are accelerating high-frequency ultrasound procurement for glaucoma and retinal procedures. FDA 510(k) streamlined review pathways are compressing clearance timelines for digital imaging platforms. The Greater Boston corridor hosts concentrated research validation activity for next-generation transducer designs.
Germany
Hospital glaucoma services in Bavaria and North Rhine-Westphalia are upgrading to combined ultrasound-biometry platforms. EU MDR clinical evidence requirements are extending CE marking timelines for Class IIb imaging equipment. The Stuttgart industrial cluster anchors precision transducer manufacturing for domestic equipment vendors.
Japan
Metropolitan Tokyo and Osaka hospital networks are standardizing on portable B-Scan units for bedside diagnostics. PMDA regulatory harmonization with FDA pathways is accelerating parallel submission strategies for high-frequency platforms. The Nagoya medical device corridor concentrates backward-integrated transducer production.
China
Provincial hospital systems in Shanghai and Guangdong are expanding A-Scan procurement for cataract surgery volume growth. NMPA Class II medical device registration requirements are reshaping import substitution priorities for domestic manufacturers. The Shenzhen electronics cluster is incubating compact ultrasound module assembly for cost-sensitive segments.
India
Private ophthalmology chains in Maharashtra and Karnataka are financing multi-modal platform acquisitions through extended equipment leases. CDSCO medical device registration timelines are influencing vendor selection toward established import brands with prior FDA clearances. The Chennai medical device manufacturing zone is emerging as a regional hub for refurbished system refurbishment.
Ophthalmic Ultrasound Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in ophthalmic ultrasound devices. The premium tier captures hospital network standardization contracts through bundled training ecosystems and PACS integration capabilities. Mid-scale specialists compete on portable form factors and mobile diagnostics accessibility. The dominant competitive moves center on backward integration into transducer manufacturing and geographic sequencing of regulatory submissions between FDA and EU MDR pathways.
Within the integrated diagnostics tier, Carl Zeiss Meditec AG and NIDEK Co., Ltd. represent contrasting supply chain architectures. Carl Zeiss Meditec AG occupies a position anchored by cross-selling leverage across installed diagnostic platforms. NIDEK Co., Ltd. exemplifies captive transducer manufacturing control. Sonomed Escalon sits within the portable specialist segment where capital budget constraints create white space for mobile B-Scan deployment.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| NIDEK Co., Ltd. |
| Sonomed Escalon |
| Lumibird Medical |
| DGH Technology, Inc. |
| Topcon Corporation |
| Accutome Inc. |
| Appasamy Associates Private Limited |
| Halma plc |
| Others |
Cost & Logistics Intelligence
Transducer manufacturing scale economies in Japan and Germany concentrate component supply among three dominant producers, compressing price floors for finished systems while elevating qualification barriers for second-tier vendors seeking FDA 510(k) clearance.
Pricing Analysis
Long-term service contracts dominate procurement in United States hospital networks, separating hardware acquisition from maintenance subscriptions and training ecosystems. Price differentiation separates FDA-cleared premium platforms from CE-marked standard systems and economy configurations lacking integrated PACS compatibility. Cost compression in the portable segment intensifies as Shenzhen-based module assemblers enter the supply base. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize total-cost-of-ownership over acquisition price.
Supply Chain Analysis
Just-in-time transducer inventory strategies predominate among German and Japanese equipment manufacturers, with strategic stockpiles of piezoelectric ceramics concentrated in Nagoya and Stuttgart industrial corridors. High-frequency crystal arrays and precision-machined acoustic lenses draw from specialized suppliers in Switzerland and South Korea. Single-source vulnerability concentrates in 50 MHz transducer substrates where PMDA and FDA dual-qualification requirements limit alternative sourcing. Distribution runs through authorized dealer networks for capital equipment, with direct OEM relationships for consumable probes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as point-of-care diagnostic workflows splinter procurement authority from centralized hospital radiology departments toward ophthalmology subspecialists with distinct equipment preferences.
For Market Incumbents: Secure captive transducer supply through backward integration or exclusive offtake agreements with Japanese crystal manufacturers. Lock in hospital network standardization contracts by bundling certified ultrasonographer training ecosystems that emerging competitors cannot replicate without third-party certification delays. For New Entrants and Emerging Players: FDA 510(k) streamlined review pathways offer accelerated clearance timelines for digital imaging platforms targeting ambulatory surgical center procurement committees. White space concentrates in portable B-Scan systems for community eye care networks where capital budget constraints prevent fixed-device purchases. Go-to-market through extended equipment financing partnerships with regional ophthalmology practice management organizations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with captive high-frequency transducer manufacturing and established FDA predicate device libraries. Long-term viability hinges on regulatory pathway diversification between FDA and EU MDR submission sequencing. Acquisition targets should demonstrate installed base cross-selling leverage or backward-integrated component control. Signal to watch is EU MDR clinical evidence burden prompting European launch delays behind FDA clearances.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Manufacturing | Captive supply of 35-50 MHz crystals insulates against Japanese component qualification bottlenecks. |
| FDA 510(k) Streamlined Submission | Accelerated clearance timelines compress commercialization cycles for digital imaging platforms. |
| Training Ecosystem Bundling | Certified ultrasonographer programs differentiate against competitors reliant on third-party pathways. |
| Hospital System Partnership | PACS-integrated platforms capture academic medical center standardization contracts. |
| Portable Form Factor Development | Compact B-Scan systems penetrate capital-constrained community eye care networks. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with ophthalmic equipment procurement managers, biomedical engineers, and GPO contracts specialists; and secondary validation against FDA 510(k) clearance databases, EU MDR submission records, and hospital capital expenditure disclosures. Bottom-up triangulation cross-referenced unit shipment estimates from component suppliers with top-down revenue segmentation across product type, end user, and technology tiers.
Across the modeling period, analytical frameworks projected value and volume trajectories by disaggregating biometric measurement demand, anterior segment subspecialty expansion, and portable diagnostic adoption patterns. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and ambulatory surgical center facility growth. Industry-specific inputs incorporated transducer supply concentration indices and regulatory pathway divergence between FDA streamlined review and EMA MDR transition timelines.
Underlying assumptions cover stable FDA 510(k) review velocity and sustained EU MDR clinical evidence requirements, with deviation risk concentrated in transducer supply disruptions or harmonization shifts between PMDA and FDA pathways. Revision becomes warranted when certification timeline divergence crosses thresholds that reshape geographic launch sequencing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
IV Poles Market
Medical Devices
Support Surfaces Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Autorefractor Keratometer Market