
 US Interventional Radiology Market | 2026-2036
US Interventional Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
US Interventional Radiology Market Insights
Software-defined imaging protocols and AI-assisted procedural planning is broadening what interventional radiology suites deliver as a service rather than capital equipment alone. Siemens Healthineers leverages its dual-source CT platform to anchor high-end academic medical center contracts. GE HealthCare sustains installed base loyalty through predictive maintenance subscriptions. Philips navigates outpatient migration with compact interventional systems designed for imaging centers.
Interventional radiology encompasses image-guided minimally invasive procedures using percutaneous needle access, catheter-based delivery, and real-time imaging navigation to diagnose and treat disease without open surgery. Catheters and guidewires constitute the procedural consumables backbone where pricing power concentrates due to sterile single-use requirements and regulatory filing burdens. Hospitals remain the dominant end-user channel by procedure volume, though imaging centers are capturing share in venous access and biopsy services where anesthesia requirements are minimal.
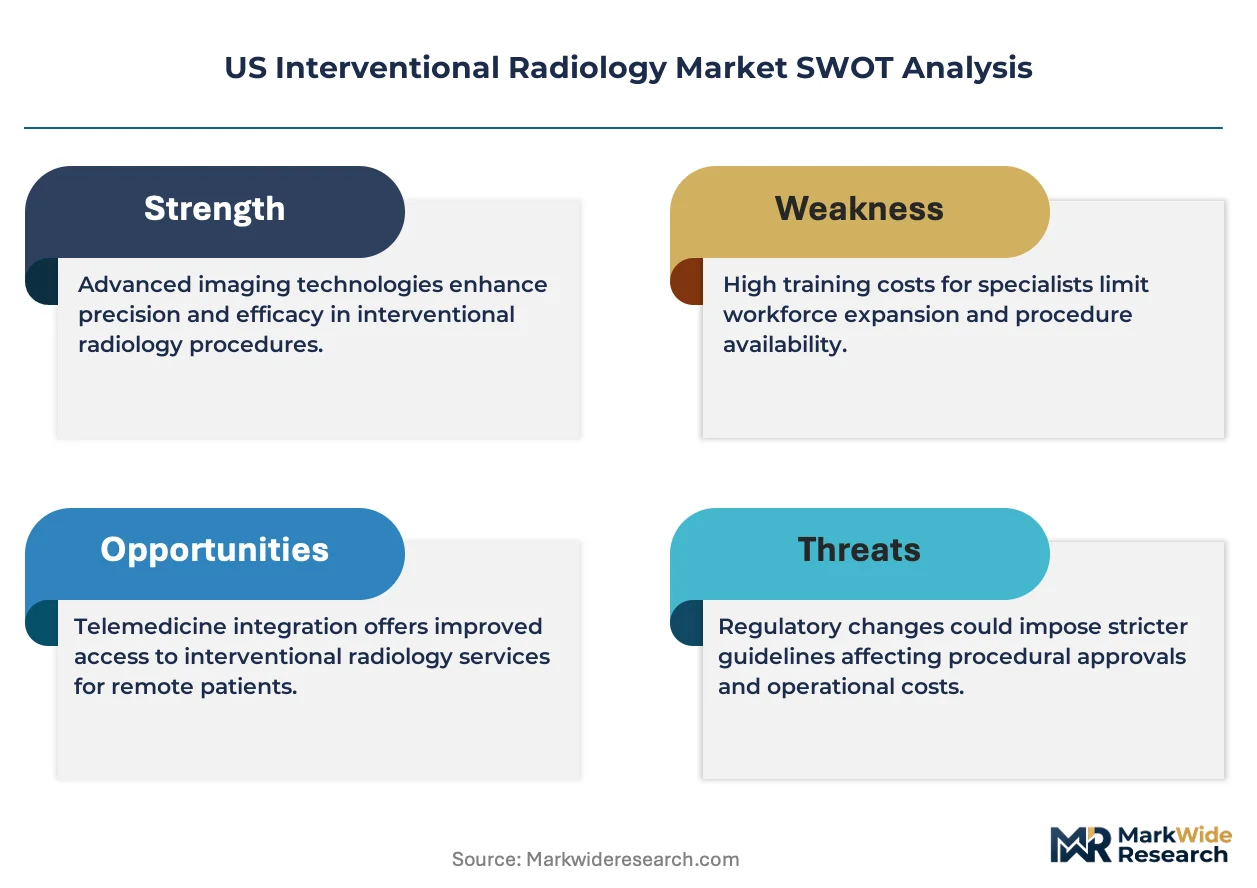
FDA 510(k) clearance pathways and CMS national coverage determinations shape product commercialization timelines and reimbursement access for novel interventional devices. State-level certificate-of-need regulations in New York, Illinois, and Pennsylvania constrain imaging center expansion and protect hospital service line economics. Stakeholders must monitor whether site-neutral payment policies expand beyond current ambulatory surgical center carve-outs.
Market Dynamics
Site-of-care migration from inpatient to outpatient settings is restructuring capital deployment and service line economics across hospital systems and imaging centers.
Growth Catalysts
- CMS site-neutral payment expansion:Reimbursement parity between hospital outpatient departments and ambulatory surgical centers accelerates procedure volume migration to lower-cost settings.
- Minimally invasive oncology protocols:Tumor ablation for liver, lung, and renal malignancies displaces surgical resection in appropriate candidates, expanding addressable procedure volumes.
- Texas-Florida-California health system consolidation:Large integrated delivery networks are centralizing interventional radiology service lines and investing in dedicated procedural suites.
Market Restraints
- Certificate-of-need statutes:New York, Illinois, and Pennsylvania maintain CON regulations that constrain imaging center expansion and protect incumbent hospital market positions.
- Single-use consumable cost structure:Catheters, guidewires, and ablation probes carry sterile manufacturing burdens and regulatory filing costs that limit pricing flexibility.
- Interventionalist workforce pipeline:Fellowship training slots and procedural credentialing requirements create bottlenecks in specialist availability relative to service demand.
Strategic Opportunities
- Venous access and biopsy migration:Imaging centers in Florida and Texas are capturing low-acuity procedures that require minimal anesthesia support.
- AI-assisted procedural planning:Machine learning algorithms for lesion segmentation and needle trajectory optimization are creating software-as-service revenue streams.
- Compact system form factors:Equipment manufacturers are designing reduced-footprint angiography and CT-fluoroscopy systems purpose-built for outpatient facility constraints.
Industry Challenges
- Cross-modality credentialing complexity:Radiologists must maintain privileges across ultrasound, CT, and MRI guidance platforms, fragmenting training resources.
- Capital equipment refresh cycles:Hospital capital committees prioritize AI-enabled imaging platforms, extending replacement timelines for standalone interventional suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Interventional Radiology Market |
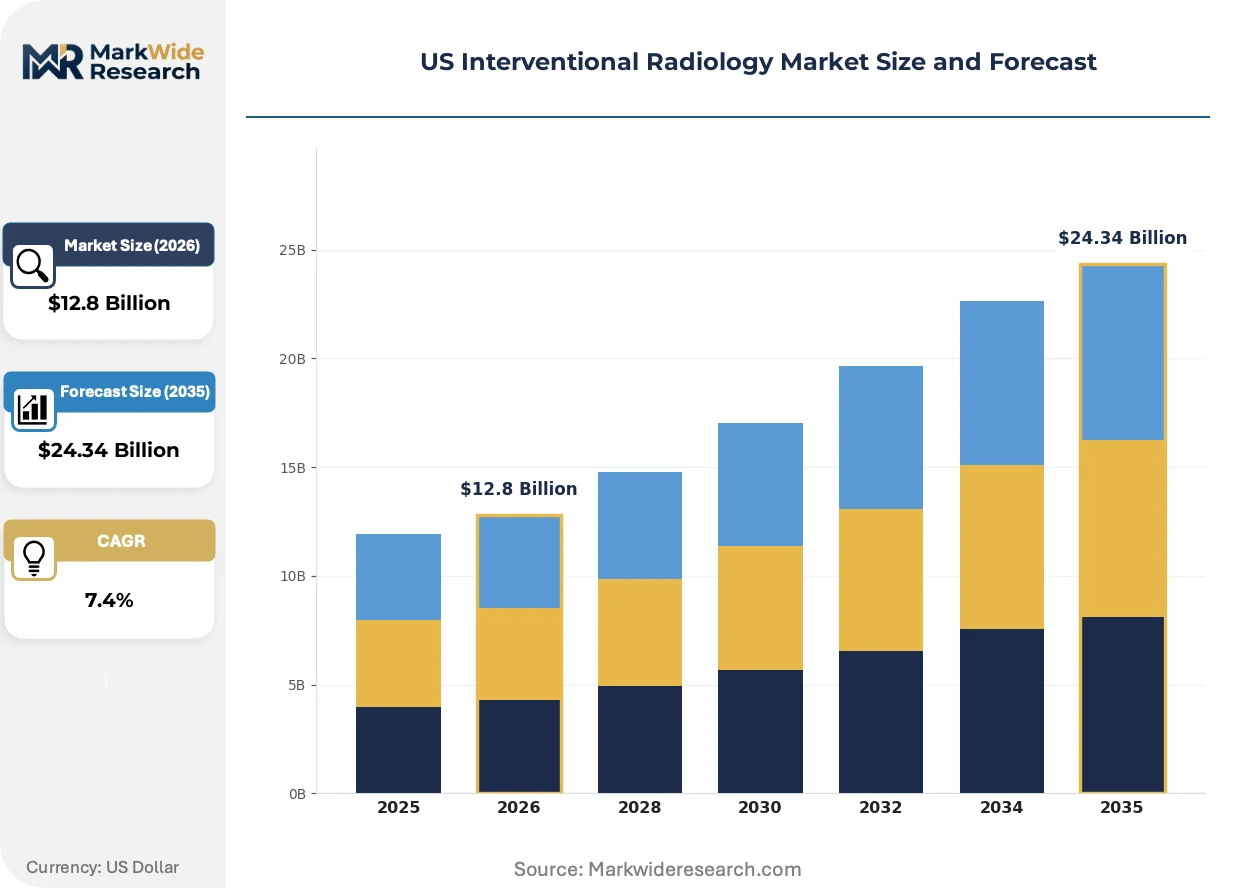
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.34 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Needles, Catheters, Guidewires, Contrast Media Technology: Ultrasound, Fluoroscopy, CT, MRI End User: Hospitals, Imaging Centers, Specialty Clinics, Research Institutions Application: Oncology, Cardiovascular, Gastroenterology, Urology |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Stryker Corporation, Becton, Dickinson and Company, Cook Group Incorporated, Teleflex Incorporated, Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Interventional Radiology Market Trends and Innovations
Software-defined imaging and procedural automation are compressing the boundary between diagnostic radiology and therapeutic intervention, altering how suites are configured and staffed.
Robotic needle guidance systems are modularizing procedural workflows by decoupling physician hand-eye coordination from direct patient contact. Academic medical centers in California are piloting these platforms for percutaneous ablation and biopsy procedures. The technology is modularizing suite design requirements, enabling smaller footprint installations without sacrificing procedural complexity.
FDA 510(k) clearance pathways for novel ablation modalities are tightening evidentiary standards for equivalence claims. Device sponsors now face expanded clinical data requirements for energy-based tumor destruction platforms. The interventional oncology segment is responding with prospective registry builds and real-world evidence programs to support subsequent indications.
Hospital procurement committees are unbundling service contracts from equipment purchases, separating preventive maintenance from software upgrade entitlements. Imaging center operators in Texas are driving this disintermediation, negotiating multi-vendor maintenance agreements that reduce vendor lock-in. The shift is most visible in independent diagnostic facilities where capital constraints favor operational expenditure models over upfront acquisition.
US Interventional Radiology Market Segmentation
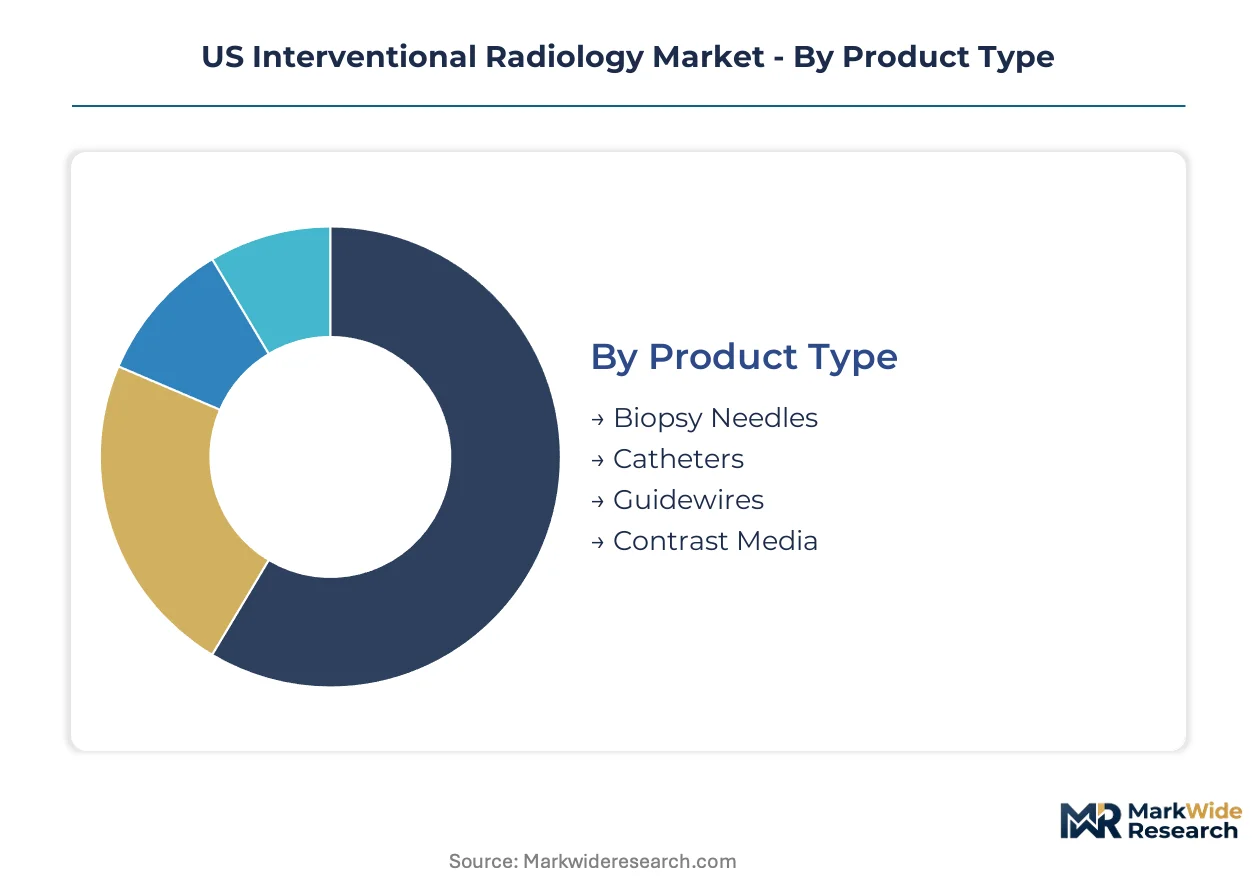
Interventional radiology procurement decisions fragment across equipment, consumables, and software layers, each with distinct margin profiles and vendor lock-in dynamics. Understanding where purchasing power concentrates within each category reveals how health systems and imaging centers allocate capital across the procedure spectrum.
Product Type:
Supply concentration clusters in sterile single-use consumables where manufacturing scale and regulatory filing history create defensive moats.
- Catheters:Multi-lumen and steerable designs dominate complex vascular interventions. Texas health systems drive demand for hydrophilic-coated variants in high-volume oncology service lines, though single-use cost structures constrain pricing flexibility.
- Guidewires:Nitinol core constructions with proprietary tip configurations enable lesion crossing in tortuous anatomy. Florida imaging centers favor exchange-length designs for outpatient biopsy workflows where procedural efficiency determines throughput economics.
- Biopsy Needles:Coaxial and vacuum-assisted systems serve core tissue acquisition across ultrasound and CT guidance platforms.
- Contrast Media:Iodinated formulations for vascular opacification and gadolinium chelates for MR-guided procedures carry supply chain concentration risks.
Today's leader: Catheters. Tomorrow's challenger: Guidewires.
Technology:
Capital deployment patterns reveal a cost-tier split between premium multi-modality suites and compact single-purpose systems.
- Fluoroscopy:C-arm configurations with digital subtraction angiography remain the workhorse for vascular interventions. California academic medical centers anchor demand for biplane systems with 3D rotational capabilities where complex embolization procedures justify capital intensity.
- CT:Dual-source platforms with rapid kV switching enable spectral imaging for perfusion assessment during tumor ablation. Texas hospital systems prioritize CT-fluoroscopy fusion for lung biopsy navigation where electromagnetic tracking reduces radiation exposure.
- Ultrasound:Point-of-care systems with needle visualization software capture venous access and superficial biopsy volume migrating to imaging centers.
- MRI:Interventional suites with wide-bore magnets and real-time sequences serve thermometry-guided ablation in prostate and uterine fibroid applications.
Fluoroscopy retains installed base dominance. CT gains share fastest in academic settings.
End User:
Site-of-care migration is redistributing procedure volume across facility types with divergent anesthesia capabilities and reimbursement profiles.
- Hospitals:Inpatient and hospital outpatient departments retain high-acuity interventions requiring anesthesia support and overnight observation. California integrated delivery networks centralize interventional radiology service lines in dedicated procedural towers where case mix spans oncology, trauma, and transplant applications.
- Imaging Centers:Independent diagnostic facilities in Florida and Texas capture venous access, superficial biopsy, and basic drainage procedures where minimal sedation suffices and CMS site-neutral payment creates margin advantage.
- Specialty Clinics:Urology and gastroenterology groups embed interventional capabilities for prostate biopsy and biliary drainage.
- Research Institutions:Academic medical centers pilot robotic guidance and ablation technologies under FDA investigational device exemptions.
Hospitals command procedure value. Imaging centers capture volume expansion.
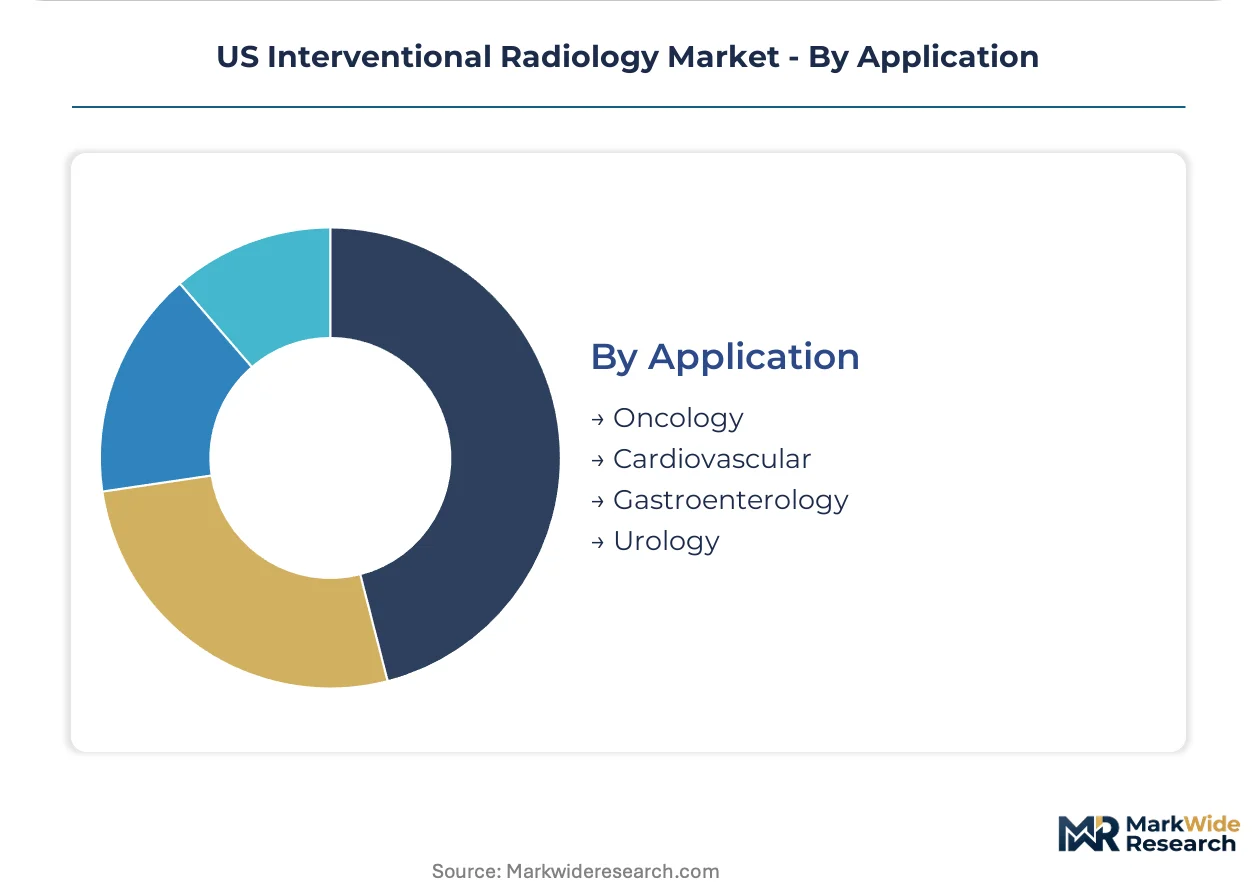
Application:
Clinical demand concentrates in oncology where tumor ablation displaces surgical resection in appropriate candidates.
- Oncology:Percutaneous ablation for liver, lung, and renal malignancies using radiofrequency, microwave, and cryoablation energy platforms. Texas and Florida health systems invest in dedicated interventional oncology suites where multidisciplinary tumor boards drive appropriate patient selection.
- Cardiovascular:Peripheral arterial disease interventions and venous thromboembolism management span catheter-directed thrombolysis and mechanical thrombectomy.
- Gastroenterology:Transhepatic biliary drainage and portal vein interventions serve decompensated liver disease.
- Urology:Nephrostomy tube placement and ureteral stenting address obstructive uropathy.
Oncology leads revenue contribution. Cardiovascular offers procedural volume depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas health systems deploy capital faster than California peers, though both states concentrate interventional radiology service line investment. Florida imaging centers capture outpatient migration most aggressively. The Northeast maintains regulatory barriers that shelter hospital economics.
Texas
MD Anderson Cancer Center and Houston Methodist anchor dedicated interventional oncology suites where tumor ablation volumes justify multi-modality capital deployment. State certificate-of-need repeal in 1985 enabled freestanding imaging center proliferation. Dallas-Fort Worth health systems consolidate venous access and biopsy services into ambulatory hubs.
California
Stanford Health Care and UCLA Health pilot robotic needle guidance systems under FDA investigational device exemptions. The state's Office of Statewide Health Planning and Development maintains facility licensing requirements that constrain rapid outpatient expansion. Los Angeles and San Francisco academic medical centers concentrate CT-fluoroscopy fusion investments for lung biopsy navigation.
Florida
Moffitt Cancer Center and Baptist Health South Florida drive demand for compact angiography systems in dedicated outpatient procedural towers. Absence of certificate-of-need regulation permits imaging center chains to scale venous access and superficial biopsy capacity. Tampa and Orlando metropolitan areas host the densest concentration of independent diagnostic facilities capturing CMS site-neutral payment margins.
New York
Memorial Sloan Kettering and NewYork-Presbyterian retain high-acuity interventional oncology within hospital outpatient departments. State certificate-of-need statutes require approval for MRI and CT installations, protecting incumbent hospital market positions. New York City health systems centralize complex embolization and transplant interventions in Manhattan-based procedural towers.
Illinois
Northwestern Medicine and University of Chicago Medicine anchor academic interventional radiology training programs that feed specialist workforce pipelines. State Health Facilities and Services Review Board maintains CON jurisdiction over imaging equipment acquisitions. Chicago metropolitan health systems balance hospital-based complex procedures with suburban imaging center partnerships for low-acuity volume.
US Interventional Radiology Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with sterile consumable producers commanding pricing power through regulatory filing history and hospital GPO contracts. Equipment vendors tier into premium multi-modality suite providers and compact single-purpose system designers. Strategic archetypes span integrated imaging conglomerates, focused interventional device specialists, and regional consumable fabricators. Consolidation concentrates in catheter and guidewire manufacturing, while software-defined imaging protocols enable new service-based revenue streams.
Within the integrated imaging tier, Siemens Healthineers, GE HealthCare, and Koninklijke Philips N.V. occupy positions spanning dual-source CT platforms, predictive maintenance subscriptions, and compact outpatient systems respectively. Among interventional device specialists, Medtronic plc and Boston Scientific Corporation exemplify the sterile single-use consumable archetype where regulatory burdens and manufacturing scale create defensive positioning. Stryker Corporation and Becton, Dickinson and Company sit within diversified medical technology portfolios where interventional radiology represents one of several growth vectors. Cook Group Incorporated and Teleflex Incorporated represent privately held and publicly traded models of focused vascular access and interventional device production.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Becton, Dickinson and Company |
| Cook Group Incorporated |
| Teleflex Incorporated |
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Others |
Pricing and Supply Chain Analysis
Interventionalist workforce concentration in Texas, Florida, and California feeds directly into pricing-tier spreads across catheter and guidewire categories, with labor-cost differentials between academic medical centers and imaging centers creating a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Capacity additions in compact outpatient systems are reshaping price floors for fluoroscopy and CT platforms, pressuring legacy equipment margins. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA clearance tier and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from imaging center procurement committees unbundling maintenance contracts from equipment purchases. Hospital systems show least price sensitivity due to GPO contract lock-in, while independent diagnostic facilities in Florida drive hardest bargain.
Supply Chain Analysis
FDA 510(k) clearance and ISO 13485 certification gating constrains supplier entry, concentrating sterile consumable manufacturing in the United States, Ireland, and Costa Rica. Nitinol wire for guidewire cores, medical-grade polymers for catheter shafts, and iodinated contrast precursors constitute critical input dependencies. Single-source vulnerability runs through specialty polymer suppliers serving hydrophilic coating applications. Distribution runs through hospital GPOs, imaging center purchasing cooperatives, and direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Interventional Radiology Market functions as a stable compounder, with CMS site-neutral payment expansion providing durable volume migration tailwinds that sustain procedure growth across economic cycles.
For Market Incumbents: Hedge against outpatient commoditization by deepening software-as-service revenue streams and securing exclusive GPO contracts for next-generation ablation platforms. Imaging center chains in Florida represent the primary margin compression threat. Vertical integration into predictive maintenance subscriptions anchors hospital loyalty. For New Entrants and Emerging Players: CMS site-neutral payment expansion in the United States opens a window for compact system manufacturers targeting independent diagnostic facilities. Venous access and superficial biopsy services in Texas imaging centers offer the most penetrable white space. A rental-plus-per-procedure pricing model bypasses capital committee friction. For Investors and Strategic Acquirers: Health system strategic venture arms are the most active acquirer in this space, pursuing AI-assisted procedural planning capabilities. The five-to-ten-year viability window favors consumable specialists with regulatory filing history over capital equipment pure-plays. Watch FDA evidentiary standard tightening for ablation modalities as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Machine learning algorithms for lesion segmentation create recurring revenue streams beyond hardware sales. |
| Reimbursement Strategy | CMS national coverage determination alignment accelerates commercialization timelines for novel ablation platforms. |
| Hospital System Partnership | Exclusive supply agreements with Texas integrated delivery networks lock out competing catheter vendors. |
| FDA Submission | Expanded clinical data requirements for equivalence claims now demand prospective registry builds. |
| CE Marking Pathway | European regulatory clearance enables parallel market development while US submissions mature. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and state certificate-of-need regulatory filings. Bottom-up procedure volume estimates and top-down equipment shipment data were triangulated to anchor market sizing.
Segment-weighting approaches applied across product type, technology platform, end-user facility category, and clinical application dimensions over the projection horizon. CAGRs were derived from procedure volume trajectories modulated by reimbursement policy shifts and capital expenditure cycle timing. Forecast inputs incorporated CMS site-neutral payment expansion scenarios and interventionalist fellowship training slot constraints.
Revisions become necessary when FDA evidentiary standards for ablation modalities tighten beyond current equivalence pathways or when certificate-of-need regulations in New York, Illinois, or Pennsylvania undergo material relaxation. A model refresh is warranted upon material change in CMS outpatient reimbursement parity implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Ultrasound Imaging Solution Market