
 Asia Pacific Nuclear Imaging Market | 2026-2036
Asia Pacific Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Nuclear Imaging Market Outlook
Hybrid imaging technology is reconfiguring diagnostic workflows across the Asia Pacific by merging functional metabolic data with high-resolution anatomical mapping. Siemens Healthineers leverages its dual-source PET-CT platforms to dominate premium hospital installations in Japan and South Korea. GE Healthcare anchors its position through extensive service networks that sustain equipment uptime across India's diagnostic center chains. Canon Medical Systems Corporation differentiates via detector material innovations that improve sensitivity in cardiac stress testing protocols.
Asia Pacific nuclear imaging encompasses the detection and visualization of radiopharmaceutical distribution using gamma-emitting isotopes, with systems typically achieving spatial resolution below 5 mm and energy discrimination across 50-600 keV spectrums. Positron Emission Tomography captures the largest margin pool due to cyclotron-dependent isotope logistics that limit competitive entry, while Single Photon Emission Computed Tomography sustains broader unit volumes through lower capital thresholds and Tc-99m supply chain accessibility. Hybrid Imaging represents the fastest-expanding technology segment as health systems prioritize fused modality suites that reduce patient visit frequency and improve lesion localization confidence.
Japan's PMDA and Australia's TGA enforce divergent device approval timelines that fragment product launch sequencing across the region, while India's CDSCO medical device rules and China's NMPA innovation pathways shape how manufacturers structure clinical trial investments. The EU AI Act's extraterritorial influence on software-integrated systems is pressing vendors to recalibrate algorithm validation protocols for Asia Pacific deployments. Stakeholders must weigh cyclotron infrastructure commitments against emerging isotope supply partnerships when evaluating market entry timing.
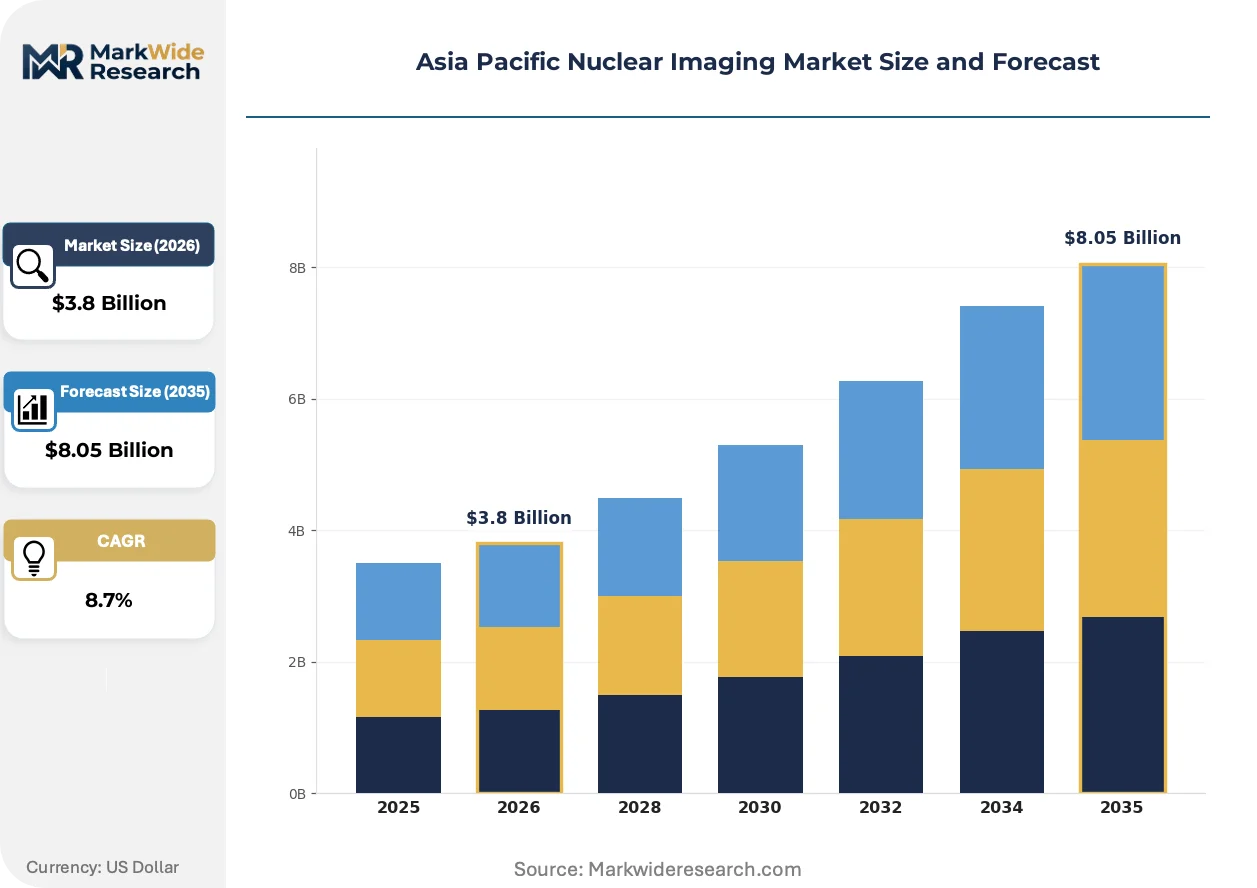
Market Dynamics
Hybrid imaging adoption across Asia Pacific is compressing diagnostic timelines by fusing metabolic and anatomical data into single-session protocols, forcing health systems to consolidate capital budgets toward integrated modality suites rather than standalone scanners.
Growth Catalysts
- India's PLI scheme:The production-linked incentive framework for medical devices is accelerating domestic manufacturing of gamma cameras and PET scanners, reducing import dependency for diagnostic center chains.
- Proton therapy expansion:China's tier-one cities are commissioning advanced treatment centers that require hybrid PET-CT and PET-MR systems for precise tumor delineation and treatment planning workflows.
- Tc-99m supply accessibility:Regional Mo-99 production infrastructure improvements are stabilizing isotope availability for SPECT procedures across Australia's hospital networks and Southeast Asian diagnostic chains.
Market Restraints
- Cyclotron capital intensity:The infrastructure requirements for on-site isotope production limit PET scanner deployment to tertiary medical centers with dedicated nuclear medicine budgets.
- Regulatory fragmentation:Divergent PMDA and TGA device approval timelines force manufacturers to sequence product launches across Japan and Australia, extending commercialization cycles.
- Short isotope half-lives:The logistical constraints of F-18 and Ga-68 distribution create geographic service radius limitations that disadvantage rural and secondary city facilities.
Strategic Opportunities
- AI-integrated reconstruction algorithms:The EU AI Act's extraterritorial influence is pressing vendors to validate machine learning protocols for Asia Pacific deployments, creating first-mover advantages for compliant systems.
- Vietnam's diagnostic center buildout:Private hospital chains in Ho Chi Minh City and Hanoi are establishing molecular imaging capabilities without legacy equipment constraints, favoring turnkey hybrid installations.
- Cardiac stress testing protocols:Detector material innovations are improving SPECT sensitivity for myocardial perfusion imaging, opening substitution opportunities against invasive catheterization referrals.
Industry Challenges
- Cyclotron technician scarcity:Qualified personnel for isotope production and quality control are concentrated in Japan and South Korea, constraining operational expansion in emerging markets.
- CDSCO clinical trial complexity:India's medical device rules require substantial local evidence generation for novel hybrid systems, extending registration timelines compared to reference market approvals.
- Legacy SPECT integration:Hospital chains with installed gamma camera bases face workflow disruption when migrating to fused modality protocols, complicating staff retraining and facility reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Nuclear Imaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Photon Emission Computed Tomography, Positron Emission Tomography, Scintigraphy, Gamma Cameras End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: Digital Imaging, Hybrid Imaging, 3D Imaging, Software Integration Application: Oncology, Cardiology, Neurology, Thyroid Studies |
| Companies Covered | Canon Medical Systems Corporation, Siemens Healthineers, Koninklijke Philips NV, GE Healthcare, Neusoft Medical Systems Co., Ltd., Fujifilm Holdings Corporation, Hitachi Medical Corporation, Shimadzu Corporation, Samsung Medison, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Nuclear Imaging Market Strategic Shifts
Digital detector technology and artificial intelligence are restructuring image acquisition and reconstruction workflows across Asia Pacific nuclear imaging, reducing scan durations while expanding the addressable patient population for molecular diagnostics.
Silicon photomultiplier (SiPM) detectors are replacing conventional photomultiplier tubes in next-generation PET systems, enabling improved timing resolution and lower energy thresholds. Japanese university hospitals and South Korean cancer centers are adopting SiPM-based digital PET-CT platforms for oncology staging protocols. This transition is hybridizing diagnostic capabilities by enabling simultaneous multi-tracer imaging that was previously impractical with analog detector architectures.
Japan's PMDA has streamlined software-as-a-medical-device pathways for AI-integrated reconstruction algorithms, reducing validation requirements for deep learning-based noise reduction tools. This regulatory accommodation is accelerating deployment of low-dose PET protocols that maintain diagnostic confidence. Cardiac and neurology applications are responding first, with pediatric oncology centers in Tokyo and Osaka piloting reduced radiopharmaceutical dose regimens.
Diagnostic center chains are unbundling equipment procurement from long-term service contracts, separating capital acquisition from maintenance and isotope supply agreements. India's standalone imaging facilities are driving this disaggregation, negotiating independent cyclotron access arrangements rather than bundled vendor packages. This restructuring is most visible in Mumbai and Delhi's competitive private diagnostic markets, where price transparency for component services is compressing total cost of ownership negotiations.
Asia Pacific Nuclear Imaging Market Segmentation
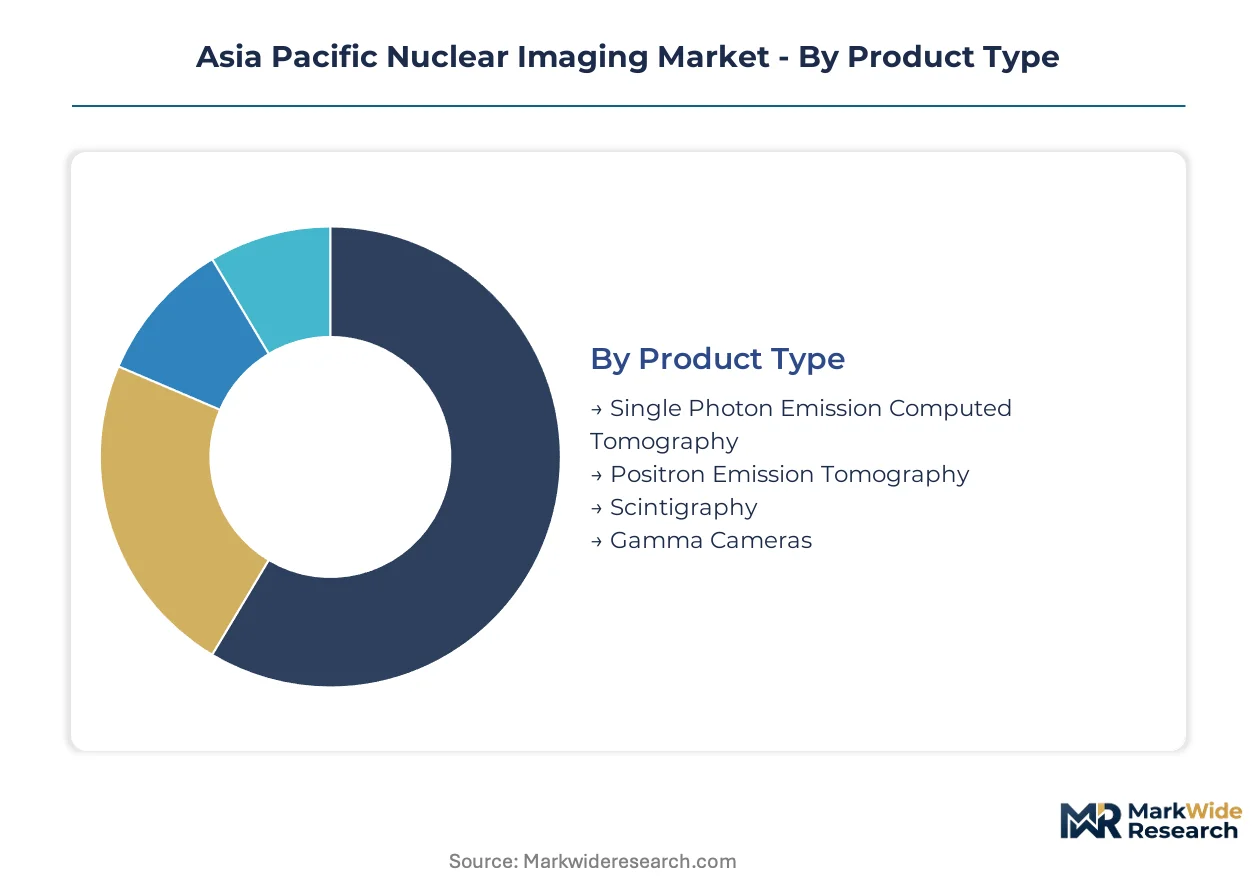
Segmentation reveals how capital allocation and clinical priorities diverge across the Asia Pacific nuclear imaging landscape. Technology maturity, reimbursement pathways, and infrastructure readiness create distinct demand pockets that manufacturers must navigate with differentiated positioning.
Product Type:
Mature modalities with established service networks coexist alongside emerging platforms that demand new technical capabilities and supply chain investments.
- Single Photon Emission Computed Tomography:Analog and digital SPECT systems detect gamma-emitting isotopes using sodium iodide or cadmium-zinc-telluride detectors, achieving spatial resolution of 8-12 mm. India's diagnostic center chains in Mumbai and Delhi deploy SPECT for cardiac stress testing and bone scans, capitalizing on stabilized Tc-99m supply chains and lower capital thresholds than PET alternatives.
- Positron Emission Tomography:Coincidence detection systems capture positron-electron annihilation events, requiring on-site or proximate cyclotron infrastructure for F-18 fluorodeoxyglucose production. China's tier-one cities—Beijing, Shanghai, Guangzhou—anchor PET-CT installations at proton therapy centers where precise tumor delineation drives hybrid imaging demand.
- Scintigraphy:Planar gamma camera imaging delivers functional snapshots for thyroid, renal, and gastrointestinal studies. Southeast Asian hospital networks in Bangkok and Jakarta favor scintigraphy for screening protocols where throughput speed outweighs tomographic precision.
- Gamma Cameras:Single-head and dual-head Anger camera configurations support general nuclear medicine departments with modular upgrade paths. Australia's regional hospitals maintain gamma camera fleets for bone scintigraphy and sentinel node mapping, constrained by TGA device approval timelines for replacement systems.
SPECT handles the majority of throughput across Asia Pacific installations; PET is the fastest mover on share as oncology centers expand molecular imaging capabilities.
End User:
Procurement authority and clinical workflow requirements fragment the customer base across capital-intensive hospital systems and agile standalone operators.
- Hospitals:Tertiary medical centers with dedicated nuclear medicine departments integrate hybrid imaging into multidisciplinary tumor boards and cardiac care pathways. Japan's university hospitals in Tokyo and Osaka deploy PET-MR systems for neurology research, supported by PMDA streamlined software validation pathways.
- Diagnostic Centers:Standalone imaging facilities unbundle equipment procurement from service contracts, negotiating independent isotope supply arrangements. India's private diagnostic chains in Bengaluru and Hyderabad drive this disaggregation, compressing total cost of ownership through component pricing transparency.
- Research Institutions:Academic medical centers and national laboratories pilot novel radiopharmaceuticals and reconstruction algorithms. South Korean cancer centers in Seoul participate in multi-tracer imaging trials using SiPM-based digital detector platforms.
- Imaging Clinics:Ambulatory facilities concentrate on high-volume, protocolized procedures such as myocardial perfusion imaging and bone densitometry. Vietnam's emerging private hospital chains in Ho Chi Minh City favor turnkey hybrid installations without legacy equipment constraints.
Hospitals command the largest capital budgets; diagnostic centers are expanding most quickly as India's PLI scheme reduces import dependency.
Technology:
Digital transformation and modality fusion are restructuring competitive differentiation around software capabilities and detector architectures.
- Digital Imaging:Solid-state detectors and direct conversion electronics replace analog signal chains, improving energy resolution and count rate performance. SiPM-based systems enable timing resolution below 300 picoseconds, supporting time-of-flight PET reconstruction.
- Hybrid Imaging:PET-CT and PET-MR platforms fuse metabolic and anatomical data into single-session protocols, reducing patient visit frequency. China's proton therapy centers require hybrid systems for treatment planning workflows.
- 3D Imaging:Iterative reconstruction algorithms and depth-of-interaction correction enhance tomographic accuracy for small-lesion detection. Cardiac applications in Japan's pediatric oncology centers pilot reduced-dose protocols using 3D-optimized acquisitions.
- Software Integration:AI-embedded reconstruction and automated lesion segmentation streamline technologist workflows. The EU AI Act's extraterritorial influence pressures vendors to validate machine learning protocols for PMDA and CDSCO submissions.
Digital imaging dominates installed base maintenance; hybrid imaging claims the steepest expansion trajectory as health systems consolidate capital budgets.
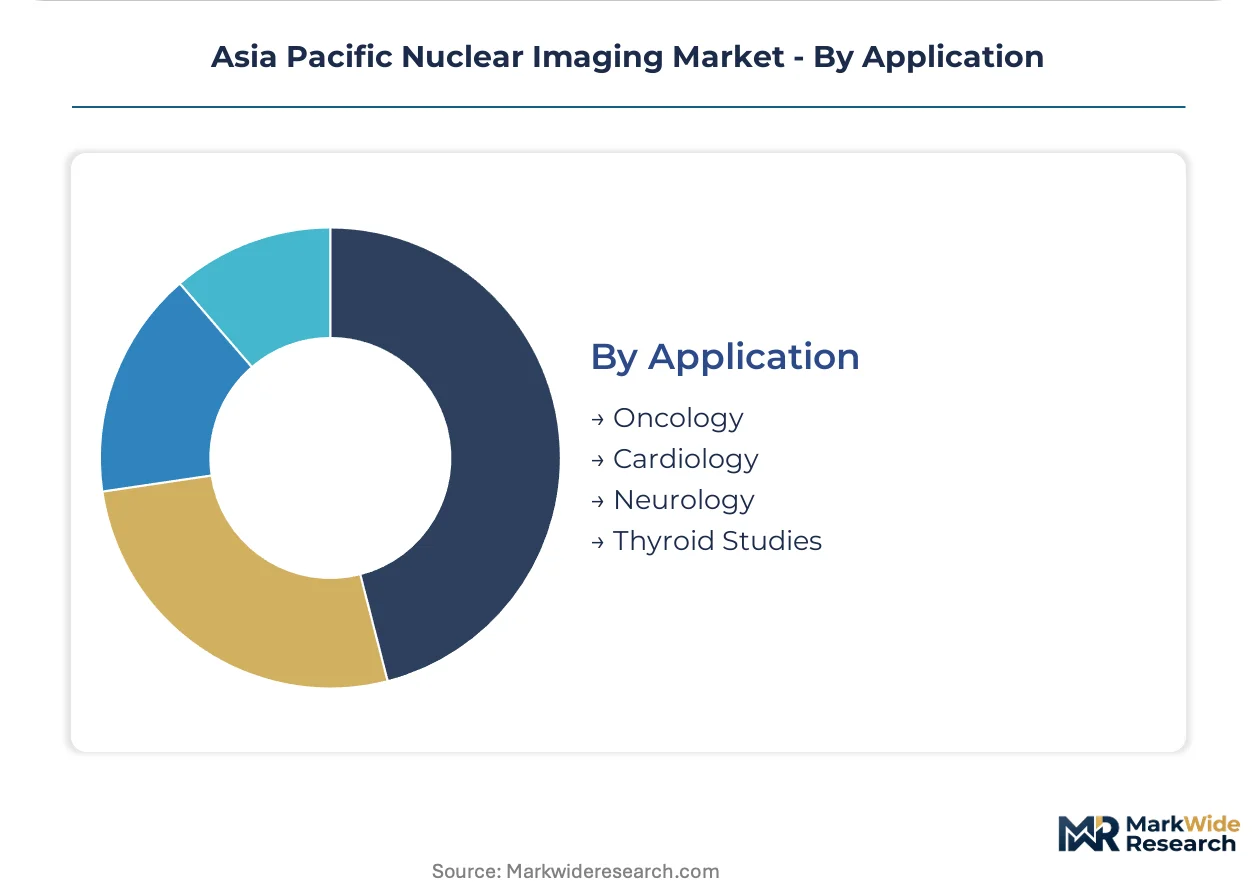
Application:
Clinical indication drives isotope selection, scan protocol design, and reimbursement negotiation across divergent therapeutic areas.
- Oncology:Tumor staging, treatment response assessment, and radiotherapy planning consume the majority of PET scanner capacity. F-18 FDG and Ga-68 PSMA tracers concentrate demand at cyclotron-equipped tertiary centers.
- Cardiology:Myocardial perfusion imaging using Tc-99m sestamibi or tetrofosmin sustains SPECT utilization rates. Detector material innovations improve sensitivity, opening substitution opportunities against invasive catheterization referrals.
- Neurology:Amyloid and tau imaging for dementia evaluation requires specialized radiochemistry and extended acquisition protocols. Japan's aging demographics expand addressable patient populations for neurology-focused molecular imaging.
- Thyroid Studies:I-131 and Tc-99m pertechnetate evaluations for hyperthyroidism and cancer surveillance maintain steady procedural volumes. Australia's hospital networks stabilize isotope availability through regional Mo-99 production infrastructure improvements.
Oncology concentrates the premium system deployments; cardiology sustains broader unit volumes through accessible isotope supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports cyclotron-produced isotopes to diagnostic centers across Southeast Asia, while South Korea supplies digital detector components to Australia's hospital procurement chains.
China
Proton therapy centers in Beijing and Shanghai drive demand for hybrid PET-CT and PET-MR systems. NMPA innovation pathways compress approval timelines for software-integrated reconstruction platforms. The Yangtze River Delta anchors manufacturing partnerships between domestic vendors and European detector suppliers.
Japan
University hospitals in Tokyo deploy PET-MR systems for neurology research and dementia imaging protocols. PMDA streamlined software-as-a-medical-device pathways accelerate AI-embedded reconstruction algorithm deployments. The Kansai region's Osaka cluster concentrates SiPM detector adoption for pediatric oncology reduced-dose trials.
India
Diagnostic center chains in Mumbai and Bengaluru unbundle equipment procurement from service contracts to compress total cost of ownership. CDSCO medical device rules require substantial local evidence generation for novel hybrid systems. The Delhi-NCR corridor concentrates gamma camera manufacturing under PLI scheme incentives.
Australia
Regional hospital networks stabilize Tc-99m availability through Mo-99 production infrastructure improvements. TGA device approval timelines extend commercialization cycles compared to reference market clearances. Southeast Queensland's Brisbane cluster maintains gamma camera fleets for bone scintigraphy and sentinel node mapping.
South Korea
Cancer centers in Seoul participate in multi-tracer imaging trials using digital detector platforms. MFDS regulates software-integrated systems with requirements shaped by EU AI Act extraterritorial influence. The Busan-Ulsan corridor anchors component fabrication for export to Vietnam's emerging diagnostic markets.
Asia Pacific Nuclear Imaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement hierarchies that favor either bundled service networks or component pricing transparency. The market structure consolidates around three tiers: premium hybrid system integrators, mid-market SPECT specialists, and emerging domestic manufacturers. Strategic archetypes include cyclotron-anchored isotope suppliers, detector material innovators, and AI-embedded software vendors. Dominant competitive moves encompass geographic expansion through local manufacturing partnerships and technology licensing agreements that accelerate regulatory clearance.
Among Japan-based conglomerates, Canon Medical Systems Corporation and Fujifilm Holdings Corporation occupy positions within the detector innovation archetype, while Siemens Healthineers anchors the European-origin premium-system tier. These companies exemplify how regional players leverage domestic regulatory relationships against multinational service network scale.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| Koninklijke Philips NV |
| GE Healthcare |
| Neusoft Medical Systems Co., Ltd. |
| Fujifilm Holdings Corporation |
| Hitachi Medical Corporation |
| Shimadzu Corporation |
| Samsung Medison |
| Others |
Value Chain & Pricing Dynamics
Cyclotron undercapacity in Southeast Asia concentrates isotope pricing power with Japanese and South Korean suppliers, compressing margins for diagnostic center chains while forcing tertiary hospitals to absorb premium hybrid system costs. India's PLI scheme is redrawing procurement economics by localizing gamma camera production and decoupling equipment acquisition from bundled service contracts.
Pricing Analysis
Next-generation SiPM-based PET systems command 40-60% premiums over analog PMT configurations, while prior-generation SPECT platforms face accelerating price erosion in India's competitive diagnostic markets. Three-tier pricing structure across premium hybrid suites, standard PET-CT configurations, and economy SPECT systems reflects divergence in after-sales service bundling and cyclotron access guarantees. Cost compression in the SPECT tier is intensifying because domestic manufacturing under PLI incentives is expanding supplier pools. Diagnostic center chains in Mumbai and Delhi exhibit highest price sensitivity, whereas proton therapy centers in Beijing and Shanghai prioritize treatment planning precision over capital outlay.
Supply Chain Analysis
Contract manufacturing for detector components concentrates with South Korean EMS providers and Japanese precision electronics specialists serving Canon Medical Systems and Fujifilm Holdings. Raw material dependencies center on lutetium-yttrium oxyorthosilicate crystals sourced from China and Japan, high-purity germanium for semiconductor detectors from Russia and Kazakhstan, and specialized lead shielding alloys from Australian foundries. Single-source vulnerability in Mo-99 reactor supply creates isotope availability risk that cascades through Tc-99m distribution networks. Distribution runs through vendor-direct installation teams for hybrid systems and independent radiopharmaceutical distributors for isotope logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around cyclotron licensing and isotope production permits creates formidable defensive moats for established nuclear imaging vendors. Switching costs for hospital systems escalate with embedded technologist training and workflow integration investments.
For Market Incumbents: Insulate service revenue streams by extending performance-based uptime guarantees that lock diagnostic center chains into long-term maintenance contracts. Deepen backward integration into SiPM detector fabrication to capture margin migrating from system sales to component replacement cycles. Emerging domestic manufacturers in India threaten mid-market positioning unless incumbents accelerate CDSCO registration timelines through local clinical trial partnerships. For New Entrants and Emerging Players: Vietnam's diagnostic infrastructure gap offers lowest competitive density among Asia Pacific growth markets, with private hospital chains in Ho Chi Minh City seeking turnkey hybrid installations without legacy migration burdens. Cardiac stress testing protocols represent the most penetrable application segment, as detector sensitivity improvements enable SPECT substitution against invasive catheterization referrals. A cyclotron-isotope supply partnership model bypasses capital intensity barriers that constrain direct PET scanner competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-embedded software layers as PMDA streamlined validation pathways reduce R&D burn rates for reconstruction algorithm developers. Acquisition targets should emphasize vendors with compliant EU AI Act protocols that accelerate Asia Pacific deployment timelines. The signal to monitor is CDSCO approval velocity for novel hybrid systems, as registration delays compress first-mover windows in India's expanding diagnostic market.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Infrastructure Partnership | Isotope supply agreements with Japan's reactor network secure F-18 availability for Southeast Asian expansion. |
| Software-as-Medical-Device Validation | PMDA streamlined pathways for AI reconstruction algorithms accelerate low-dose protocol deployment in pediatric oncology. |
| PLI-Anchored Manufacturing Scale-Up | Domestic gamma camera production under India's incentive scheme reduces import dependency for diagnostic chains. |
| Detector Material Innovation | SiPM timing resolution below 300 picoseconds enables time-of-flight PET capabilities that differentiate premium offerings. |
| Hospital System GPO Alignment | Procurement consolidation through Australia's hospital networks demands service-unbundled pricing transparency. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and trade flow records. Nuclear medicine department heads, biomedical engineers at tertiary centers, cyclotron operations managers, and GPO contracts managers provided operational perspective on equipment utilization and isotope logistics. Secondary validation drew from PMDA device approvals, CDSCO medical device rules, NMPA innovation pathway documentation, and customs data on detector component imports. Bottom-up installation tracking across hospital networks and diagnostic chains triangulates against top-down market sizing from capital expenditure disclosures.
Forecast inputs incorporate technology adoption curves across analog-to-digital detector transitions, cyclotron infrastructure buildout timelines, and reimbursement pathway evolution for hybrid imaging procedures. Segmentation modeling spans product type, end-user procurement authority, technology generation, and clinical application with regional regulatory cluster overlays. CAGRs derive from fitted growth curves adjusted for capital intensity thresholds and isotope supply constraints. Cyclotron capacity utilization rates and PLI scheme disbursement velocity serve as industry-specific forecast sensitivities.
Practitioners should monitor reactor maintenance schedules, PLI scheme expansion announcements, and AI Act compliance certification timelines for early signals of supply disruption or competitive repositioning. Quarterly review of CDSCO approval queues, NMPA innovation pathway decisions, and Mo-99 production facility status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
Ultrasound Market