
 Mexico Continuous Glucose Monitoring Market | 2026-2036
Mexico Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Continuous Glucose Monitoring Market Insights
Hospital outpatient departments are hardening their position as the dominant clinical setting for continuous glucose monitoring adoption in Mexico. Abbott Laboratories leverages its established pharmacy channel presence to sustain broad retail availability across major metropolitan zones. Dexcom Inc. differentiates through sensor accuracy specifications that appeal to endocrinology practices seeking tighter glycemic control protocols. Medtronic anchors its competitive stance via integrated insulin pump connectivity that appeals to technologically sophisticated patient cohorts.
Continuous glucose monitoring comprises wearable electrochemical sensor systems that measure interstitial glucose concentrations through enzymatic reactions, typically sampling every one to five minutes and transmitting data to receivers or smartphones for real-time trend analysis and hypoglycemic event alerting. The primary commercial purpose centers on reducing HbA1c variability while minimizing fingerstick blood glucose testing burden for insulin-dependent patients. Flash glucose monitoring occupies the largest installed base among technology segments, reflecting patient preference for on-demand scanning without alarm fatigue. Real-time monitoring registers the fastest expansion trajectory, driven by closed-loop artificial pancreas development and payer willingness to reimburse predictive alert functionality. Wearable sensors concentrate the majority of hardware margin pools, though software platforms capture recurring subscription revenue with superior lifetime value economics.
COFEPRIS maintains Class III medical device oversight for continuous glucose monitoring systems, requiring clinical validation submissions that extend registration timelines and elevate barrier costs for new entrants. Mexico's General Health Law provisions on medical device traceability mandate unique device identification compliance, shaping packaging and distribution infrastructure investments. NOM-241-SSA1-2012 standards govern good manufacturing practices for active medical devices, influencing quality system audits for both domestic assemblers and importers. Stakeholders must monitor pending modifications to the national formulary reimbursement catalog that could expand public sector access beyond current limited indications.
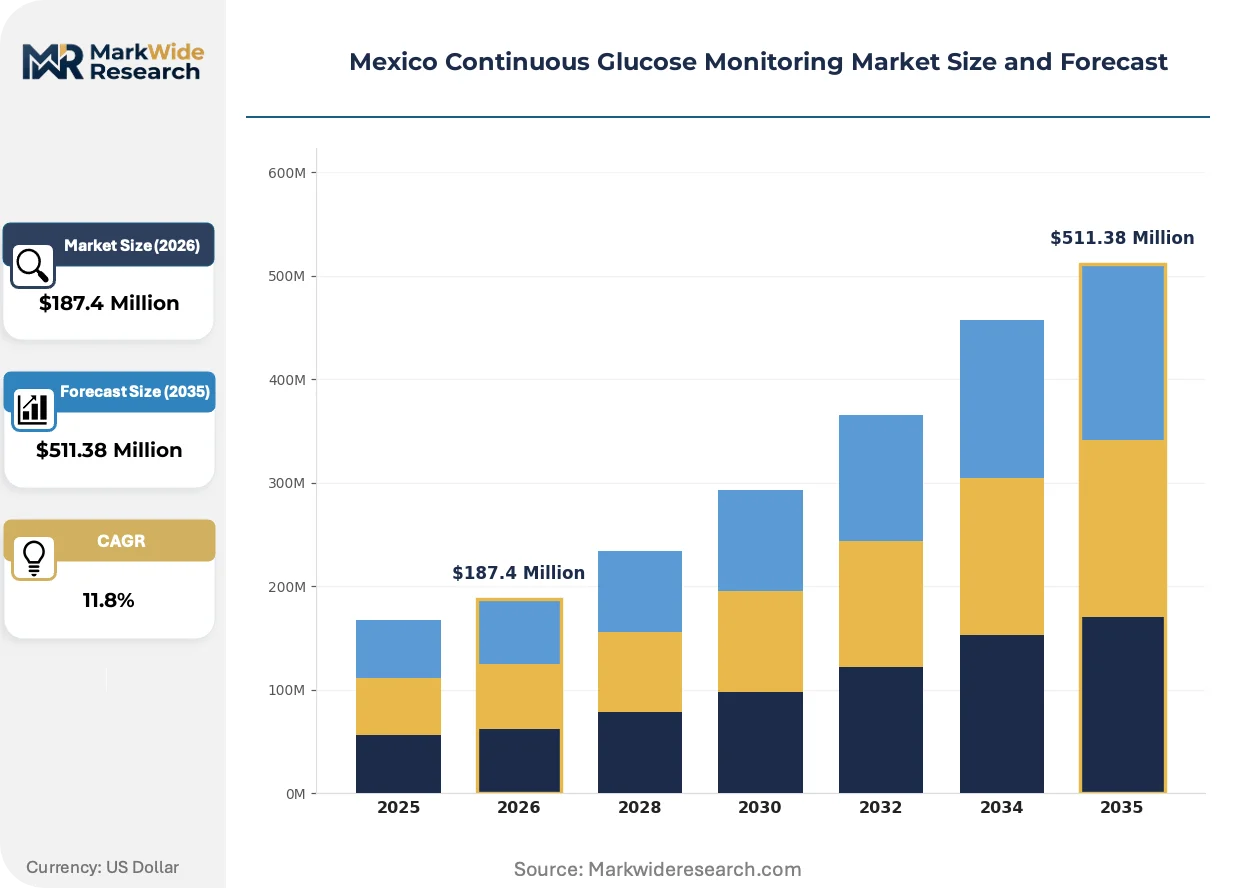
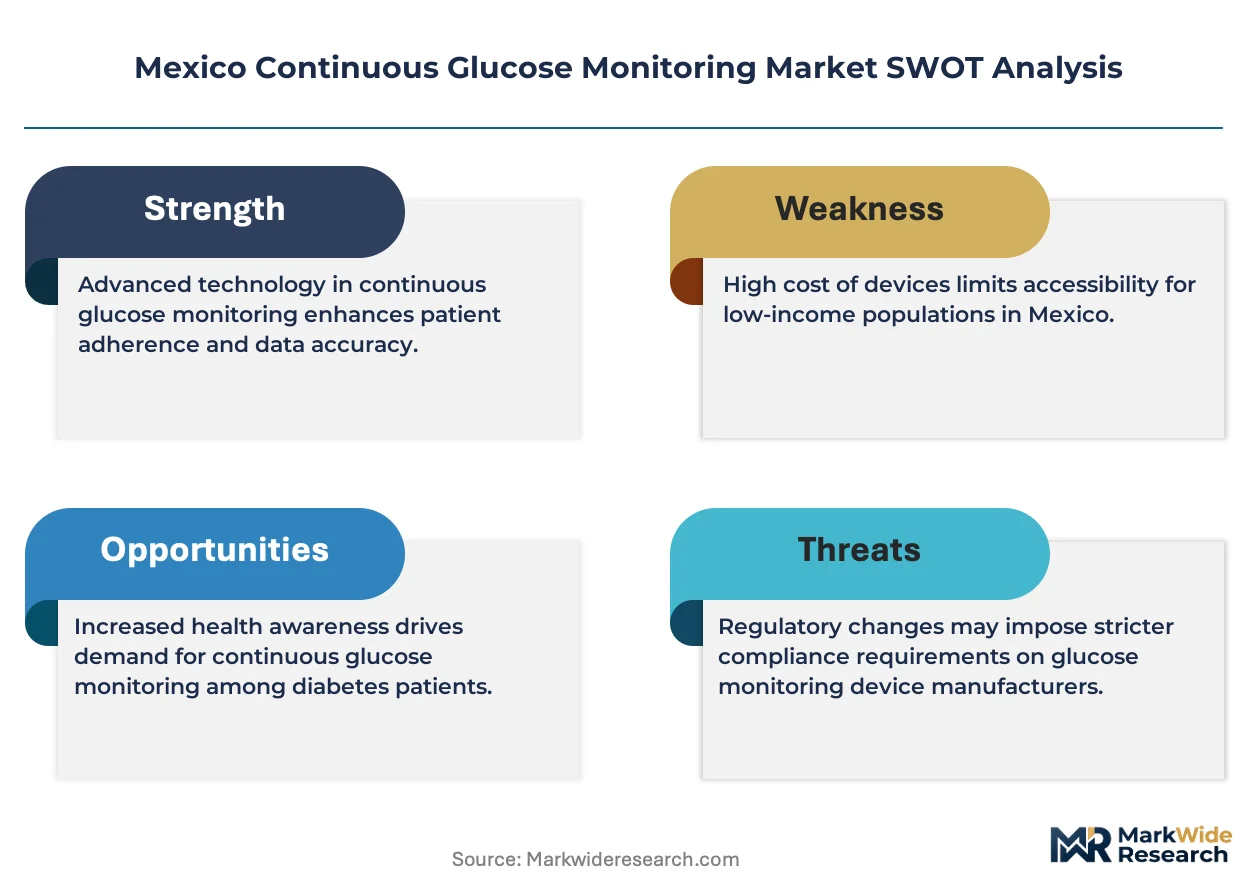
Market Dynamics
COFEPRIS Class III registration timelines are compressing competitive entry windows while hospital outpatient procurement centralization concentrates purchasing power among metropolitan health systems.
Growth Catalysts
- NOM-241-SSA1-2012 compliance:Active medical device manufacturing standards are elevating quality system investments that differentiate established importers from new market entrants.
- Flash glucose monitoring preference:Patient-driven demand for on-demand scanning without alarm fatigue is expanding the installed base beyond insulin-dependent cohorts.
- Monterrey endocrinology cluster:Specialist density and private insurance penetration in this northern metropolitan zone are accelerating clinical protocol standardization.
Market Restraints
- COFEPRIS clinical validation requirements:Extended registration timelines for Class III diagnostics create capital lockup periods that deter smaller manufacturers.
- Sensor substrate cost volatility:Electrochemical membrane materials face input price fluctuations that compress hardware margins at volume tiers.
- Unique device identification mandates:Mexico's General Health Law traceability provisions necessitate packaging infrastructure investments that raise per-unit fixed costs.
Strategic Opportunities
- Public sector formulary expansion:Pending modifications to the national reimbursement catalog could unlock hospital inpatient coverage beyond current limited indications.
- Real-time predictive alert integration:Closed-loop artificial pancreas development is unifying sensor data with automated insulin delivery protocols.
- Pharmacy channel deepening:Retail availability expansion into secondary cities beyond Mexico City and Monterrey addresses geographic access gaps.
Industry Challenges
- COFEPRIS audit preparation capacity:Domestic assemblers and importers face talent scarcity in regulatory affairs functions capable of navigating quality system inspections.
- Legacy glucose meter integration:Health information system compatibility requirements complicate hospital procurement decisions for standalone CGM deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Continuous Glucose Monitoring Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Transmitters, Software Platforms, Mobile Applications Technology: Flash Glucose Monitoring, Real-Time Monitoring, Continuous Glucose Sensors, Implantable Sensors End User: Diabetics, Healthcare Professionals, Research Institutions, Home Users Delivery Mode: Online Distribution, Pharmacy Sales, Direct-to-Consumer, Healthcare Facilities |
| Companies Covered | Medtronic, Abbott Laboratories, Dexcom Inc., Roche Diabetes Care, Tandem Diabetes Care, Insulet, Senseonics, Ascensia Diabetes Care, LifeScan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Continuous Glucose Monitoring Market Trends and Innovations
Sensor miniaturization and algorithmic glucose prediction are compressing the gap between intermittent scanning and continuous automated glycemic management.
Factory-calibrated electrochemical sensors are eliminating fingerstick calibration requirements that previously burdened patient onboarding. Endocrinology practices in Mexico City are adopting these systems at accelerated pace for type 1 diabetes protocols. This calibration-free architecture is unifying patient adherence metrics with clinical workflow efficiency.
COFEPRIS maintains Class III oversight for software-as-medical-device updates, requiring post-market change control submissions that slow iterative algorithm deployment. This regulatory friction compresses competitive differentiation timelines for real-time alert accuracy improvements. Manufacturers are responding with pre-submission strategy investments to parallel-track hardware and software registration pathways.
Hospital procurement centralization is consolidating purchasing authority within supply chain committees that evaluate total cost of ownership across sensor life. Private insurers in Monterrey are displacing fragmented clinic-level purchasing with preferred device contracts tied to outcomes reporting. This committee-based decision structure is most visible in tertiary care networks where endocrinology departments anchor glycemic management standardization.
Mexico Continuous Glucose Monitoring Market Segmentation
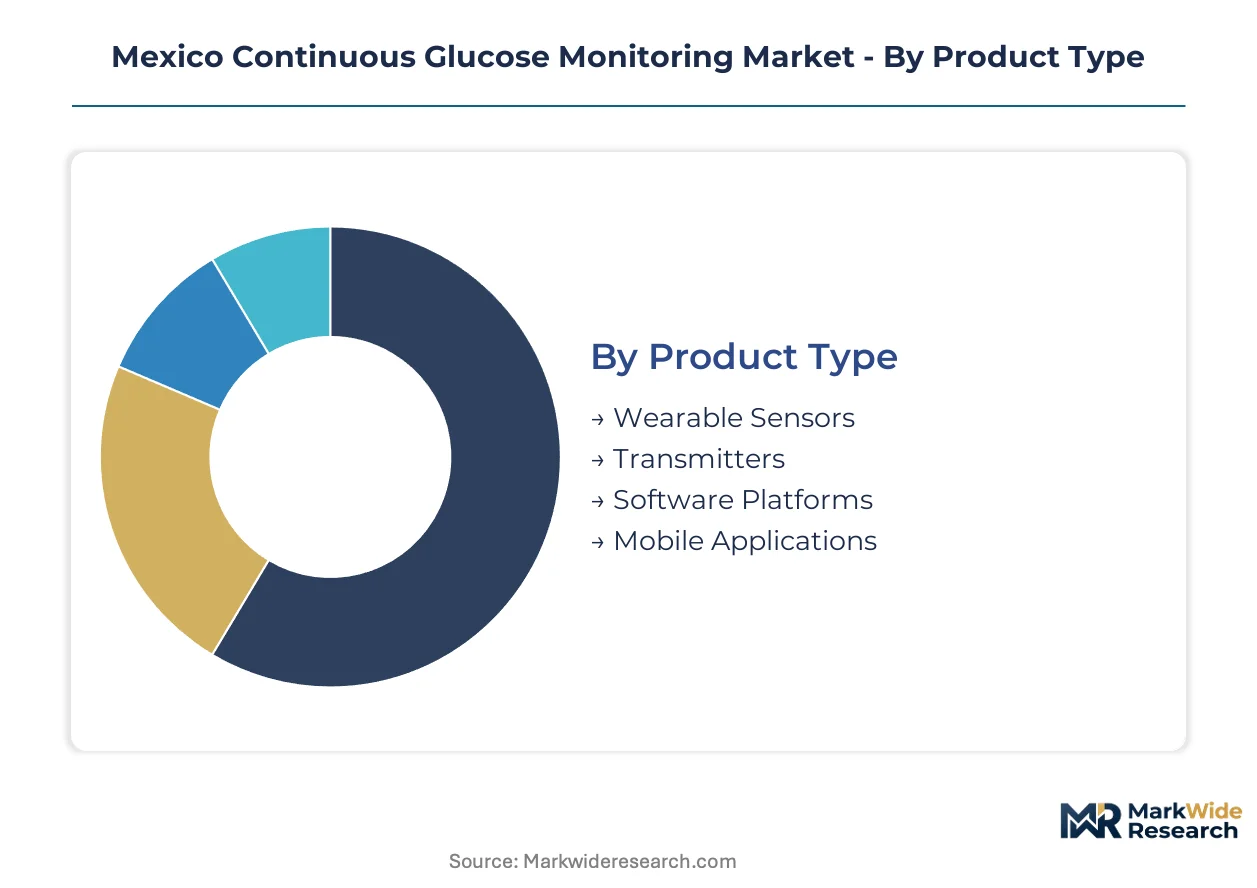
Continuous glucose monitoring in Mexico fragments across hardware, software, and service layers that command distinct margin profiles and regulatory treatment. Understanding these segment boundaries clarifies where COFEPRIS compliance costs concentrate versus where recurring revenue streams accumulate.
Product Type:
Wearable sensors capture the volume tier while software platforms extract the premium tier through subscription economics.
- Wearable Sensors:Electrochemical membrane assemblies with factory-calibrated enzymatic glucose oxidase layers attach to patient skin for interstitial fluid sampling. Demand clusters in Mexico City hospital outpatient departments where procurement committees evaluate total cost of ownership across sensor life. COFEPRIS Class III oversight elevates barrier costs for new entrants.
- Software Platforms:Cloud-based analytics engines aggregate glucose trend data and generate predictive hypoglycemic alerts for clinical decision support. Monterrey endocrinology practices are adopting these systems fastest for closed-loop artificial pancreas development. Recurring subscription revenue carries superior lifetime value economics versus hardware sales.
- Transmitters:Bluetooth-enabled relay devices bridge sensor data to smartphones or dedicated receivers, typically replaced every three months.
- Mobile Applications:Patient-facing interfaces for glucose visualization and caregiver data sharing, subject to COFEPRIS software-as-medical-device change control requirements.
Today's leader: Wearable Sensors. Tomorrow's challenger: Software Platforms.
Technology:
Flash systems dominate installed base while real-time architectures climb fastest on artificial pancreas development.
- Flash Glucose Monitoring:On-demand scanning systems eliminate alarm fatigue through patient-initiated glucose checks rather than automated alerts. Demand concentrates among type 2 diabetes patients in Monterrey private insurance networks seeking reduced fingerstick burden. Patient preference for control over alert frequency drives expansion beyond insulin-dependent cohorts.
- Real-Time Monitoring:Continuous automated data transmission with predictive alerting enables tighter glycemic control protocols for type 1 diabetes management. Mexico City tertiary care networks are standardizing these systems for inpatient glycemic management committees. Closed-loop insulin pump integration represents the steepest expansion trajectory.
- Continuous Glucose Sensors:Standalone electrochemical sensing elements without integrated data transmission infrastructure.
- Implantable Sensors:Long-duration subcutaneous devices with extended replacement intervals, facing extended COFEPRIS clinical validation timelines.
Flash glucose monitoring anchors current volume. Real-time architectures are gaining share fastest on closed-loop protocol adoption.
End User:
Diabetic patients drive unit economics while healthcare professionals command purchasing authority.
- Diabetics:Insulin-dependent patients requiring continuous glycemic visibility to reduce HbA1c variability and hypoglycemic event frequency.
- Healthcare Professionals:Endocrinologists and hospital glycemic management committees in Mexico City and Monterrey concentrate procurement decision power.
- Research Institutions:Clinical trial sponsors evaluating sensor accuracy against laboratory reference methods for COFEPRIS registration submissions.
- Home Users:Non-insulin-dependent patients seeking lifestyle optimization through metabolic awareness, expanding addressable market beyond traditional indications.
Healthcare Professionals control purchasing today. Home Users represent the volume expansion frontier.
Delivery Mode:
Pharmacy channels capture retail accessibility while healthcare facilities concentrate high-value institutional contracts.
- Pharmacy Sales:Retail distribution through established pharmacy networks enables patient self-selection and reduces clinical onboarding friction.
- Healthcare Facilities:Hospital outpatient departments and tertiary care networks in Mexico City concentrate bulk purchasing authority for integrated glycemic management programs.
- Online Distribution:Direct digital sales channels expanding into secondary cities beyond Monterrey and Mexico City metropolitan zones.
- Direct-to-Consumer:Manufacturer-direct subscription models bypassing traditional clinical gatekeepers, subject to evolving reimbursement eligibility constraints.
Healthcare Facilities dominate contract value today. Online Distribution is expanding geographic reach fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where glucose monitoring manufacturers concentrate assembly operations, with Mexico's proximity to US demand and COFEPRIS pathway efficiency attracting regional production investment.
Mexico City Metro
Hospital outpatient procurement committees in Mexico City concentrate purchasing authority for integrated glycemic management systems. COFEPRIS Class III registration requirements for active medical devices extend product entry timelines. Tertiary care networks in the metropolitan zone are standardizing real-time monitoring protocols for type 1 diabetes inpatient management.
Nuevo León
Monterrey's endocrinology specialist density and private insurance penetration accelerate clinical protocol adoption. NOM-241-SSA1-2012 good manufacturing practice standards elevate quality system investments for domestic assemblers. The metropolitan area anchors northern Mexico's fastest CGM expansion trajectory through preferred device contracts tied to outcomes reporting.
Jalisco
Guadalajara's medical device manufacturing base supports electrochemical sensor assembly for regional distribution. The state's pharmaceutical cluster benefits from trade agreement access to North American markets. Local production facilities navigate COFEPRIS quality system audits to serve hospital procurement networks.
Bajío Region
Querétaro and Guanajuato industrial corridors attract medical device component manufacturing seeking central Mexico logistics positioning. The region's automotive electronics heritage transfers workforce skills into sensor transmitter assembly. Emerging pharmacy channel distribution extends retail availability beyond traditional metropolitan strongholds.
Northern Border States
Chihuahua and Baja California assembly operations leverage maquiladora frameworks for glucose monitoring hardware production. Cross-border supply chains integrate US sensor substrates with Mexican final assembly. These facilities serve COFEPRIS-registered distribution throughout Latin America while maintaining FDA pathway optionality.
Mexico Continuous Glucose Monitoring Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinational medical device corporations commanding hospital procurement channels while regional distributors capture pharmacy retail volume. The vendor base concentrates among three strategic archetypes: full-stack glucose management platforms with insulin pump connectivity, sensor-focused specialists emphasizing accuracy specifications, and diversified diagnostics portfolios leveraging existing clinical relationships. Competitive moves center on regulatory pathway pre-submission investments to compress COFEPRIS registration timelines and pharmacy channel deepening into secondary metropolitan zones.
Among US-based medical device corporations, Medtronic, Abbott Laboratories, and Dexcom Inc. occupy positions across the competitive spectrum. Medtronic exemplifies the integrated systems archetype through its historical insulin pump infrastructure. Abbott Laboratories represents the diversified diagnostics portfolio model with established pharmacy channel presence. Dexcom Inc. anchors the sensor-specialist positioning that appeals to endocrinology practices seeking predictive alert functionality.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Dexcom Inc. |
| Roche Diabetes Care |
| Tandem Diabetes Care |
| Insulet |
| Senseonics |
| Ascensia Diabetes Care |
| LifeScan |
| Others |
Pricing and Supply Chain Analysis
Captive sensor substrate production anchors both supply security and pricing power for established glucose monitoring manufacturers navigating Mexico's NOM-241-SSA1-2012 quality mandates. Electrochemical membrane manufacturing investments in Jalisco and Nuevo León compress procurement lead times while insulating hardware margins from commodity volatility.
Pricing Analysis
Distributor margin layers concentrate pricing power within hospital procurement committees evaluating total cost of ownership across sensor life. Subscription-based software platforms stratify across premium alert functionality, standard data visualization, and economy tier glucose logging tiers. Pricing pressure stems from COFEPRIS registration cost absorption competing with pharmacy channel margin compression. Home users exhibit highest price sensitivity, while tertiary care networks prioritize accuracy specifications over unit economics.
Supply Chain Analysis
NOM-241-SSA1-2012 domestic-content provisions reshape sourcing toward Jalisco and Nuevo León electrochemical assembly facilities. Sensor substrates draw from US specialty chemical suppliers, Taiwanese semiconductor foundries, and German precision membrane manufacturers. Single-source vulnerability concentrates in electrochemical enzyme supply chains. Distribution runs through pharmacy retail networks for patient-facing volume and healthcare facility contracts for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality-tier differentiation now commands premium positioning as endocrinology practices shift toward factory-calibrated, calibration-free sensor specifications. This demand migration favors manufacturers with validated accuracy protocols over commodity hardware competitors.
For Market Incumbents: Acquire regulatory affairs talent pools capable of parallel-tracking COFEPRIS hardware and software registration pathways. Consolidate pharmacy channel control in secondary metropolitan zones beyond Mexico City and Monterrey to preempt emerging entrant retail positioning. COFEPRIS audit preparation capacity scarcity threatens quality system compliance timelines for established importers. For New Entrants and Emerging Players: Begin with flash glucose monitoring white-space in Guadalajara and Bajío Region pharmacy channels where Abbott's retail dominance remains underdeveloped. Target home user segments seeking metabolic awareness beyond insulin-dependent indications. Deploy direct-to-consumer subscription models bypassing hospital procurement gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmacy distributors because COFEPRIS registration barriers prevent rapid competitive replication. Five-to-ten year viability hinges on formulary expansion timing for public sector coverage. Watch pending national reimbursement catalog modifications as inflection signal for volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Pre-Submission Investment | Parallel-tracked hardware and software registrations compress competitive entry windows for real-time alert systems. |
| Pharmacy Channel Deepening | Retail availability expansion into Querétaro and Guanajuato addresses geographic access gaps beyond dominant metropolitan zones. |
| Software Companion Development | Predictive hypoglycemic alert platforms capture recurring subscription revenue with superior lifetime value economics versus hardware sales. |
| Hospital System Partnership | Integrated glycemic management contracts with Mexico City tertiary care networks standardize procurement committee decision criteria. |
| Reimbursement Strategy | Outcomes reporting alignment with Monterrey private insurer preferred device contracts accelerates clinical protocol adoption. |
Research Methodology
Coverage spans Mexico City, Monterrey, Guadalajara, and northern border states, with primary inputs from each regional cluster. Endocrinologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided qualitative validation. Secondary sources included COFEPRIS registration databases, hospital procurement records, NOM-241-SSA1-2012 audit filings, and private insurance formulary documentation. Bottom-up sensor shipment estimates triangulated against top-down healthcare expenditure allocations.
Rate-of-change decomposition separated volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end user category, and delivery mode. CAGRs derived from fitted growth curves incorporating COFEPRIS registration timeline assumptions and pharmacy channel penetration rates. Factory-calibrated sensor adoption curves and closed-loop artificial pancreas development timelines shaped forward projections.
Several conditions sit outside the modeled scope, including pending modifications to Mexico's national formulary reimbursement catalog and potential NOM-241-SSA1-2012 standard revisions. Forecasts reflect assumptions about COFEPRIS audit capacity and electrochemical membrane supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
BRICS Diabetes Drugs Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Iran Diabetes Care Devices Market