
 Disposable Insulin-Delivery Device Market | 2026-2036
Disposable Insulin-Delivery Device Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Insulin-Delivery Device Market Outlook
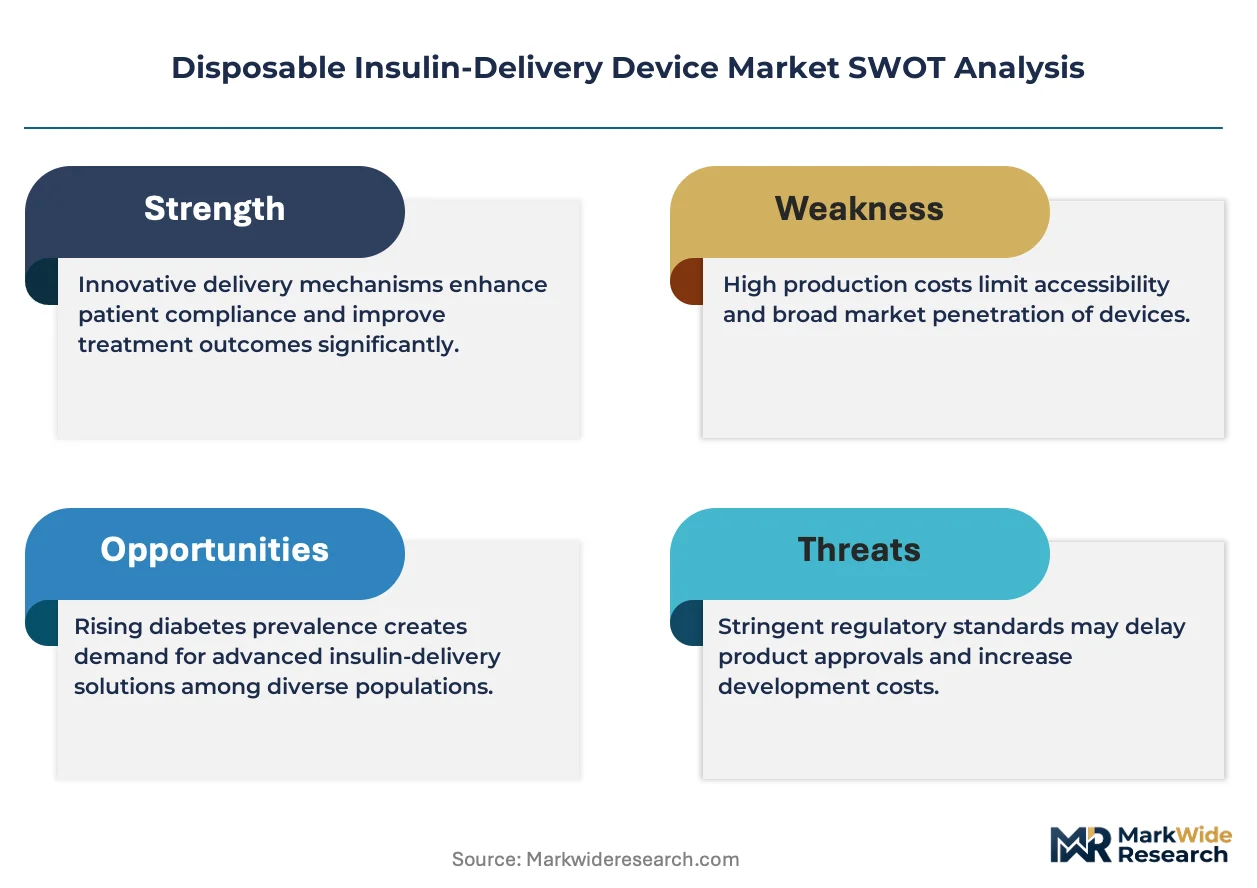
Home care patients are redrawing demand patterns away from hospital-administered insulin delivery. Medtronic leverages its pump technology heritage to compete in disposable-compatible ecosystems. Insulet Corporation specializes in tubeless patch pump designs that anchor its position among ambulatory users. Novo Nordisk dominates disposable pen manufacturing through captive supply of prefilled insulin cartridges.
Disposable insulin-delivery devices are single-use instruments engineered for precise subcutaneous insulin administration, typically incorporating sterile needles, dose-calibration mechanisms, and polymer housings manufactured via injection molding and gamma sterilization. Their primary purpose is to enable safe, repeatable glycemic control without cross-contamination risk. Prefilled pens command the largest revenue pool due to patient convenience and pharmacy reimbursement alignment, while smart delivery systems represent the fastest-expanding technology segment as connectivity features integrate with continuous glucose monitors. Conventional injectors remain entrenched in emerging markets where cost sensitivity limits electromechanical adoption.
FDA regulates these products as combination devices under 21 CFR Part 820 quality system requirements, while EMA enforces MDR compliance for CE-marked disposable pens sold across Europe. Both frameworks mandate biocompatibility testing, sterility assurance, and human-factors validation that elevate barriers for new entrants. Stakeholders must monitor evolving reimbursement criteria for smart delivery systems and anticipate how FDA digital health pre-certification may reshape competitive access for connected disposable platforms.
Market Dynamics
Home care migration is compressing hospital channel volumes while amplifying pharmacy-direct and direct-to-patient fulfillment requirements for single-use insulin delivery formats.
Growth Catalysts
- Reimbursement expansion:Germany's Statutory Health Insurance and China's National Healthcare Security Administration now cover prefilled pen devices for Type 2 patients, accelerating pharmacy substitution away from vial-and-syringe formats.
- Connectivity integration:Bluetooth-enabled dose logging is fragmenting the traditional pen market into connected and non-connected tiers, with endocrinology practices in the United States driving patient demand for CGM-paired systems.
- Sterility assurance standards:EMA's MDR Annex I requirements for single-use combination products are elevating quality benchmarks that favor manufacturers with validated gamma sterilization and automated visual inspection capabilities.
Market Restraints
- Polymer input volatility:Medical-grade polycarbonate and cyclic olefin copolymer prices fluctuate with benzene and ethylene feedstock markets, compressing margins for injection-molded pen housing producers.
- Needle supply concentration:Thin-wall cannula manufacturing concentrates among Japanese and South Korean precision metalworking clusters, creating single-source vulnerability for pen needle assemblies.
- Regulatory divergence friction:FDA's 21 CFR Part 820 quality system requirements and EMA's MDR technical documentation demands impose parallel compliance burdens that extend time-to-market for new entrants.
Strategic Opportunities
- Rural China penetration:County-level hospital networks and township health centers remain underpenetrated by branded disposable pens, offering volume expansion for localized distribution partnerships.
- Smart delivery convergence:Integration of near-field communication chips with disposable pen platforms enables dose verification without reusable electronics, opening subscription revenue models for data-analytics services.
- Specialty pharmacy channel:CVS Health and Walgreens hub-and-spoke models for chronic disease management are creating dedicated fulfillment pathways that bypass traditional wholesale distribution.
Industry Challenges
- Human factors engineering talent:ISO 62366 usability validation requires specialized industrial design and clinical evaluation expertise that remains scarce in emerging manufacturing hubs.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, extending pre-submission timelines for novel polymer formulations.
- Legacy ERP integration:Track-and-trace requirements for unit-level serialization demand upgrades to manufacturing execution systems that many mid-tier producers have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Insulin-Delivery Device Market |
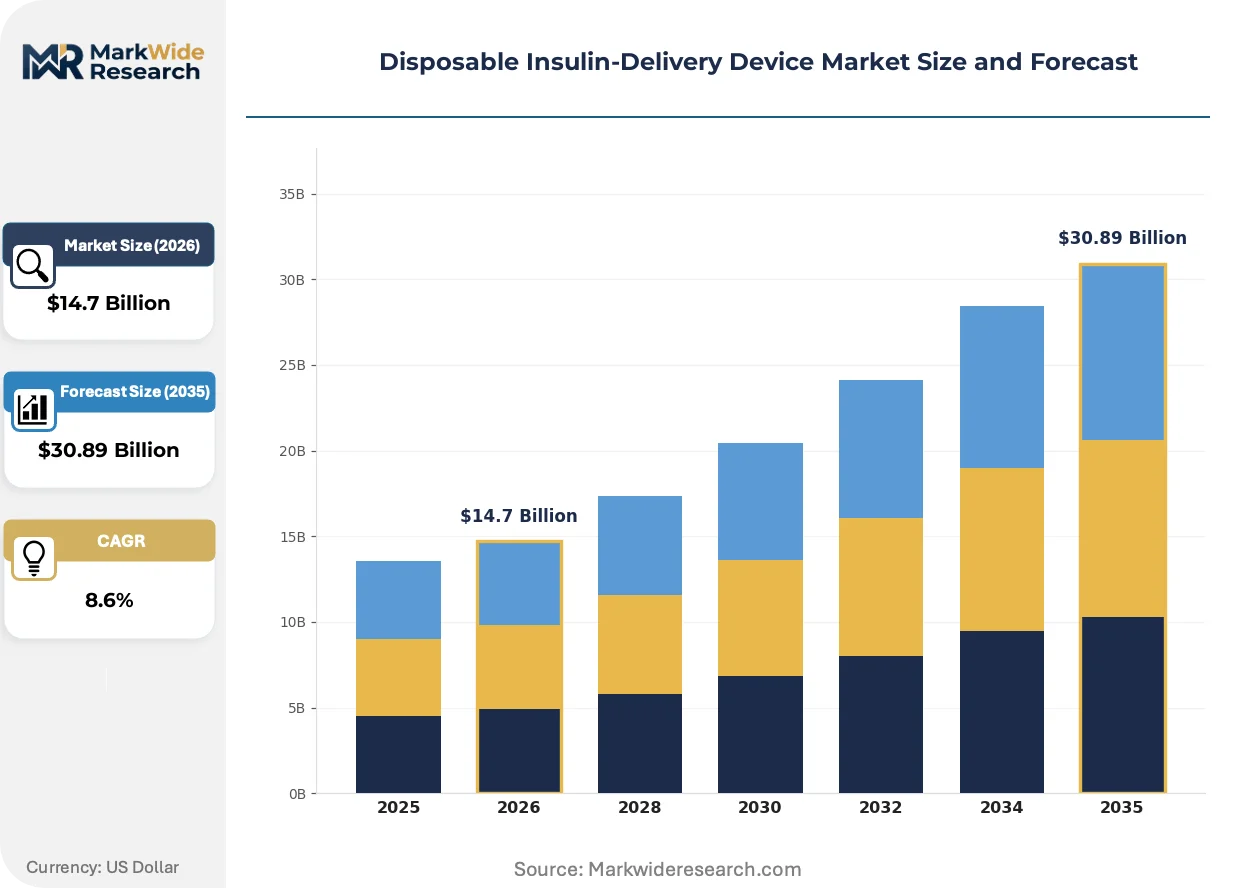
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefilled Pens, Insulin Syringes, Insulin Pumps, Jet Injectors Technology: Micro-Needle, Smart Delivery Systems, Electromechanical Devices, Conventional Injectors End User: Home Care, Hospitals, Diabetes Clinics, Rehabilitation Centers Delivery Mode: Subcutaneous, Intravenous, Intra-arterial, Intrapulmonary |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, Novo Nordisk, Sanofi, Eli Lilly and Company, Embecta Corp., Ypsomed, Roche Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Insulin-Delivery Device Market Strategic Shifts
Electromechanical miniaturization and data connectivity are redefining what "disposable" means in insulin delivery, blurring boundaries between single-use and durable device categories.
Tubeless patch pump microfluidics is fragmenting the ambulatory insulin delivery landscape. These systems combine piezoelectric micropumping with flexible substrate manufacturing to deliver basal and bolus insulin without tubing sets. Adolescent and young adult Type 1 patients in the United States are adopting patch pumps at rates that outpace traditional pump conversion curves. The technology is fragmenting endocrinology practice workflows by requiring remote monitoring infrastructure that most clinics lack.
EMA's MDR clinical evaluation requirements for legacy predicate devices are forcing substantial equivalence pathway reformulations for pen platform renewals. Manufacturers must now generate clinical data or literature reviews demonstrating acceptable benefit-risk profiles under the updated regulation. Prefilled pen lines with pre-2017 CE marks face the steepest compliance cliffs, with several major portfolio refreshes currently under notified body review.
Direct-to-patient subscription models are displacing traditional pharmacy fulfillment for connected pen systems. Patients in Germany and the Netherlands receive quarterly shipments of prefilled cartridges paired with reusable Bluetooth-enabled dose trackers, with data services bundled into per-month fees. This pattern concentrates among digitally engaged patient populations with private insurance or supplemental coverage, creating a two-tier access structure that regulators in both countries are scrutinizing for equity implications.
Disposable Insulin-Delivery Device Market Segmentation
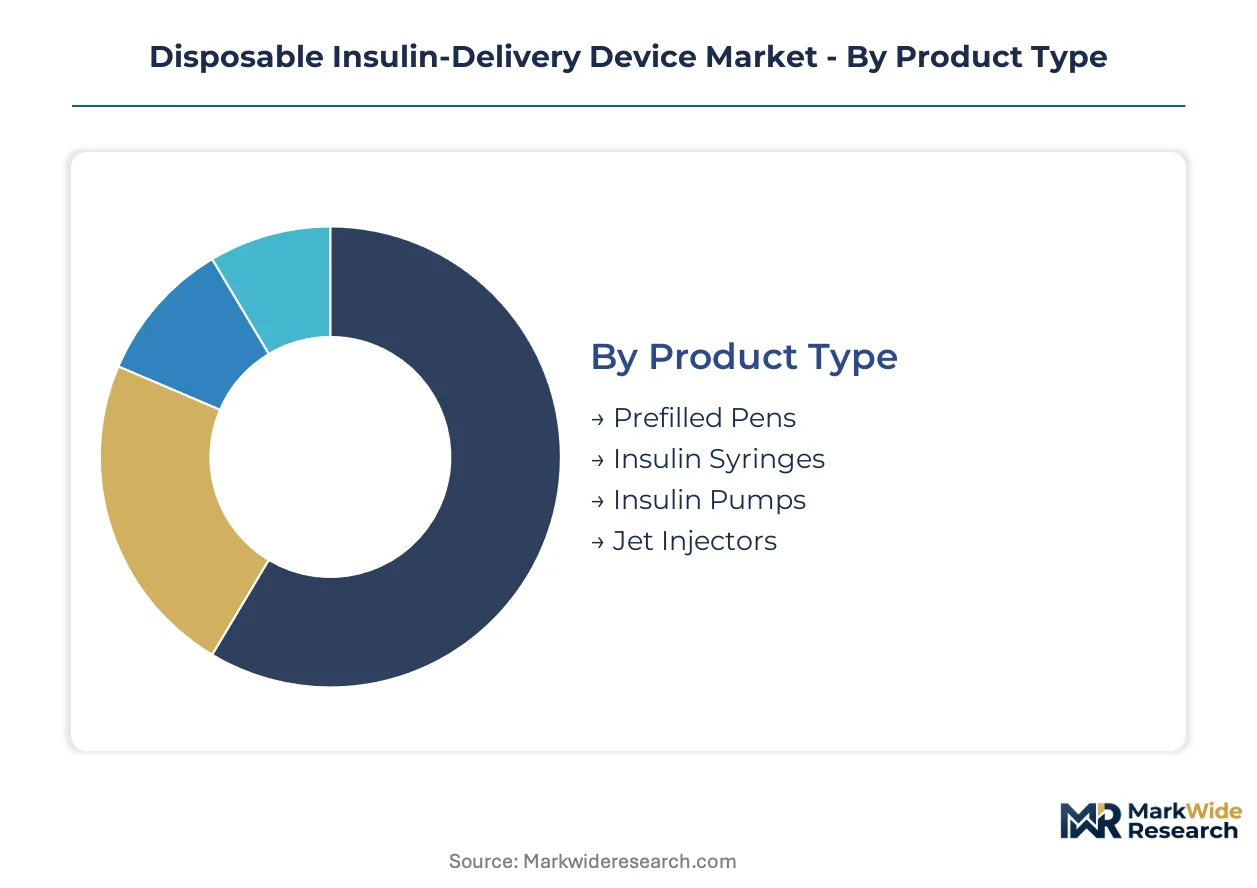
Channel economics and reimbursement pathways determine which device formats capture volume in disposable insulin delivery. Pharmacy-direct fulfillment, hospital procurement contracts, and specialty distributor networks each favor distinct product configurations and technology tiers.
Product Type:
Pharmacy channels in the United States and Germany move prefilled pens in highest volumes, while hospital procurement concentrates syringe purchases through group purchasing organizations. Direct-to-patient subscription services are fragmenting traditional channel structures for connected pen systems.
- Prefilled Pens:These devices integrate sterile insulin cartridges with precision dose-calibration mechanisms in injection-molded polymer housings. Germany's Statutory Health Insurance and China's National Healthcare Security Administration reimbursement expansions are accelerating pharmacy substitution away from vial-and-syringe formats.
- Insulin Syringes:Conventional single-use syringes with fixed or detachable needles remain the lowest-cost administration option. Emerging markets where cost sensitivity limits electromechanical adoption sustain volume concentration, particularly in county-level hospital networks across rural China.
- Insulin Pumps:Tubeless patch pump designs with piezoelectric micropumping and flexible substrate manufacturing serve adolescent and young adult Type 1 patients.
- Jet Injectors:Needle-free systems using high-pressure fluid streams for transdermal insulin delivery occupy niche therapeutic applications.
By volume, insulin syringes lead. By growth pace, prefilled pens are ahead.
Technology:
Cost tiers separate premium connected systems from economy conventional injectors, with reimbursement eligibility determining which tier patients access. Manufacturing complexity and regulatory validation requirements widen margin spreads between technology tiers.
- Smart Delivery Systems:Bluetooth-enabled dose logging and near-field communication chips enable CGM-paired insulin administration with data verification. United States endocrinology practices are driving patient demand for connectivity features that fragment the traditional pen market into connected and non-connected tiers.
- Micro-Needle:Arrays of micron-scale projections penetrate stratum corneum for minimally invasive insulin delivery with reduced pain perception.
- Electromechanical Devices:Motor-driven dose delivery with electronic feedback mechanisms requires ISO 62366 usability validation and specialized industrial design expertise.
- Conventional Injectors:Spring-loaded or manual mechanical systems without electronic components dominate cost-sensitive procurement segments.
Smart delivery systems command premium positioning. Micro-needle platforms are climbing the fastest.
End User:
Application requirements vary sharply across settings, with home care patients prioritizing portability and discretion while clinical environments emphasize sterility assurance and workflow integration. FDA and EMA quality system requirements apply differentially based on point-of-care classification.
- Home Care:Type 2 diabetes patients in residential settings are accelerating uptake of prefilled pen devices that enable self-administration without clinical supervision. Reimbursement alignment with pharmacy-direct fulfillment in the United States, Germany, and China is compressing hospital channel volumes while amplifying direct-to-patient requirements.
- Hospitals:Acute care facilities require single-use devices with validated gamma sterilization and automated visual inspection for inpatient glycemic management.
- Diabetes Clinics:Outpatient specialty practices concentrate prescription authority for connected pen systems and serve as gatekeepers for CGM-paired therapy adoption.
- Rehabilitation Centers:Skilled nursing and long-term care facilities balance cost containment with reduced infection risk from disposable formats.
Home care settings generate the highest shipment volumes. Diabetes clinics are gaining share fastest as prescription gatekeepers.
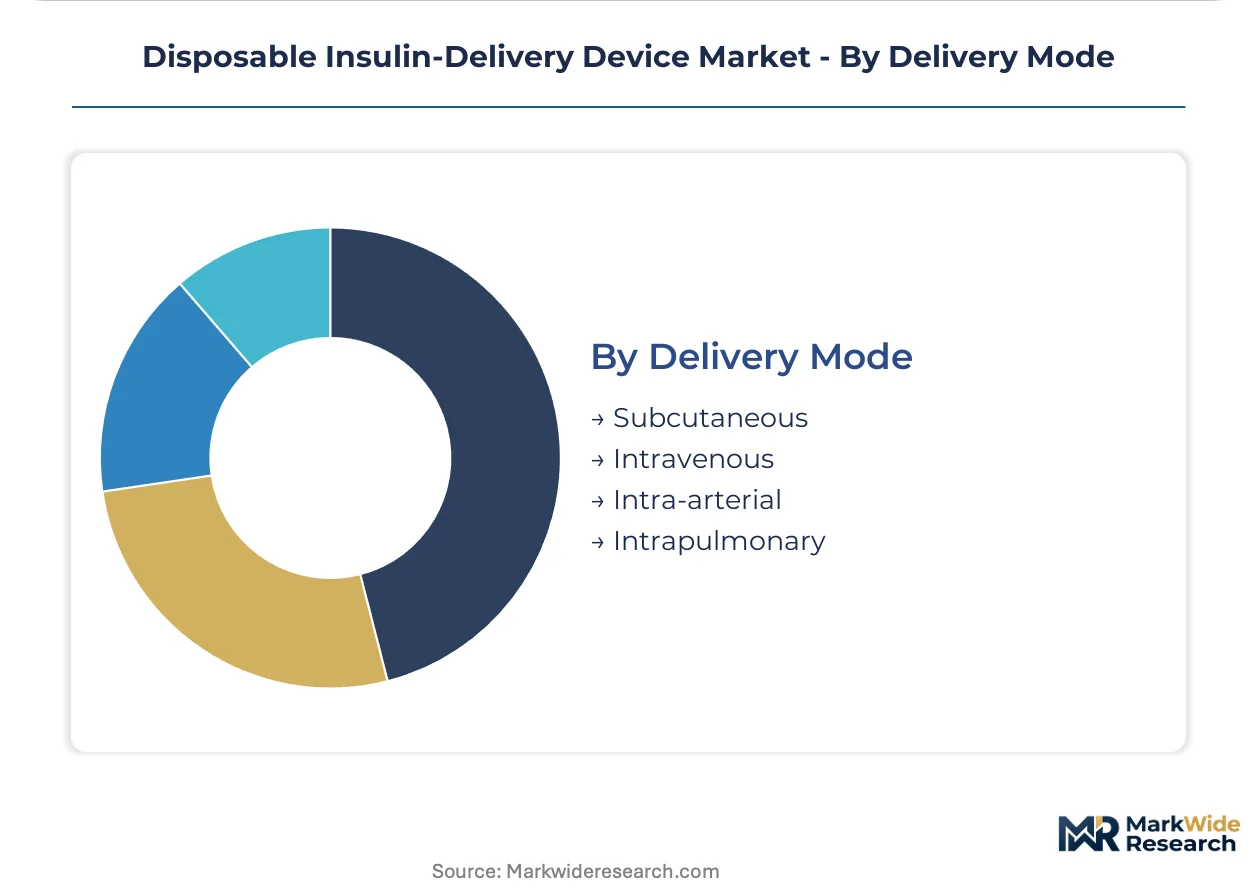
Delivery Mode:
Volume concentration and patient safety profiles determine which administration routes dominate insulin therapy, with subcutaneous delivery achieving near-universal adoption for basal and bolus dosing. Regulatory frameworks classify delivery mode as a critical design characteristic for combination product submissions.
- Subcutaneous:Injection into adipose tissue layers enables gradual insulin absorption with predictable pharmacokinetic profiles. Prefilled pens and conventional syringes engineered for precise subcutaneous administration command the largest revenue pool due to patient convenience and pharmacy reimbursement alignment.
- Intravenous:Direct vascular administration reserved for acute hyperglycemic crisis management in hospital settings.
- Intra-arterial:Arterial catheter delivery for specialized interventional procedures and research applications.
- Intrapulmonary:Inhalation-based insulin absorption through alveolar membranes, currently limited to specific therapeutic niches.
Subcutaneous delivery leads by volume. Smart delivery convergence is expanding fastest within this mode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer compounding and precision injection molding capabilities concentrate in Germany, the United States, and China, with gamma sterilization infrastructure clustering around pharmaceutical manufacturing corridors in each country.
United States
Type 1 patients in ambulatory settings are driving uptake of connected pen systems paired with continuous glucose monitors. FDA's 21 CFR Part 820 quality system requirements and digital health pre-certification pathways shape competitive access for Bluetooth-enabled disposable platforms. Endocrinology practices in Boston and Minneapolis anchor prescription authority for smart delivery systems.
Germany
Statutory Health Insurance reimbursement expansion for prefilled pen devices is accelerating pharmacy substitution away from vial-and-syringe formats. EMA's MDR Annex I sterility assurance standards elevate barriers for manufacturers lacking validated gamma sterilization capabilities. Industrial design and human factors engineering talent concentrates in Baden-Württemberg's medical technology cluster around Stuttgart.
China
The National Healthcare Security Administration's coverage expansion for disposable pens in Type 2 diabetes is compressing hospital channel volumes toward pharmacy-direct fulfillment. NMPA biocompatibility testing requirements under GB standards extend pre-submission timelines for novel polymer formulations. County-level hospital networks and township health centers across rural provinces remain underpenetrated by branded devices.
Japan
Aging demographics and rising diabetes prevalence are sustaining demand for precision dose-calibration mechanisms in prefilled formats. PMDA quality system requirements for combination products mandate ISO 62366 usability validation that favors established manufacturers. Thin-wall cannula manufacturing capabilities concentrate in precision metalworking clusters around Osaka and Nagoya.
Switzerland
Specialty pharmaceutical packaging and polymer formulation expertise supports high-barrier disposable pen housing production. Swissmedic technical documentation requirements for CE-marked devices align with EMA MDR compliance frameworks. Basel's pharmaceutical manufacturing corridor hosts sterile filling and device assembly operations serving European distribution networks.
Disposable Insulin-Delivery Device Market Competitive Environment
Concentration sits with diversified pharmaceutical-device conglomerates and specialized diabetes technology firms that command integrated manufacturing and regulatory validation capabilities. The vendor base spans three tiers: multinational pharma majors with captive insulin supply, dedicated diabetes device specialists with patch pump expertise, and regional injection system fabricators serving cost-sensitive procurement segments. Dominant competitive moves include strategic partnerships for connectivity integration and backward integration into polymer compounding to secure medical-grade material supply.
Within the diversified pharmaceutical-device tier, Novo Nordisk and Sanofi represent archetypes of manufacturers leveraging captive insulin supply chains to dominate prefilled pen production. Among diabetes technology specialists, Insulet Corporation occupies a position exemplifying tubeless patch pump design focus, while Medtronic anchors a heritage in pump technology extended toward disposable-compatible ecosystems. Ypsomed sits within the precision injection molding and pen platform tier, representing European manufacturing depth in dose-calibration mechanisms.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Embecta Corp. |
| Ypsomed |
| Roche Diabetes Care |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles for medical-grade polycarbonate and cyclic olefin copolymer feedstocks concentrate pricing power among gamma-sterilization facility operators in Germany, the United States, and China, while compressing margins for injection-molded pen housing producers facing benzene and ethylene volatility.
Pricing Analysis
FDA's 21 CFR Part 820 quality system requirements dictate the pricing tier structure across premium connected pens, standard prefilled formats, and economy conventional injectors. Price differentiation rests on ISO 62366 usability validation tier and CGM-pairing certification level. Cost compression in economy syringe tiers is intensifying because of polymer input volatility. County-level hospital networks across rural China exhibit highest price sensitivity, while United States endocrinology practices driving connected pen adoption show lowest sensitivity to per-unit pricing.
Supply Chain Analysis
Sixty-day inventory cycles expose thin-wall cannula sourcing vulnerability. Manufacturing concentrates in Germany, the United States, and China, with precision metalworking for needle assemblies drawing from Japanese and South Korean clusters. Raw material dependencies span medical-grade polycarbonate, cyclic olefin copolymer, and gamma-sterilization capacity. Single-source vulnerability in cannula supply creates structural risk. Distribution runs through pharmacy-direct fulfillment, specialty distributor networks, and direct-to-patient subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data-analytics subscription layers for connected pen platforms are expanding faster than hardware shipments, transforming device economics toward recurring-revenue models that reward service-attach capabilities over unit manufacturing scale.
For Market Incumbents: Fortify gamma-sterilization infrastructure and automated visual inspection capabilities to defend against EMA MDR Annex I compliance cliffs threatening legacy prefilled pen portfolios. Backward integration into medical-grade polymer compounding secures input cost control against benzene and ethylene volatility eroding injection-molded housing margins. For New Entrants and Emerging Players: FDA digital health pre-certification fast-tracks offer regulatory pathway acceleration into the connected pen segment fragmenting United States endocrinology practice demand. Rural China county-level hospital networks remain the most penetrable geography. Partnership with township health center distribution networks provides localized go-to-market leverage absent from branded incumbent channel structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart delivery system manufacturing requiring ISO 62366 usability validation and NFC chip integration capabilities. Five-to-ten year viability favors acquisition targets with validated notified body relationships and gamma-sterilization infrastructure. Watch EMA MDR clinical evaluation requirement enforcement as inflection signal for portfolio refresh timelines and compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR Annex I sterility assurance standards elevate barriers for manufacturers lacking validated gamma sterilization capabilities. |
| Software Companion Development | Bluetooth-enabled dose logging and CGM-pairing integration fragment traditional pen markets into connected and non-connected tiers. |
| Backward Integration | Captive medical-grade polymer compounding secures supply against benzene and ethylene feedstock volatility compressing margins. |
| Reimbursement Strategy | Germany's Statutory Health Insurance and China's National Healthcare Security Administration expansions accelerate pharmacy substitution from vial-and-syringe formats. |
| Hospital System Partnership | CVS Health and Walgreens hub-and-spoke chronic disease models create dedicated fulfillment pathways bypassing wholesale distribution. |
Study Parameters
Cross-validation between primary interviews with regulatory affairs leads, biomedical engineers, hospital purchasing committees, and GPO contracts managers and secondary validation through FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement contract records anchors the qualitative findings. Bottom-up shipment modeling by product type, technology tier, end-user setting, and delivery mode triangulates against top-down pharmaceutical manufacturer revenue disclosures.
Sensitivity analysis across polymer input cost scenarios, reimbursement policy shifts, and regulatory timeline variations shapes the analytical framework over the projection horizon. Segmentation dimensions span product type, technology tier, end-user setting, and delivery mode alongside regional regulatory cluster differentiation. CAGRs derive from volume trajectory modeling incorporating patient population growth, device substitution rates, and connectivity adoption curves.
Decision-makers should treat outputs as directional under stable reimbursement expansion and polymer supply continuity assumptions; material deviation in FDA digital health pre-certification pacing or EMA MDR enforcement stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
Indonesia Diabetes Care Devices Market