
 Middle-East and Africa Blood Glucose Monitoring Market | 2026-2036
Middle-East and Africa Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Blood Glucose Monitoring Market Foresight
Modular sensor-and-receiver bundling is shifting how diabetes clinics and home care buyers evaluate total cost of ownership across the Middle-East and Africa region. Abbott Laboratories leverages its FreeStyle platform architecture to anchor hospital contracts in Saudi Arabia and the UAE. F. Hoffmann-La Roche Ltd competes through Accu-Chek ecosystem specialization, sustaining brand loyalty among long-standing diabetes clinic partners. Dexcom differentiates with real-time data integration capabilities, positioning its G-series receivers for high-growth home care segments.
Blood glucose monitoring encompasses electrochemical and optical sensor technologies that quantify interstitial or capillary glucose concentration through enzymatic reactions, typically reporting values in milligrams per deciliter for clinical decision-making in diabetes management. Continuous glucose monitors employ subcutaneous filament sensors with factory-calibrated algorithms, eliminating routine fingerstick requirements while transmitting data to handheld receivers or smartphone applications. Test strips retain dominant volume share across pharmacy and hospital procurement channels, though continuous glucose monitors represent the fastest-expanding product category as Gulf state health systems prioritize remote patient monitoring infrastructure. Home care end users constitute the most rapidly growing demand segment, driven by rising type 2 diabetes prevalence and expanding medical insurance coverage for self-monitoring devices.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce medical device quality management standards that shape product registration timelines and clinical evidence requirements for glucose monitoring entrants. The UAE's MOHAP and Egypt's EDA maintain parallel regulatory frameworks, creating a multi-jurisdictional compliance landscape that favors manufacturers with established regional quality assurance operations. Stakeholders must monitor evolving reimbursement policies across national health insurance schemes and assess how local distribution channel consolidation affects pharmacy and online store access for device replenishment.
Market Dynamics
Hospital procurement departments across Gulf states are consolidating supplier contracts around connected glucose monitoring systems, compressing vendor margins while elevating technical integration requirements for device interoperability with electronic health records.
Growth Catalysts
- SFDA Streamlined Registration:Saudi Arabia's medical device registration pathways are reducing time-to-market for continuous glucose monitor manufacturers seeking hospital procurement contracts.
- Remote Patient Monitoring Infrastructure:Gulf state health systems are prioritizing capital allocation toward real-time data transmission capabilities for chronic disease management.
- Private Diabetes Clinic Networks:South Africa's specialized diabetes care facilities are driving concentrated test strip volume through centralized purchasing agreements.
Market Restraints
- Enzyme Sensor Input Volatility:Glucose oxidase and glucose dehydrogenase reagent costs fluctuate with biopharmaceutical supply chain disruptions, squeezing test strip manufacturing margins.
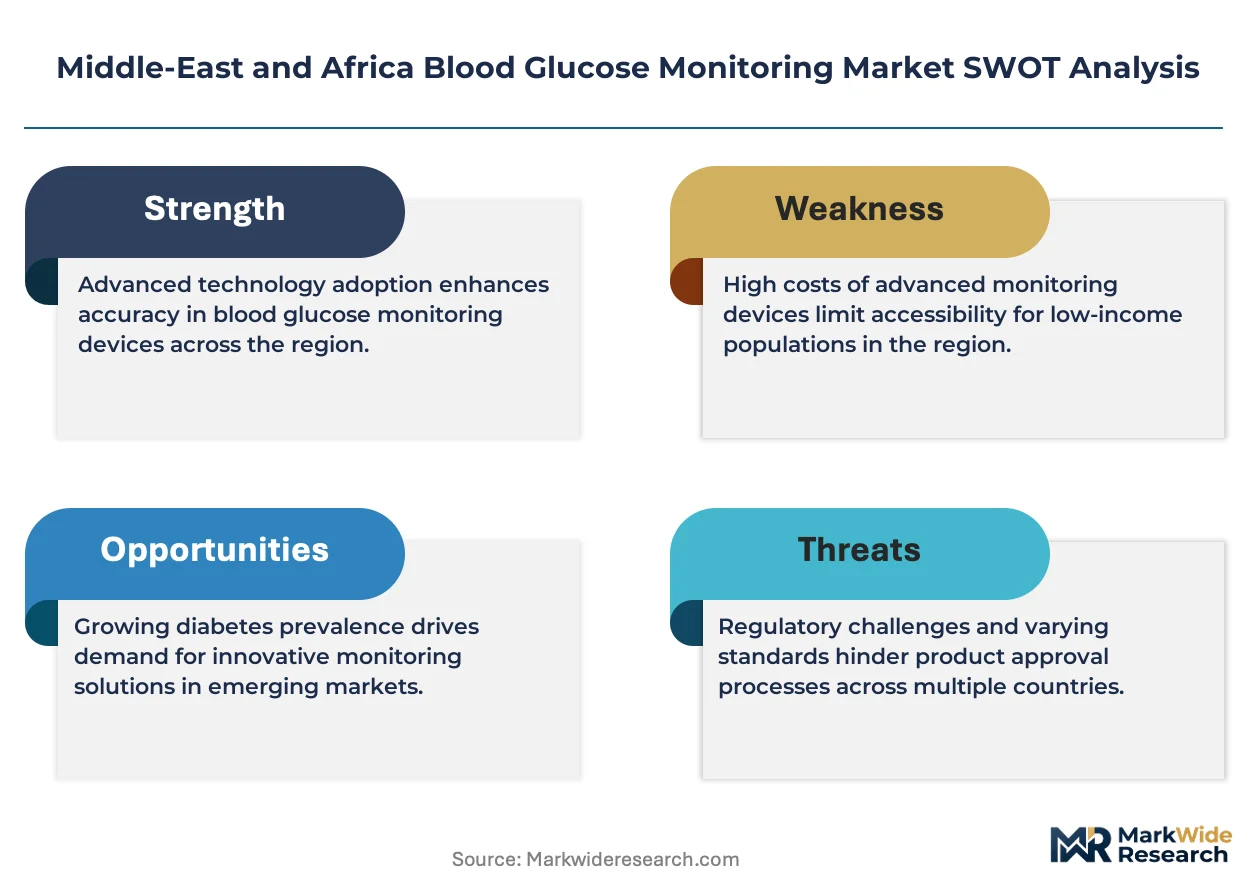
- Multi-Jurisdictional Compliance Burden:Parallel SFDA, MOHAP, SAHPRA, and EDA quality management standards force manufacturers to maintain redundant regional quality assurance operations.
- Optical Sensing Accuracy Limitations:Non-invasive glucose monitoring technologies face clinical validation gaps that restrict their displacement of electrochemical fingerstick methods in reimbursement schemes.
Strategic Opportunities
- Underpenetrated Egyptian Market:Egypt's EDA regulatory framework is maturing, creating first-mover advantages for manufacturers establishing local distribution partnerships before competitor saturation.
- Smartphone Application Convergence:Continuous glucose monitor data streams are integrating with native mobile health platforms, enabling direct-to-consumer subscription models bypassing traditional pharmacy channels.
- Medical Insurance Coverage Expansion:Gulf Cooperation Council national health insurance schemes are adding self-monitoring device reimbursement categories, reducing out-of-pocket cost barriers for home care users.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Sensor calibration algorithm development and clinical data science functions face recruitment bottlenecks across Middle-East and Africa regional headquarters.
- ISO 15197 Certification Timelines:In vitro diagnostic accuracy standards require extensive clinical evidence collection that delays product launches by 18-24 months relative to initial regulatory submission.
- Legacy Hospital Information System Integration:Proprietary data formats from incumbent glucose meter vendors create technical friction for connected device interoperability in Saudi and UAE hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Blood Glucose Monitoring Market |
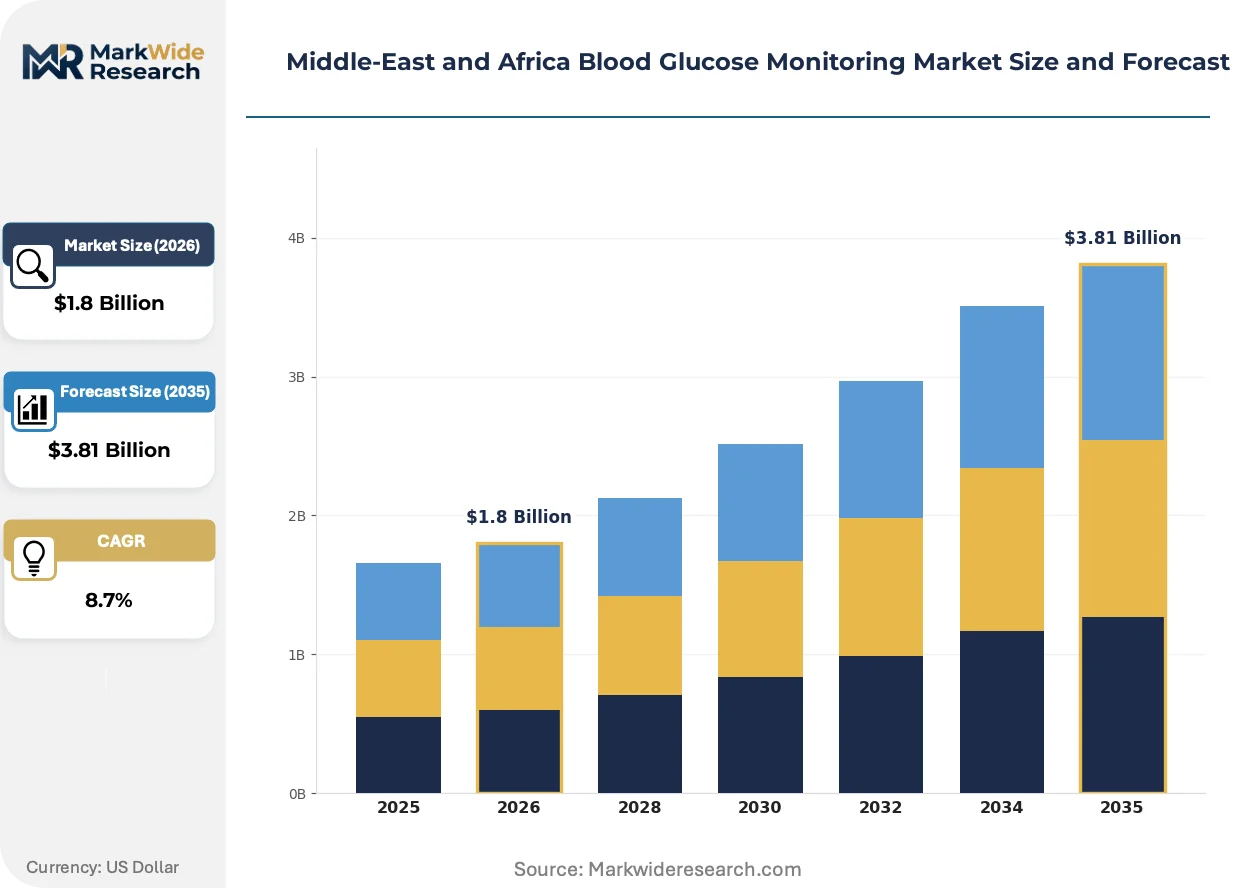
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Strips, Glucometers, Continuous Glucose Monitors, Lancing Devices End User: Hospitals, Diabetes Clinics, Home Care, Research Laboratories Technology: Enzymatic, Electrochemical, Optical, Non-Invasive Distribution Channel: Pharmacies, Online Stores, Hypermarkets, Specialty Stores |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Medtronic Plc, Dexcom, Johnson & Johnson, Ypsomed Holding AG, B. Braun SE, Nipro Corp, GE HealthCare Technologies Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Blood Glucose Monitoring Market Shifts & Advancements
Factory-calibrated filament sensors are eliminating routine fingerstick requirements while reshaping competitive positioning around data analytics capabilities rather than hardware accuracy specifications alone.
Subcutaneous glucose sensing technology employs electrochemical enzymatic reactions within flexible polymer filaments that transmit interstitial glucose readings to handheld receivers. Home care segments across the UAE and Saudi Arabia are adopting these systems at accelerating rates as medical insurance coverage expands. Real-time data integration is compressing hospital procurement decisions toward vendors offering comprehensive remote patient monitoring platforms rather than standalone devices.
SAHPRA in South Africa is enforcing strengthened medical device quality management standards that align with ISO 13485 certification requirements for glucose monitoring entrants. This regulatory convergence is extending product registration timelines while elevating clinical evidence thresholds. Continuous glucose monitor manufacturers are responding by establishing captive regional quality assurance operations in Johannesburg to accelerate market access.
Pharmacy channel consolidation across Gulf states is concentrating test strip replenishment purchasing through centralized hospital procurement departments and online subscription platforms. Independent retail pharmacies are losing volume share to diabetes clinic networks with integrated e-commerce capabilities. This channel rotation is most visible in Saudi Arabia, where SFDA-regulated online medical device sales are capturing growing share of repeat purchases from type 2 diabetes patients.
Middle-East and Africa Blood Glucose Monitoring Market Segmentation
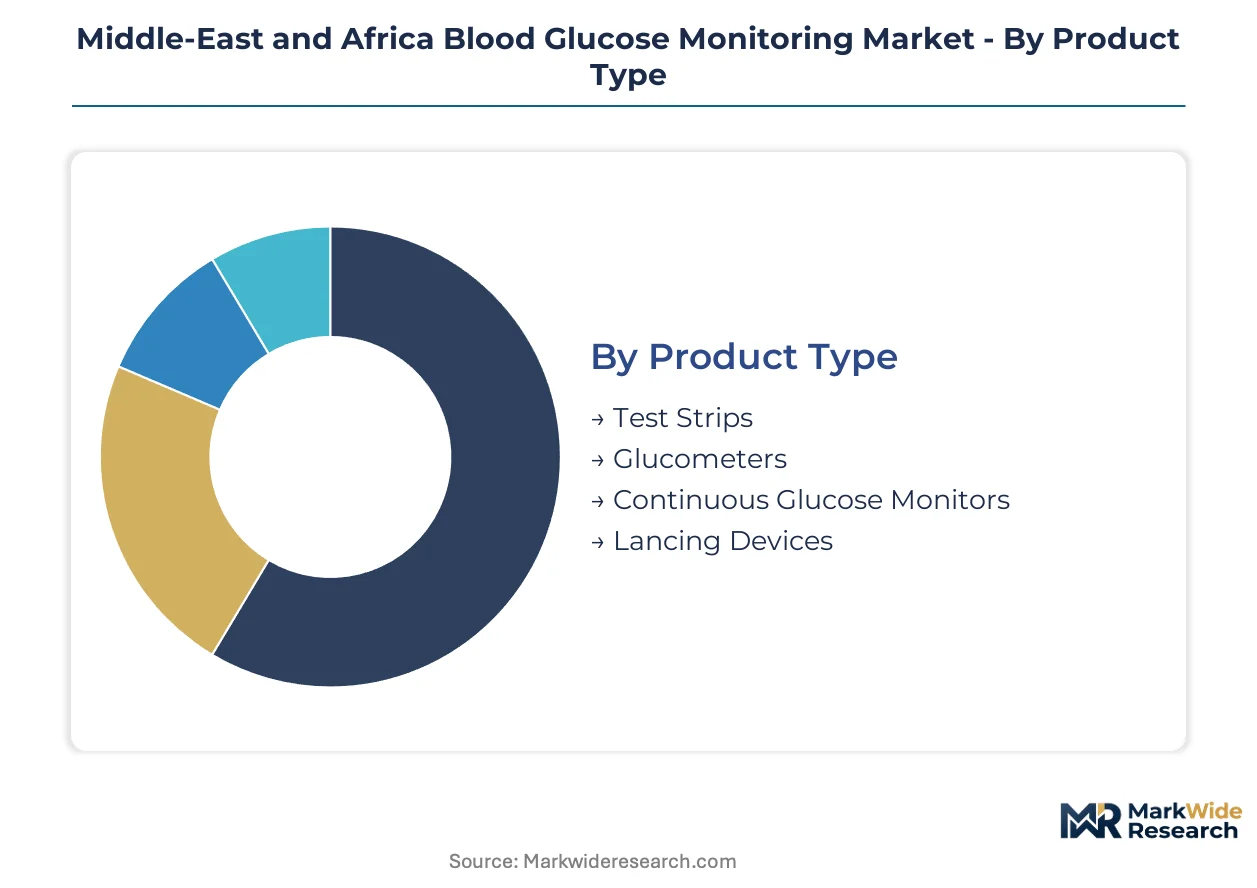
Segmentation in the Middle-East and Africa blood glucose monitoring market reveals distinct procurement patterns across Gulf state hospitals and South African private clinics. Understanding these divides helps manufacturers align product portfolios with diverging technical requirements and reimbursement pathways.
Product Type:
Test strips function as standalone consumables in high-volume screening programs, while continuous glucose monitors embed into integrated chronic disease management platforms.
- Test Strips:Enzymatic reagent strips utilizing glucose oxidase chemistry dominate pharmacy replenishment cycles. South Africa's private diabetes clinic networks drive concentrated volume through centralized purchasing agreements with enzyme cost volatility squeezing manufacturing margins.
- Continuous Glucose Monitors:Factory-calibrated subcutaneous filament sensors transmit real-time interstitial glucose data to smartphone applications. Saudi Arabia's SFDA streamlined registration pathways are accelerating hospital procurement adoption for remote patient monitoring infrastructure.
- Glucometers:Handheld electrochemical meters retain dominant placement in Egypt's pharmacy channel and Nigeria's primary care settings.
- Lancing Devices:Spring-loaded lancet mechanisms accompany test strip bundles in home care starter kits across Gulf Cooperation Council markets.
Volume placements concentrate in test strips; the faster expansion belongs to continuous glucose monitors.
End User:
Cost tier stratification separates institutional buyers with capital budgets from out-of-pocket home care spenders.
- Hospitals:Inpatient glycemic management protocols require connected meter systems with electronic health record interoperability. UAE's MOHAP procurement departments are consolidating supplier contracts around data-integrated platforms that compress vendor margins.
- Home Care:Self-monitoring type 2 diabetes patients purchase devices through pharmacy and online channels. Expanding medical insurance coverage across Saudi Arabia and the UAE is reducing out-of-pocket barriers for continuous glucose monitor adoption.
- Diabetes Clinics:Specialized facilities in South Africa and Kenya drive test strip volume through repeat patient visits.
- Research Laboratories:Clinical validation studies for ISO 15197 certification utilize reference-grade analyzers in Johannesburg and Cairo testing facilities.
Institutional procurement dominates absolute spend; home care segments are climbing the fastest as insurance coverage broadens.
Technology:
Application maturity separates clinically validated electrochemical methods from emerging optical approaches facing reimbursement gaps.
- Electrochemical:Amperometric glucose oxidase sensors deliver milligram-per-deciliter precision in fingerstick and continuous formats. Hospital procurement across Gulf states specifies this chemistry for inpatient glycemic control protocols.
- Enzymatic:Glucose dehydrogenase variants reduce oxygen interference in test strip manufacturing. Supply chain disruptions for biopharmaceutical reagents are elevating input cost volatility for strip producers.
- Optical:Near-infrared and Raman spectroscopy approaches target non-invasive measurement without skin penetration.
- Non-Invasive:Transdermal glucose sensing technologies face SAHPRA and SFDA clinical evidence thresholds that delay market entry.
Electrochemical platforms anchor current volume; non-invasive technologies face the steepest regulatory climb.
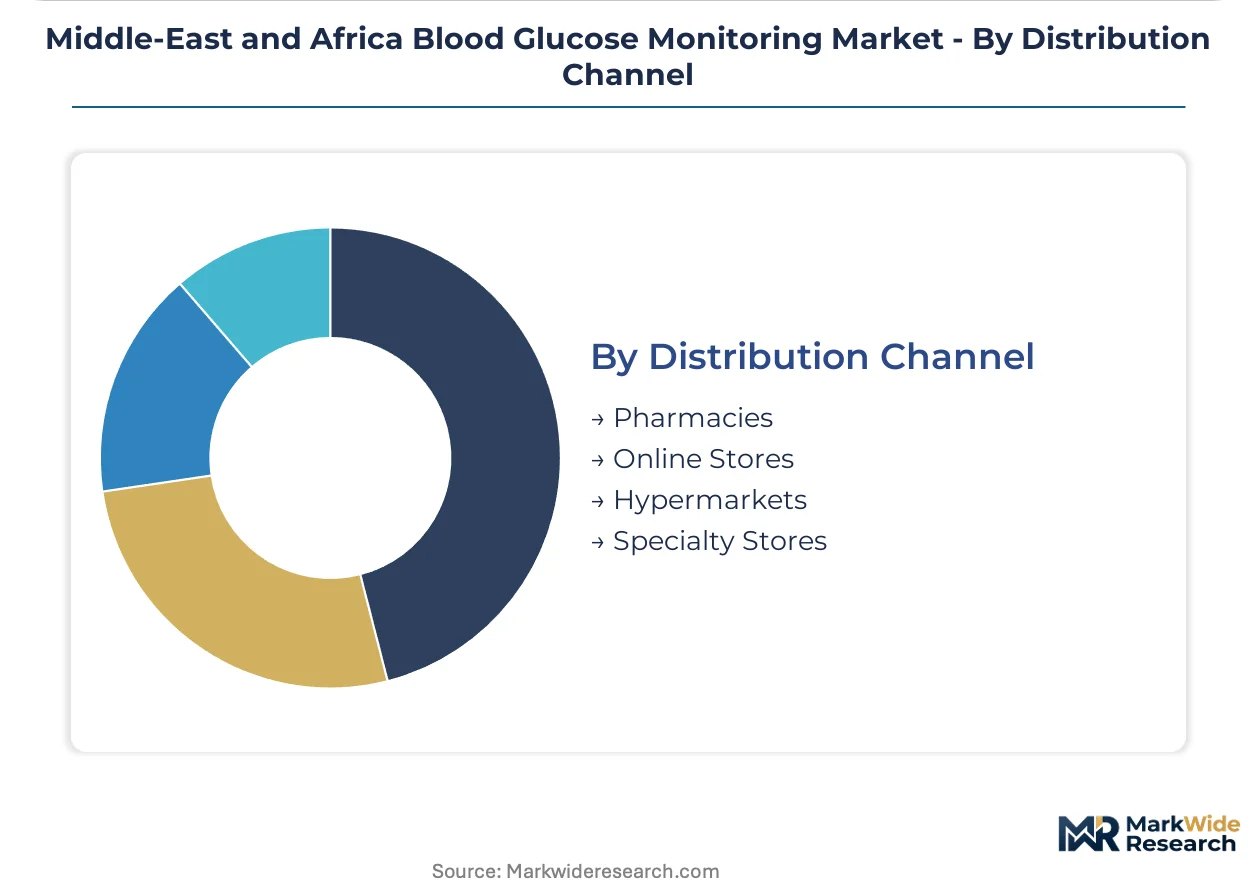
Distribution Channel:
Supply concentration is shifting from fragmented retail toward consolidated e-commerce and hospital procurement portals.
- Pharmacies:Community and hospital-affiliated dispensaries handle test strip replenishment for chronic patients. Independent retail operators in Egypt and Morocco are losing share to clinic-integrated subscription models.
- Online Stores:SFDA-regulated medical device e-commerce platforms in Saudi Arabia capture growing repeat purchase volume from type 2 diabetes patients seeking home delivery convenience.
- Hypermarkets:Mass retail channels in South Africa and Nigeria stock economy-tier glucometer starter kits.
- Specialty Stores:Diabetes-focused medical supply retailers in Dubai and Johannesburg provide device training and insurance claim assistance.
Pharmacy channels retain the largest transaction volume; online platforms are gaining share fastest through subscription replenishment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Dubai Healthcare City anchor medical device distribution networks that concentrate blood glucose monitoring procurement across the Gulf Cooperation Council corridor.
Saudi Arabia
SFDA registration pathways for continuous glucose monitors are compressing time-to-market for manufacturers targeting hospital procurement contracts. The national health insurance scheme is expanding reimbursement categories for self-monitoring devices. Riyadh's King Faisal Specialist Hospital network is consolidating supplier contracts around connected glucose monitoring platforms with electronic health record interoperability.
United Arab Emirates
MOHAP procurement departments in Dubai and Abu Dhabi are prioritizing capital allocation toward remote patient monitoring infrastructure for diabetes management. The Dubai Health Authority mandates medical device quality management standards aligned with ISO 13485 certification requirements. Dubai Healthcare City's cluster of diabetes specialty clinics is driving concentrated test strip volume through centralized purchasing agreements.
South Africa
Private diabetes clinic networks in Johannesburg and Cape Town are sustaining brand loyalty among long-standing test strip suppliers through repeat patient visit cycles. SAHPRA enforces strengthened medical device quality management standards that extend product registration timelines. Johannesburg's captive regional quality assurance operations are accelerating market access for continuous glucose monitor manufacturers seeking ISO 15197 certification.
Egypt
EDA regulatory framework maturation is creating first-mover advantages for manufacturers establishing local distribution partnerships before competitor saturation. Pharmacy channel consolidation is shifting test strip replenishment toward clinic-integrated subscription models. Cairo's clinical validation testing facilities are utilizing reference-grade analyzers for glucose monitor accuracy certification studies.
Nigeria
Primary care settings in Lagos and Abuja retain dominant placement for handheld electrochemical glucometers in outpatient diabetes screening programs. The country's national pharmaceutical regulator maintains parallel quality management standards for imported medical devices. Lagos port customs clearance bottlenecks are elevating inventory holding costs for test strip distributors serving northern state clinic networks.
Middle-East and Africa Blood Glucose Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers in the Middle-East and Africa blood glucose monitoring market. Hospital procurement consolidation in Gulf states favors vendors offering comprehensive platform ecosystems over standalone device manufacturers. Three strategic archetypes dominate: multinational health technology conglomerates with diversified diagnostic portfolios, diabetes-focused pure-play specialists with concentrated sensor expertise, and regional distributors with captive pharmacy channel relationships. Competitive moves center on strategic partnerships with national health insurance schemes and geographic expansion through localized quality assurance operations.
Among Switzerland-based health technology conglomerates, F. Hoffmann-La Roche Ltd exemplifies the diversified diagnostic portfolio archetype through its Accu-Chek ecosystem specialization. Dexcom, a California-based pure-play specialist, occupies a position within the real-time data integration tier for home care segments. Abbott Laboratories represents the multinational platform strategy, leveraging its FreeStyle architecture to anchor hospital contracts across Saudi Arabia and the UAE.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Medtronic Plc |
| Dexcom |
| Johnson & Johnson |
| Ypsomed Holding AG |
| B. Braun SE |
| Nipro Corp |
| GE HealthCare Technologies Inc |
| Others |
Supply & Pricing Matrix
Biomedical engineering talent scarcity across Johannesburg and Dubai compresses algorithm development costs into tiered sensor pricing, widening spreads between factory-calibrated continuous glucose monitors and consumable test strips. Labor-cost differentials between Gulf state headquarters operations and South African quality assurance facilities feed directly into manufacturer margin structures across the region.
Pricing Analysis
Premium pricing attaches to continuous glucose monitors with sub-90-day SFDA registration lead times, while spot inventory of legacy glucometers trades at discounted rates through Egyptian pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels separates data-integrated hospital platforms from clinic-grade bundles and basic home care starter kits. Price differentiation hinges on ISO 15197 certification status and electronic health record interoperability depth. Cost compression in economy test strips is intensifying because glucose oxidase reagent supply volatility squeezes manufacturing margins. Home care segments in Nigeria and Morocco exhibit highest price sensitivity; Saudi hospital procurement departments demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for continuous glucose monitor receivers concentrate refurbishment activity in Dubai Healthcare City distribution hubs, feeding redeployed units into Egyptian and Nigerian clinic networks. Manufacturing of enzymatic test strips draws from glucose oxidase and glucose dehydrogenase biopharmaceutical suppliers anchored in India, Germany, and the United States. Subcutaneous filament sensors for continuous monitors rest on polymer substrate and electrochemical coating inputs from Japanese and South Korean specialty chemical producers. Single-source vulnerability in enzyme reagent supply creates procurement risk for strip manufacturers serving South African diabetes clinic networks. Distribution runs through King Abdullah Economic City medical device clusters into hospital procurement portals, bypassing fragmented independent retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in ISO 13485-certified quality assurance capacity prop pricing power for manufacturers with captive Johannesburg operations, insulating margins against test strip commoditization.
For Market Incumbents: Cement hospital procurement lock-in through Accu-Chek and FreeStyle platform data integration investments that raise switching costs for UAE MOHAP and Saudi SFDA-contracted facilities. Defend against Dexcom's real-time analytics encroachment by embedding algorithm calibration expertise within regional headquarters, deepening backward integration into sensor filament production. Prioritize SAHPRA and EDA regulatory pathway acceleration to compress entrant time-to-market advantages. For New Entrants and Emerging Players: Diabetes clinic network partnerships in Egypt's underpenetrated Nile Delta region offer lowest competitive density for test strip volume capture. Target Kenya's emerging private healthcare corridor where centralized purchasing agreements remain unconsolidated. Pursue direct-to-consumer subscription models through SFDA-regulated e-commerce platforms, bypassing pharmacy channel margin extraction. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play continuous glucose monitor specialists given Gulf Cooperation Council reimbursement expansion catalysts accelerating home care adoption curves. Long-term viability centers on algorithm differentiation and data platform monetization rather than hardware manufacturing scale. Monitor SAHPRA registration timeline compression as inflection signal for regional quality assurance operation valuations.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Acceleration | Compressed approval timelines enable first-mover hospital contract capture in Riyadh and Jeddah networks. |
| ISO 15197 Certification Investment | Accuracy standard compliance unlocks reimbursement eligibility across MOHAP and SAHPRA jurisdictions. |
| Hospital System Partnership | King Faisal Specialist Hospital network consolidation favors vendors with electronic health record interoperability depth. |
| Software Companion Development | Native mobile health platform integration enables direct-to-consumer subscription bypass of pharmacy channels. |
| Reimbursement Strategy | Gulf Cooperation Council national health insurance scheme category expansion reduces out-of-pocket barriers for home care segments. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineering director consultations, and diabetes clinic network administrator surveys underwrites the qualitative findings. Primary fieldwork engaged hospital purchasing managers in Saudi Arabia and the UAE, SAHPRA regulatory affairs specialists, South African private clinic procurement leads, and Egyptian pharmacy chain distribution heads. Secondary validation drew from SFDA medical device registration databases, MOHAP procurement disclosure filings, SAHPRA ISO 13485 certification records, and GPO contract repositories. Bottom-up sensor shipment estimates and top-down health system expenditure analysis were cross-referenced for triangulation.
Rate-of-change decomposition across the analysis window separated volume drivers from price-mix effects in continuous glucose monitor versus test strip category evolution. Segmentation modeling incorporated product type, end user archetype, electrochemical versus optical technology pathways, and distribution channel concentration. CAGRs were derived from installed base growth rates and replacement cycle assumptions calibrated to regional insurance reimbursement expansion trajectories. Forecast inputs included SFDA registration pipeline velocity, enzyme reagent cost indices, and hospital procurement consolidation momentum.
Caveats apply where SAHPRA regulatory tightening or Gulf state reimbursement policy reversals could materially shift the outlook beyond modeled sensitivity bands. Forecasts reflect assumptions regarding sensor accuracy standard harmonization and remote patient monitoring infrastructure capital allocation continuity. Practitioners should monitor EDA framework maturation pace and Nigerian customs clearance efficiency for early signals of supply chain disruption or market access acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Germany Continuous Glucose Monitoring Market