
 PPG Biosensors Market | 2026-2036
PPG Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
PPG Biosensors Market Intelligence
Silicon photodiodes is decoupling from legacy germanium substrates in PPG sensor fabrication, cutting unit costs while improving signal-to-noise ratios at green and infrared wavelengths. Apple Inc. leverages vertical integration across sensor design and watchOS algorithms to dominate consumer-grade heart rate monitoring. Masimo Corporation specializes in hospital-grade pulse oximetry, sustaining premium positioning through FDA-cleared medical claims that consumer rivals cannot match. Samsung Electronics Co., Ltd. competes by bundling PPG modules across Galaxy Watch and smartphone ecosystems, extending reach into sleep tracking and stress management applications.
Photoplethysmography biosensors employ light-emitting diodes and photodetectors to measure blood volume changes in peripheral vasculature, typically operating at wavelengths between 510 nm and 940 nm for tissue penetration optimization. These devices serve continuous cardiovascular monitoring, sleep architecture analysis, and hypoxemia detection across clinical and consumer settings. Wearable Devices anchor the product mix, with Medical Grade Sensors capturing disproportionate margin pools due to regulatory barriers and clinical validation costs. Optical Sensors lead the technology stack, though Hybrid Sensors combining PPG with accelerometry and temperature sensing represent the fastest-expanding configuration for multi-parameter health monitoring.
FDA 510(k) clearance requirements and EU MDR Class IIa designation shape product development timelines and commercial access for PPG biosensor vendors seeking clinical claims. Japan's PMDA and South Korea's MFDS impose additional electromagnetic compatibility and biocompatibility testing that filters out lower-tier suppliers. China's NMPA has tightened software-as-a-medical-device oversight for PPG algorithms, complicating market entry for foreign wearable brands. Stakeholders must monitor evolving software validation standards and reimbursement decisions for remote patient monitoring codes to determine whether clinical-grade PPG applications justify the regulatory investment over consumer wellness positioning.
Market Dynamics
Silicon photodiode substrates are displacing legacy germanium in PPG sensor fabrication, compressing unit economics while tightening FDA 510(k) validation windows for Class IIa medical device claims.
Growth Catalysts
- EU MDR Class IIa pathway:Medical-grade pulse oximetry vendors leverage stricter clinical validation requirements to build defensible margin pools against consumer-grade competitors.
- Continuous cardiovascular monitoring:Hospital procurement systems in Germany and South Korea are expanding remote patient monitoring codes to reimburse PPG-based hypoxemia detection.
- Multi-parameter health sensing:Hybrid sensor configurations combining PPG with accelerometry and temperature sensing are capturing sleep architecture analysis contracts.
Market Restraints
- Electromagnetic compatibility testing:Japan's PMDA and South Korea's MFDS impose biocompatibility requirements that filter out lower-tier optical module suppliers.
- Software-as-a-medical-device oversight:China's NMPA has tightened algorithm validation standards, complicating market entry for foreign wearable brands seeking clinical claims.
- Signal-to-noise ratio limitations:Green wavelength PPG modules struggle with motion artifact rejection in high-activity consumer applications.
Strategic Opportunities
- Stress management applications:Samsung Electronics extends PPG module deployment across smartphone ecosystems beyond wearable form factors.
- Hospital-grade pulse oximetry:FDA-cleared medical claims create premium positioning that consumer rivals cannot replicate through wellness positioning alone.
- SpO2 tracking integration:Apple's vertical integration across sensor design and watchOS algorithms dominates consumer-grade heart rate monitoring procurement.
Industry Challenges
- Optical engineering talent scarcity:PPG algorithm development requires rare combinations of biomedical signal processing and semiconductor fabrication expertise.
- 510(k) clearance timelines:FDA software validation standards for PPG-based medical claims extend product development cycles by 18-24 months.
- Legacy system integration:Hospital IT infrastructure requires HL7 FHIR compatibility that consumer-grade sensor vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PPG Biosensors Market |
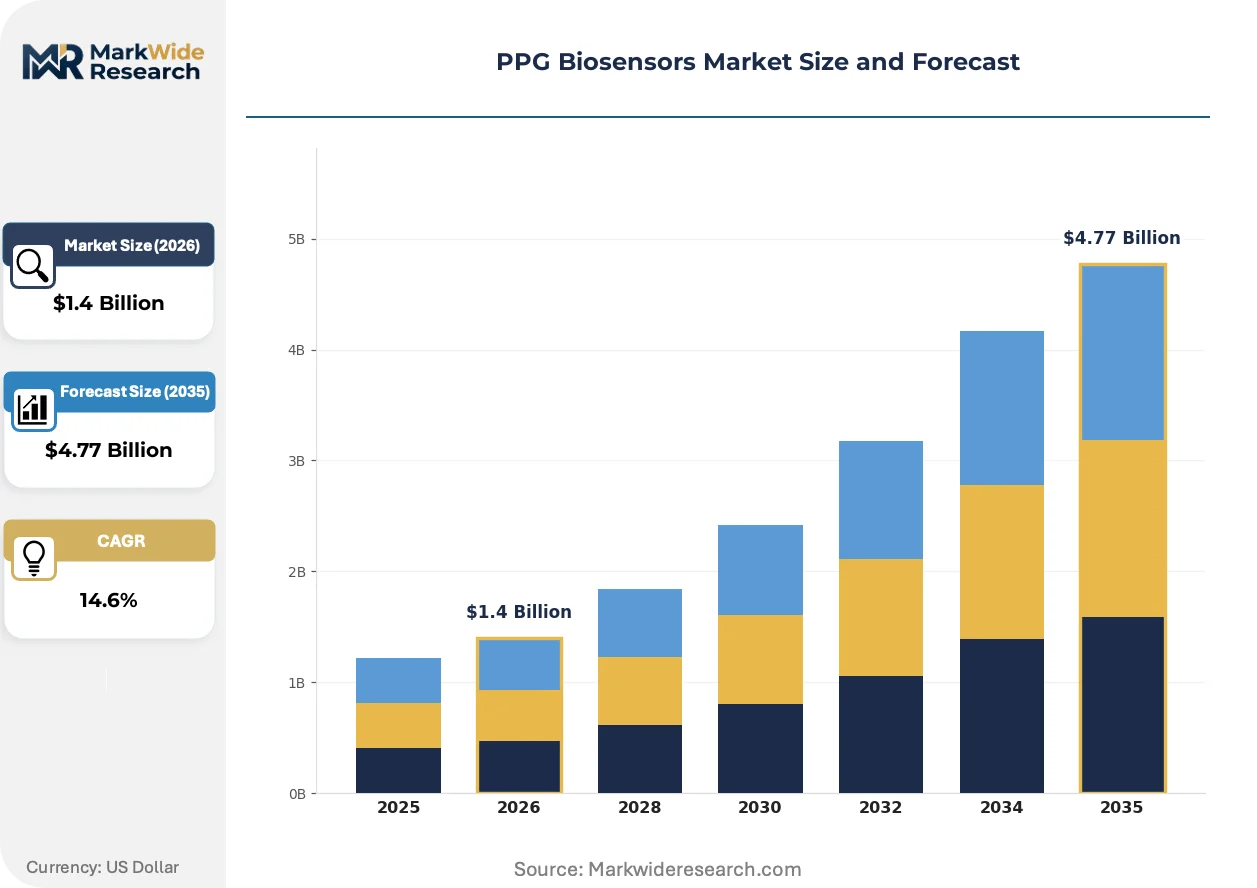
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smartphone Applications, Health Monitors, Medical Grade Sensors Technology: Optical Sensors, Microelectronic Sensors, Thermal Sensors, Hybrid Sensors End User: Hospitals, Fitness Enthusiasts, Research Laboratories, Home Users Application: Heart Rate Monitoring, Sleep Tracking, Stress Management, Blood Oxygen Level Measurement |
| Companies Covered | Garmin Ltd., Medtronic plc, Apple Inc., Omron Corporation, Philips Healthcare, Samsung Electronics Co., Ltd., Masimo Corporation, Xiaomi Corporation, Fitbit LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PPG Biosensors Market Strategic Shifts & Innovations
Optical sensing architectures are bifurcating between medical-grade precision and consumer-scale volume, with regulatory classification determining viable commercialization pathways.
Multi-wavelength PPG arrays operating between 510 nm and 940 nm are converging with machine learning-based motion artifact compensation. Wearable device manufacturers in the United States are adopting these configurations for FDA 510(k) submissions. The technology is converging with clinical validation requirements that compress development timelines for vendors seeking medical claims over wellness positioning.
China's NMPA has implemented algorithm transparency requirements for software-as-a-medical-device PPG applications. Foreign wearable brands must submit source code audits and clinical trial data from domestic patient populations. Vendors targeting hospital procurement systems are responding by establishing joint ventures with local optical module fabricators.
Hospital procurement committees now require FDA-cleared or EU MDR Class IIa certification for pulse oximetry devices used in acute care settings. This certification-driven preference shift displaces consumer-grade sensors from clinical workflows. The pattern is most visible in German hospital networks, where reimbursement codes for remote patient monitoring explicitly exclude wellness-grade hardware.
PPG Biosensors Market Segmentation
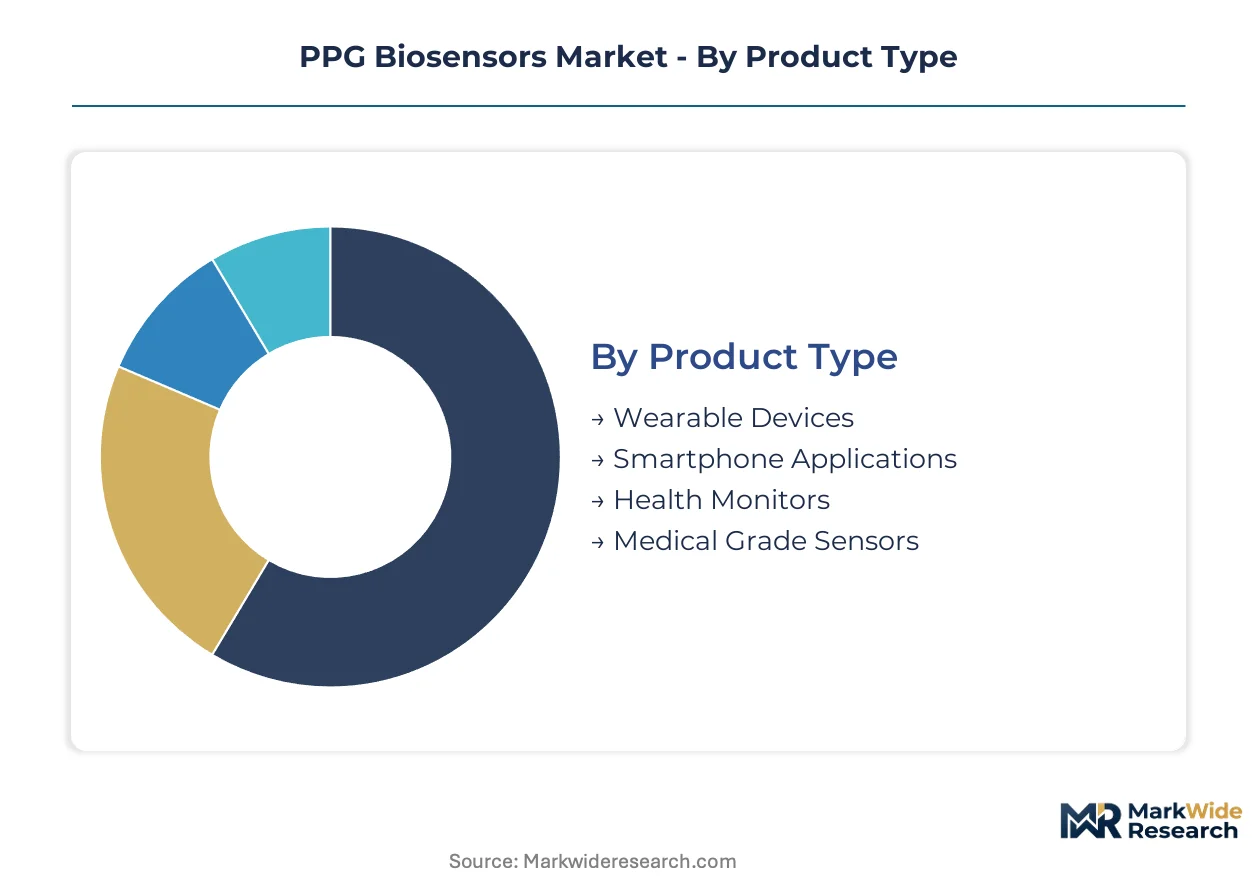
PPG biosensor vendors face divergent certification burdens across segments. FDA 510(k) pathways and EU MDR Class IIa designations fragment product development timelines, forcing strategic choices between clinical claims and wellness positioning.
Product Type:
FDA 510(k) clearance requirements and EU MDR Class IIa certification separate medical-grade claims from consumer wellness positioning across these segments.
- Wearable Devices:Wrist-worn and ear-worn form factors integrate optical modules for continuous heart rate and SpO2 tracking. Demand concentrates in the United States and South Korea where Apple and Samsung drive procurement volumes for consumer wellness applications.
- Medical Grade Sensors:Hospital-grade pulse oximetry modules require FDA-cleared medical claims that consumer rivals cannot match. German hospital networks and South Korean procurement systems explicitly exclude wellness-grade hardware from reimbursement codes for remote patient monitoring.
- Health Monitors:Dedicated fingertip and bedside devices for clinical and home diagnostic use.
- Smartphone Applications:Camera-based PPG implementations leveraging device-integrated photodiodes.
Leading the category by volume: Wearable Devices. Growing fastest: Medical Grade Sensors.
Technology:
Cost tiers stratify sharply between commodity optical modules and multi-sensor fusion architectures requiring rare engineering talent.
- Optical Sensors:LED-photodiode pairs operating between 510 nm and 940 nm dominate unit economics. Silicon photodiode substrates are displacing legacy germanium fabrication, compressing costs while tightening signal-to-noise performance for green and infrared wavelengths.
- Hybrid Sensors:Configurations combining PPG with accelerometry and temperature sensing capture sleep architecture analysis contracts. These architectures command premium positioning in the United States where FDA 510(k) submissions require multi-parameter validation datasets.
- Microelectronic Sensors:CMOS-integrated photodetector arrays for miniaturized form factors.
- Thermal Sensors:Thermopile-based peripheral perfusion monitoring adjuncts.
Dominating unit volume: Optical Sensors. Expanding most quickly: Hybrid Sensors.
End User:
Customer type determines pricing power, with hospital procurement systems demanding HL7 FHIR compatibility that consumer-grade vendors lack.
- Hospitals:Acute care settings require FDA-cleared or EU MDR Class IIa certification for pulse oximetry devices. German hospital procurement committees explicitly mandate medical-grade certification, displacing consumer sensors from clinical workflows.
- Fitness Enthusiasts:Consumer wellness tracking drives volume in wearable form factors. South Korea's MFDS and Japan's PMDA impose electromagnetic compatibility testing that filters lower-tier suppliers from this segment.
- Home Users:Over-the-counter health monitoring for chronic condition management.
- Research Laboratories:Validated optical modules for clinical trial endpoints and algorithm development.
Capturing highest absolute volume: Fitness Enthusiasts. Generating steepest margin expansion: Hospitals.
Application:
Application maturity varies widely, with established heart rate monitoring contrasting against emerging stress management use cases lacking standardized validation protocols.
- Heart Rate Monitoring:Green wavelength PPG modules serve continuous cardiovascular tracking across consumer and clinical settings. Apple's vertical integration across sensor design and watchOS algorithms dominates procurement for this application in the United States.
- Blood Oxygen Level Measurement:Red and infrared wavelength configurations enable SpO2 quantification. Masimo Corporation sustains premium positioning through FDA-cleared medical claims that consumer rivals cannot replicate through wellness positioning alone.
- Sleep Tracking:Multi-parameter sensing for sleep architecture analysis combining PPG with accelerometry.
- Stress Management:Heart rate variability-derived metrics for wellness applications without standardized clinical validation.
Highest deployment maturity: Heart Rate Monitoring. Gaining share fastest: Blood Oxygen Level Measurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for PPG biosensors concentrates in the United States, Germany, and South Korea, where consumer electronics procurement and hospital reimbursement systems drive volume. Regulatory classification determines market access, with FDA 510(k) and EU MDR pathways fragmenting commercialization timelines. Silicon photodiode fabrication clusters in East Asia supply optical modules to branded device manufacturers worldwide.
United States
Wearable device procurement from Apple and Garmin anchors domestic volume for consumer-grade heart rate monitoring. FDA 510(k) clearance requirements compress development timelines for vendors seeking medical claims over wellness positioning. The San Francisco Bay Area and Greater Boston host optical engineering talent pools developing multi-wavelength PPG arrays for clinical validation.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia mandate EU MDR Class IIa certification for pulse oximetry devices used in acute care. Reimbursement codes for remote patient monitoring explicitly exclude wellness-grade hardware, displacing consumer sensors from clinical workflows. Berlin-Brandenburg hosts regulatory consulting clusters specializing in medical device software validation.
South Korea
Samsung Electronics bundles PPG modules across Galaxy Watch and smartphone ecosystems, extending reach into sleep tracking applications. MFDS electromagnetic compatibility and biocompatibility testing filters lower-tier optical module suppliers from market entry. The Seoul Capital Area concentrates semiconductor fabrication capacity for silicon photodiode substrates displacing legacy germanium.
China
NMPA algorithm transparency requirements for software-as-a-medical-device PPG applications complicate market entry for foreign wearable brands. Domestic patient population clinical trial data mandates force joint ventures with local optical module fabricators. The Yangtze River Delta and Pearl River Delta host CMOS-integrated photodetector manufacturing clusters serving cost-sensitive consumer segments.
Japan
PMDA electromagnetic compatibility testing imposes barriers that filter out lower-tier suppliers from fitness enthusiast segments. METI standards for biocompatibility extend validation timelines for foreign vendors seeking clinical claims. The Kanto region around Tokyo anchors demand for multi-parameter health sensing combining PPG with accelerometry and temperature monitoring.
PPG Biosensors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with medical-grade certification creating defensible margin pools against consumer wellness positioning. The vendor base organizes around three strategic archetypes: vertically integrated consumer electronics giants, hospital-grade pulse oximetry specialists, and optical module contract manufacturers. Competitive dynamics center on FDA 510(k) clearance timelines and EU MDR Class IIa certification investments that extend product development cycles by 18-24 months.
Among vertically integrated consumer electronics groups, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions exemplifying the wellness-to-clinical spectrum, while Masimo Corporation represents the hospital-grade pulse oximetry archetype through FDA-cleared medical claims that consumer rivals cannot replicate. Garmin Ltd. and Xiaomi Corporation sit within the scale-driven volume tier targeting fitness enthusiast segments with cost-optimized optical module configurations.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Medtronic plc |
| Apple Inc. |
| Omron Corporation |
| Philips Healthcare |
| Samsung Electronics Co., Ltd. |
| Masimo Corporation |
| Xiaomi Corporation |
| Fitbit LLC |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees in Germany mandating EU MDR Class IIa certification for pulse oximetry devices are compressing margins for uncertified optical module suppliers while rewarding validated vendors with pricing power in acute care workflows.
Pricing Analysis
Volume concentrates in consumer wellness tiers while margin pools accrue to medical-grade certification holders. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital systems from fitness enthusiast wearables and unbranded commodity modules. Pricing pressure stems from silicon photodiode substrate cost compression displacing legacy germanium fabrication. Fitness enthusiast segments exhibit highest price sensitivity; hospital procurement systems demonstrate lowest sensitivity due to reimbursement code dependencies.
Supply Chain Analysis
Single-source vulnerability sits with East Asian silicon photodiode foundries concentrated in South Korea, Taiwan, and mainland China. Raw material dependencies include gallium arsenide LED emitters, indium phosphide photodetectors, and biocompatible encapsulation polymers. Supply chain risk centers on PMDA and MFDS electromagnetic compatibility testing bottlenecks filtering lower-tier suppliers. Distribution runs through branded device OEMs controlling firmware-locked optical module procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory certification barriers that filter out optical module suppliers lacking FDA 510(k) or EU MDR validation capabilities.
For Market Incumbents: Lock in hospital procurement relationships through HL7 FHIR compatibility investments that consumer-grade rivals cannot replicate. Deepen backward integration into silicon photodiode fabrication to secure supply against East Asian foundry concentration. Prioritize multi-parameter sensor fusion R&D capturing sleep architecture analysis contracts before hybrid configurations commoditize. For New Entrants and Emerging Players: EU MDR Class IIa pathway in Germany opens a window for specialized pulse oximetry vendors targeting Bavarian and North Rhine-Westphalia hospital networks excluded from reimbursement codes. Stress management applications lack standardized clinical validation protocols, creating penetrable white space. Pursue joint venture structures with Yangtze River Delta optical fabricators to satisfy NMPA algorithm transparency requirements. For Investors and Strategic Acquirers: The window for entry favors biomedical signal processing specialists with rare combinations of semiconductor fabrication and clinical validation expertise. Target acquisition archetypes include FDA-cleared medical claims holders facing capital constraints for EU MDR expansion. Watch for remote patient monitoring reimbursement code expansions as inflection signal for clinical-grade PPG demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears pathway for hospital procurement systems excluding wellness-grade hardware from acute care workflows. |
| EU MDR Class IIa Certification | Unlocks German reimbursement codes for remote patient monitoring explicitly mandating medical-grade pulse oximetry. |
| Hospital System Partnership | Secures HL7 FHIR integration requirements that consumer-grade sensor vendors lack for clinical IT infrastructure. |
| Software Companion Development | Addresses NMPA algorithm transparency mandates complicating market entry for foreign wearable brands. |
| Reimbursement Strategy | Aligns product positioning with expanding remote patient monitoring codes in South Korean and German systems. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and optical module fabrication executives combined with secondary validation from FDA 510(k) filings, EU MDR submission records, and MFDS electromagnetic compatibility test reports. Bottom-up demand modeling triangulates against top-down market sizing across wearable device shipments and medical-grade sensor unit economics.
Rate-of-change decomposition isolates volume drivers from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end user category, and application maturity. CAGRs derive from weighted average growth assumptions calibrated to procurement pattern shifts and regulatory timeline compressions. Industry-specific forecast inputs incorporate silicon photodiode substrate adoption curves and FDA software validation standard evolution.
The model assumes a particular technology adoption path; alternative pathways for hybrid sensor fusion architectures would alter the outlook. Forecasts reflect assumptions about reimbursement code expansion timelines and electromagnetic compatibility testing harmonization that regulatory bodies may revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peri-Implantitis Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Drainage Catheters Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Interlaminar Device Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Spinal Implant Market