
 India Self-Monitoring Blood Glucose Devices Market | 2026-2036
India Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Self-Monitoring Blood Glucose Devices Market Insights
Leasing of glucose monitoring equipment to diagnostic chains and pharmacy networks is narrowing the capital barrier for mid-tier distributors. Abbott leverages its strip manufacturing footprint to sustain pricing power across retail channels. F. Hoffmann-La Roche Ltd anchors premium meter sales through hospital procurement contracts. Morepen Laboratories competes on volume in the strip-based segment via pharmacy tie-ups.
Self-monitoring blood glucose devices comprise electrochemical biosensors, optical reflectance modules, and enzymatic test strips engineered to quantify capillary glucose concentration within seconds. These systems enable real-time metabolic tracking for insulin dosing decisions outside clinical settings. Strip-based products dominate unit sales due to low per-test cost and established reimbursement pathways. Continuous glucose monitoring is expanding fastest among insulin-dependent users seeking trend data. Wireless-enabled meters are capturing margin pools through subscription-linked cloud analytics.
CDSCO mandates post-market surveillance for all glucose monitoring devices sold in India, while BIS certification governs electrical safety and electromagnetic compatibility standards. The PLI scheme for medical electronics subsidizes domestic manufacturing of precision biosensors, redirecting procurement toward local assembly. Stakeholders must monitor how state-level tendering for Ayushman Bharat beneficiaries reshapes volume allocation between hospital and homecare channels.
Market Dynamics
CDSCO's tightened quality norms for point-of-care diagnostics are compressing product approval timelines while elevating compliance costs for strip-based glucose monitoring systems across Maharashtra and Gujarat pharmacy networks.
Growth Catalysts
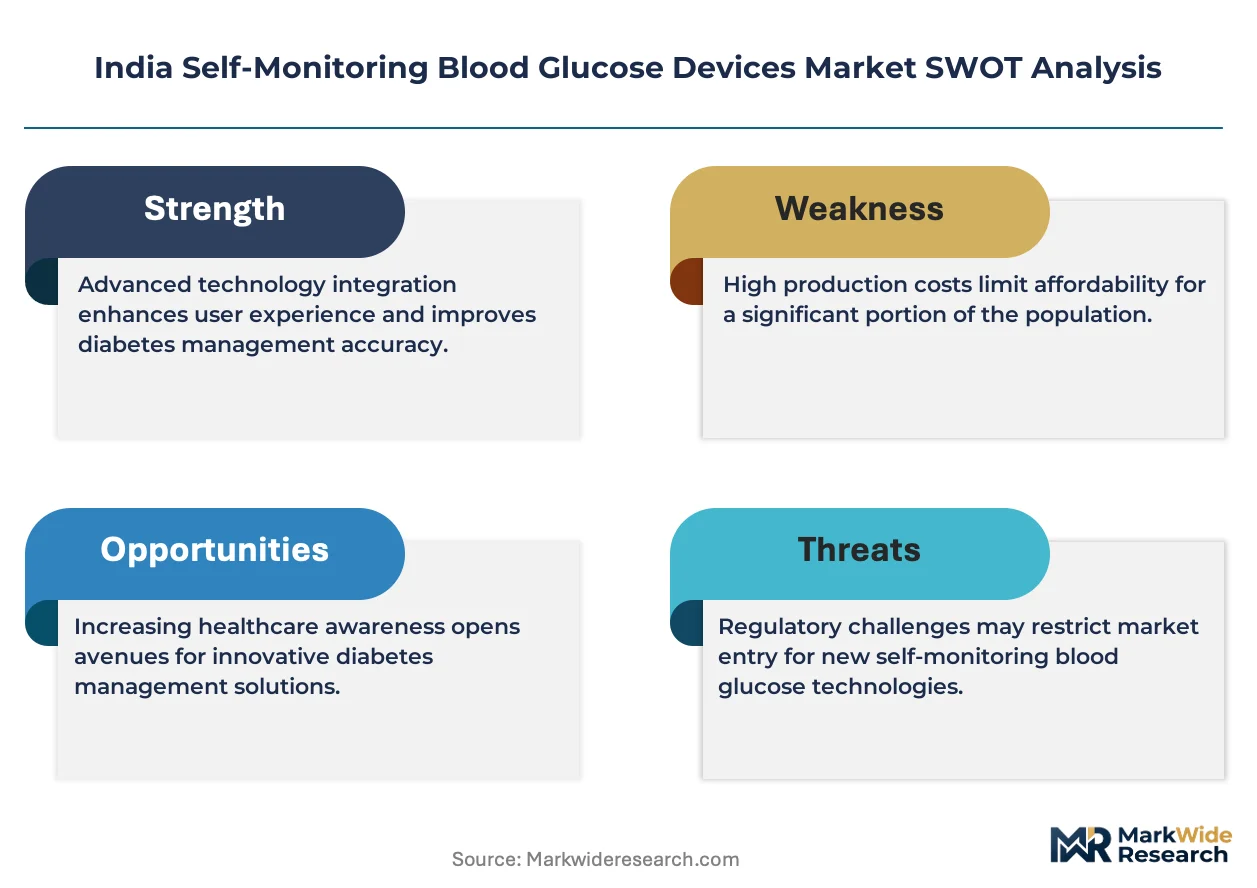
- PLI scheme subsidies:The medical electronics production-linked incentive scheme subsidizes domestic precision biosensor assembly, redirecting hospital procurement toward locally manufactured meters.
- Ayushman Bharat state tenders:State-level tendering for beneficiary coverage is reallocating volume between hospital and homecare channels, expanding addressable patient populations.
- Homecare adoption acceleration:Type 2 diabetes patients across tier-1 cities are migrating from clinic-based testing to self-monitoring protocols, driving strip consumption through pharmacy networks.
Market Restraints
- Enzymatic strip input volatility:Glucose oxidase and mediator chemical costs fluctuate with biotech feedstock markets, squeezing margins for strip manufacturers.
- Electrochemical biosensor technical ceiling:Capillary blood sample size requirements limit testing frequency for pediatric and geriatric patients with compromised circulation.
- CDSCO post-market surveillance burden:Mandatory adverse event reporting and periodic safety updates impose recurring compliance overhead on device importers.
Strategic Opportunities
- Continuous glucose monitoring convergence:Integration of optical reflectance modules with wireless-enabled meters is hybridizing real-time trend analytics for insulin-dependent users.
- Diagnostic chain leasing models:Capital-light equipment rental programs are lowering entry barriers for mid-tier distributors serving tier-2 cities.
- Cloud analytics subscription bundling:Wireless meters paired with glucose data platforms capture recurring revenue streams from pharmacy-loyal patient cohorts.
Industry Challenges
- BIS electromagnetic compatibility certification:Electrical safety testing timelines for imported meters create inventory gaps during peak demand periods.
- Legacy clinic workflow integration:Hospital information systems require custom API development to ingest homecare-generated glucose data, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Self-Monitoring Blood Glucose Devices Market |
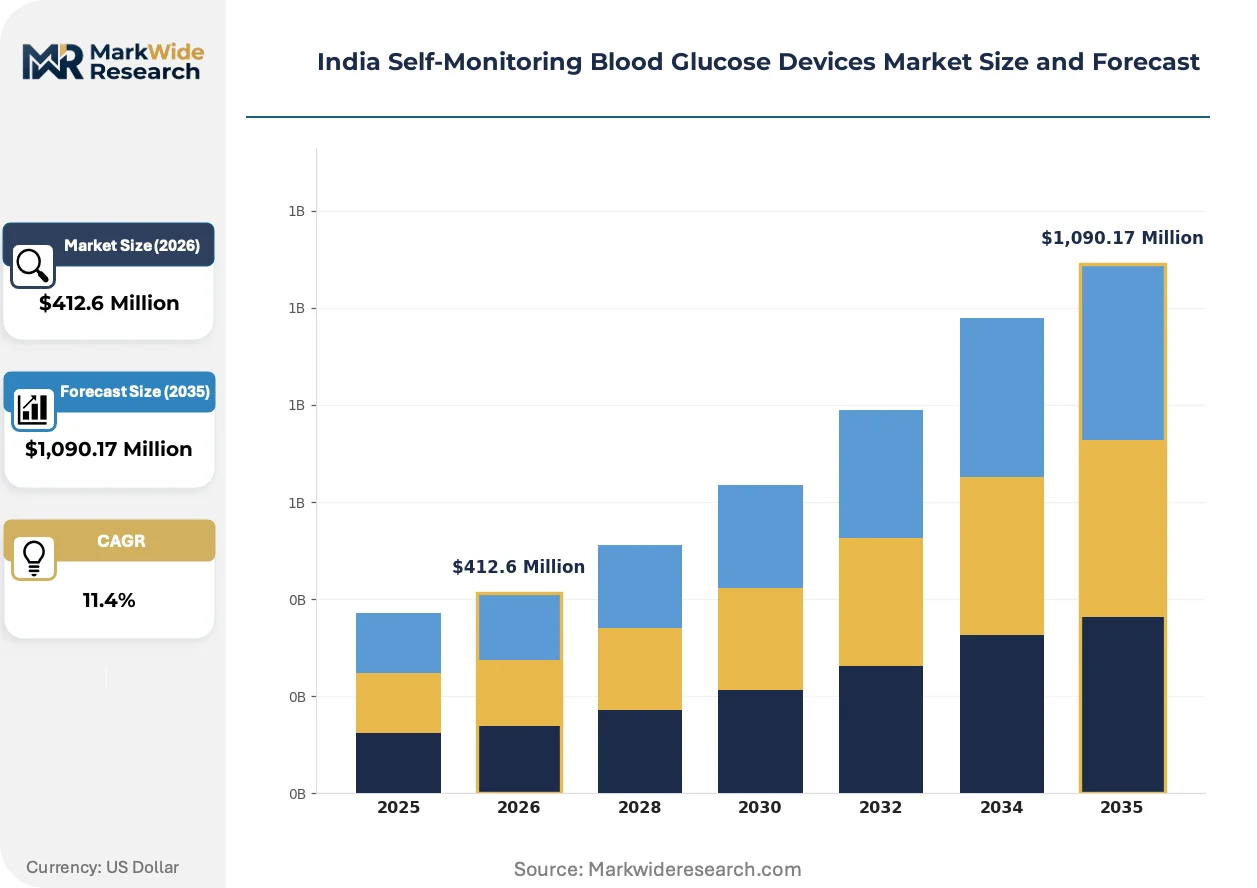
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip-based, Continuous Glucose Monitoring, Meter-based, Smartphone Integrated Technology: Electrochemical, Optical, Enzymatic, Wireless End User: Homecare, Hospitals, Clinics, Pharmacies Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Medtronic plc, Ascensia Diabetes Care Holdings AG, Arkray Inc., LifeScan, Morepen Laboratories, Johnson & Johnson Ltd., B. Braun Medical (India) Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Wireless connectivity and enzymatic sensing architectures are converging to reshape how capillary glucose data flows from patient to provider across India's fragmented diagnostic infrastructure.
Optical reflectance technology is hybridizing with electrochemical biosensor platforms to enable dual-mode glucose quantification. Insulin-dependent patients in Mumbai and Delhi diagnostic chains are adopting these hybrid systems at accelerating rates. The convergence is compressing price premiums between basic strip meters and continuous monitoring patches.
CDSCO's 2023 point-of-care diagnostic quality circular mandates enhanced accuracy validation for all new glucose device registrations. Manufacturers must submit expanded clinical performance data, extending approval cycles by four to six months. Strip-based product categories face the steepest documentation burden as volume leaders.
Pharmacy networks are consolidating procurement authority previously dispersed across individual store owners. Apollo and MedPlus chains in Karnataka and Telangana now negotiate centralized meter and strip contracts, displacing distributor-mediated purchasing. This concentration is visible most acutely in Bengaluru's organized retail corridor.
India Self-Monitoring Blood Glucose Devices Market Segmentation
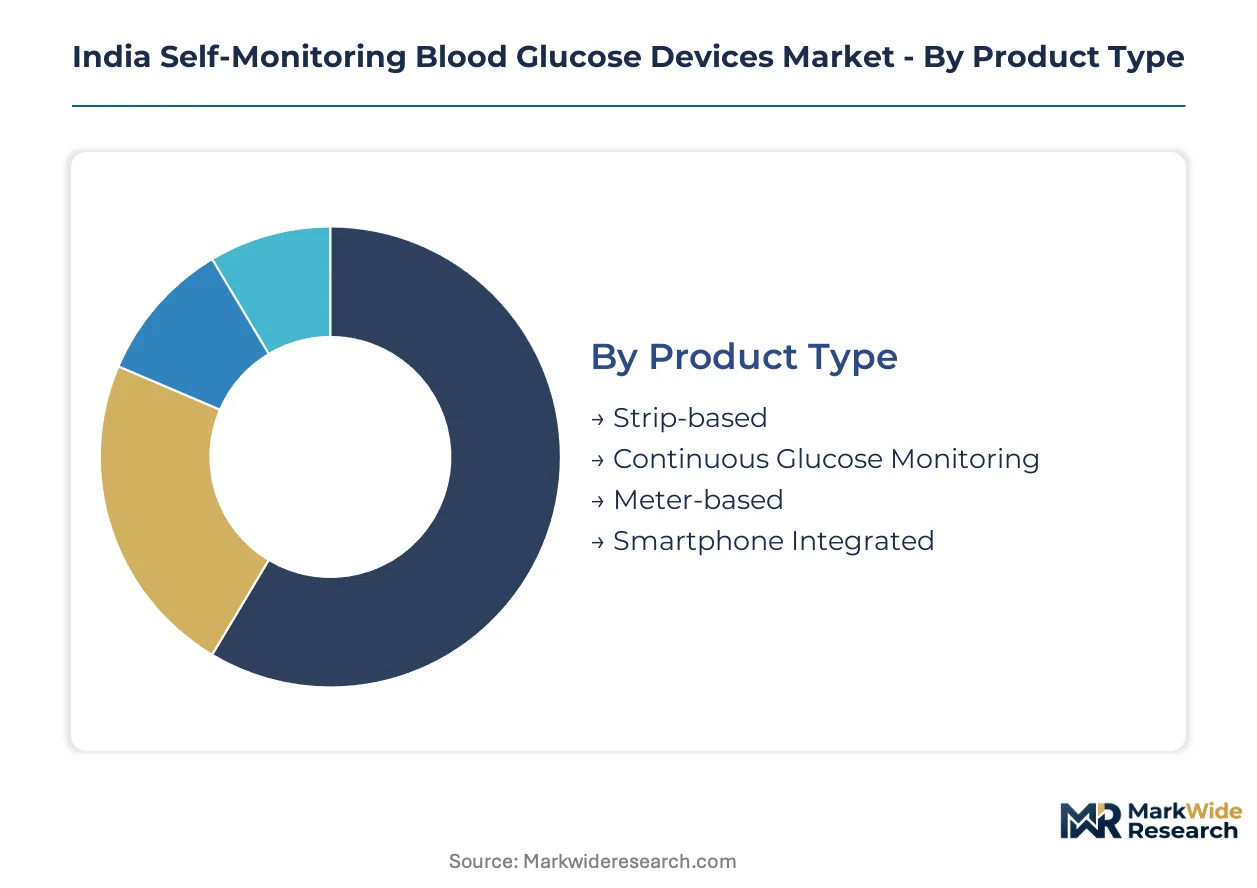
Device segmentation in India's glucose monitoring market determines calibration protocols, consumable replenishment cycles, and regulatory filing pathways. CDSCO approval requirements vary sharply across product architectures, creating divergent commercialization timelines for manufacturers.
Product Type:
After-sales calibration service intensity varies dramatically across device architectures, with continuous systems demanding remote technical support while strip-based products require only consumable replenishment.
- Strip-based:Electrochemical biosensors paired with disposable enzymatic test strips dominate unit economics through low per-test pricing. Maharashtra and Gujarat pharmacy networks drive volume concentration as homecare adoption accelerates among type 2 diabetes patients managing insulin dosing independently.
- Continuous Glucose Monitoring:Optical reflectance modules with subcutaneous sensors deliver real-time trend data for insulin-dependent users. Mumbai and Delhi diagnostic chains are expanding fastest here as patients seek reduced finger-prick frequency and cloud-integrated analytics.
- Meter-based:Handheld electrochemical readers with digital displays serve price-sensitive patients through retail pharmacy channels.
- Smartphone Integrated:Wireless-enabled meters transmitting data to mobile applications capture subscription-linked recurring revenue from pharmacy-loyal cohorts.
Strip-based holds the largest share; momentum sits with continuous glucose monitoring.
Technology:
Cost tier stratification separates premium wireless architectures from economy enzymatic platforms, with electrochemical systems occupying the mid-market sweet spot for reimbursement alignment.
- Electrochemical:Amperometric biosensors measuring glucose oxidase reactions deliver precision at moderate cost. BIS certification requirements for electrical safety govern manufacturing standards across domestic assembly operations.
- Optical:Near-infrared spectroscopy and colorimetric reflectance enable non-invasive measurement attempts. Tier-1 city hospitals are piloting these systems for pediatric populations where capillary sampling proves difficult.
- Enzymatic:Glucose oxidase and mediator chemistry on polymer substrates constitute the foundational strip technology. Input cost volatility for biotech feedstocks squeezes manufacturer margins unpredictably.
- Wireless:Bluetooth and cellular connectivity modules enable cloud data transmission. PLI scheme subsidies for medical electronics are redirecting procurement toward locally assembled wireless meters.
Electrochemical captures dominant volume; wireless is climbing the fastest as subscription models proliferate.
End User:
Application context dictates device specification, with homecare settings prioritizing portability while hospital procurement emphasizes EMR integration and multi-patient workflow efficiency.
- Homecare:Individual patients managing type 2 diabetes through self-monitoring protocols. Bengaluru's organized retail corridor and expanding pharmacy networks are accelerating strip consumption through centralized procurement contracts.
- Hospitals:Inpatient glycemic management and pre-surgical screening drive meter procurement. Ayushman Bharat state tenders are reallocating volume between hospital and homecare channels, expanding addressable beneficiary populations.
- Clinics:Physician office-based point-of-care testing requires rapid turnaround with moderate accuracy. CDSCO's tightened quality norms are compressing approval timelines while elevating compliance documentation burdens.
- Pharmacies:Over-the-counter sales and diagnostic service counters serve walk-in patients. Leasing models for glucose monitoring equipment are narrowing capital barriers for mid-tier distributors.
Homecare holds the largest share; momentum sits with hospitals as tender volumes expand.
Distribution Channel:
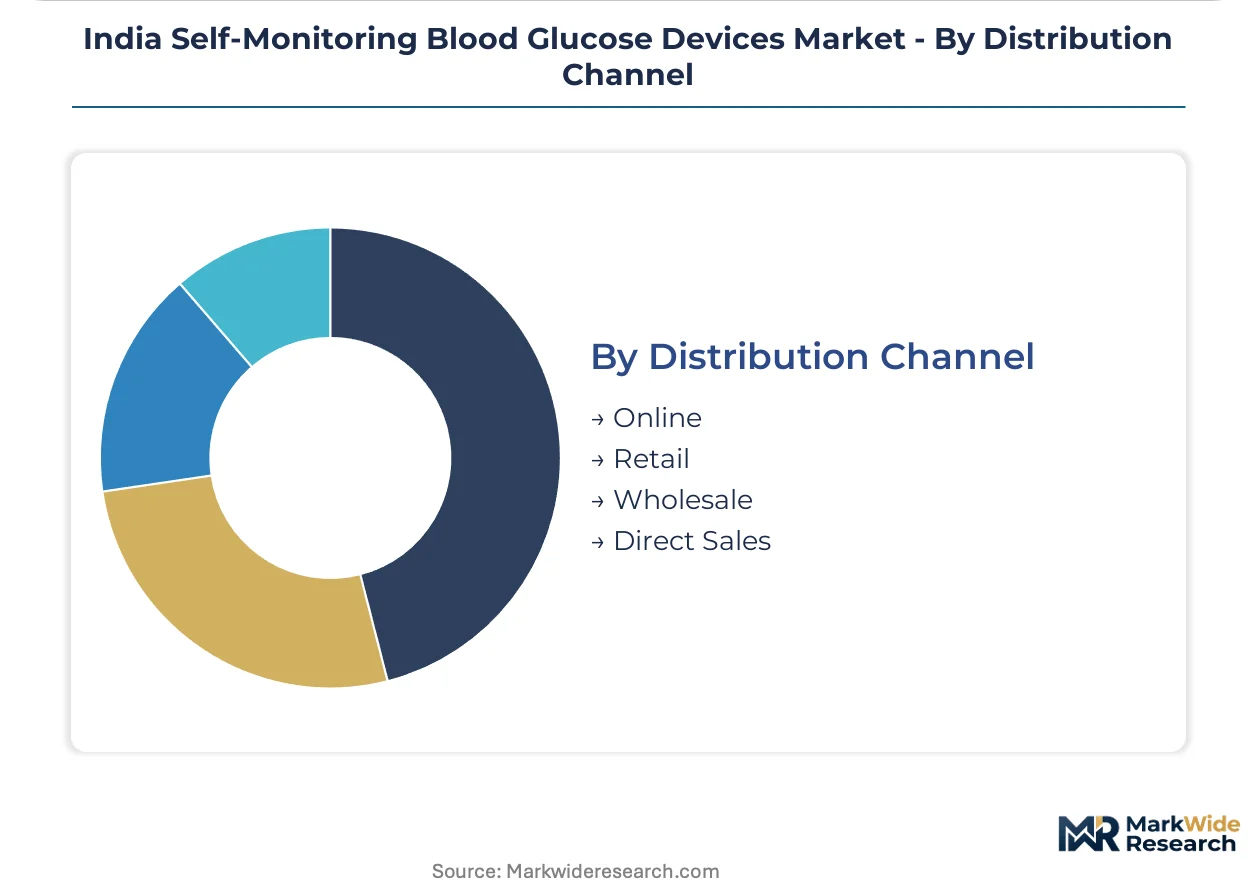
Customer type determines channel preference, with chronic patients favoring pharmacy loyalty programs while newly diagnosed users explore online comparison shopping.
- Online:E-commerce platforms and direct-to-consumer portals enable price transparency and subscription bundling. Wireless-enabled meters with cloud analytics are gaining share fastest through digital-native patient cohorts.
- Retail:Pharmacy chains and diagnostic equipment stores provide immediate product access and pharmacist consultation. Apollo and MedPlus centralized contracts in Karnataka and Telangana are displacing distributor-mediated purchasing.
- Wholesale:Regional distributors serving tier-2 and tier-3 cities with inventory financing. Capital-light equipment rental programs are lowering entry barriers for mid-tier distributors.
- Direct Sales:Manufacturer field forces targeting hospital procurement committees and diagnostic chain headquarters. F. Hoffmann-La Roche Ltd anchors premium meter sales through this channel.
Retail holds the largest share; online is expanding most quickly as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's glucose monitoring device trade tilts toward import dependency for precision biosensor components, while domestic assembly gains traction through PLI scheme subsidies. State-level procurement under Ayushman Bharat is redistributing demand across sub-regional healthcare networks.
Maharashtra
Mumbai's diagnostic chains and Pune's hospital procurement committees drive premium meter adoption among insulin-dependent patients. CDSCO's post-market surveillance requirements apply stringently to devices distributed through the state's organized pharmacy networks. Thane and Nagpur industrial corridors host contract manufacturing for enzymatic test strip assembly.
Gujarat
Ahmedabad's pharmaceutical manufacturing ecosystem supports glucose oxidase chemistry supply for domestic strip producers. BIS certification for electrical safety governs meter imports through Mundra and Kandla port facilities. Surat and Vadodara pharmacy networks are expanding homecare penetration among type 2 diabetes patients managing dosing independently.
Karnataka
Bengaluru's organized retail corridor concentrates centralized procurement contracts for Apollo and MedPlus pharmacy chains. The state's medical electronics PLI beneficiaries are scaling precision biosensor assembly for wireless-enabled meters. Mysuru and Hubballi diagnostic chains are adopting leasing models to lower capital barriers for mid-tier distributors.
Delhi-NCR
Government hospital procurement under central health schemes anchors volume demand for strip-based systems across the capital region. CDSCO headquarters proximity accelerates regulatory filing timelines for manufacturers seeking device registration. Gurugram and Noida logistics hubs facilitate distribution to tier-2 cities in Haryana and Uttar Pradesh.
Tamil Nadu
Chennai's diagnostic equipment import channels serve hospital glycemic management and pre-surgical screening demand. State-level tendering for beneficiary coverage is reallocating volume between hospital and homecare channels in Coimbatore and Madurai. Tiruppur and Salem pharmacy networks are displacing distributor-mediated purchasing through chain consolidation.
India Self-Monitoring Blood Glucose Devices Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: multinational device manufacturers with hospital procurement relationships, domestic strip producers competing on pharmacy network penetration, and emerging wireless-enabled meter specialists capturing subscription revenue. Strategic archetypes include precision biosensor assemblers leveraging PLI subsidies, diagnostic chain lessors deploying capital-light equipment models, and cloud analytics bundlers monetizing patient data platforms. Competitive moves center on backward integration into enzymatic chemistry supply and geographic expansion through state-level tender participation.
Among multinational manufacturers, Abbott and F. Hoffmann-La Roche Ltd occupy positions reflecting divergent channel strategies, while Morepen Laboratories exemplifies domestic volume competition through pharmacy tie-ups. Abbott represents the integrated archetype combining strip manufacturing with meter distribution. F. Hoffmann-La Roche Ltd anchors premium positioning through hospital procurement committee relationships. Morepen Laboratories sits within the high-volume, low-margin tier focused on consumable replenishment cycles.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Medtronic plc |
| Ascensia Diabetes Care Holdings AG |
| Arkray Inc. |
| LifeScan |
| Morepen Laboratories |
| Johnson & Johnson Ltd. |
| B. Braun Medical (India) Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Chinese glucose oxidase and mediator chemical suppliers anchor enzymatic strip manufacturing costs, concentrating margin capture in downstream meter distribution and cloud analytics subscription tiers where brand loyalty and data platform lock-in sustain pricing power.
Pricing Analysis
Hospital procurement committees and diagnostic chain buyers anchor contract-based pricing for premium electrochemical meters, while retail pharmacy networks drive per-unit transactional volume for strip-based consumables. Three-tier pricing structure across premium wireless-enabled, standard electrochemical, and economy strip-only tiers separates reimbursement-aligned hospital sales from cash-pay homecare segments. Cost compression in the enzymatic strip tier is intensifying because glucose oxidase feedstock volatility squeezes manufacturer margins. Price-sensitive tier-2 pharmacy networks exhibit highest elasticity, while insulin-dependent patients in Mumbai and Delhi diagnostic chains show lowest sensitivity for continuous monitoring systems.
Supply Chain Analysis
Thane and Nagpur industrial corridors host contract manufacturing for enzymatic test strip assembly, with precision biosensor component fabrication concentrated in South Korea, Taiwan, and select domestic PLI beneficiaries. Raw material dependencies span glucose oxidase enzymes from Chinese biotech suppliers, polymer substrates from South Korean petrochemical producers, and mediator chemicals from German specialty chemical houses. Single-source vulnerability in glucose oxidase supply creates exposure to export licensing disruptions. Distribution runs through Apollo and MedPlus centralized procurement contracts displacing traditional distributor-mediated flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring patches and smartphone-integrated non-invasive sensing technologies threaten strip-based meter incumbents, forcing defensive repositioning around data platform stickiness and consumable replenishment lock-in.
For Market Incumbents: Build switching-cost moats through cloud analytics subscription bundling that ties glucose data history to pharmacy loyalty programs. Deepen backward integration into enzymatic chemistry supply to offset glucose oxidase feedstock volatility. Secure CDSCO post-market surveillance compliance infrastructure ahead of tightened quality norm enforcement. Channel control through diagnostic chain leasing partnerships represents the critical defensive lever against continuous monitoring substitution. For New Entrants and Emerging Players: Tier-2 city diagnostic chains in Gujarat and Tamil Nadu represent the most penetrable entry point for capital-light equipment rental programs targeting mid-tier distributors. Wireless-enabled meter penetration among digital-native patient cohorts in Bengaluru's organized retail corridor offers white-space for subscription-linked cloud analytics. Go-to-market execution should prioritize state-level Ayushman Bharat tender participation to secure volume allocation. For Investors and Strategic Acquirers: Capital is best deployed toward precision biosensor assemblers leveraging PLI scheme subsidies with demonstrated CDSCO regulatory navigation capabilities. Long-term viability in this market hinges on convergence between continuous monitoring trend data and electrochemical point-of-care accuracy. Watch for inflection in state-level homecare reimbursement policy under Ayushman Bharat beneficiary expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Quality Compliance Investment | Post-market surveillance infrastructure separates viable registrants from approval timeline casualties. |
| PLI Scheme Precision Biosensor Assembly | Domestic manufacturing subsidies redirect hospital procurement toward locally assembled wireless meters. |
| Diagnostic Chain Leasing Partnership | Capital-light equipment rental lowers entry barriers for mid-tier distributors serving tier-2 cities. |
| Cloud Analytics Platform Development | Subscription-linked glucose data capture recurring revenue from pharmacy-loyal patient cohorts. |
| State Tender Participation Strategy | Ayushman Bharat beneficiary volume allocation reshapes hospital-homecare channel mix. |
Research Methodology
A standing panel of hospital procurement managers, diagnostic chain operations heads, pharmacy network category buyers, and CDSCO regulatory affairs specialists provided ongoing calibration against secondary validation from BIS certification databases, CDSCO device registration filings, PLI scheme beneficiary disclosures, and state-level Ayushman Bharat tender documentation. Primary fieldwork combined structured interviews with biomedical engineers and GPO contracts managers alongside bottom-up and top-down triangulation across trade flow data and hospital procurement databases.
Scenario-bracketing around enzymatic input cost volatility, regulatory approval timeline compression, and reimbursement policy evolution framed projections across the analysis window. Segmentation modeling incorporated product architecture, technology tier, end-use setting, and distribution channel with state-level geographic clustering. CAGRs derived from patient population growth trajectories, testing frequency assumptions, and channel mix evolution across homecare, hospital, and clinic settings.
Stress conditions across glucose oxidase feedstock pricing, CDSCO approval cycle extension, and Ayushman Bharat tender participation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of state-level reimbursement policy announcements and PLI scheme capacity utilization disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market