
 Oman Diabetes Drugs Market | 2026-2036
Oman Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Diabetes Drugs Market Analytics
Market Context
A wide manufacturing-scale gap between multinational suppliers and local distributors is reorganizing competitive tiers in Oman's diabetes therapeutics sector. Novo Nordisk leverages its recombinant insulin production network to secure hospital tender contracts across the Sultanate's public health system. Sanofi anchors its position through established cold-chain logistics partnerships that reach Muscat, Salalah, and Sohar. Eli Lilly differentiates via concentrated R&D investment in GLP-1 receptor agonist formulations suited to regional metabolic profiles.
Technical Definition and Segment Structure
Oman diabetes drugs comprise synthetic and biological active pharmaceutical ingredients formulated to regulate blood glucose through insulin supplementation, hepatic glucose suppression, or incretin pathway modulation, with stability requirements typically mandating two to eight degrees Celsius storage for biologic products. These therapeutics serve to prevent microvascular and macrovascular complications in diabetic populations while reducing hospitalization burden on national health expenditure. Injectable delivery modes dominate value capture due to insulin dependence among Type 1 and advanced Type 2 cohorts, though oral DPP-4 inhibitors are gaining fastest volume traction among newly diagnosed Type 2 patients seeking regimen simplicity. Hospital end users currently command the largest procurement volumes through centralized Ministry of Health tendering, while home care channels represent the emerging margin pool as self-administration training programs expand.
Regulatory Framework and Outlook
MOHAP and the Ministry of Health Oman jointly oversee drug registration, pricing controls, and reimbursement formulary decisions that determine market access for imported diabetes therapeutics. The country's national pharmaceutical regulator enforces stability testing and bioequivalence standards aligned with Gulf Central Committee for Drug Registration harmonized guidelines. Stakeholders must monitor evolving local manufacturing incentives and tender localization requirements that could reshape import dependency patterns.
Market Dynamics
Hospital formulary centralization under Ministry of Health Oman tendering is compressing distributor margins while accelerating biosimilar substitution for originator insulins across the Sultanate's public procurement system.
Growth Catalysts
- Home Care Transition Programs:Ministry of Health Oman self-administration training initiatives are expanding addressable patient populations beyond hospital walls into chronic disease management networks.
- GLP-1 Formulation Advances:Weekly injectable incretin mimetics are capturing newly diagnosed Type 2 cohorts seeking reduced injection frequency compared to daily basal insulin regimens.
- MOHAP Harmonized Registration:Gulf Central Committee for Drug Registration alignment is accelerating multi-market product approvals for manufacturers targeting Oman alongside Saudi Arabia and UAE.
Market Restraints
- Cold-Chain Infrastructure Gaps:Temperature excursions during last-mile delivery to Salalah and interior governorates degrade biologic stability and trigger batch rejections.
- Import Dependency Concentration:Active pharmaceutical ingredient sourcing from European recombinant protein manufacturers creates single-point vulnerability for insulin supply security.
- Reimbursement Ceiling Rigidity:Ministry of Health Oman reference pricing mechanisms prevent premium capture for novel formulations despite clinical differentiation.
Strategic Opportunities
- Dhofar Governorate Penetration:Salalah's underserved diabetic population represents expansion whitespace beyond Muscat's saturated tertiary care cluster.
- Digital Therapeutic Integration:Continuous glucose monitor data streams paired with dose-optimization algorithms are creating adherence-focused service revenue pools.
- Local Compounding Incentives:Ministry of Health Oman manufacturing localization requirements may reward domestic formulation facilities with preferential tender weighting.
Industry Challenges
- Endocrinology Specialist Scarcity:Limited physician training capacity constrains patient onboarding velocity for complex insulin initiation protocols.
- Multi-Tender Compliance Burden:Parallel MOHAP and Ministry of Health Oman documentation requirements duplicate regulatory submission efforts for identical products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Diabetes Drugs Market |
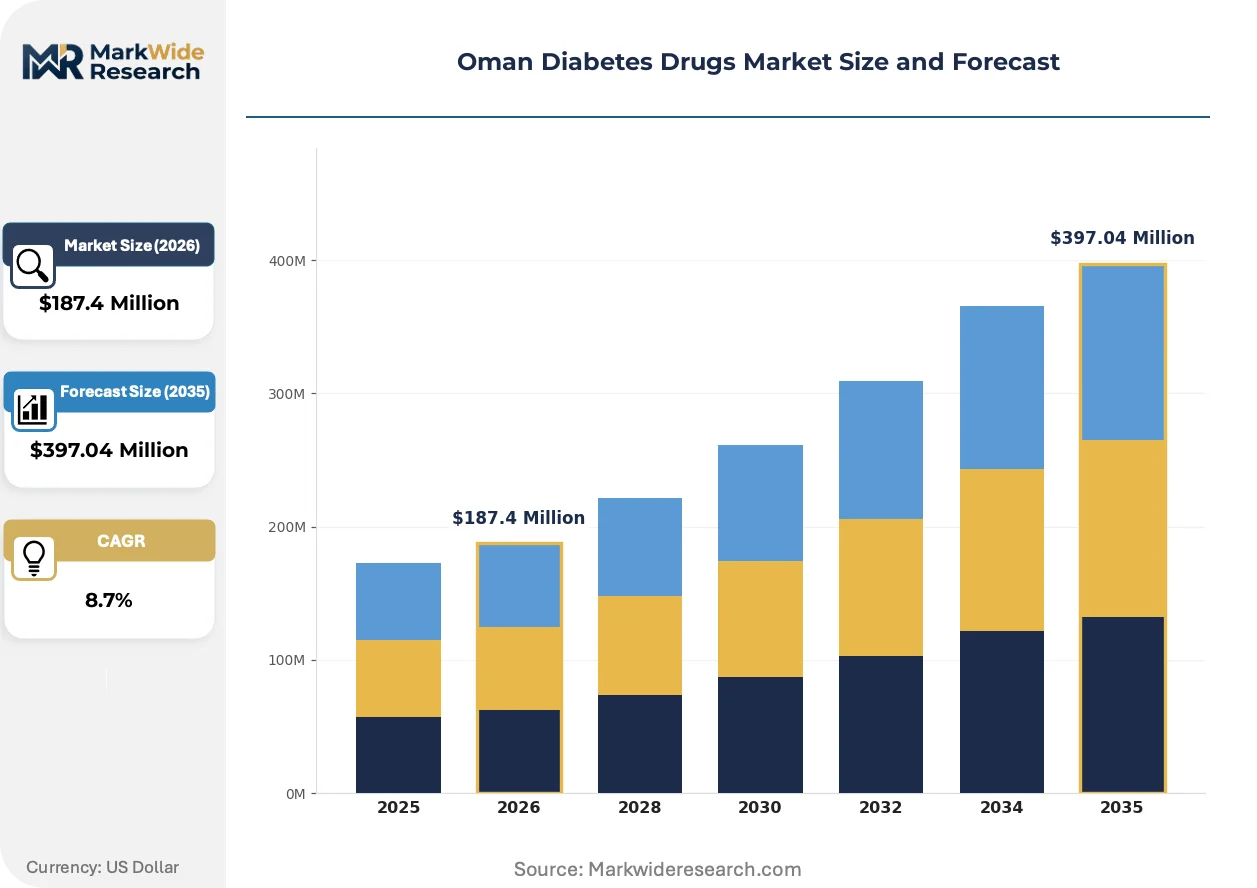
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Metformin, Sulfonylureas, DPP-4 Inhibitors Delivery Mode: Injectable, Oral, Inhalable, Continuous End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Prediabetes, Gestational Diabetes |
| Companies Covered | AstraZeneca, Merck and Co., Novo Nordisk, Pfizer, Takeda, Sanofi, Boehringer Ingelheim, Janssen Pharmaceuticals, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Diabetes Drugs Market Evolving Landscape
Connected delivery devices and algorithmic dosing support are transforming diabetes management from episodic clinical intervention into continuous data-driven care coordination across Oman's health system.
Smart insulin pens with dose-logging and Bluetooth connectivity are bifurcating the injectables segment into connected and conventional device categories. Private hospital chains in Muscat Governorate are prioritizing pen procurement with integrated mobile application support for remote patient monitoring. This technology compression is forcing distributors to maintain dual inventory streams while training pharmacy staff on device pairing protocols.
Ministry of Health Oman stability testing protocols aligned with Gulf Central Committee for Drug Registration guidelines are tightening documentation requirements for temperature excursion investigations. Manufacturers must now submit continuous monitoring data across the full distribution chain for biologic registration renewals. The insulin and GLP-1 segments are responding by investing in validated cold-chain telemetry systems for tender compliance.
Specialized diabetes clinic networks are consolidating procurement decisions away from individual hospital pharmacies toward centralized governorate-level purchasing committees. Muscat's tertiary care cluster is leading this transition, with aggregated volume commitments replacing fragmented site-by-site ordering. This concentration is most visible in the public sector, where Ministry of Health Oman tender participation now requires minimum annual supply guarantees that exclude smaller distributors.
Oman Diabetes Drugs Market Segmentation
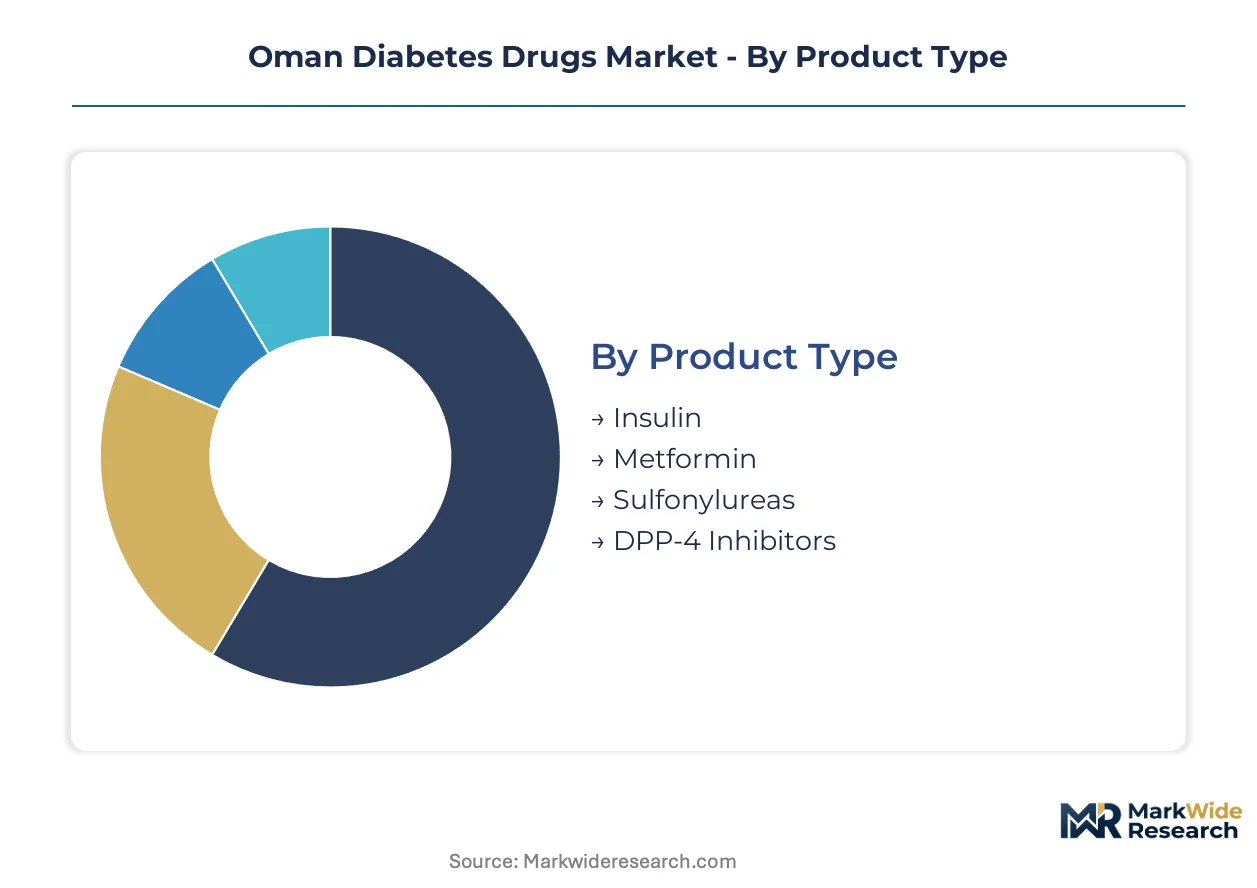
Diabetes therapeutics in Oman fragment across four critical dimensions that determine procurement patterns, margin structures, and regulatory pathways. Product type and delivery mode classifications shape Ministry of Health tender specifications, while end-user and therapy area distinctions govern distribution channel economics and patient onboarding protocols.
Product Type:
Substitution pressure concentrates on insulin analogs as Ministry of Health Oman formulary revisions accelerate biosimilar acceptance for originator products.
- Insulin:Recombinant human and analog formulations requiring two to eight degrees Celsius cold-chain integrity dominate hospital procurement volumes. Muscat Governorate's tertiary care cluster absorbs the majority of rapid-acting and long-acting basal insulin tenders.
- DPP-4 Inhibitors:Oral incretin enhancers with once-daily dosing profiles are displacing sulfonylureas in newly diagnosed Type 2 protocols. Private clinic networks in Salalah and Sohar are expanding sitagliptin and linagliptin prescriptions for regimen simplicity.
- Metformin:First-line biguanide therapy remains the standard of care for prediabetes and early Type 2 management across Ministry of Health primary health centers.
- Sulfonylureas:Glipizide and gliclazide formulations face volume erosion as DPP-4 inhibitors capture preference for reduced hypoglycemia risk.
Insulin retains volume leadership; DPP-4 inhibitors hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates premium connected devices from commodity vial-and-syringe formats in Ministry of Health procurement categories.
- Injectable:Pen devices and traditional syringes command the highest value share due to insulin dependence in Type 1 and advanced Type 2 populations. Smart pen adoption is bifurcating this segment between Bluetooth-enabled and conventional formats.
- Oral:Tablet and capsule formulations for metformin, sulfonylureas, and DPP-4 inhibitors offer distribution simplicity without cold-chain burden. Pharmacies in interior governorates favor oral therapies for last-mile reliability.
- Continuous:Insulin pump therapy with integrated continuous glucose monitoring is penetrating private hospital chains in Muscat for intensive management protocols.
- Inhalable:Technosphere insulin and other non-injectable alternatives remain limited to specialized endocrinology centers with advanced patient training capacity.
Injectable formats retain volume leadership; continuous delivery holds the steepest expansion curve.
End User:
Customer type concentration is shifting procurement authority from individual hospital pharmacies toward governorate-level purchasing committees.
- Hospitals:Tertiary care institutions in Muscat, Salalah, and Sohar aggregate the largest tender volumes through centralized Ministry of Health procurement. Formulary standardization is compressing distributor margins while accelerating biosimilar substitution.
- Home Care:Self-administration training programs are expanding addressable populations beyond clinical settings into chronic disease management networks. Home care channels represent the emerging margin pool for connected delivery devices.
- Clinics:Private diabetes specialty centers in Muscat Governorate are consolidating purchasing decisions toward aggregated volume commitments.
- Pharmacies:Retail dispensing for oral therapies and insulin pen refills serves patient populations in interior governorates with limited hospital access.
Hospitals retain volume leadership; home care holds the steepest expansion curve.
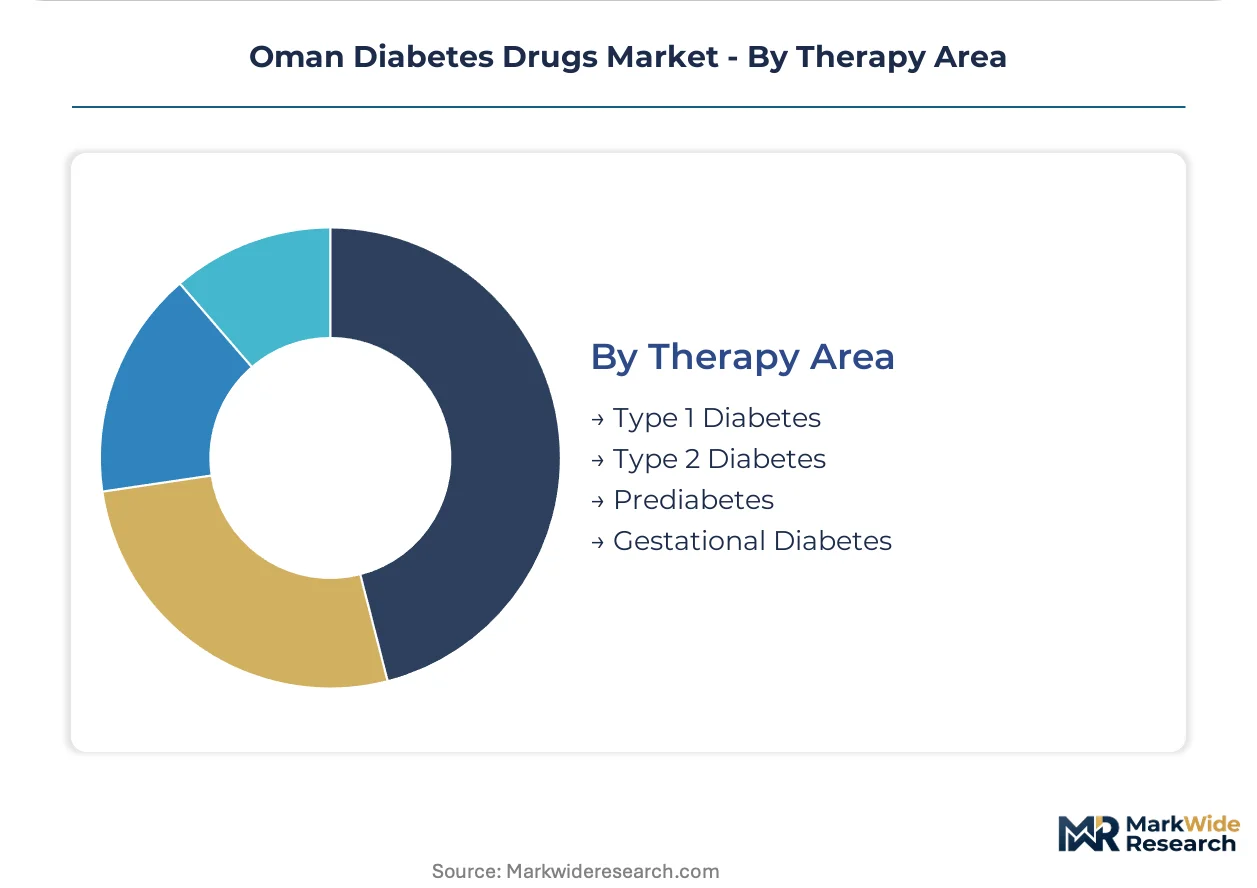
Therapy Area:
Application severity determines product mix intensity, with Type 1 protocols requiring continuous insulin versus Type 2 management spanning oral-to-injectable escalation pathways.
- Type 2 Diabetes:The predominant patient population drives volume for oral hypoglycemics and escalating injectable regimens. GLP-1 receptor agonist penetration is fastest among this cohort seeking reduced injection frequency.
- Type 1 Diabetes:Absolute insulin dependence creates captive demand for basal-bolus regimens and pump therapy. Pediatric endocrinology centers in Muscat concentrate this high-intensity management segment.
- Prediabetes:Metformin prophylaxis and lifestyle intervention protocols are expanding through Ministry of Health screening programs in Dhofar and Al Batinah governorates.
- Gestational Diabetes:Insulin therapy during pregnancy requires specialized obstetric-endocrine coordination available primarily in Muscat's tertiary cluster.
Type 2 Diabetes retains volume leadership; prediabetes holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Oman's governorates, with interior regions prioritizing cost minimization for oral therapies while Muscat's tertiary cluster absorbs premium biologic pricing for intensive insulin protocols.
Muscat Governorate
Royal Hospital and Sultan Qaboos University Hospital anchor the Sultanate's highest-volume insulin procurement, driven by concentrated Type 1 pediatric cases and complex gestational diabetes referrals. Ministry of Health Oman tender specifications here emphasize cold-chain validation and biosimilar substitution protocols. The capital's tertiary care cluster is consolidating purchasing authority through governorate-level pharmacy committees.
Dhofar Governorate
Salalah's underserved diabetic population generates expanding demand for oral DPP-4 inhibitors as first-line therapy, with patients facing long travel distances to specialized endocrinology services. Ministry of Health Oman self-administration training programs are extending into Dhofar's primary health centers. The port city's logistics constraints create last-mile delivery challenges for temperature-sensitive biologics.
Al Batinah Governorate
Sohar's industrial workforce drives employer-sponsored screening programs that expand prediabetes identification and metformin prophylaxis uptake. Ministry of Health Oman reference pricing mechanisms cap reimbursement for novel formulations in this cost-sensitive segment. The governorate's hospital network is integrating with Muscat's tertiary cluster through telemedicine consultation pathways.
Ad Dakhiliyah Governorate
Nizwa's expanding diabetes clinic network is capturing patients transitioning from hospital-based to home care management, with growing pen device adoption. Ministry of Health Oman stability testing protocols are tightening documentation requirements for temperature monitoring across this interior region's distribution chain. The governorate represents emerging whitespace for connected delivery device penetration.
Ash Sharqiyah Governorate
Sur's coastal location enables direct sea freight receipt of imported insulin shipments, reducing cold-chain excursion risks versus overland routes from Muscat. Ministry of Health Oman tender participation requires minimum supply guarantees that favor established distributors with validated logistics infrastructure. The governorate's hospital procurement is shifting toward aggregated volume commitments.
Oman Diabetes Drugs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Oman's diabetes therapeutics sector, with multinational recombinant protein manufacturers commanding hospital tender contracts through established cold-chain partnerships. The market structure concentrates procurement authority among originator insulin suppliers with Gulf Central Committee for Drug Registration alignment, while biosimilar challengers gain formulary access through price-undercutting strategies. Three archetypes dominate: integrated biologic manufacturers with captive production networks, regional distributors with logistics specialization, and formulation specialists with localized packaging capabilities. Competitive moves center on tender compliance investments and digital therapeutic integration partnerships.
Among European-integrated biologic manufacturers, Novo Nordisk, Sanofi, and Eli Lilly occupy positions reflecting distinct strategic emphases—recombinant insulin production scale, cold-chain distribution reach, and GLP-1 formulation advancement respectively. These entities exemplify the premium-tier archetype through their Ministry of Health Oman tender participation and Gulf Central Committee for Drug Registration harmonization. Their collective presence anchors the competitive structure, with each representing a different pathway to market access in the Sultanate's procurement system.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck and Co. |
| Novo Nordisk |
| Pfizer |
| Takeda |
| Sanofi |
| Boehringer Ingelheim |
| Janssen Pharmaceuticals |
| Eli Lilly |
| Others |
Value Network & Pricing Analysis
Long-term tender contracts with Ministry of Health Oman lock in insulin supply access while capping price visibility for originator manufacturers, binding pricing power to cold-chain compliance investments and biosimilar substitution timelines.
Pricing Analysis
Connected device service revenue drives lifetime value as smart pen subscriptions and remote monitoring bundles displace transactional vial sales. Three-tier pricing structure across premium connected pens, standard disposable devices, and economy vial-and-syringe formats reflects Ministry of Health Oman reimbursement ceilings. Cost compression in the economy tier intensifies as Indian and Egyptian biosimilar manufacturers undercut European originators on tender bids. Private hospital chains in Muscat exhibit lowest price sensitivity; primary health centers in interior governorates face strict reference pricing constraints.
Supply Chain Analysis
Denmark, France, and the United States anchor recombinant insulin production for Oman's hospital procurement system. Active pharmaceutical ingredient sourcing draws from European microbial fermentation facilities and specialized fill-finish operations in Germany and Ireland. Single-source vulnerability concentrates in cold-chain logistics partnerships, where temperature excursions during Salalah port receipt trigger batch rejections. Distribution runs through Ministry of Health Oman central warehouses in Muscat before governorate-level redistribution to hospital pharmacies and home care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar insulin substitution threatens originator margin structures, forcing incumbents to defend through service differentiation and digital therapeutic integration.
For Market Incumbents: Fortify tender compliance investments by embedding continuous glucose monitoring data services into insulin pen contracts, neutralizing biosimilar price undercutting. Deepen cold-chain telemetry partnerships with Salalah port operators to reduce batch rejection rates below Ministry of Health Oman thresholds. Prioritize GLP-1 formulation advancement as the defensive lever against oral DPP-4 inhibitor displacement in newly diagnosed Type 2 protocols. For New Entrants and Emerging Players: Anchor in Dhofar Governorate's underserved diabetic population, where Salalah's distance from Muscat's tertiary cluster creates whitespace for home care training program partnerships. Target oral DPP-4 inhibitor distribution through private clinic networks seeking regimen simplicity for patient retention. Deploy telemedicine-integrated pharmacy services as the go-to-market angle, linking remote endocrinology consultation with medication delivery. For Investors and Strategic Acquirers: Regional distributors with validated Gulf Central Committee for Drug Registration alignment and cold-chain infrastructure represent the acquisition target archetype with highest strategic value. Long-term viability hinges on digital therapeutic integration capabilities and Ministry of Health Oman tender participation history. Watch for biosimilar formulary acceptance acceleration as the inflection signal indicating originator pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Salalah port temperature validation reduces biologic batch rejections under Ministry of Health Oman protocols. |
| Digital Therapeutic Integration | Continuous glucose monitor data streams create adherence-focused service revenue beyond commodity insulin sales. |
| GLP-1 Formulation Advancement | Weekly injectable incretin mimetics capture Type 2 patients seeking reduced injection frequency versus basal insulin. |
| Biosimilar Registration Pathway | Gulf Central Committee for Drug Registration alignment accelerates multi-market approvals across Oman, Saudi Arabia, and UAE. |
| Home Care Training Program Expansion | Ministry of Health Oman self-administration initiatives extend addressable populations beyond hospital walls into chronic disease networks. |
Research Methodology
Desk research of Ministry of Health Oman tender databases, Gulf Central Committee for Drug Registration filings, and hospital procurement records preceded structured interviews with formulary directors, cold-chain logistics managers, and diabetes clinic heads. Primary fieldwork with pharmaceutical distribution executives and regulatory affairs specialists validated secondary data on biosimilar substitution timelines and pricing compression patterns. Bottom-up patient population modeling triangulated against top-down Ministry of Health expenditure forecasts.
Variance decomposition across product type, delivery mode, end user, and therapy area segments informed volume and value projections over the analysis window. CAGRs derived from segment-level growth rate blending weighted by current procurement volumes. Forecast inputs incorporated Ministry of Health Oman localization incentive trajectories, GLP-1 penetration curves in Type 2 populations, and cold-chain infrastructure investment pipelines.
Material uncertainties — regulatory approval delays for novel formulations, biosimilar tender acceptance acceleration, and cold-chain excursion frequency in interior governorates — sit outside the modeled envelope. Forecasts reflect documented assumptions on patient screening program expansion and connected device adoption curves. Recalibration cycles align with material shifts in Ministry of Health Oman formulary revisions and Gulf Central Committee for Drug Registration harmonization updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market