
 United States Self-Monitoring Blood Glucose Market | 2026-2036
United States Self-Monitoring Blood Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
United States Self-Monitoring Blood Glucose Market Analytics
CMS expanded Medicare coverage for therapeutic continuous glucose monitors is pivoting reimbursement policy toward remote patient monitoring. Abbott Laboratories leverages vertically integrated sensor manufacturing to sustain cost advantages in disposable patch production. DexCom Inc anchors the connected device segment through proprietary algorithm development and direct-to-consumer channel control. Roche Holding AG competes on test strip volume through pharmacy benefit manager contracts and wholesale distribution scale.
Self-monitoring blood glucose encompasses electrochemical biosensor systems that quantify capillary glucose concentration through enzymatic reactions, typically using glucose oxidase or glucose dehydrogenase chemistry on disposable strips with 5-second readout times and hematocrit correction algorithms. Continuous glucose monitors now lead product type expansion as real-time data streams replace point-in-time measurements, while smartphone-integrated technology captures the fastest growth trajectory by embedding glucose data into Apple Health and Android ecosystems. Standard meters occupy a mature, price-compressed tier concentrated in cash-pay and emerging patient populations.
FDA premarket notification pathways under 21 CFR 862.1355 shape device classification and clinical evidence requirements for new glucose monitoring systems, while CMS national coverage determinations directly control reimbursement access and patient out-of-pocket exposure. HIPAA privacy rules govern data transmission architecture for connected devices, creating compliance cost layers for cloud-based glucose platforms. Stakeholders must monitor FDA draft guidance on integrated continuous glucose monitor-insulin pump systems, as interoperability standards will determine competitive positioning in closed-loop artificial pancreas development.
Market Dynamics
Medicare reimbursement expansion for continuous glucose monitors is restructuring demand economics across Type 2 diabetes populations, compressing traditional meter volumes while accelerating sensor-based platform adoption in home care settings.
Growth Catalysts
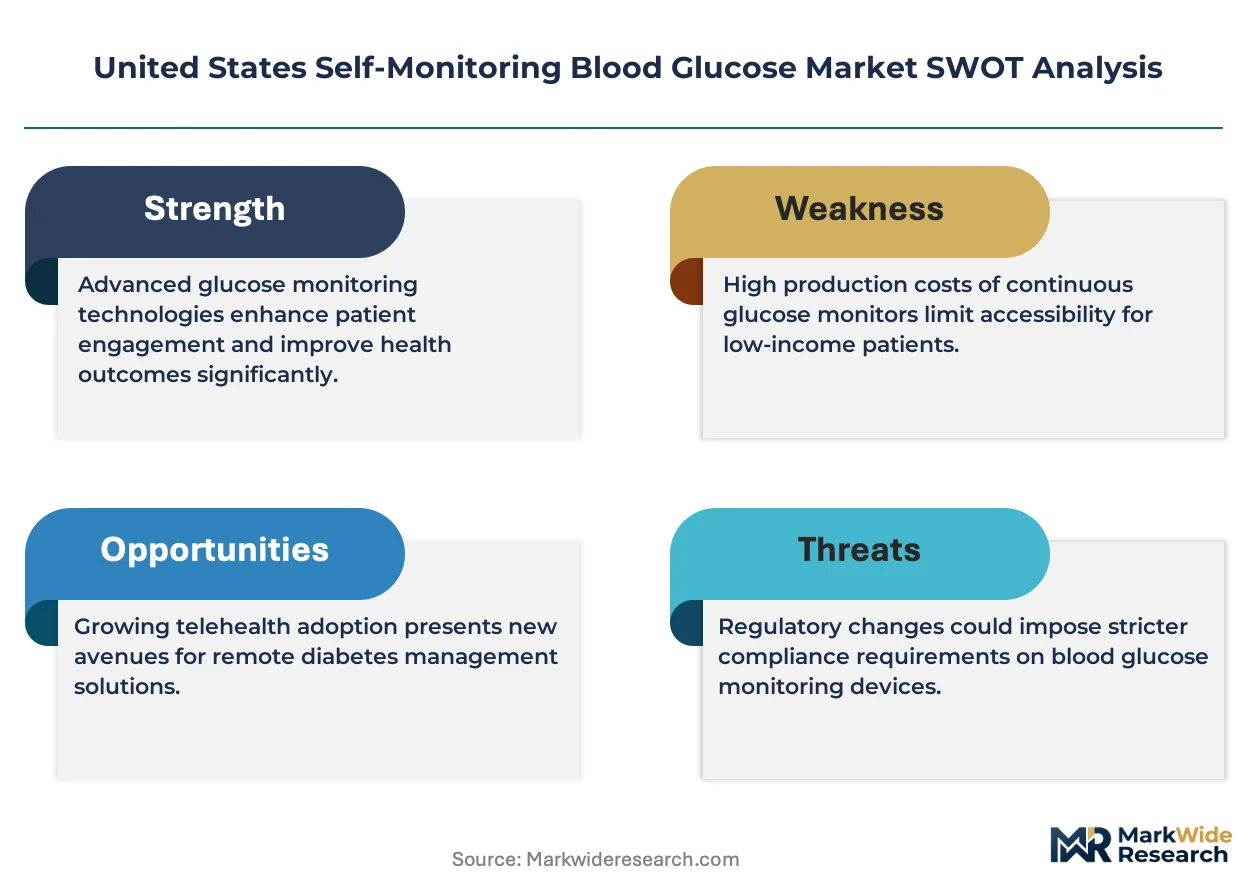
- CMS National Coverage Determinations:Expanded therapeutic continuous glucose monitor reimbursement under Medicare Part B eliminates prior authorization barriers for non-insulin-using Type 2 patients, unlocking access for approximately 1.5 million additional beneficiaries.
- Smartphone-integrated biosensors:Bluetooth-enabled patch systems stream real-time glucose data into Apple Health and Android ecosystems, embedding metabolic monitoring within consumer electronics workflows that patients already use daily.
- Texas-California-Florida demand concentration:These three states account for disproportionate volume due to combined high diabetes prevalence, large insured Medicare Advantage populations, and concentrated endocrinology specialist networks.
Market Restraints
- Platinum and palladium input volatility:Electrochemical biosensor electrodes depend on precious metal catalysts whose price swings compress manufacturing margins for disposable test strip producers.
- Single-source sensor membrane supply:Polyurethane and fluoropolymer membranes for implantable glucose sensors concentrate among three specialty chemical suppliers, creating vulnerability to force majeure disruptions.
- FDA 510(k) clinical evidence requirements:Predicate device comparisons for new continuous glucose monitor submissions demand 15-day accuracy studies against laboratory reference methods, extending time-to-market by 18-24 months.
Strategic Opportunities
- Remote patient monitoring CPT codes:New CMS reimbursement for physician interpretation of continuous glucose data creates recurring revenue streams for endocrinology practices and telehealth platforms.
- Closed-loop artificial pancreas convergence:Integration of continuous glucose monitors with insulin pump algorithms and control software opens premium-tier product positioning for interoperable device ecosystems.
- Pharmacy benefit manager channel bypass:Direct-to-consumer subscription models for continuous glucose monitor sensors circumvent formulary exclusion risk and capture patient lifetime value through recurring revenue.
Industry Challenges
- Biocompatibility engineering talent scarcity:Specialized expertise in foreign body response mitigation for long-term implantable sensors concentrates among academic medical centers and a handful of device manufacturers.
- HIPAA-compliant cloud architecture costs:Real-time glucose data transmission requires encrypted health information infrastructure that adds $2-4 million in annual compliance expenditure for connected device platforms.
- Legacy electronic health record integration:Proprietary data formats from established continuous glucose monitor systems resist seamless flow into Epic and Cerner workflows, forcing manual data entry at clinical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Self-Monitoring Blood Glucose Market |
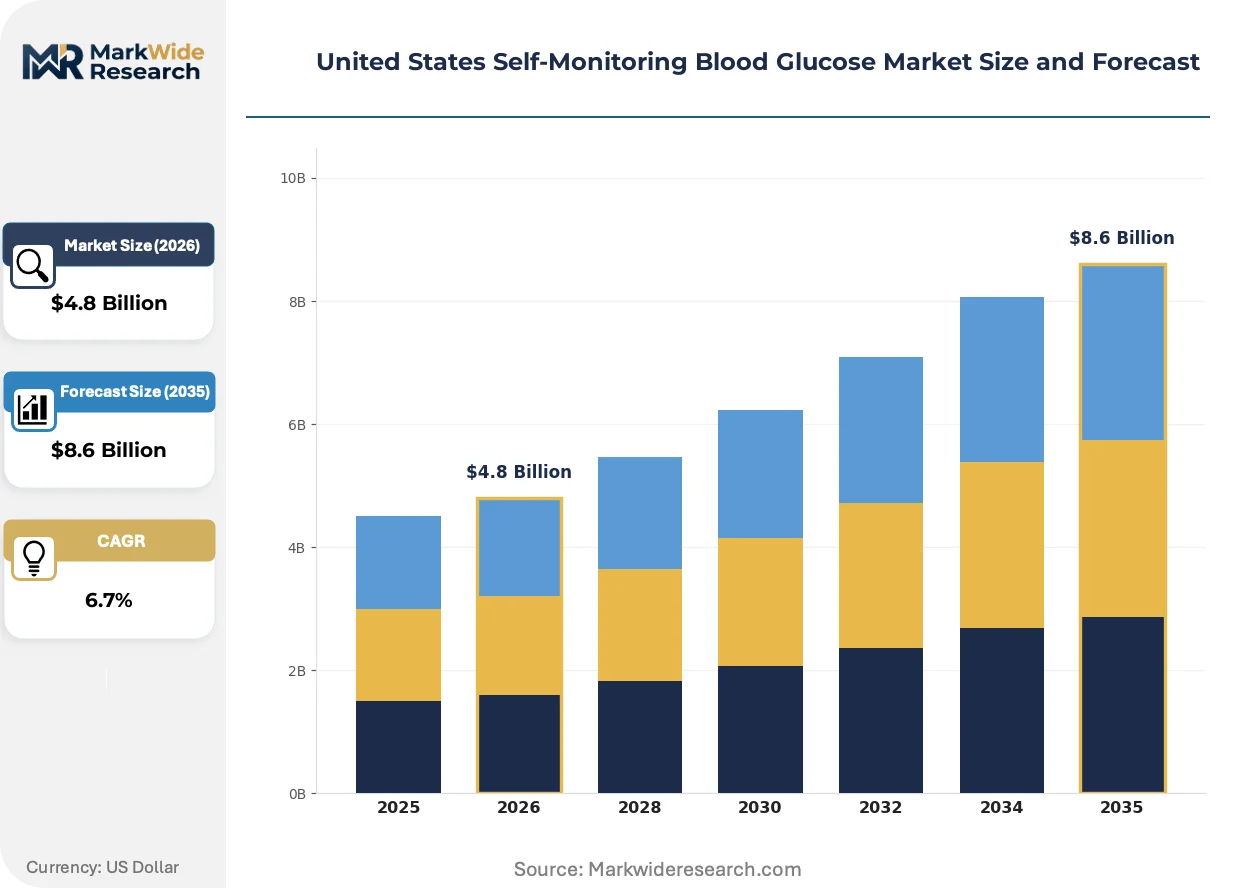
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Meters, Continuous Glucose Monitors, Test Strips, Lancets Technology: Non-Invasive, Smartphone-Integrated, Smart Meters, Connected Devices End User: Clinics, Hospitals, Home Care, Diagnostic Laboratories Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Wholesalers |
| Companies Covered | Abbott Laboratories, DexCom Inc, Roche Holding AG, Medtronic PLC, LifeScan Inc, Ascensia Diabetes Care, Arkray Inc, PHC Holdings Corp, Senseonics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Self-Monitoring Blood Glucose Market Evolving Landscape
Real-time metabolic data streams are displacing point-in-time measurements as the clinical standard, while algorithm-driven insulin dosing recommendations automate therapeutic decision-making that previously required physician interpretation.
Factory-calibrated continuous glucose monitors eliminate fingerstick blood glucose confirmation requirements through improved sensor chemistry and proprietary algorithm development. Type 1 diabetes patients and intensive insulin users in Medicare Advantage plans adopt these systems at the fastest pace. This technology is consolidating market share among sensor-native manufacturers while marginalizing legacy meter-strip ecosystems.
FDA draft guidance on integrated continuous glucose monitor-insulin pump systems establishes interoperability standards for closed-loop artificial pancreas development. Manufacturers must demonstrate secure wireless communication protocols and fail-safe glucose control algorithms to secure premarket approval. The pediatric Type 1 diabetes segment faces the steepest compliance burden due to heightened safety evidence requirements for vulnerable populations.
Patients increasingly expect glucose data ownership and platform portability across competing device ecosystems. Direct-to-consumer marketing and pharmacy retail channels displace traditional durable medical equipment distribution for continuous glucose monitor initiation. This behavioral shift concentrates in Florida and California, where Medicare Advantage penetration and consumer-directed health plan adoption are highest.
United States Self-Monitoring Blood Glucose Market Segmentation
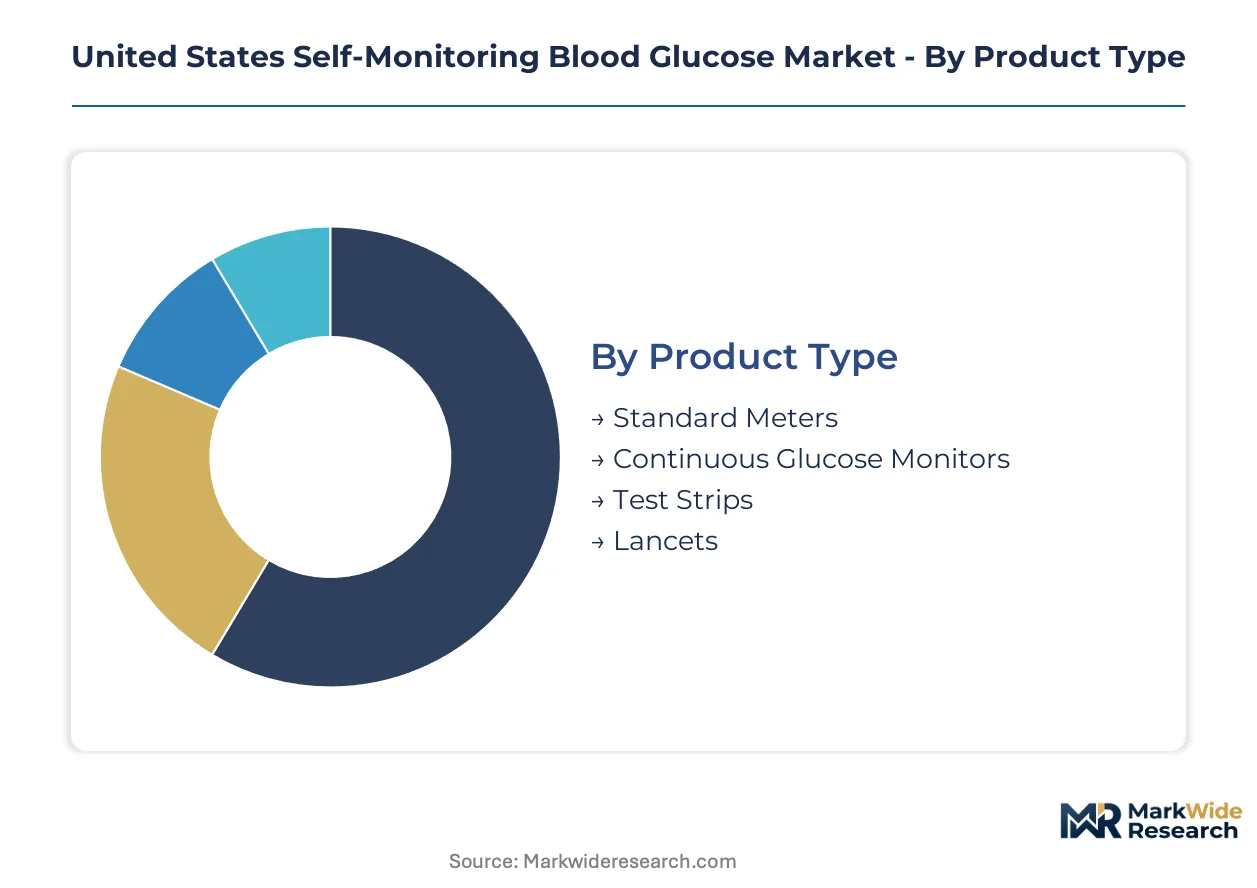
Segmentation reveals how reimbursement policy and patient workflow preferences reshape product mix across the United States Self-Monitoring Blood Glucose Market. Understanding these divisions exposes where Medicare coverage expansion and direct-to-consumer channels concentrate commercial opportunity.
Product Type:
FDA 510(k) clearance requirements vary sharply across this category, with implantable sensors demanding 15-day accuracy studies against laboratory reference methods while disposable strips follow abbreviated predicate pathways.
- Continuous Glucose Monitors:Implantable electrochemical biosensors with polyurethane membranes stream real-time glucose data via Bluetooth to smartphones. Texas and California Medicare Advantage populations drive fastest adoption as CMS therapeutic coverage expansion eliminates prior authorization barriers for Type 2 patients.
- Standard Meters:Portable electrochemical devices using glucose oxidase chemistry on disposable strips deliver 5-second capillary glucose readouts with hematocrit correction. Florida's large cash-pay and uninsured diabetes populations sustain this mature tier despite sensor displacement in insured segments.
- Test Strips:Single-use enzymatic biosensors depend on platinum-catalyzed electrodes vulnerable to precious metal price volatility.
- Lancets:Spring-loaded penetration devices for capillary blood sampling accompany meter-strip systems in pharmacy benefit manager bundles.
Continuous Glucose Monitors sits at the top of the volume ranking, with Continuous Glucose Monitors climbing the fastest.
Technology:
Cost stratification separates premium subscription-based platforms from one-time hardware purchases, with recurring sensor revenue models commanding valuation multiples above disposable consumables.
- Smartphone-Integrated:Bluetooth-enabled patch systems embed glucose data into Apple Health and Android ecosystems, capturing patient lifetime value through direct-to-consumer subscription channels that bypass formulary exclusion risk.
- Connected Devices:Cloud-architected platforms transmit encrypted glucose readings to HIPAA-compliant servers, requiring $2-4 million annual compliance expenditure that favors scaled manufacturers over emerging entrants.
- Smart Meters:Cellular-enabled standalone units with integrated displays target Medicare populations lacking smartphone adoption.
- Non-Invasive:Optical and transdermal glucose sensing technologies remain preclinical, awaiting FDA breakthrough device designation for commercial viability.
Smartphone-Integrated commands premium pricing tiers, while Non-Invasive platforms face steepest regulatory ascent timelines.
End User:
Application context determines whether glucose monitoring supports intensive insulin titration, periodic screening, or automated closed-loop control.
- Home Care:Patient-directed monitoring dominates volume as real-time data streams replace point-in-time measurements in daily diabetes management workflows across Texas, Florida, and California.
- Clinics:Endocrinology practices leverage remote patient monitoring CPT codes for physician interpretation of continuous glucose data, creating recurring revenue streams.
- Hospitals:Inpatient glycemic management protocols favor point-of-care systems with immediate laboratory correlation.
- Diagnostic Laboratories:Centralized reference method testing validates consumer device accuracy claims for regulatory submissions.
Home Care generates absolute volume leadership, with Clinics expanding most quickly through reimbursement-enabled remote monitoring services.
Distribution Channel:
Customer acquisition economics favor direct relationships that capture patient lifetime value over intermediary-dependent models subject to formulary exclusion.
- Online Retail:Direct-to-consumer subscription models for continuous glucose monitor sensors circumvent pharmacy benefit manager channel control and enable recurring revenue capture.
- Pharmacies:Retail chains compete on test strip volume through pharmacy benefit manager contracts and wholesale distribution scale.
- Medical Supply Stores:Durable medical equipment distributors retain relevance for Medicare Part B initial device provisioning.
- Wholesalers:Institutional procurement channels serve hospital and laboratory segments with volume pricing structures.
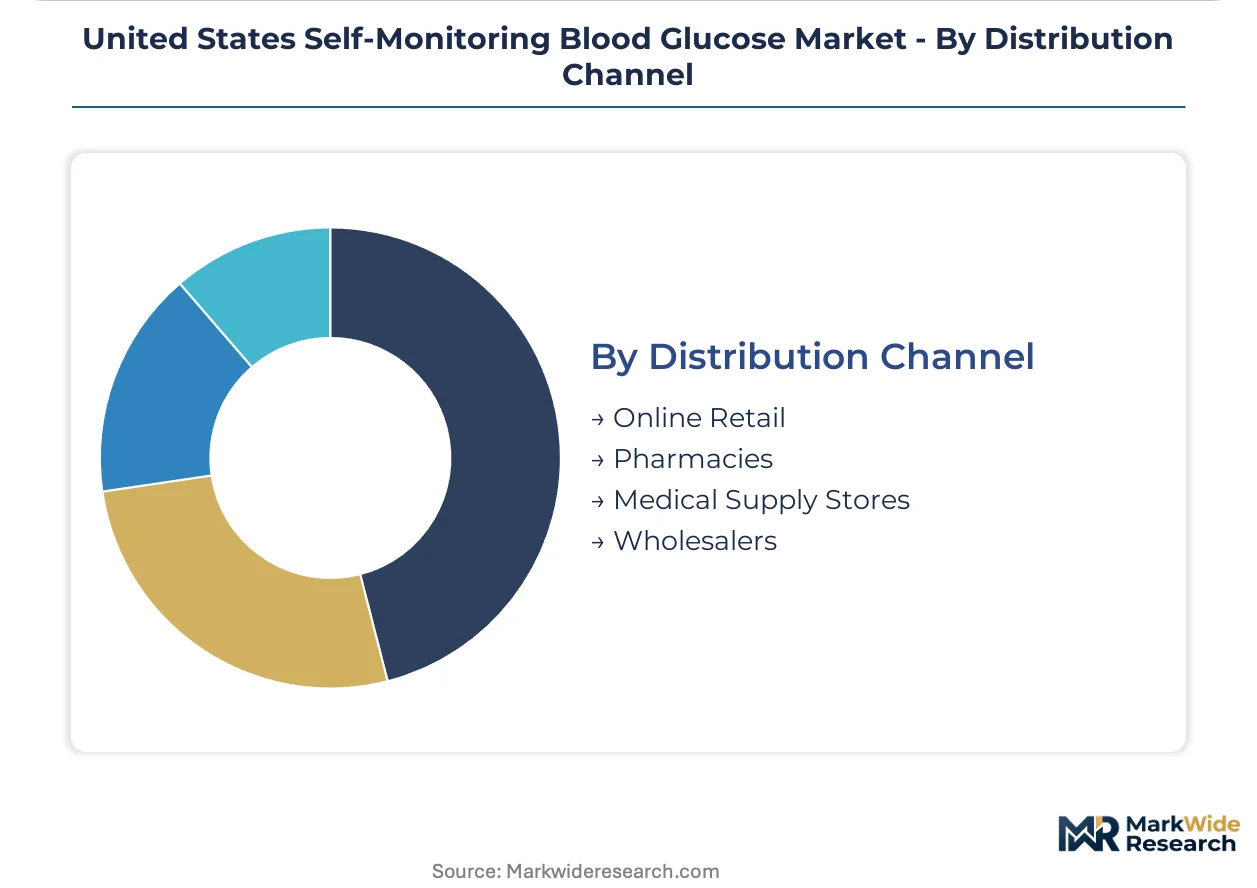
Online Retail captures margin expansion opportunity, with Pharmacies defending position through legacy strip volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endocrinology specialist networks and Medicare Advantage penetration anchor demand geography across the United States. State-level diabetes prevalence and insured population density determine market concentration.
Texas
Texas harbors the nation's second-largest diabetes patient population and dense Medicare Advantage networks in Houston and Dallas-Fort Worth. FDA-cleared continuous glucose monitors flow through durable medical equipment distributors serving endocrinology practices concentrated in the Texas Medical Center. San Antonio anchors sensor manufacturing operations for major device suppliers.
California
California leads smartphone-integrated biosensor adoption due to tech-savvy patient demographics and direct-to-consumer marketing penetration in Los Angeles and San Francisco Bay Area markets. HIPAA-compliant cloud architecture investments cluster in Silicon Valley data centers supporting real-time glucose data transmission. San Diego hosts specialized biocompatibility engineering talent pools for implantable sensor development.
Florida
Florida sustains legacy meter-strip volume through large cash-pay and uninsured diabetes populations in Miami-Dade and Broward counties. Pharmacy benefit manager contracts dominate distribution channels across the state's retail pharmacy network. Tampa and Orlando concentrate durable medical equipment provisioning for Medicare Part B initial device access.
Illinois
Illinois anchors Midwest demand through Chicago's extensive endocrinology specialist networks and hospital system purchasing power. Remote patient monitoring CPT code utilization expands fastest among Illinois endocrinology practices seeking recurring revenue streams. The state's central logistics position supports wholesale distribution to surrounding markets.
New York
New York's dense academic medical center concentration in Manhattan and Long Island drives clinical trial recruitment for FDA premarket notification studies. Closed-loop artificial pancreas development programs cluster around Columbia and Mount Sinai research institutions. Upstate manufacturing facilities produce electrochemical biosensor components for national distribution.
United States Self-Monitoring Blood Glucose Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sensor manufacturing landscape. Vertically integrated chemical suppliers control membrane supply chains while algorithm developers license software platforms. The market structures around three archetypes: sensor-native manufacturers with captive production, legacy meter-strip suppliers defending pharmacy channel volume, and emerging entrants pursuing direct-to-consumer subscription models. Dominant competitive moves include backward integration into specialty chemical supply and strategic partnerships with telehealth platforms for remote monitoring service bundling.
Within the sensor-native tier, Abbott Laboratories and DexCom Inc exemplify vertically integrated production models. Roche Holding AG anchors the legacy consumables segment. These three firms occupy positions reflecting divergent strategic bets on continuous monitoring adoption versus test strip volume defense.
| Leading Market Players |
|---|
| Abbott Laboratories |
| DexCom Inc |
| Roche Holding AG |
| Medtronic PLC |
| LifeScan Inc |
| Ascensia Diabetes Care |
| Arkray Inc |
| PHC Holdings Corp |
| Senseonics |
| Others |
Value Network & Pricing Analysis
FDA biocompatibility requirements for long-term implantable sensors gate qualified supply to manufacturers with validated polyurethane membrane chemistry and foreign body response mitigation expertise, creating tiered access where premium-tier continuous glucose monitor pricing accrues to sensor-native incumbents while standard meter-strip producers compete on pharmacy benefit manager volume contracts with compressed margins.
Pricing Analysis
Bundled subscription models for continuous glucose monitor sensors now dominate pricing architecture, separating hardware provisioning from recurring sensor revenue streams that capture patient lifetime value. Three-tier pricing structure across premium factory-calibrated systems, standard Bluetooth-enabled patches, and economy legacy meters reflects differentiation by algorithm sophistication and hematocrit correction capability. Pricing pressure stems from Medicare Part B reimbursement rate compression for therapeutic continuous glucose monitors as CMS expands coverage to Type 2 non-insulin users. Cash-pay and uninsured patient segments in Florida and Texas exhibit highest price sensitivity, while Medicare Advantage populations in California accept premium subscription pricing for smartphone-integrated platforms.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 quality system certification requirements gate supplier qualification for electrochemical biosensor electrode production, concentrating qualified supply among domestic specialty chemical manufacturers and select German and Japanese precision coating operations. Platinum and palladium catalysts for disposable test strip electrodes draw from South African and Russian mining operations, while fluoropolymer sensor membranes source from captive production at Abbott and DexCom or limited third-party specialty polymer suppliers in the United States and Germany. Single-source membrane supply creates vulnerability to force majeure disruptions at polyurethane specialty chemical facilities. Distribution runs through durable medical equipment distributors for Medicare Part B initial provisioning, direct-to-consumer online channels for subscription sensor replenishment, and pharmacy retail networks for legacy strip volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as real-time metabolic data streams displace point-in-time measurements, with demand shifting toward factory-calibrated continuous glucose monitors that eliminate fingerstick confirmation requirements and command premium subscription pricing.
For Market Incumbents: Anchor market position through backward integration into specialty polyurethane membrane production and proprietary algorithm development that sustains factory-calibration accuracy advantages. Defend against emerging direct-to-consumer entrants by deepening pharmacy benefit manager contract exclusivity for Medicare Advantage channel control. Prioritize HIPAA-compliant cloud architecture investments that create compliance barriers for scaled competitors. For New Entrants and Emerging Players: Cash-pay Type 2 diabetes populations in Florida and Texas represent underserved buyer archetypes with limited continuous glucose monitor penetration due to formulary exclusion barriers. Target this segment through unbundled hardware pricing and pay-as-you-go sensor models that circumvent prior authorization requirements. Pursue white-label partnerships with telehealth platforms for remote patient monitoring service bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for sensor-native mid-cap specialists because FDA 510(k) clinical evidence requirements and biocompatibility engineering talent scarcity create durable moats against commoditization. Long-term viability favors manufacturers with vertically integrated membrane production and direct-to-consumer channel control. Watch CMS national coverage determination expansions for non-insulin Type 2 populations as the signal for inflection in addressable market size.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Factory-Calibrated Systems | Premarket notification pathways under 21 CFR 862.1355 accelerate time-to-market for sensor-native manufacturers with predicate device strategies. |
| CMS Reimbursement Strategy Expansion | National coverage determinations for therapeutic continuous glucose monitors unlock Medicare Part B access for 1.5 million additional Type 2 beneficiaries. |
| Hospital System Partnership for Inpatient Protocols | Epic and Cerner EHR integration agreements enable seamless glucose data flow into clinical workflows at academic medical centers. |
| Software Companion Development for Closed-Loop Control | Algorithm-driven insulin dosing recommendations automate therapeutic decision-making previously requiring physician interpretation. |
| Backward Integration into Membrane Manufacturing | Captive polyurethane and fluoropolymer production mitigates single-source supply risk and sustains cost advantages in disposable sensor economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with endocrinology practice administrators, biomedical engineers at sensor manufacturers, CMS policy specialists, and pharmacy benefit manager formulary directors with secondary validation against FDA 510(k) premarket notification databases, CMS national coverage determination records, and Medicare Advantage enrollment data. Bottom-up patient population estimates by diabetes type and insurance status triangulated against top-down manufacturer revenue disclosures and durable medical equipment distributor shipment records.
Segment-weighting approaches applied differential growth assumptions across product type, technology, end user, and distribution channel dimensions, with continuous glucose monitor adoption curves modeled separately for Type 1 intensive insulin users, Type 2 insulin-dependent patients, and Type 2 non-insulin populations. CAGRs derived from regression analysis of historical Medicare reimbursement expansion patterns and smartphone-integrated platform penetration rates across Texas, California, and Florida. Forecast inputs incorporated CMS policy trajectory for remote patient monitoring CPT codes and FDA draft guidance timelines for integrated continuous glucose monitor-insulin pump systems.
Inputs from FDA premarket notification databases and CMS coverage determination records were available through the study window; gaps in real-time continuous glucose monitor utilization data from Medicare claims introduce uncertainty bands around Type 2 non-insulin adoption assumptions. Forecasts reflect documented assumptions regarding reimbursement expansion velocity and biocompatibility engineering talent pipeline constraints. A model refresh is warranted upon material change in CMS national coverage determination scope or FDA interoperability standards for closed-loop artificial pancreas systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Indonesia Diabetes Care Devices Market