
 South Korea Insulin Infusion Pump Market | 2026-2036
South Korea Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Insulin Infusion Pump Market Insights
Cloud-based insulin dose analytics is repositioning how manufacturers monetize pump ecosystems beyond hardware sales. Medtronic Korea leverages its hospital-installed base to sustain service contracts across Seoul's major medical centers. Roche Diabetes Care Korea competes through integrated glucose monitoring workflows that anchor clinician loyalty. SOOIL Development dominates domestic manufacturing with localized pump production that controls cost structures for national reimbursement.
An insulin infusion pump is a programmable electromechanical device that delivers continuous subcutaneous insulin through a disposable infusion set, typically operating with basal rates of 0.025 units per hour and bolus increments of 0.1 units for precise glycemic control in diabetes management. Smart pumps with closed-loop algorithm integration are capturing premium margin pools as clinicians prioritize automated glucose regulation over manual basal programming. Patch pumps are extending fastest among younger Type 1 diabetes patients who value wearable discretion and reduced tubing burden during daily activities in Seoul and Busan.
MFSD medical device licensing requirements and National Health Insurance Service reimbursement schedules shape product entry timelines and pricing ceilings for foreign and domestic manufacturers alike. JIS-adjacent electrical safety standards and Bluetooth radio compliance protocols filter which connectivity features reach Korean patients. Stakeholders must track how MFDS real-world evidence requirements for software-upgradable pumps reshape clinical trial investments and post-market surveillance obligations.
Market Dynamics
Cloud-based insulin dose analytics is restructuring competitive economics by shifting manufacturer revenue from hardware margins toward recurring software subscriptions and data-driven service contracts across Seoul's tertiary hospital network.
Growth Catalysts
- MFDS real-world evidence pathways:Accelerated software-upgradable pump approvals compress clinical trial timelines for algorithm-enhanced devices. Domestic manufacturers leverage this framework to outpace foreign regulatory submissions.
- National Health Insurance Service reimbursement expansion:Broader coverage for closed-loop systems pulls premium pump adoption into outpatient diabetes centers. Patient out-of-pocket costs drop substantially under revised benefit schedules.
- Gyeonggi-do diabetes center cluster concentration:Aggregated patient volumes in this province generate economies of scale for pump training programs and remote monitoring infrastructure deployment.
Market Restraints
- Disposable infusion set cost volatility:Polymer supply chain exposure to petrochemical price swings compresses per-patient profitability for providers operating under fixed reimbursement rates.
- Bluetooth radio compliance complexity:JIS-adjacent electrical safety standards and radio frequency protocols filter connectivity features, delaying feature parity with EU and US devices by 12-18 months.
- Continuous glucose monitor substitution pressure:Standalone CGM systems with predictive alerts capture Type 2 diabetes patients who might otherwise advance to pump therapy, narrowing addressable market expansion.
Strategic Opportunities
- Busan metropolitan diabetes underpenetration:Lower pump density relative to Seoul creates whitespace for ambulatory care networks to build specialized glycemic management units with dedicated pump educators.
- AI-driven bolus prediction convergence:Integration of machine learning with existing pump hardware enables algorithm licensing revenue streams without full device replacement cycles.
- Pharmacy channel pump distribution pilots:Community pharmacy networks with certified diabetes educators expand access points beyond hospital-based procurement, reducing patient travel burden.
Industry Challenges
- Certified diabetes educator workforce scarcity:Specialized training requirements for pump initiation and troubleshooting outpace university program output, creating bottlenecked patient onboarding queues.
- Legacy hospital EMR integration friction:Proprietary data formats from pump cloud platforms require costly middleware development for seamless glucose data flow into institutional electronic records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Insulin Infusion Pump Market |
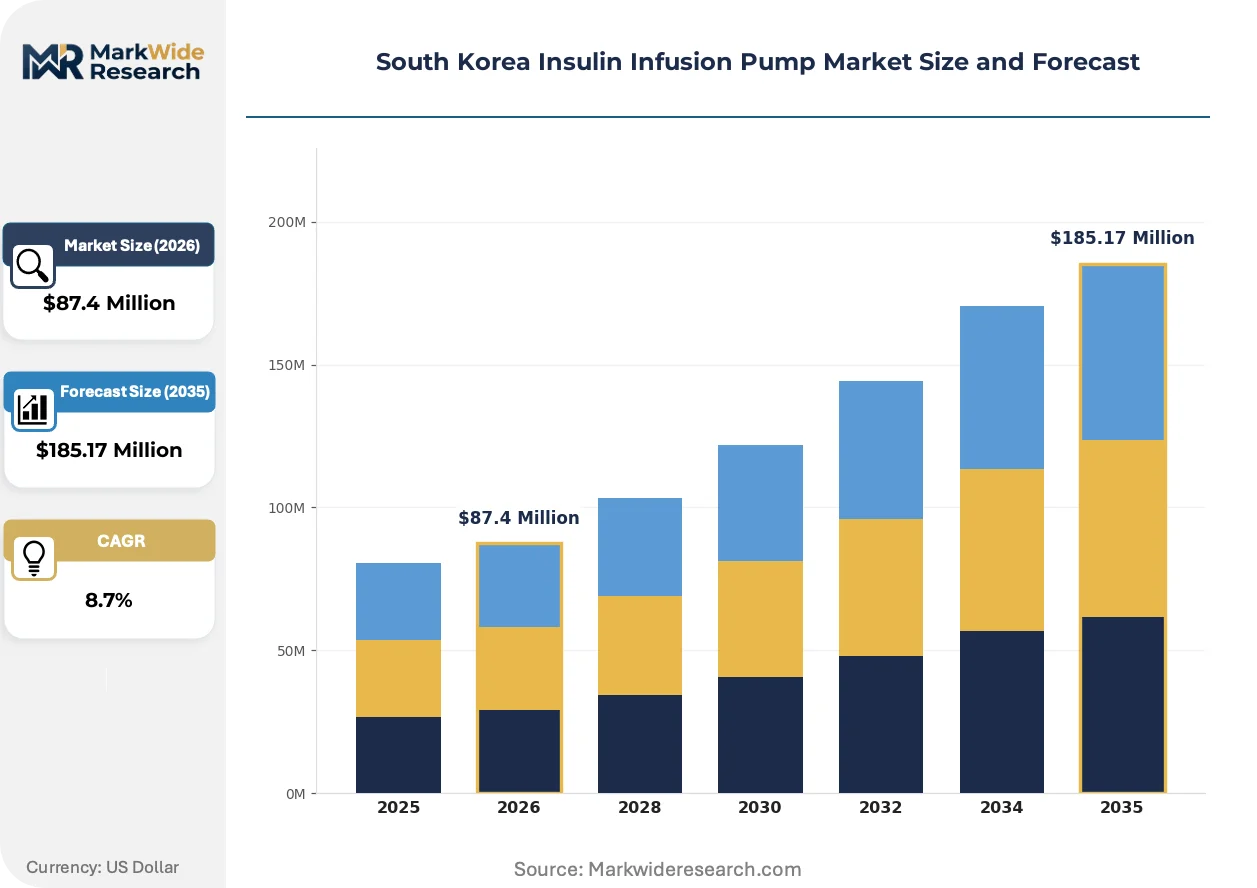
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Pump, Conventional Pump, Implantable Pump, Smart Pump Technology: Continuous Glucose Monitoring, Data Integration, Closed-Loop System, Bluetooth Connectivity Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pediatric Diabetes End User: Hospitals, Homecare, Clinics, Diabetes Centers |
| Companies Covered | Medtronic Korea, Roche Diabetes Care Korea, Insulet Corporation, Ypsomed Korea, Tandem Diabetes Care, Ascensia Diabetes Care, DexCom, Abbott Laboratories, SOOIL Development, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Insulin Infusion Pump Market Trends and Innovations
Patch pump form factors are capturing preference share among younger Type 1 diabetes cohorts who prioritize wearable discretion and tubing elimination during school and workplace activities in Seoul and Busan.
Closed-loop algorithm integration is expanding into premium pump tiers as MFDS establishes clearer software-as-medical-device classification pathways. Tertiary hospitals in Seoul's Gangnam and Jongno districts are piloting these systems for inpatient glycemic control, with endocrinology departments negotiating bundled hardware-service contracts that span three-year replacement cycles. This technology is expanding into subscription revenue models that decouple manufacturer economics from device replacement frequency.
MFDS post-market surveillance requirements for connected pumps now mandate cybersecurity incident reporting and software update documentation. Manufacturers must maintain domestic quality management system auditors and localized adverse event databases. Small and mid-sized foreign suppliers face disproportionate compliance burden, advantaging domestic producers with established MFDS inspection relationships.
Younger patients are bypassing traditional hospital-based pump procurement through direct-to-consumer telehealth platforms that coordinate remote prescription, device delivery, and virtual educator sessions. This channel compression disrupts longstanding relationships between Seoul's major medical centers and incumbent suppliers. The shift is most pronounced among employed adults aged 25-40 in the capital region who prioritize scheduling flexibility over institutional continuity.
South Korea Insulin Infusion Pump Market Segmentation
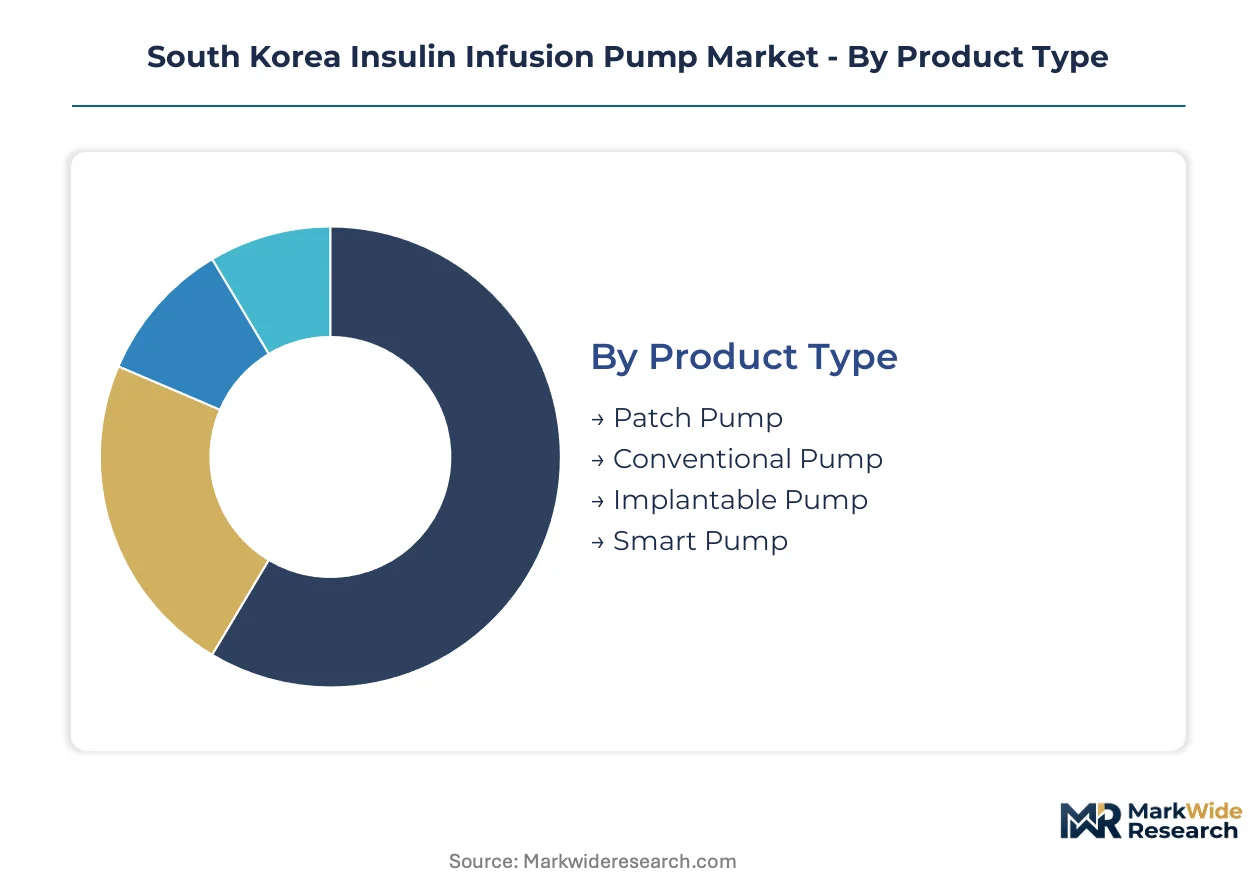
Insulin infusion pump segmentation in South Korea reflects competing pressures between reimbursement constraints, MFDS regulatory pathways, and patient lifestyle preferences. Manufacturers must align product portfolios across four intersecting dimensions where technology sophistication, care setting economics, and disease severity determine commercial viability.
Product Type:
Form factor specifications dictate reimbursement tier placement and patient onboarding complexity within National Health Insurance Service schedules.
- Smart Pump:Algorithm-enabled devices with automated basal adjustment and predictive low-glucose suspend functionality. Seoul's tertiary hospitals in Gangnam and Jongno districts prioritize these systems for bundled three-year service contracts that merge hardware procurement with continuous educator support.
- Patch Pump:Tubeless wearable units with on-body insulin reservoir and disposable pod design. Younger Type 1 patients in Busan and Seoul select this format for workplace discretion and elimination of tubing snags during commutes on metropolitan subway networks.
- Conventional Pump:Traditional tethered devices with external reservoir and infusion set tubing. Remains the volume workhorse for cost-sensitive patients in Gyeonggi-do diabetes centers where reimbursement ceilings favor established hardware economics.
- Implantable Pump:Surgically placed intraperitoneal delivery systems for severe insulin resistance cases. Limited to specialized metabolic surgery units at Samsung Medical Center and Asan Medical Center with dedicated explant-replacement surgical protocols.
Conventional Pump leads on scale; Patch Pump leads on momentum.
Technology:
Connectivity and automation capabilities separate premium reimbursement tiers from basic coverage categories under MFDS software-as-medical-device classifications.
- Closed-Loop System:Integrated sensor-pump algorithms that autonomously modulate insulin delivery based on real-time glucose trajectories. MFDS accelerated approval pathways for software-upgradable pumps have compressed launch timelines for these systems relative to foreign regulatory submissions.
- Continuous Glucose Monitoring:Real-time interstitial glucose sensing with trend arrow displays and predictive alert thresholds. Endocrinology departments at Severance Hospital and Seoul National University Hospital require CGM compatibility as a non-negotiable procurement specification.
- Bluetooth Connectivity:Wireless data transmission to smartphone applications and cloud analytics platforms. JIS-adjacent radio frequency compliance protocols delay feature parity with EU and US devices by 12-18 months.
- Data Integration:Interoperability with hospital EMR systems and remote monitoring dashboards. Proprietary data formats from pump cloud platforms require costly middleware development for seamless glucose data flow into institutional electronic records at Seoul's major medical centers.
Continuous Glucose Monitoring dominates current installations; Closed-Loop System climbs the fastest toward standard-of-care status.
Application:
Disease severity and patient age cohorts determine pump eligibility criteria under National Health Insurance Service benefit schedules and physician prescribing patterns.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring exogenous insulin replacement. Absolute pump indication with highest reimbursement coverage rates drives concentrated demand in pediatric and young adult populations across Seoul's tertiary network.
- Type 2 Diabetes:Progressive insulin deficiency with residual beta-cell function. Expanding pump adoption among intensified insulin regimens in Gyeonggi-do diabetes centers as oral agent failure accelerates.
- Pediatric Diabetes:Age-specific glycemic targets and caregiver-mediated device management. Dedicated pump educators at Asan Medical Center and Samsung Medical Center maintain specialized training protocols for school-age initiation.
- Gestational Diabetes:Hyperglycemia during pregnancy requiring tight glycemic control. Limited pump penetration due to temporary condition duration and preference for multiple daily injection flexibility.
Type 1 Diabetes anchors absolute volume; Type 2 Diabetes gains share fastest as intensification thresholds shift.
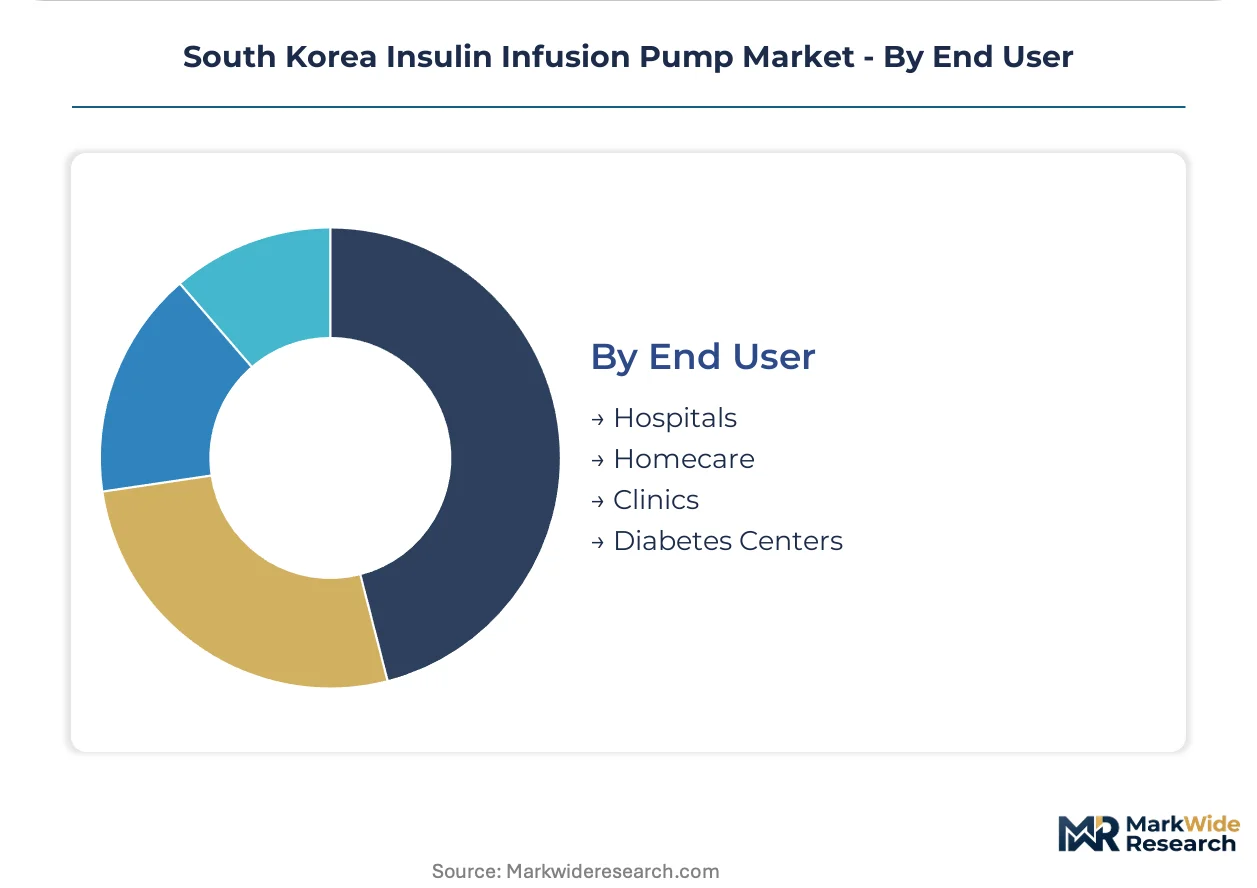
End User:
Care setting economics and reimbursement flow structures determine procurement decision-makers and patient access pathways.
- Hospitals:Tertiary academic medical centers with inpatient glycemic management protocols. Procurement departments at Seoul National University Hospital and Severance Hospital negotiate multi-year bundled contracts spanning device, consumables, and educator services.
- Diabetes Centers:Specialized outpatient facilities with certified educator staffing. Gyeonggi-do cluster concentration generates economies of scale for pump training programs and remote monitoring infrastructure deployment.
- Homecare:Direct-to-patient delivery with telehealth-coordinated virtual educator sessions. Younger employed adults in Seoul's capital region bypass traditional hospital procurement through telehealth platforms prioritizing scheduling flexibility.
- Clinics:Community-based endocrinology practices with limited educator bandwidth. Pharmacy channel pump distribution pilots with certified diabetes educators are expanding access points beyond hospital-based procurement in Busan metropolitan area.
Hospitals command premium contract values; Homecare shows steepest expansion trajectory as channel compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's pump penetration trails South Korea despite comparable diabetes prevalence, while Taiwan's reimbursement gaps constrain algorithm-enabled device uptake. These disparities illuminate how regulatory velocity and insurance design shape regional adoption trajectories.
Seoul Capital Area
Gangnam and Jongno district tertiary hospitals drive algorithm-enabled pump procurement through bundled service contracts. MFDS accelerated approval pathways for software-upgradable devices compress launch timelines versus foreign regulatory submissions. Samsung Medical Center and Severance Hospital anchor the national glycemic management infrastructure.
Busan-Ulsan
Metropolitan pump density lags Seoul by approximately forty percent, creating whitespace for ambulatory network expansion. National Health Insurance Service reimbursement reforms pull closed-loop systems into outpatient coverage. Pusan National University Hospital and regional diabetes centers build dedicated pump educator programs.
Gyeonggi-do
Diabetes center clustering generates economies of scale for training infrastructure and remote monitoring deployment. Provincial reimbursement ceilings favor conventional pump hardware economics over premium tier adoption. Suwon and Seongnam host the densest concentration of certified diabetes educators outside Seoul.
Daegu-Gyeongbuk
Manufacturing cost advantages attract domestic pump component suppliers and assembly operations. Kyungpook National University Hospital maintains specialized protocols for pediatric pump initiation. Regional procurement departments negotiate multi-year consumables contracts that stabilize per-patient economics.
Daejeon-Sejong
Government research institutes pilot next-generation closed-loop algorithms through public-private partnerships. Korea Advanced Institute of Science and Technology collaborations accelerate MFDS real-world evidence generation. Sejong administrative city concentration streamlines regulatory consultation pathways for device manufacturers.
South Korea Insulin Infusion Pump Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with foreign multinationals dominating algorithm-enabled tiers while domestic fabricators capture conventional pump volume. The vendor base concentrates around three strategic archetypes: integrated glucose management platform providers, localized hardware manufacturers with cost-optimized production, and patch pump specialists targeting younger patient cohorts. Scale-driven consolidation and algorithm licensing partnerships represent the dominant competitive moves reshaping positioning.
Within the integrated platform tier, Medtronic Korea and Roche Diabetes Care Korea exemplify service-contract economics that merge hardware procurement with continuous clinical support. SOOIL Development anchors domestic manufacturing capabilities with localized production controlling cost structures for national reimbursement compliance. Among patch pump specialists, Insulet Corporation occupies a position targeting tubing-elimination preferences among employed adults in Seoul and Busan.
| Leading Market Players |
|---|
| Medtronic Korea |
| Roche Diabetes Care Korea |
| Insulet Corporation |
| Ypsomed Korea |
| Tandem Diabetes Care |
| Ascensia Diabetes Care |
| DexCom |
| Abbott Laboratories |
| SOOIL Development |
| Others |
Pricing and Supply Chain Analysis
Seoul's tertiary hospital procurement departments concentrate purchasing power for algorithm-enabled pumps, anchoring subscription-based service contracts that bundle hardware, software, and educator support across three-year replacement cycles. This buyer concentration enables manufacturers to sustain premium pricing tiers while conventional pump volumes compete on cost structures optimized for National Health Insurance Service reimbursement ceilings.
Pricing Analysis
Capacity additions in Gyeonggi-do province are reshaping price floors for domestically manufactured conventional pumps. Three-tier pricing structure across premium closed-loop systems, standard smart pumps, and economy conventional devices separates reimbursement tiers under MFDS classifications. Price differentiation rests on MFDS software-as-medical-device certification level and bundled educator service intensity. Cost compression in the economy tier is intensifying as SOOIL Development scales localized production. Pediatric diabetes centers show least price sensitivity due to absolute clinical indication, while Type 2 intensification patients in provincial diabetes centers exhibit highest out-of-pocket cost consciousness.
Supply Chain Analysis
MFDS domestic-content requirements for medical device licensing are reshaping sourcing patterns toward Korean component suppliers. Manufacturing concentrates in South Korea, China, and Japan for precision motors, polymer infusion sets, and glucose sensor substrates. Raw material dependencies draw from petrochemical-derived polymers, lithium-ion cells, and semiconductor-grade silicon substrates. Single-source vulnerability runs through specialized insulin-compatible polymers subject to petrochemical price volatility. Distribution runs through hospital procurement committees, Gyeonggi-do diabetes center networks, and emerging pharmacy channel pilots with certified educators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea insulin infusion pump market functions as a regulatory compounder where MFDS real-world evidence pathways for software-upgradable devices accelerate approval timelines and expand addressable premium tiers faster than foreign regulatory submissions.
For Market Incumbents: Acquire certified diabetes educator training capacity to secure bundled service contract renewals across Seoul's tertiary hospital network. Lock in multi-year consumables supply agreements with Gyeonggi-do diabetes centers to defend against patch pump substitution among younger Type 1 cohorts. Deepen backward integration into polymer infusion set manufacturing to buffer petrochemical cost volatility compressing per-patient profitability under fixed reimbursement rates. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Busan-Ulsan metropolitan area creates whitespace for ambulatory care networks building specialized glycemic management units. Target pharmacy channel distribution with certified educator partnerships to bypass entrenched hospital procurement relationships in Seoul. Position patch pump form factors for employed adults aged 25-40 prioritizing wearable discretion and scheduling flexibility over institutional continuity. For Investors and Strategic Acquirers: Integrated glucose management platform providers are the most active acquirer in this space, consolidating algorithm licensing capabilities and cloud analytics infrastructure. Long-term viability hinges on recurring software subscription revenue decoupling manufacturer economics from hardware replacement cycles. Acquisition target archetype: domestic manufacturers with established MFDS inspection relationships and scalable educator training programs. Monitor MFDS cybersecurity incident reporting mandates as signal for compliance cost escalation disadvantaging smaller foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Software-as-Medical-Device Certification | Accelerated approval timelines compress competitive launch windows for algorithm-enhanced pumps. |
| Hospital System Partnership | Bundled three-year service contracts at Samsung Medical Center and Severance Hospital anchor revenue visibility. |
| Software Companion Development | Cloud-based insulin dose analytics platforms shift economics toward recurring subscription revenue streams. |
| Reimbursement Strategy | National Health Insurance Service closed-loop expansion pulls premium adoption into outpatient diabetes centers. |
| Backward Integration into Infusion Sets | Domestic polymer supply control buffers petrochemical price volatility under fixed reimbursement rates. |
Research Methodology
Multiple input streams — structured interviews with endocrinology department heads, hospital procurement managers, and certified diabetes educators; MFDS regulatory filing databases and National Health Insurance Service reimbursement schedules; and customs records for insulin pump component imports — were reconciled through bottom-up patient volume modeling and top-down expenditure triangulation. Secondary validation drew from hospital procurement databases, GPO contracts, and MFDS adverse event reporting systems. Cross-referencing manufacturer service contract disclosures with educator staffing ratios at Seoul's tertiary hospitals tested primary interview findings.
Historical adoption curves were cross-referenced against expert panel inputs on MFDS pathway evolution and reimbursement reform timing. Segmentation modeling across product type, technology tier, disease application, and end-user setting generated volume and value outputs across the analysis window. CAGRs were derived from algorithm diffusion assumptions, replacement cycle dynamics, and provincial expansion patterns. Forecast inputs included MFDS inspection capacity constraints and certified diabetes educator program graduation rates.
Caveats apply where MFDS cybersecurity mandate enforcement intensity or National Health Insurance Service benefit schedule revisions could materially shift the outlook for software-upgradable pump economics. Forecasts embed assumptions about educator workforce expansion and polymer supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Thailand Diabetes Care Devices Market
Diabetes Care
Digital Diabetes Market