
 Vietnam Oral Anti-Diabetic Drug Market | 2026-2036
Vietnam Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Oral Anti-Diabetic Drug Market Insights
Patient adherence programs is hardening as a distinct revenue layer alongside pill sales. AstraZeneca leverages its SGLT-2 inhibitor portfolio to sustain premium positioning in urban hospital networks. Novo Nordisk anchors its presence through deep engagement with endocrinology specialists across northern and central provinces.
Vietnam oral anti-diabetic drugs encompass chemically synthesized hypoglycemic agents administered perorally to reduce blood glucose in diabetic patients, with formulations ranging from immediate-release metformin tablets to extended-release DPP-4 inhibitor capsules requiring precise dissolution profiles. These therapeutics serve to delay diabetic complications and reduce insulin dependency in Type 2 diabetes management. Metformin occupies the largest volume share as the foundational first-line therapy, while SGLT-2 inhibitors represent the fastest-expanding margin pool driven by cardiovascular outcome benefits. Retail pharmacies control the dominant distribution channel for chronic refill prescriptions, though hospital initiation protocols govern initial therapy selection.
Vietnam's Ministry of Health and the Drug Administration of Vietnam enforce bioequivalence requirements and periodic price controls that compress margins on older generics while creating access barriers for novel molecules. The country's national health insurance scheme, managed by Vietnam Social Security, determines reimbursement tiers that directly shape physician prescribing patterns and patient out-of-pocket exposure. Stakeholders must monitor evolving local clinical trial requirements and domestic manufacturing incentives as policy levers that will determine which drug classes achieve sustainable market access.
Market Dynamics
Hospital formulary committees in Vietnam are accelerating SGLT-2 inhibitor adoption ahead of national reimbursement updates, compressing the window for older DPP-4 inhibitors to defend their positions in urban prescribing networks.
Growth Catalysts
- Cardiovascular Outcome Trials:Hospital cardiology departments are expanding SGLT-2 inhibitor protocols based on renal and heart failure data, pulling prescribing away from sulfonylureas in Ho Chi Minh City tertiary centers.
- Vietnam Social Security Reimbursement Expansion:The national health insurance scheme is widening coverage for second-line oral therapies, reducing out-of-pocket burdens that previously blocked patient access to newer drug classes.
- Red River Delta Urbanization:Population density concentration around Hanoi is creating diabetes patient pools large enough to justify dedicated endocrinology wards and specialized pharmacy services.
Market Restraints
- Active Pharmaceutical Ingredient Import Dependency:Domestic formulation manufacturers rely on Chinese and Indian API suppliers, exposing margin structures to currency volatility and cross-border logistics disruptions.
- Drug Administration of Vietnam Bioequivalence Requirements:Stringent local clinical trial mandates for generic substitution create 18-24 month registration delays that freeze out low-cost competitors.
- Insulin Pricing Arbitrage:Subsidized human insulin through international procurement channels undercuts oral therapy cost advantages in rural provinces where injection stigma has weakened.
Strategic Opportunities
- Central Highlands Underservice:Dak Lak and Gia Lai provinces show diabetes prevalence above national averages with specialist-to-patient ratios below one-tenth of Hanoi levels, creating whitespace for telemedicine-linked pharmacy networks.
- Fixed-Dose Combination Formulations:Metformin-SGLT-2 inhibitor single-pill products align with Vietnam Ministry of Health adherence targets and simplify procurement for district hospital formularies.
- Domestic Manufacturing Incentives:Special economic zone tax holidays for pharmaceutical production are attracting contract manufacturers to establish formulation facilities near Ho Chi Minh City.
Industry Challenges
- Clinical Pharmacist Shortage:Vietnam's pharmacy education pipeline produces insufficient specialists for medication therapy management programs that hospitals require for chronic disease accreditation.
- Cold Chain Integrity for Stability Samples:Bioequivalence studies demand temperature-controlled storage infrastructure that provincial trial sites lack, forcing sponsors to centralize testing in Hanoi and Ho Chi Minh City at elevated cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Oral Anti-Diabetic Drug Market |
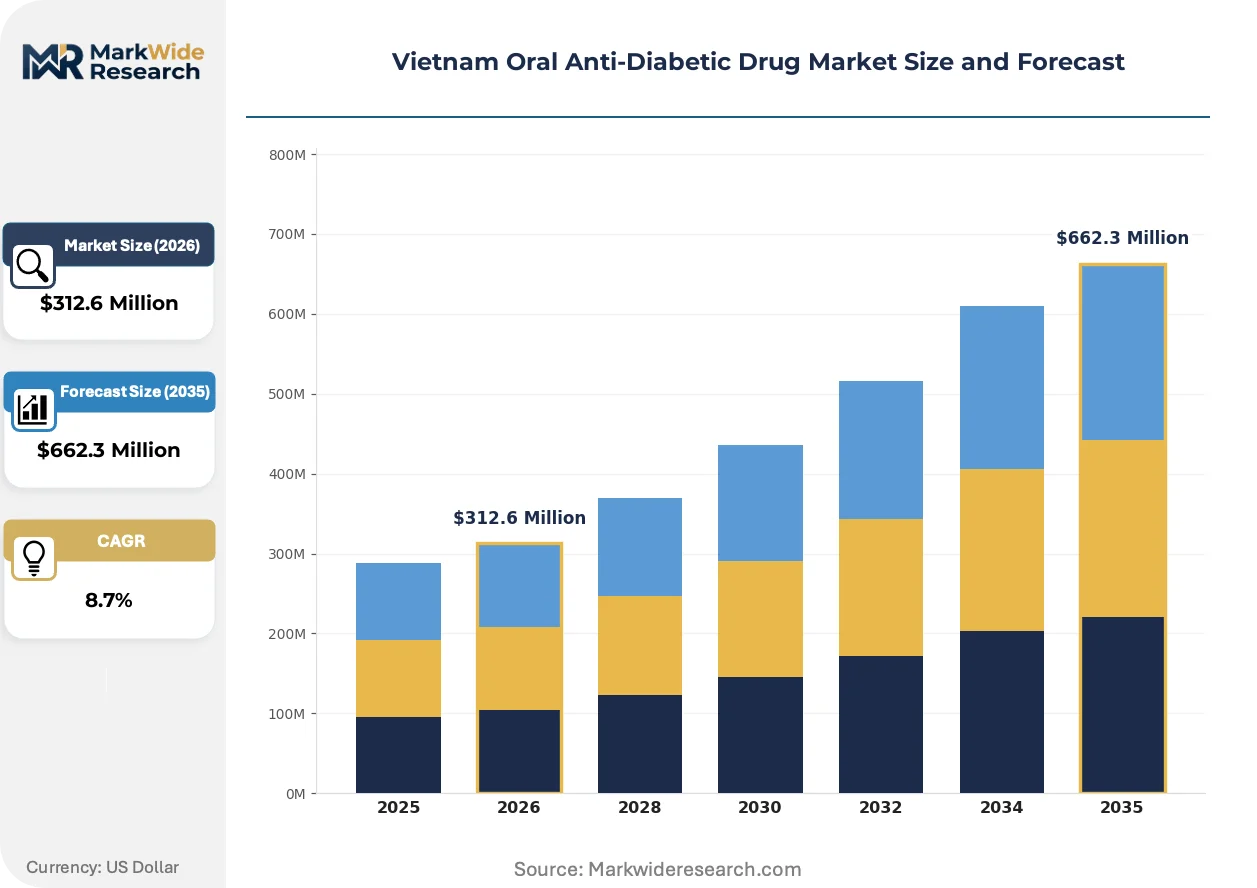
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT-2 Inhibitors Delivery Mode: Tablet, Capsule, Liquid, Powder End User: Hospitals, Clinics, Retail Pharmacies, Online Pharmacies Patient Type: Type 2 Diabetes, Prediabetes, Elderly Patients, Obese Patients |
| Companies Covered | AstraZeneca, Eli Lilly and Company, Novo Nordisk, Sanofi, Pfizer, Merck And Co, Takeda, Astellas Pharma, Janssen Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Oral Anti-Diabetic Drug Market Trends and Innovations
Digital therapeutics and connected delivery devices are penetrating Vietnam's diabetes management ecosystem, altering how pharmaceutical firms structure patient support programs and physician engagement.
Extended-release metformin formulations with modified dissolution profiles are absorbing volume from immediate-release generics in hospital procurement tenders. Endocrinology departments at Cho Ray Hospital and Bach Mai Hospital are specifying these products in standard treatment pathways. The technology is absorbing margin compression pressure by creating differentiation where bioequivalence alone cannot command price premiums.
Vietnam's Ministry of Health circulars on drug pricing transparency are forcing manufacturers to disclose transfer pricing documentation for imported active ingredients. Domestic generic producers face compressed allowable markups on older molecules. Multinational innovators are responding by accelerating local clinical trial investments to secure data exclusivity windows before compulsory licensing threats materialize.
Retail pharmacy chains in Ho Chi Minh City are unbundling chronic disease management from pure product dispensing. Pharmacity and Long Chau stores now offer HbA1c testing and medication synchronization services that capture refill loyalty. This model is displacing independent pharmacy relationships in urban corridors where patient mobility and insurance portability have weakened geographic prescribing lock-in.
Vietnam Oral Anti-Diabetic Drug Market Segmentation
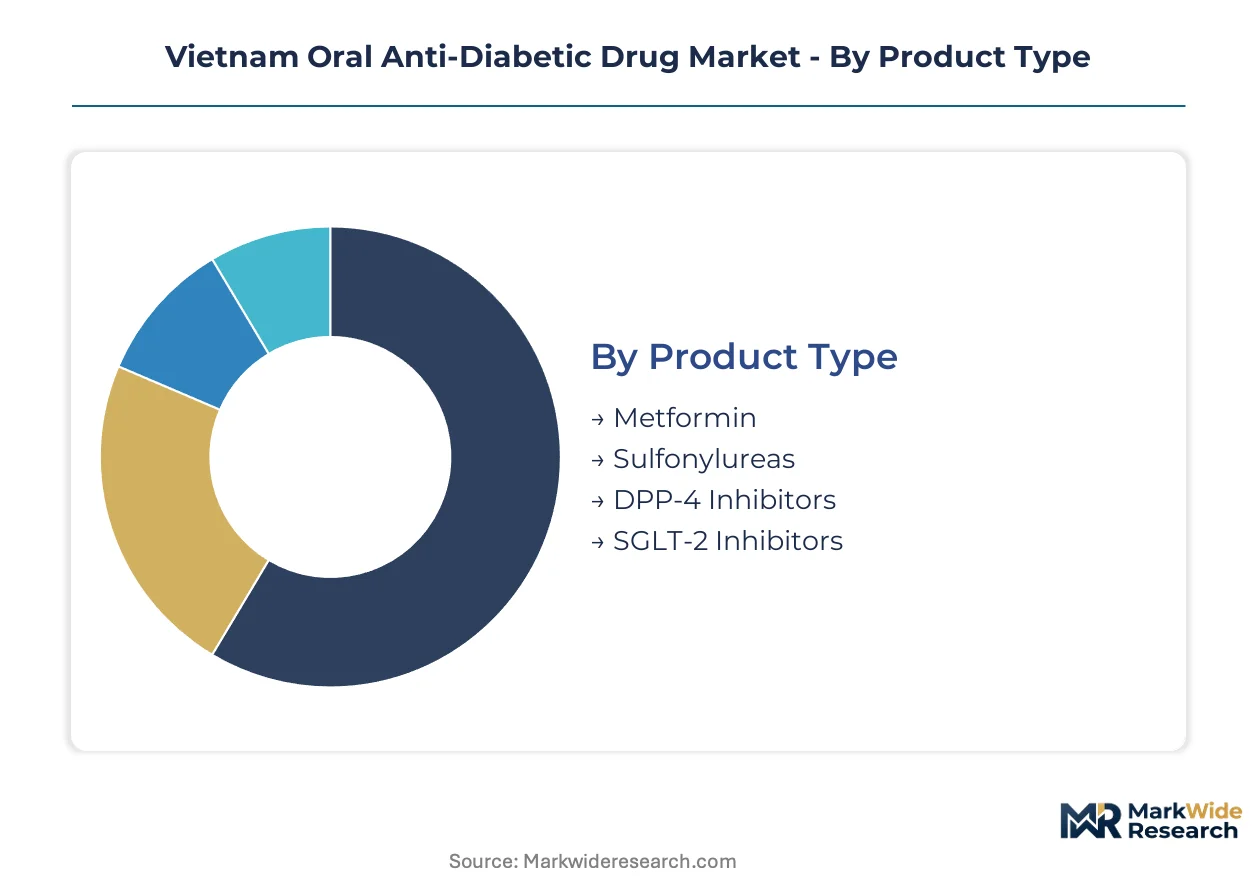
Segmentation reveals how capital deployment, regulatory exposure, and patient access pathways diverge across drug classes and distribution channels in Vietnam's oral anti-diabetic market. Manufacturers must align portfolio investments with the specific reimbursement and procurement mechanics governing each segment.
Product Type:
Capital intensity varies sharply across drug classes, with novel molecule development demanding sustained R&D outlays while generic manufacturing rewards scale economies.
- Metformin:Immediate-release and extended-release formulations of this biguanide dominate procurement volumes through Vietnam Social Security tenders. Demand concentrates in district hospital formularies across the Red River Delta where first-line therapy protocols mandate its use.
- SGLT-2 Inhibitors:Sodium-glucose cotransporter-2 inhibitors require substantial clinical trial investment to satisfy Drug Administration of Vietnam bioequivalence standards. Ho Chi Minh City tertiary hospitals are expanding cardiovascular outcome-based protocols that pull prescribing toward this class.
- Sulfonylureas:Glipizide and glimepiride formulations face margin compression from centralized procurement pricing.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors defend position in second-line combination therapy through established endocrinology specialist relationships.
Most installed capacity flows through Metformin. Expansion is steepest in SGLT-2 Inhibitors.
Delivery Mode:
Manufacturing infrastructure requirements determine competitive entry barriers, with solid dosage forms rewarding high-throughput investments and liquid formats demanding specialized containment systems.
- Tablet:Immediate-release and modified-release compressed dosage forms absorb the majority of Vietnam Social Security reimbursement expenditure. Bach Mai Hospital and Cho Ray Hospital procurement specifications favor scored tablets for dose titration flexibility.
- Capsule:Hard gelatin and HPMC capsules serve extended-release DPP-4 inhibitor formulations with precise dissolution profiles. District hospital pharmacies in Da Nang and Can Tho favor blister-packaged capsules for stability in tropical storage conditions.
- Liquid:Oral solutions address pediatric and geriatric populations with swallowing difficulties.
- Powder:Sachet formulations for metformin suspension serve rural provinces with intermittent cold chain access.
Tablet manufacturing commands the greatest fixed asset base. Capsule capacity is expanding most quickly to serve hospital formulary upgrades.
End User:
Channel economics diverge based on who controls prescribing authority and bears reimbursement risk.
- Hospitals:Tertiary and district medical facilities govern initial therapy selection through formulary committees and specialist consultation requirements. Vietnam Social Security direct settlement mechanisms concentrate high-value prescribing in Hanoi and Ho Chi Minh City hospital networks.
- Retail Pharmacies:Pharmacity and Long Chau chains dominate chronic refill capture through medication synchronization programs. Urban corridors around Hai Phong and Bien Hoa show the densest pharmacy network penetration.
- Clinics:Provincial endocrinology clinics serve as referral gateways to hospital care.
- Online Pharmacies:E-prescription platforms are gaining regulatory clarity for chronic disease medication delivery.
Hospital procurement channels handle the greatest prescription value. Retail pharmacy expansion is gaining share fastest in urban chronic disease management.
Patient Type:
Therapy intensity and complication risk profiles shape product mix and pricing power across patient populations.
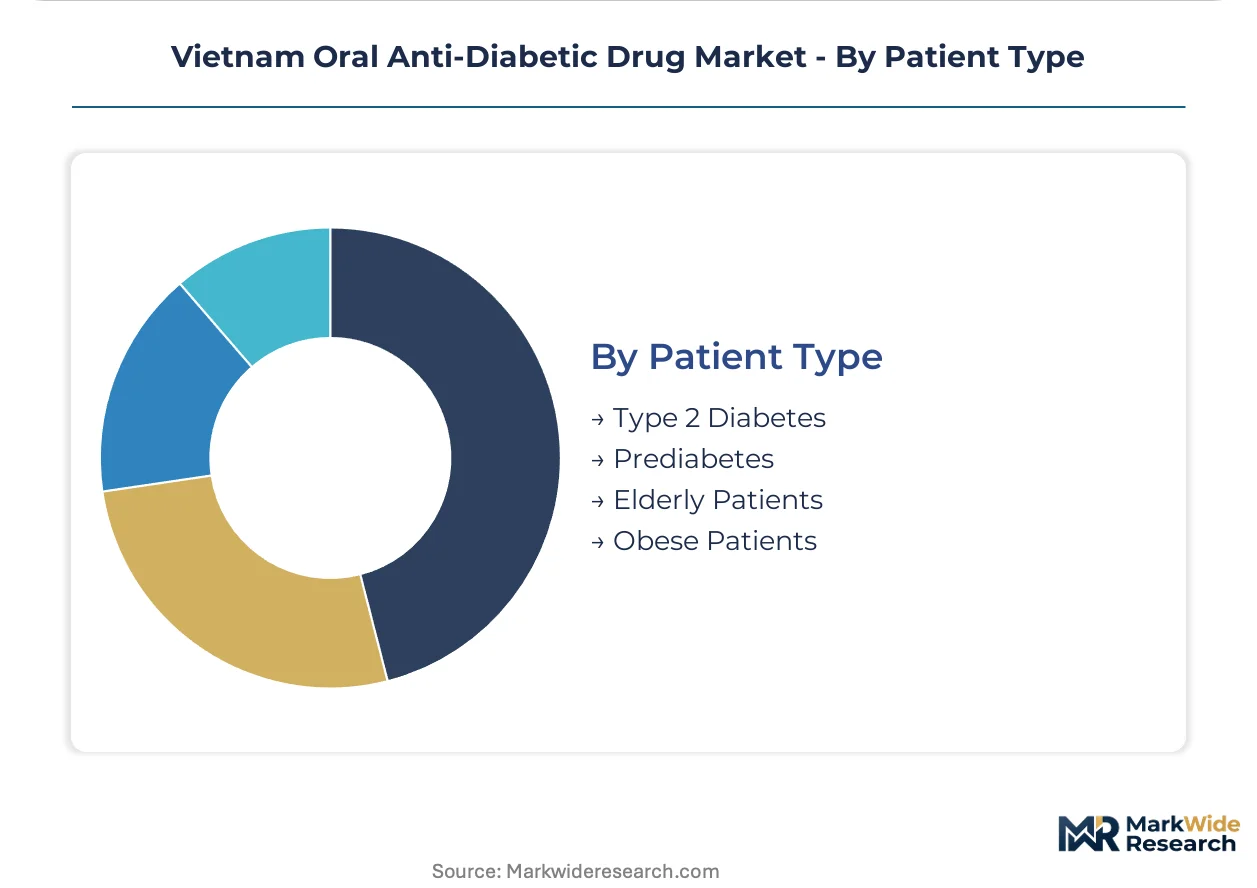
- Type 2 Diabetes:Established disease patients requiring progressive combination therapy generate the majority of oral drug consumption. Central Highlands provinces show prevalence rates exceeding national averages with limited specialist access.
- Obese Patients:BMI-driven prescribing protocols favor SGLT-2 inhibitors and metformin combinations with weight-neutral or weight-loss profiles. Endocrinology departments at Hue Central Hospital are refining obesity-stratified treatment pathways.
- Elderly Patients:Renal function monitoring requirements complicate sulfonylurea use in geriatric populations.
- Prediabetes:Lifestyle intervention pharmacotherapy remains limited by reimbursement constraints.
Type 2 Diabetes patients account for the largest treated population. Obese Patient segmentation is climbing the fastest as cardiovascular outcome data reshapes prescribing algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic formulation facilities cluster where bioequivalence trial costs and special economic zone incentives create arbitrage against import-dependent supply chains. Vietnam's pharmaceutical production geography reflects this regulatory-cost gradient.
Ho Chi Minh City
Specialist endocrinology wards at Cho Ray Hospital and district medical centers drive demand for SGLT-2 inhibitors and extended-release metformin. The Drug Administration of Vietnam processes the majority of bioequivalence study approvals through offices here. Industrial parks in Binh Duong and Dong Nai provinces host contract manufacturing organizations serving both domestic and export markets.
Red River Delta
Hanoi anchors the northern prescribing network through Bach Mai Hospital and Vietnam Social Security's largest direct settlement operations. Population density around the capital supports dedicated diabetes clinics with medication therapy management accreditation. Domestic generic producers concentrate formulation capacity in Hung Yen and Bac Ninh provinces to access tax holidays.
Central Coast
Hue Central Hospital refines obesity-stratified treatment pathways that favor weight-neutral oral therapies. Da Nang serves as the procurement hub for Quang Nam and Quang Ngai provinces with blister-packaged capsule demand driven by tropical storage requirements. Provincial health departments here face tighter Vietnam Social Security reimbursement caps than northern or southern counterparts.
Central Highlands
Dak Lak and Gia Lai provinces exhibit diabetes prevalence rates above national averages with specialist-to-patient ratios below one-tenth of Hanoi levels. The Ministry of Health's rural health insurance expansion programs are slowly penetrating these areas. Telemedicine-linked pharmacy networks represent the primary commercial access model given infrastructure constraints.
Mekong Delta
Can Tho coordinates chronic disease management for An Giang and Kien Giang provinces through centralized pharmacy procurement. District hospitals here rely heavily on immediate-release metformin from Vietnam Social Security tenders. Cold chain limitations restrict access to stability-sensitive formulations in Ca Mau and Bac Lieu sub-regions.
Vietnam Oral Anti-Diabetic Drug Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational innovators defending premium positioning in urban hospital networks while domestic formulators capture volume through centralized procurement. The market exhibits moderate concentration at the top tier with fragmentation below. Three archetypes dominate: cardiovascular outcome data specialists, broad diabetes portfolio holders, and domestic generic scale players. Competitive moves center on local clinical trial investments for bioequivalence data exclusivity and fixed-dose combination launches that simplify district hospital procurement.
Among multinational innovators, AstraZeneca and Novo Nordisk anchor the premium tier through specialist engagement and cardiovascular outcome positioning. Sanofi occupies a position bridging innovative and established therapy segments. Domestic generic manufacturers compete through Vietnam Social Security tender participation and extended-release formulation differentiation where bioequivalence alone cannot command price premiums.
| Leading Market Players |
|---|
| AstraZeneca |
| Eli Lilly and Company |
| Novo Nordisk |
| Sanofi |
| Pfizer |
| Merck And Co |
| Takeda |
| Astellas Pharma |
| Janssen Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Vietnam's Ministry of Health circulars on drug pricing transparency are gating qualified supply access and premium-tier pricing authorization through mandatory transfer pricing disclosure for imported active ingredients. Domestic generic producers face compressed allowable markups on older molecules while multinational innovators secure data exclusivity windows through accelerated local clinical trial investments.
Pricing Analysis
Capacity additions in Binh Duong and Dong Nai provinces are reshaping price floors for extended-release metformin formulations. Three-tier pricing structure across premium, standard, and economy levels separates cardiovascular outcome-validated SGLT-2 inhibitors from bioequivalent generics and subsidized human insulin alternatives. Cost compression in the sulfonylurea segment is intensifying because Vietnam Social Security centralized procurement tenders favor lowest-compliant bids. District hospital procurement officers exhibit the highest price sensitivity, while tertiary center formulary committees prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Domestic-content mandates through special economic zone tax holidays are reshaping sourcing decisions for formulation manufacturers establishing production near Ho Chi Minh City. Active pharmaceutical ingredient supply draws from China and India, with secondary inputs from South Korea and Japan for specialized excipients. Key raw material dependencies include metformin hydrochloride, dapagliflozin intermediates, and modified-release polymers. Single-source vulnerability concentrates in Indian API suppliers subject to currency volatility. Distribution runs through Vietnam Social Security direct settlement mechanisms for hospital procurement, with retail pharmacy chains capturing urban refill volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's oral anti-diabetic market operates as a geographic-arbitrage play where formulation costs in Hung Yen and Bac Ninh provinces undercut import-dependent supply chains by 15-25 percent after tax holiday benefits. The Red River Delta corridor offers regulatory pathway advantages through proximity to Drug Administration of Vietnam headquarters and Bach Mai Hospital's formulary influence.
For Market Incumbents: Extend cardiovascular outcome data advantages into fixed-dose combination launches that simplify district hospital procurement protocols. Deepen specialist engagement at Cho Ray Hospital and Bach Mai Hospital to defend against SGLT-2 inhibitor commoditization. Backward integration into API sourcing mitigates margin pressure from Chinese supplier currency volatility.
For New Entrants and Emerging Players: Begin with telemedicine-linked pharmacy networks targeting Dak Lak and Gia Lai provinces where specialist-to-patient ratios lag Hanoi by an order of magnitude. The Central Highlands whitespace offers the most penetrable geography given diabetes prevalence above national averages and limited incumbent presence. A go-to-market angle anchored on medication therapy management accreditation addresses the clinical pharmacist shortage constraining hospital chronic disease programs.
For Investors and Strategic Acquirers: Roll-up economics work for domestic generic scale players because Vietnam Social Security tender participation rewards volume concentration and extended-release formulation differentiation. The five-to-ten year viability window favors manufacturers with captive API supply or special economic zone production assets. Watch for Drug Administration of Vietnam bioequivalence study approval velocity as the inflection indicator signaling regulatory access tightening or loosening.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Local bioequivalence studies secure data exclusivity windows before compulsory licensing threats materialize at Drug Administration of Vietnam. |
| Fixed-Dose Combination Launch | Metformin-SGLT-2 inhibitor single-pill products align with Ministry of Health adherence targets and simplify district hospital formulary procurement. |
| Backward Integration | Captive API production reduces exposure to Chinese and Indian supplier currency volatility and cross-border logistics disruptions. |
| Telemedicine Network Expansion | Remote pharmacy services penetrate Central Highlands provinces where specialist-to-patient ratios fall below one-tenth of Hanoi levels. |
| Special Economic Zone Manufacturing | Tax holidays in Hung Yen and Bac Ninh provinces attract contract manufacturers seeking cost arbitrage against import-dependent competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Vietnam Social Security formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulated segment-level estimates.
Segment-weighting approaches distributed value across product type, delivery mode, end user channel, and patient population dimensions throughout the forecast period. CAGRs derived from longitudinal prescription trend analysis, reimbursement expansion trajectories, and urbanization-driven patient pool growth in the Red River Delta and Ho Chi Minh City corridors. Forecast inputs incorporated Vietnam Ministry of Health pricing circular impacts and bioequivalence study approval timelines.
Caveats apply where Drug Administration of Vietnam regulatory shifts, Vietnam Social Security reimbursement tier revisions, or API supply disruptions could materially shift the outlook. Forecasts reflect assumptions documented in the analytical framework without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
BRICS Diabetes Drugs Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market