
 New Zealand Insulin Drugs and Devices Market | 2026-2036
New Zealand Insulin Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Insulin Drugs and Devices Market Foresight
Human insulin analogs is decoupling from conventional recombinant formulations as biosimilar manufacturing gains technical parity, compressing cost structures for public tenders. Novo Nordisk leverages its recombinant protein platform to sustain dominance in basal insulin supply across District Health Boards. Sanofi anchors its position through long-acting analog R&D intensity, while Eli Lilly and Company differentiates via rapid-acting formulations designed for pump compatibility.
New Zealand Insulin Drugs and Devices encompasses pharmaceutical formulations of peptide hormones for glycemic control alongside mechanical and electronic systems for parenteral administration, typically requiring cold-chain distribution at two to eight degrees Celsius and ISO 11608 needle-based injection compliance. Insulin Pens occupy the largest volume share due to Pharmac's bulk purchasing agreements favoring disposable pen systems for Type 2 populations. Continuous Glucose Monitors represent the fastest-expanding technology segment as wearable sensor accuracy improves and automated insulin delivery integration deepens. Home Care emerges as a concentrated margin pool where patient self-management reduces hospital burden and shifts reimbursement toward ambulatory models.
Pharmac governs market access through its national tender system, while Medsafe regulates product registration under the Medicines Act 1981 and Medical Devices Safety Authority standards. The Therapeutic Products Act 2023 reshapes oversight pathways for software-as-medical-device features in connected pens and automated delivery systems. Stakeholders must monitor how real-world evidence requirements for reimbursement evolve alongside interoperability mandates for glucose sensor-to-pump data exchange.
Market Dynamics
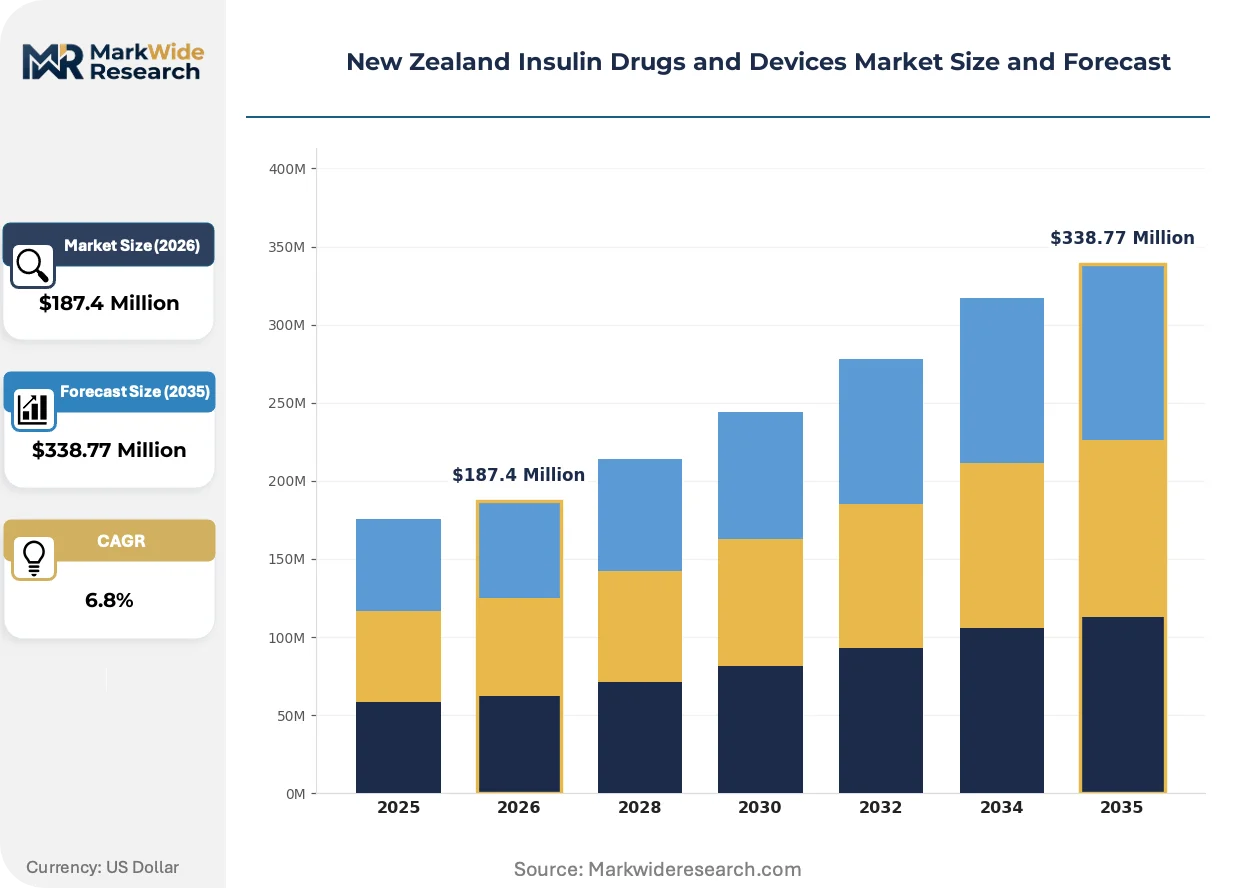
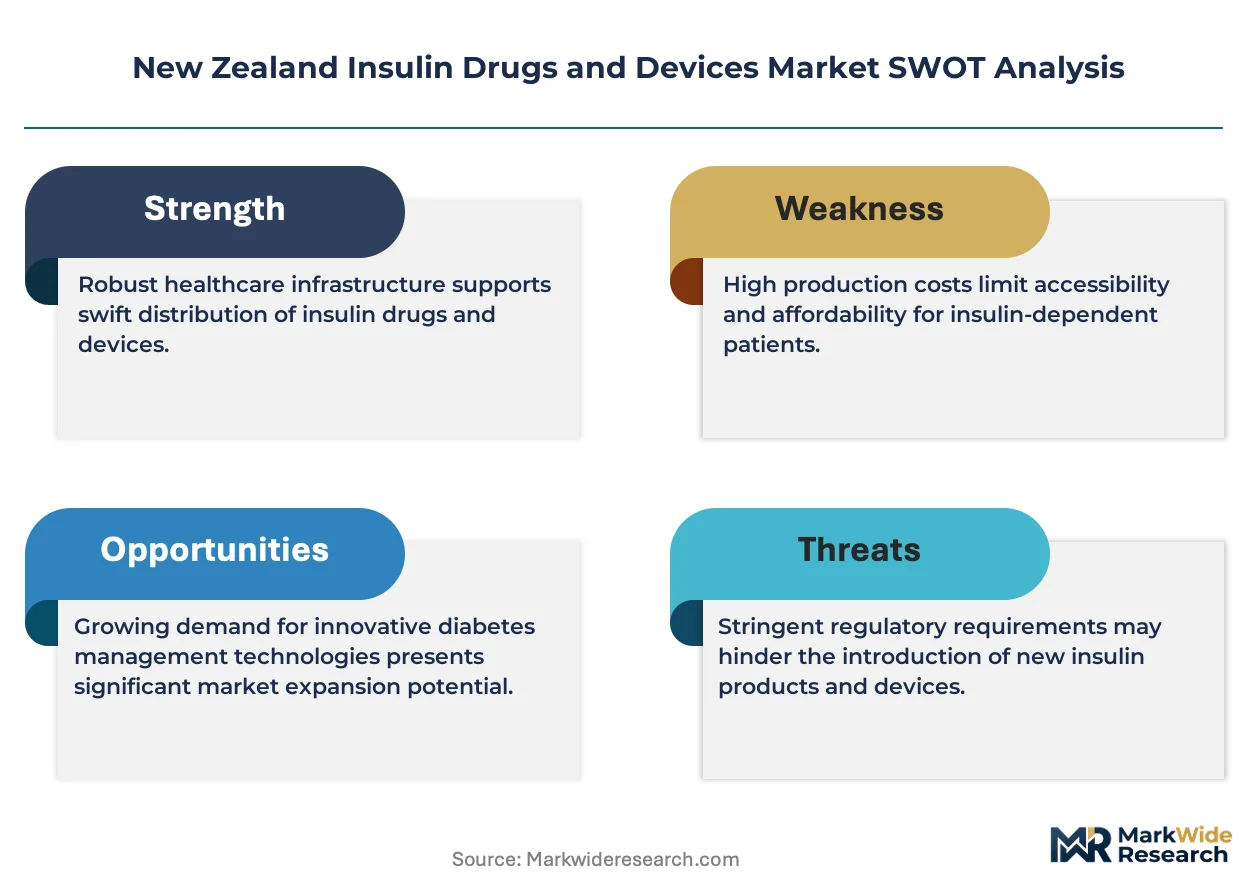
Pharmac's tender-driven procurement model is compressing margins while simultaneously accelerating uptake of automated insulin delivery systems through expanded reimbursement pathways for integrated diabetes technologies.
Growth Catalysts
- Therapeutic Products Act 2023:The legislation creates clearer approval pathways for software-as-medical-device features in connected insulin pens, reducing regulatory uncertainty for manufacturers seeking market entry.
- Auckland metropolitan health networks:Concentration of specialist endocrinology services in this urban cluster drives disproportionate adoption of connected insulin delivery platforms and continuous glucose monitoring systems.
- Automated insulin delivery integration:Sensor-to-pump data exchange capabilities are deepening as interoperability standards mature, enabling closed-loop systems that reduce hospital burden and shift care toward ambulatory models.
Market Restraints
- Cold-chain distribution costs:Maintaining two to eight degrees Celsius compliance across New Zealand's dispersed geography inflates logistics expenditure for insulin formulations.
- Pharmac tender concentration:Single-payer procurement power compresses pricing flexibility and limits manufacturer ability to differentiate on premium features.
- Biosimilar technical parity:Manufacturing advances in recombinant protein production erode brand moats in basal insulin supply, intensifying price competition.
Strategic Opportunities
- Home Care ambulatory models:Patient self-management platforms represent concentrated margin pools where reimbursement shifts away from acute settings toward community-based diabetes management.
- Continuous Glucose Monitors:Wearable sensor accuracy improvements are expanding addressable populations beyond Type 1 into Type 2 diabetes monitoring.
- Medsafe Medical Devices Safety Authority standards:Evolving requirements for real-world evidence create first-mover advantages for manufacturers with robust post-market surveillance infrastructure.
Industry Challenges
- ISO 11608 needle-based injection compliance:Certification timelines for pen injector systems create bottlenecks as manufacturers navigate updated mechanical and electronic system requirements.
- Interoperability mandate complexity:Glucose sensor-to-pump data exchange standards vary across device ecosystems, forcing engineering trade-offs between proprietary optimization and open architecture compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Insulin Drugs and Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Syringes, Vials Delivery Mode: Subcutaneous, Intravenous, Inhaled, Transdermal End User: Hospitals, Clinics, Home Care, Pharmacies Technology: Smart Insulin Pens, Continuous Glucose Monitors, Wearable Devices, Automated Insulin Delivery |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Medtronic, Roche, Merck And Co, Pfizer, Takeda, AstraZeneca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Insulin Drugs and Devices Market Shifts & Advancements
Digital connectivity and automated glycemic control are converging to transform how insulin therapies are delivered and monitored across New Zealand's district health boards.
Closed-loop automated insulin delivery systems are integrating predictive algorithms with real-time glucose sensing to enable autonomous basal rate adjustments. District Health Boards in Auckland and Wellington are piloting these platforms for high-risk Type 1 populations. The technology is integrating hospital and home care workflows, compressing the traditional boundary between acute and ambulatory diabetes management.
Medsafe's implementation of Therapeutic Products Act 2023 provisions is reshaping software validation requirements for connected pen devices. Manufacturers must now submit cybersecurity documentation and algorithm performance data alongside traditional safety dossiers. Insulin pump and smart pen segments face the steepest compliance ramps as they incorporate Bluetooth connectivity and dose-decision support features.
Patient-generated health data is displacing clinic-centric monitoring as the primary input for therapy optimization. Endocrinology practices in metropolitan Auckland are restructuring around continuous data streams rather than quarterly HbA1c measurements. This behavioral pivot is most visible among working-age Type 1 populations who prioritize minimal disruption to professional schedules.
New Zealand Insulin Drugs and Devices Market Segmentation
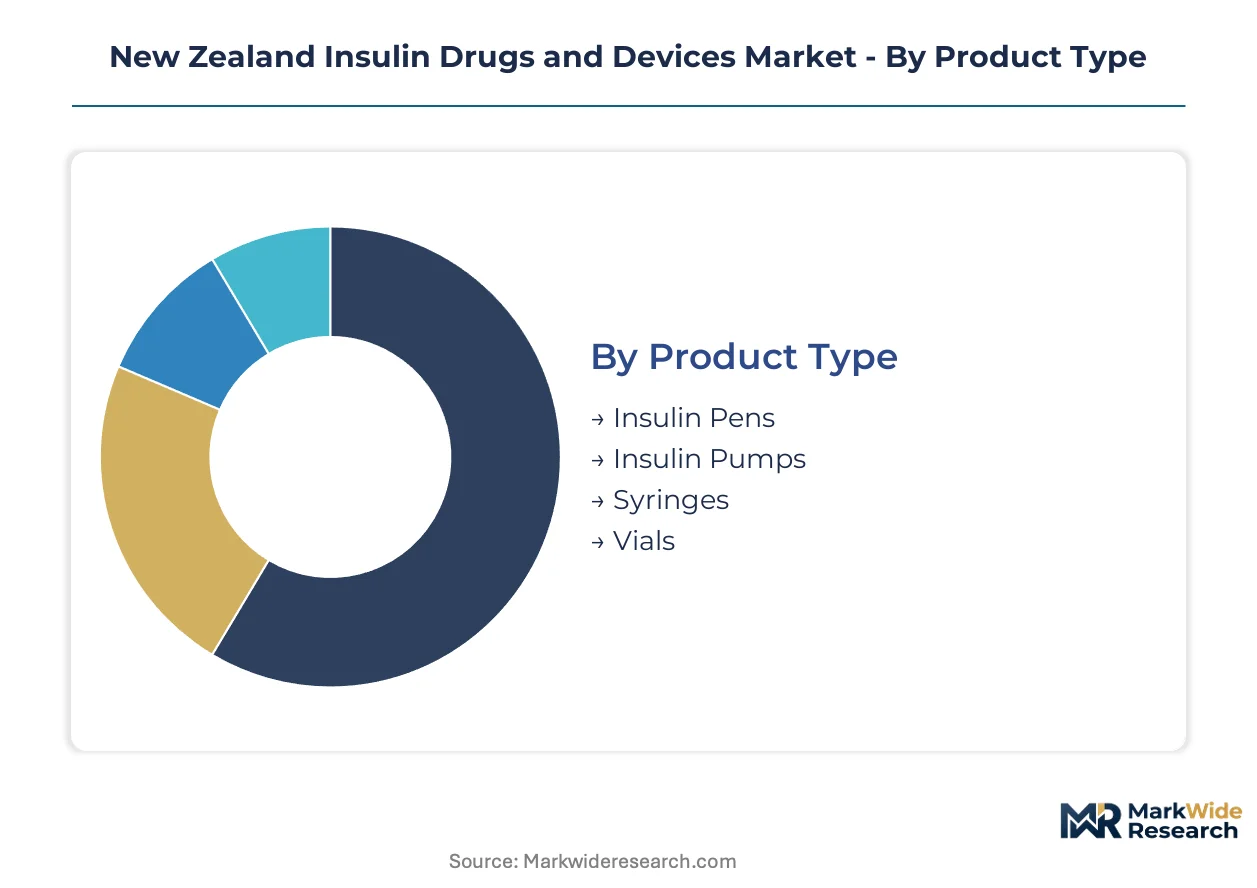
Pharmac's tender-driven procurement creates distinct demand profiles across delivery technologies, with reimbursement tiers favoring disposable systems for Type 2 populations while specialist networks accelerate uptake of integrated platforms for Type 1 management.
Product Type:
Cost tier separates high-volume disposable formats from capital-intensive reusable systems.
- Insulin Pens:Disposable and reusable pen injectors dominate procurement volumes under Pharmac's bulk purchasing agreements. District Health Boards favor pen systems for ambulatory Type 2 populations across Auckland and Canterbury health networks.
- Insulin Pumps:Electronic infusion devices enable programmable basal-bolus delivery with pump compatibility driving rapid-acting analog formulation demand. Wellington and Auckland metropolitan clusters show disproportionate concentration of tethered and patch pump adoption.
- Syringes:Conventional needle-and-barrel systems retain niche use in cost-constrained settings and specific clinical protocols requiring precise volume adjustment.
- Vials:Multi-dose glass or polymer containers supply hospital inpatient settings and home care patients with established injection routines.
Volume sits with Insulin Pens; growth tilts toward Insulin Pumps.
Delivery Mode:
Application context determines route selection, with self-administration feasibility driving ambulatory preferences.
- Subcutaneous:Abdominal, thigh, and upper arm tissue deposition remains standard for basal and prandial insulin across all patient categories. Home Care reimbursement frameworks explicitly cover subcutaneous pen and pump supplies.
- Intravenous:Hospital inpatient settings utilize IV insulin infusion for perioperative glycemic control and diabetic ketoacidosis management in intensive care units.
- Inhaled:Pulmonary delivery of prandial insulin addresses needle-averse populations, though Pharmac coverage remains restricted compared to injectable formulations.
- Transdermal:Microneedle and iontophoretic patches represent emerging modalities with limited current reimbursement but active Medsafe evaluation under Therapeutic Products Act pathways.
Subcutaneous commands absolute volume; Automated Insulin Delivery integration is expanding pump-based subcutaneous growth fastest.
End User:
Customer type dictates procurement channel and margin structure, with institutional tenders compressing pricing while direct-to-patient models preserve differentiation.
- Hospitals:District Health Boards procure through national tender for inpatient and outpatient services, with Auckland, Wellington, and Christchurch facilities driving automated delivery system pilots.
- Clinics:Specialist endocrinology practices in metropolitan clusters prescribe connected devices and interpret continuous glucose monitor data streams for therapy optimization.
- Home Care:Patient self-management platforms attract concentrated margins as reimbursement shifts toward ambulatory models and community pharmacy distribution.
- Pharmacies:Community dispensers fulfill pen needle and disposable pen prescriptions under Pharmac's pharmaceutical schedule with defined patient co-payment structures.
Home Care captures margin expansion; Hospital procurement governs volume allocation.
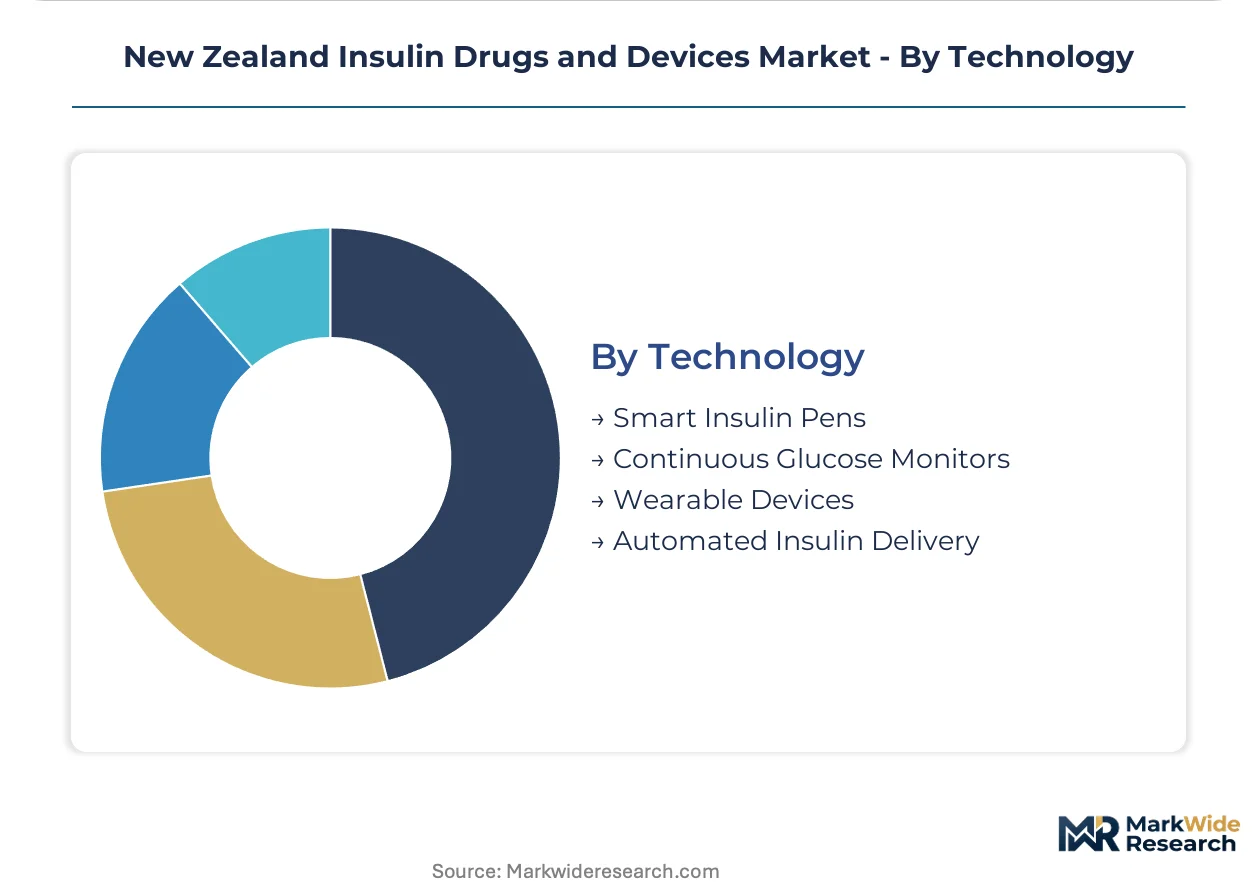
Technology:
Maturity stage separates established monitoring from emerging closed-loop integration.
- Continuous Glucose Monitors:Factory-calibrated wearable sensors with Bluetooth transmission enable real-time glucose trending and predictive alerts. Auckland specialist networks are restructuring clinical workflows around these data streams.
- Smart Insulin Pens:Bluetooth-enabled dose capture and timing logs address adherence gaps in pen-based therapy. Medsafe's Therapeutic Products Act implementation now requires cybersecurity documentation for these software-as-medical-device features.
- Wearable Devices:Patch pumps and sensor-integrated platforms prioritize discretion and professional schedule compatibility for working-age Type 1 populations.
- Automated Insulin Delivery:Closed-loop systems integrating CGM data with algorithm-driven pump adjustments are piloting across Auckland and Wellington District Health Boards for high-risk cohorts.
Continuous Glucose Monitors hold installed base leadership; Automated Insulin Delivery is climbing the fastest trajectory toward mainstream reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for insulin drugs and devices concentrates in Auckland's metropolitan health networks, where specialist endocrinology services cluster and drive uptake of connected delivery platforms. District Health Board procurement patterns create distinct regional demand profiles across New Zealand's North and South Islands.
Auckland Region
Auckland's three District Health Boards—Auckland, Counties Manukau, and Waitematā—account for disproportionate volumes of automated insulin delivery system procurement. Pharmac's expanded reimbursement for integrated diabetes technologies accelerates adoption in this urban cluster. Specialist endocrinology practices in Auckland Central and North Shore restructure clinical workflows around continuous glucose monitor data streams.
Wellington Region
Capital and Coast District Health Board pilots closed-loop insulin delivery systems for high-risk Type 1 cohorts, leveraging proximity to central government health policy formation. Medsafe's Therapeutic Products Act 2023 implementation receives operational interpretation from Wellington-based regulatory affairs units. Hutt Valley and Wairarapa districts follow procurement templates set by the capital's specialist diabetes services.
Canterbury Region
Canterbury District Health Board maintains substantial pen injector volumes through Pharmac's bulk purchasing agreements for Type 2 populations. Christchurch Hospital's endocrinology department anchors South Island specialist referral patterns. Rolleston and satellite clinics extend pen-based therapy distribution into rural Canterbury plains.
Waikato Region
Waikato District Health Board balances hospital-based insulin pump services with community pharmacy pen needle distribution across Hamilton and surrounding districts. Pharmac's pharmaceutical schedule defines patient co-payment structures that shape product selection in this mid-sized urban market. Rural outreach clinics in Thames and Tokoroa rely on cold-chain logistics networks radiating from Auckland.
New Zealand Insulin Drugs and Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with recombinant protein platforms dominating pharmaceutical supply and electronic device makers capturing premium technology tiers. Novo Nordisk, Sanofi, and Eli Lilly anchor the insulin formulation segment through distinct analog specializations. Medtronic and Roche compete for connected device integration contracts. Competitive moves concentrate on strategic partnerships for sensor-to-pump interoperability and portfolio diversification into automated delivery systems.
Within the multinational pharmaceutical tier, Novo Nordisk and Sanofi occupy positions exemplifying basal insulin supply dominance through recombinant manufacturing scale. Eli Lilly and Company represents rapid-acting formulation specialization designed for pump compatibility. Among device-integrated players, Medtronic anchors the automated insulin delivery segment through closed-loop algorithm development.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Medtronic |
| Roche |
| Merck And Co |
| Pfizer |
| Takeda |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Pharmac's sovereign-backed procurement dominance compresses manufacturer margins while simultaneously enforcing supply security through multi-source qualification mandates. District Health Board tender concentration creates asymmetric pricing power where volume commitments trade against premium feature differentiation.
Pricing Analysis
Volume concentrates in disposable pen injectors while margins pool in automated insulin delivery systems. Pharmac's bulk purchasing agreements enforce three-tier pricing structure across premium, standard, and economy levels differentiated by device connectivity and algorithm sophistication. Pricing pressure stems from biosimilar technical parity in basal insulin analogs. Type 2 populations in community pharmacy channels exhibit highest price sensitivity; Type 1 cohorts in specialist networks accept premium tiers for closed-loop integration.
Supply Chain Analysis
Dual-sourcing requirements for District Health Board tenders mandate multi-supplier qualification for insulin formulations and electronic delivery devices. Manufacturing concentrates in Denmark, France, and Ireland for recombinant protein production; electronic components originate from Malaysia, Mexico, and China. Active pharmaceutical ingredients and precision pump motors represent critical dependencies. Single-source vulnerability in glucose sensor membrane supply creates concentration risk. Distribution runs through Auckland cold-chain hubs radiating to regional pharmacy networks under Pharmac's pharmaceutical schedule.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into biosimilar manufacturing and algorithm development determines competitive durability as Pharmac's tender mechanics compress standalone formulation margins.
For Market Incumbents: Anchor market position through backward integration into recombinant protein production and captive supply of glucose sensor components. Novo Nordisk's recombinant platform demonstrates how manufacturing scale defends basal insulin share against biosimilar entrants. Secure District Health Board automated delivery system contracts by bundling pump hardware with continuous glucose monitor data analytics. For New Entrants and Emerging Players: Direct-to-patient digital channels offer lowest-friction entry for smart insulin pen companion apps and subscription-based continuous glucose monitor services. Home Care ambulatory models present the most penetrable white-space as reimbursement shifts from hospital procurement toward patient self-management platforms. Target Wellington and Auckland metropolitan specialist networks with interoperability-first positioning that addresses Medsafe's Therapeutic Products Act software validation requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap device manufacturers with ISO 11608 certification infrastructure and established Pharmac tender relationships in Canterbury and Waikato regions. Five-to-ten year viability hinges on sensor-to-pump interoperability patent positions. Watch Pharmac's real-world evidence reimbursement criteria as the inflection signal for automated insulin delivery system adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Pharmac's expanded framework for integrated diabetes technologies accelerates automated delivery system procurement across Auckland District Health Boards. |
| Regulatory Approval Pathway | Medsafe's Therapeutic Products Act implementation creates first-mover advantage for manufacturers with cybersecurity documentation and algorithm performance dossiers. |
| Backward Integration | In-house recombinant protein production defends margin position against biosimilar technical parity in basal insulin supply tenders. |
| Platform Integration | Sensor-to-pump data exchange standardization enables closed-loop system contracts with Wellington and Auckland specialist endocrinology networks. |
| Hospital System Partnership | Capital and Coast District Health Board pilot programs establish reference sites for automated insulin delivery rollout across New Zealand. |
Research Methodology
Pharmac tender documentation, Medsafe regulatory filings, and District Health Board procurement databases formed the secondary backbone of this analysis. Primary interviews with formulary directors, biomedical engineers, hospital procurement managers, and diabetes technology specialists validated demand assumptions. Bottom-up pen injector volume estimates and top-down automated delivery system value projections were triangulated across data streams.
Historical trendline analysis of insulin analog pricing and device adoption rates informed the projection framework. Segmentation modeling incorporated delivery mode, end user channel, technology maturity tier, and regional District Health Board cluster across the analysis window. CAGRs derived from elasticity-adjusted volume trajectories and reimbursement policy scenario analysis. Forecast inputs included Pharmac pharmaceutical schedule revisions and Medsafe software-as-medical-device approval timelines.
The model holds under stable Pharmac procurement mechanics and Therapeutic Products Act implementation pace; deviation in reimbursement criteria for real-world evidence or accelerated biosimilar tender awards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Global Diabetic Retinopathy Market