
 Australia Insulin Infusion Pump Market | 2026-2036
Australia Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Insulin Infusion Pump Market Insights
Australia is tilting toward localized diabetes technology distribution as import dependency for insulin infusion hardware faces supply-chain reassessment. Medtronic leverages its established infusion set manufacturing partnerships to sustain hospital channel dominance. Ypsomed anchors the patch pump category through compact form factors suited to pediatric and active adult cohorts. Insulet Corporation differentiates via tubeless platform architecture that eliminates tethered tubing, competing directly for patient self-management segments.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous cannula at calibrated basal rates and patient-triggered bolus doses, typically with reservoir capacities of 1.8 mL to 3.0 mL and precision dosing increments of 0.025 to 0.1 units. Its primary commercial purpose is to replicate physiological pancreatic beta-cell secretion patterns for intensive insulin therapy outside clinical settings. Durable pumps retain the largest installed base due to established reimbursement codes and endocrinologist familiarity, while patch pumps capture the fastest-growing patient segment among insulin-naive Type 2 diabetics seeking discretion. Bluetooth connectivity and automated insulin delivery technologies concentrate margin pools where algorithm licensing and sensor integration create recurring revenue streams beyond hardware sales.
TGA medical device registration requirements and the NDIS assistive technology approval framework shape market access timelines and pricing ceilings for pump manufacturers seeking national formulary inclusion. The Therapeutic Goods Administration enforces ISO 15197 and IEC 62304 standards for glucose monitoring interoperability and software lifecycle safety, raising compliance costs for new entrants. Stakeholders must monitor how the Australian Digital Health Agency integrates pump data into My Health Record architectures, as this interoperability mandate will determine which platforms achieve preferential clinician workflow adoption.
Market Dynamics
Automated insulin delivery algorithms are compressing the gap between sensor data and pump response, forcing manufacturers to integrate continuous glucose monitors directly into closed-loop architectures. This convergence is restructuring competitive advantage around software licensing rather than hardware durability alone.
Growth Catalysts
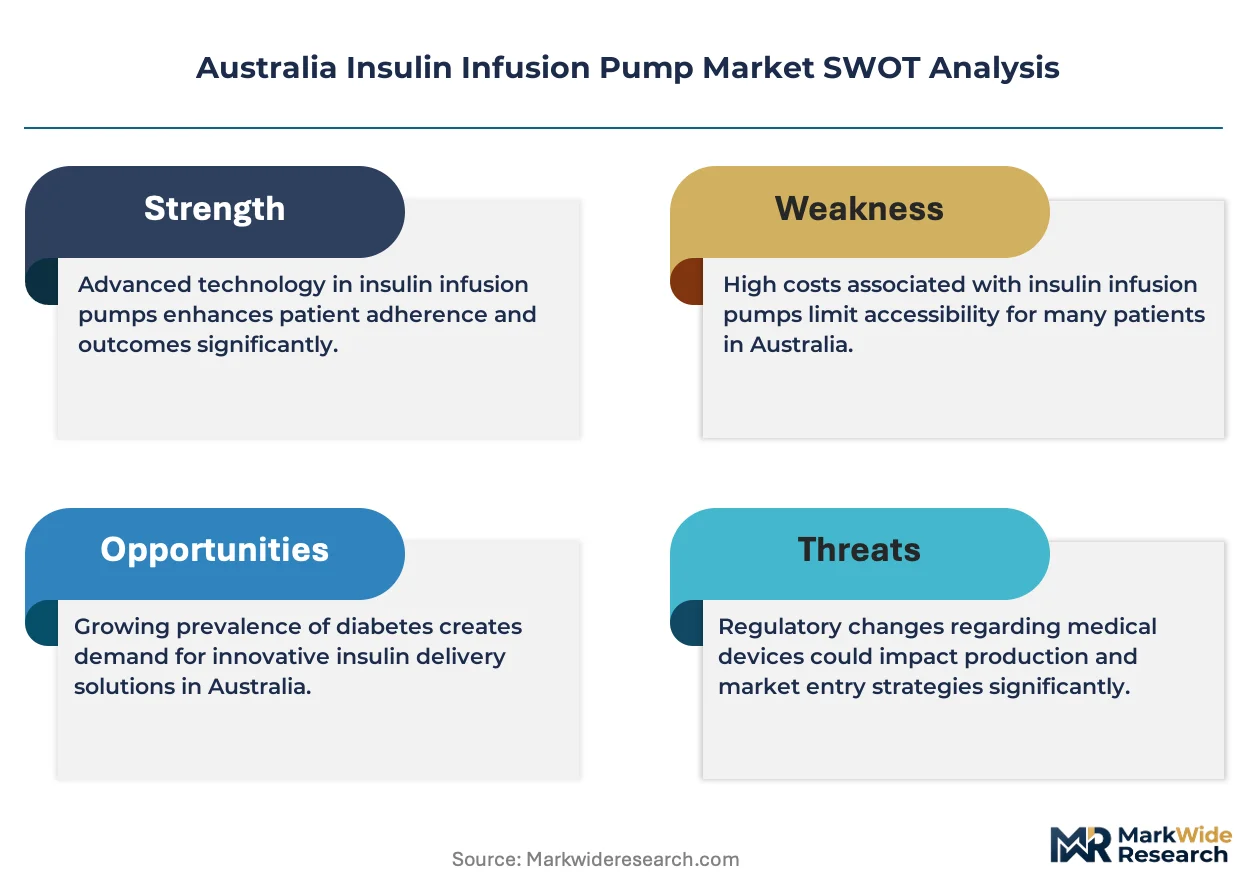
- NDIS assistive technology funding:The National Disability Insurance Scheme expanded reimbursement eligibility for insulin infusion systems, removing out-of-pocket barriers for Type 1 diabetics across Queensland and Western Australia.
- Tubeless patch pump miniaturization:Reduced device footprint and adhesive advances enable discreet wear during physical activity, attracting insulin-naive Type 2 patients previously resistant to pump therapy.
- New South Wales endocrinology cluster density:Sydney's concentration of tertiary diabetes centers creates referral network effects that accelerate patient onboarding onto intensive insulin protocols.
Market Restraints
- Single-source sensor dependency:Dexcom and Abbott Freestyle Libre dominate interoperable glucose sensing, creating supply vulnerability if manufacturing disruptions affect transmitter availability.
- TGA software lifecycle compliance costs:IEC 62304 documentation requirements for algorithm updates extend revision cycles and elevate regulatory expenditure for firmware modifications.
- Multiple daily injection persistence:Pen needle systems with smart dose logging (NovoPen Echo, InPen) retain cost-conscious patients who perceive pump complexity as unjustified for their glycemic targets.
Strategic Opportunities
- Tasmania and Northern Territory coverage gaps:Endocrinologist scarcity in these states creates telehealth-integrated pump management models that bypass geographic access constraints.
- My Health Record interoperability mandate:The Australian Digital Health Agency's data integration requirements favor pump platforms with open API architectures, penalizing proprietary closed systems.
- Pediatric automated delivery convergence:Hybrid closed-loop systems combining predictive suspend with adaptive basal rates address the unique glycemic variability of adolescent diabetes.
Industry Challenges
- Diabetes educator workforce constraints:Certified pump trainer scarcity limits patient onboarding velocity, particularly in regional Victoria and South Australia where endocrinology nursing ratios lag metropolitan benchmarks.
- Legacy hospital procurement system integration:State health department ERP platforms require custom HL7 FHIR middleware to ingest pump-generated ambulatory glucose profile data into electronic medical records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Insulin Infusion Pump Market |
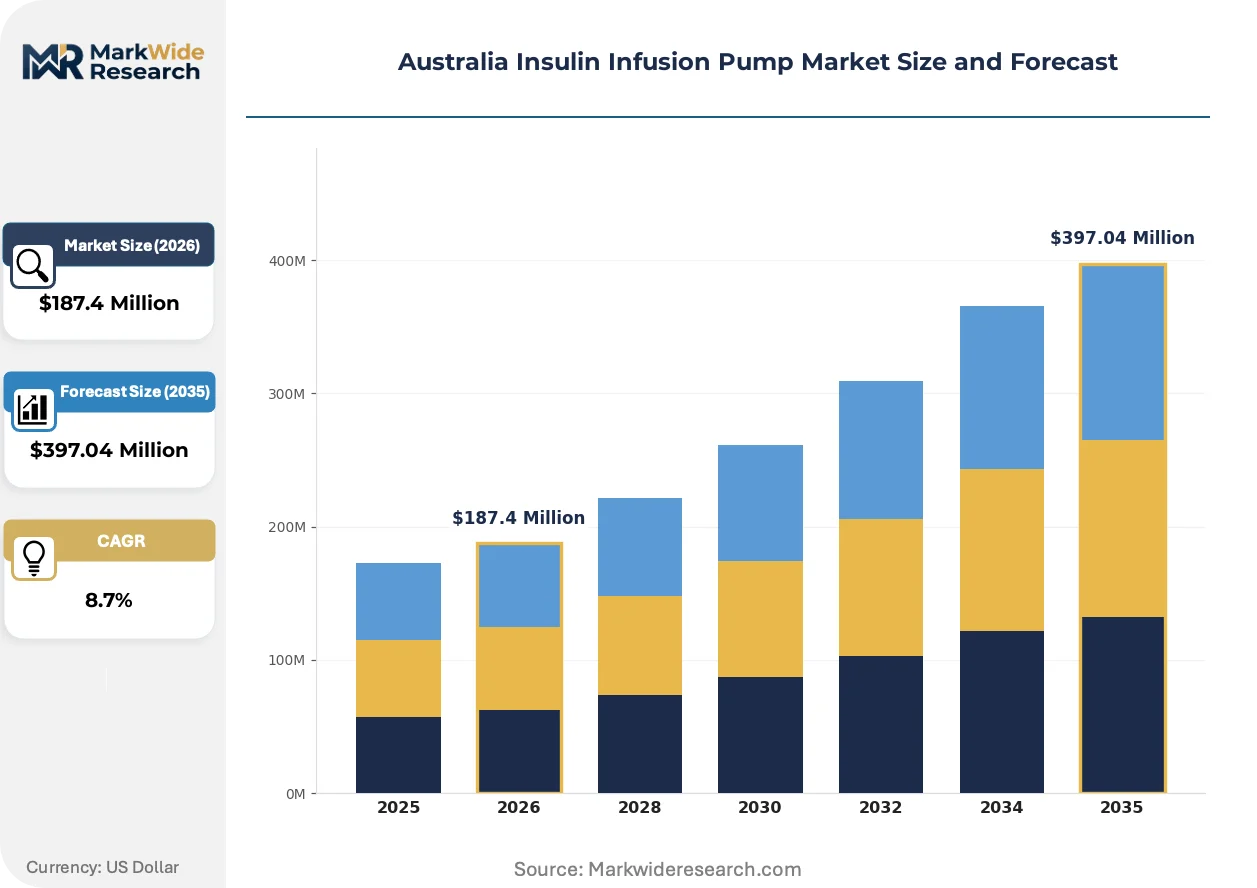
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Durable Pumps, Patch Pumps, Tubeless Pumps, Portable Pumps, Waterproof Pumps Technology: Continuous Glucose Monitoring, Automated Insulin Delivery, Bluetooth Connectivity, Remote Monitoring, Smart Sensors Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Cystic Fibrosis-Related Diabetes, Latent Autoimmune Diabetes End User: Hospitals, Specialized Clinics, Outpatient Care Centers, Diabetes Care Specialists, Home Healthcare Providers |
| Companies Covered | Tandem Diabetes Care, Roche Diabetes Care, Medtronic, Bigfoot Biomedical, Dexcom, Ascensia Diabetes Care, Ypsomed, Modular Medical, Insulet Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Insulin Infusion Pump Market Trends and Innovations
Algorithm-driven insulin dosing is displacing static basal-bolus programming as the default therapeutic paradigm. This shift elevates software reliability above hardware durability in purchasing criteria.
Dual-hormone infusion architecture is hybridizing pump functionality beyond insulin monotherapy. Devices now accommodate glucagon cassettes alongside insulin reservoirs for hypoglycemia mitigation. Pediatric endocrinology units in Melbourne and Brisbane are piloting these systems for nocturnal glucose stability. The technology is hybridizing competitive positioning around acute complication prevention rather than chronic hyperglycemia management alone.
TGA's 2022 guidance on artificial pancreas system classification created a distinct regulatory pathway for automated insulin delivery. Manufacturers must now demonstrate fault-tree analysis for algorithm failure modes prior to market authorization. Patch pump vendors face compressed approval timelines if they leverage predicate device comparisons, while novel closed-loop architectures endure extended clinical evidence requirements.
Patient data ownership expectations are reshaping subscription pricing models. Device users increasingly resist cloud platforms that restrict raw glucose data export. Victoria's private insurance market has responded with pump benefit structures that reward open-data compliance, while South Australian hospital procurement tenders now mandate interoperability certification as a mandatory evaluation criterion.
Australia Insulin Infusion Pump Market Segmentation
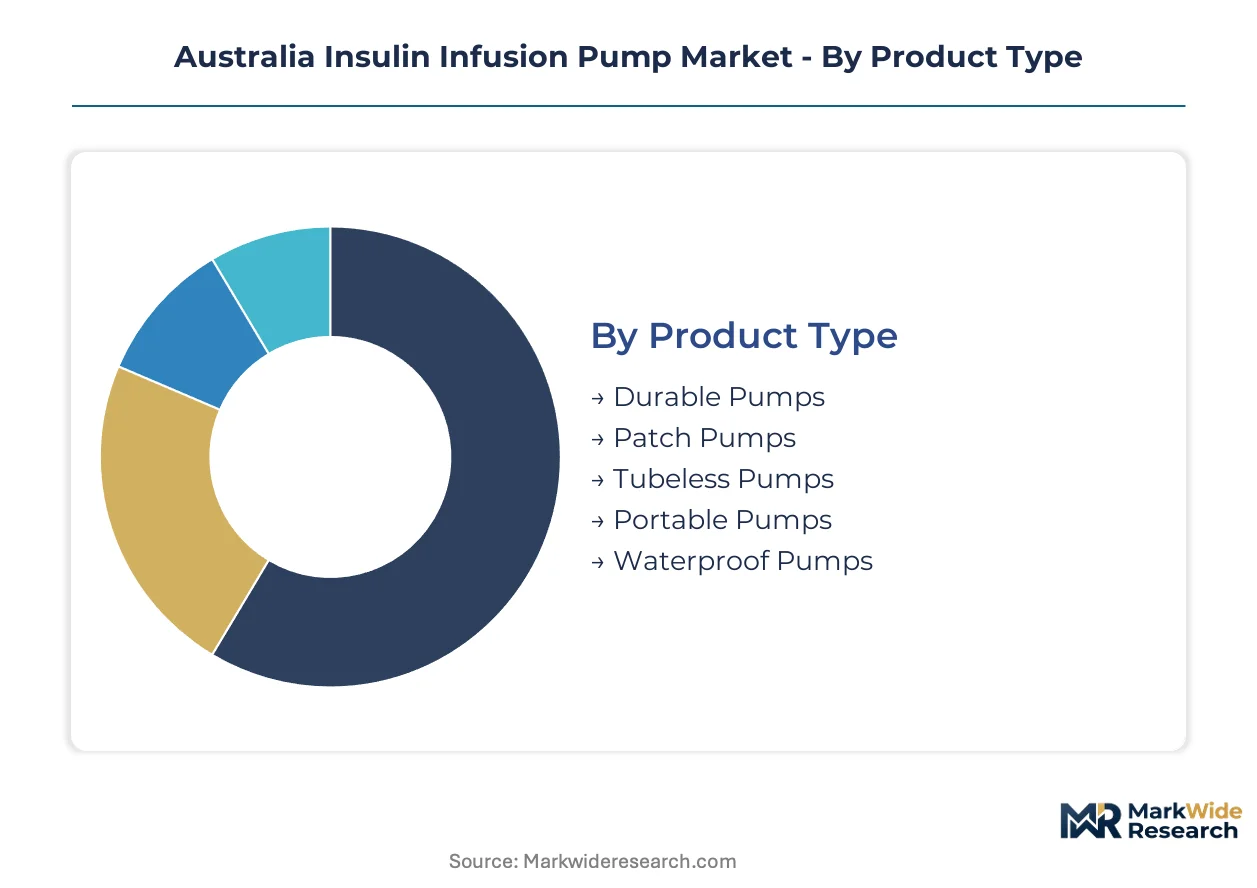
Segmentation in Australia's insulin infusion pump market reveals how reimbursement pathways, clinical infrastructure, and patient self-management preferences distribute demand across device categories. Understanding these divisions clarifies where TGA registration investments and NDIS eligibility lobbying deliver maximum commercial leverage.
Product Type:
Cost tier differentiation separates devices by capital expenditure requirements and consumable attachment models, shaping how manufacturers structure subscription versus outright purchase offerings.
- Durable Pumps:These electromechanical units feature 1.8 mL to 3.0 mL insulin reservoirs with precision dosing increments of 0.025 to 0.1 units, tethered to the body via infusion sets. Demand concentrates in New South Wales tertiary hospitals where endocrinology clusters support intensive patient onboarding protocols. Established TGA reimbursement codes and clinician familiarity sustain this segment's installed base dominance.
- Patch Pumps:Compact adhesive-mounted devices eliminate external tubing through fully integrated reservoir-cannula systems suited to pediatric and physically active adult cohorts. Western Australia and Queensland show accelerating uptake as NDIS assistive technology funding removes out-of-pocket barriers for younger Type 1 diabetics seeking discretion during sport and employment.
- Tubeless Pumps:Platform architectures separate the insulin delivery mechanism from control interfaces via wireless communication, enabling smartphone-based dosing commands.
- Portable Pumps:Lightweight designs prioritize travel and occupational mobility through reduced device mass and extended battery duration.
- Waterproof Pumps:Sealed housings rated for submersion address swimming and water sport participants in coastal Australian populations.
Durable pumps command the established base. The steepest expansion runs through patch pumps.
Technology:
Application sophistication determines margin capture, with algorithm licensing and sensor integration generating recurring revenue streams beyond hardware margins.
- Continuous Glucose Monitoring:Interoperable transmitter-receiver systems sample interstitial glucose at 1-5 minute intervals, enabling real-time trend visualization. Victorian private insurers now reward open-data compliance with preferential benefit structures, accelerating patient demand for platforms with raw glucose export capabilities.
- Automated Insulin Delivery:Closed-loop architectures modulate basal rates algorithmically based on predictive glucose trajectory modeling, suspending insulin delivery before hypoglycemic thresholds. Melbourne and Brisbane pediatric endocrinology units pilot these systems for nocturnal stability in adolescent diabetes, where glycemic variability exceeds adult patterns.
- Bluetooth Connectivity:Wireless protocol integration enables smartphone-based dosing commands and caregiver remote oversight.
- Remote Monitoring:Cloud-based data transmission permits clinician intervention without clinic attendance, addressing Tasmania and Northern Territory endocrinologist scarcity.
- Smart Sensors:Predictive algorithms anticipate glucose excursions through machine learning pattern recognition.
Continuous glucose monitoring anchors current revenue. Automated insulin delivery is climbing the fastest as TGA's artificial pancreas guidance streamlines regulatory pathways.
Application:
Customer type severity stratifies device complexity requirements, with intensive insulin protocols demanding programmable basal-bolus flexibility that simpler regimens do not justify.
- Type 1 Diabetes:Absolute insulin deficiency mandates basal rate programming and bolus dosing for carbohydrate intake, making pump therapy standard of care for patients failing multiple daily injection regimens. Sydney's concentration of tertiary diabetes centers creates referral network effects that accelerate patient onboarding onto intensive protocols.
- Type 2 Diabetes:Progressive beta-cell dysfunction in insulin-naive patients drives patch pump adoption as device miniaturization reduces therapy initiation barriers. South Australian hospital procurement tenders now mandate interoperability certification, favoring platforms that integrate with My Health Record architectures.
- Gestational Diabetes:Temporary insulin requirements during pregnancy prioritize short-term device rental models over capital purchase.
- Cystic Fibrosis-Related Diabetes:Unique glucagon deficiency patterns in this population create demand for dual-hormone capable devices.
- Latent Autoimmune Diabetes:Slowly progressive beta-cell failure in adult onset resembles Type 1 pathophysiology with delayed insulin dependency.
Type 1 diabetes maintains volume leadership. Type 2 diabetes is gaining share fastest as tubeless form factors attract insulin-naive patients.
End User:
Supply concentration varies by channel sophistication, with specialized infrastructure requirements filtering which device categories penetrate each setting.
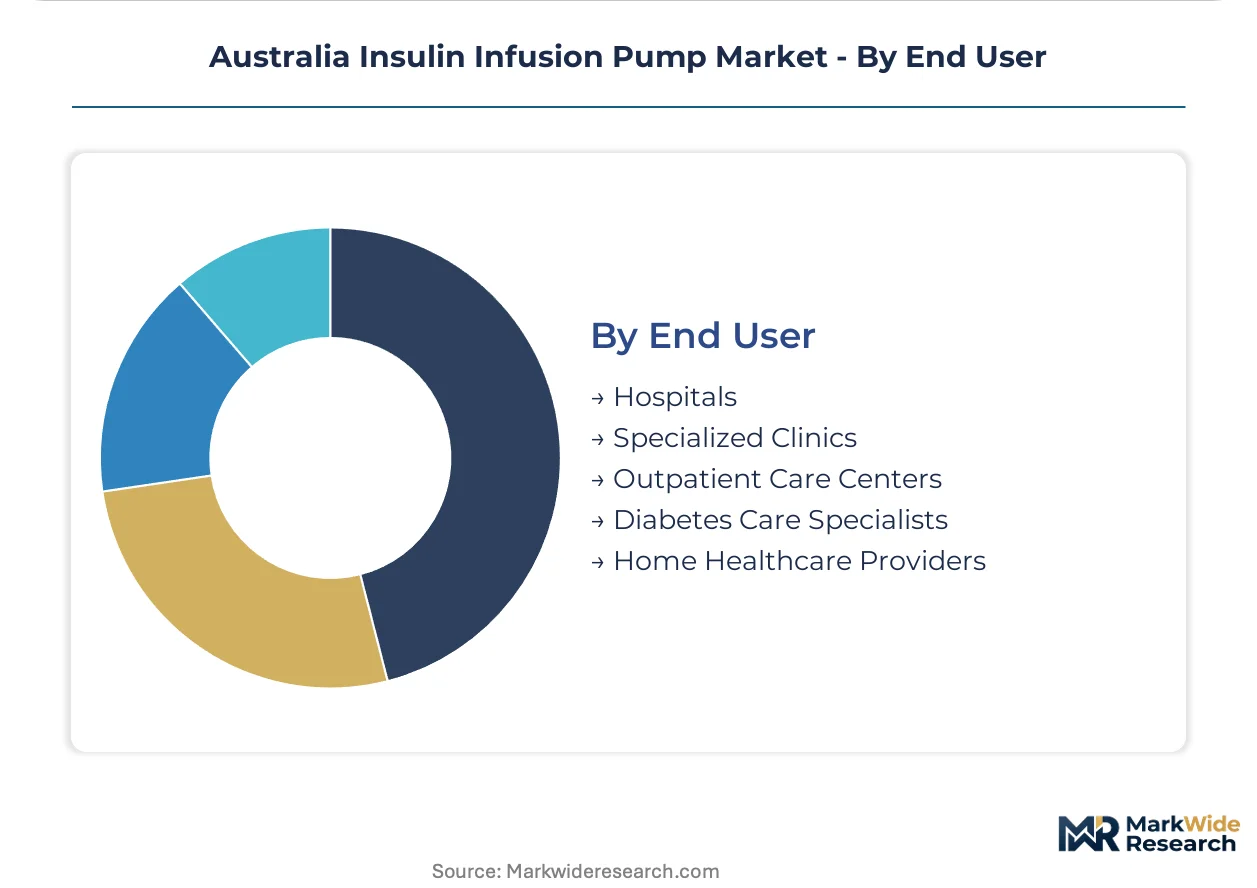
- Hospitals:Acute care settings utilize pumps for perioperative glycemic management and diabetic ketoacidosis resolution, requiring enterprise-scale procurement integration with state health department ERP platforms. Custom HL7 FHIR middleware investments limit vendor switching for incumbent suppliers.
- Specialized Clinics:Endocrinology-focused facilities in Melbourne and Sydney drive patient onboarding velocity through certified pump trainer availability, though workforce constraints in regional Victoria and South Australia create geographic bottlenecks.
- Outpatient Care Centers:Ambulatory settings bridge hospital discharge and home self-management with transitional pump training programs.
- Diabetes Care Specialists:Credentialled diabetes educator practices concentrate device initiation expertise, with scarcity limiting national expansion.
- Home Healthcare Providers:Distributors with nursing staff deliver pump setup and troubleshooting directly to residential settings, expanding fastest as patients seek outpatient glycemic management.
Hospitals anchor procurement volume. Home healthcare providers show the steepest expansion trajectory as NDIS funding shifts accelerate device accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device distribution concentrates where endocrinology infrastructure and reimbursement pathways align. New South Wales and Victoria dominate procurement volume, while Queensland and Western Australia accelerate through NDIS funding expansion.
New South Wales
Sydney's tertiary diabetes centers generate referral network effects for intensive insulin protocols. TGA reimbursement codes sustain durable pump procurement through established hospital channels. The Sydney metropolitan cluster anchors patient onboarding velocity for automated delivery systems.
Victoria
Melbourne pediatric endocrinology units pilot hybrid closed-loop architectures for adolescent glycemic stability. Private insurers reward open-data compliance with preferential benefit structures. The state's credentialled diabetes educator workforce density exceeds national benchmarks, accelerating device initiation.
Queensland
NDIS assistive technology eligibility expansion removes out-of-pocket barriers for Type 1 diabetics in Brisbane and regional centers. Home healthcare providers extend pump setup services to residential settings outside metropolitan corridors. Telehealth-integrated models address endocrinologist scarcity in northern coastal regions.
Western Australia
Patch pump uptake accelerates among younger patients seeking discretion during sport and employment. Perth's diabetes care infrastructure supports tubeless platform adoption through certified trainer availability. State procurement frameworks increasingly mandate interoperability certification for My Health Record integration.
South Australia
Hospital tenders now require HL7 FHIR middleware compatibility for ambulatory glucose data ingestion. Adelaide's specialized clinics bridge discharge and home self-management with transitional training programs. Regional nursing ratio constraints create geographic bottlenecks for patient onboarding velocity.
Australia Insulin Infusion Pump Market Competitive Landscape
Durable pump incumbents and patch pump specialists split the market along reimbursement maturity lines. Established manufacturers leverage TGA registration longevity and clinician familiarity to defend hospital procurement relationships. Emerging entrants concentrate on tubeless form factors and algorithm licensing to bypass capital-intensive hardware competition. Consolidation pressure intensifies around automated insulin delivery capabilities, with sensor integration partnerships determining competitive viability.
Within the durable pump tier, Medtronic and Tandem Diabetes Care anchor established positions through infusion set manufacturing scale and endocrinology channel penetration. Ypsomed occupies the compact device segment with adhesive-mounted systems suited to pediatric and active adult cohorts. Insulet Corporation exemplifies the tubeless platform architecture that eliminates tethered tubing, competing directly for patient self-management segments where discretion drives selection criteria.
| Leading Market Players |
|---|
| Tandem Diabetes Care |
| Roche Diabetes Care |
| Medtronic |
| Bigfoot Biomedical |
| Dexcom |
| Ascensia Diabetes Care |
| Ypsomed |
| Modular Medical |
| Insulet Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in precision insulin pump motor manufacturing across Southeast Asian contract manufacturers is compressing supplier margins and forcing tiered pricing differentiation between volume hospital contracts and discrete home healthcare purchases. This utilization squeeze elevates procurement negotiation leverage for New South Wales tertiary hospitals while NDIS-funded patch pump orders absorb residual capacity at premium rates.
Pricing Analysis
TGA medical device registration pathways dictate the pricing tier structure across Australia's insulin infusion pump market. Three-tier pricing separates premium closed-loop systems with algorithm licensing from standard Bluetooth-enabled durable pumps and economy patch pump configurations. Price differentiation hinges on ISO 15197 glucose monitoring interoperability certification and after-sales educator support bundling. Cost compression in the economy tier is intensifying because of NDIS bulk procurement aggregation. Home healthcare providers exhibit highest price sensitivity, while pediatric endocrinology units in Melbourne and Sydney demonstrate lowest sensitivity due to clinical outcome guarantees.
Supply Chain Analysis
Flex, Jabil, and Benchmark Electronics hold concentrated capacity for miniature electromechanical pump assembly serving Australian device manufacturers. Component sourcing draws from Malaysia for precision motors, Switzerland for sensor microelectronics, and China for lithium-polymer battery cells. Raw material dependencies include medical-grade polycarbonate housings, platinum-cured silicone tubing, and subcutaneous-grade stainless steel cannulae. Single-source vulnerability in Dexcom and Abbott Freestyle Libre transmitter supply creates exposure if manufacturing disruptions affect glucose sensor interoperability. Distribution runs through hospital procurement consortia in New South Wales and Victoria, with home healthcare direct-to-patient fulfillment expanding fastest in Queensland and Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's insulin infusion pump market sits in early-cycle expansion as NDIS assistive technology funding removes out-of-pocket barriers and accelerates patient onboarding velocity beyond historical penetration rates.
For Market Incumbents: Insulate hospital procurement relationships in New South Wales and Victoria through exclusive infusion set supply contracts and embedded HL7 FHIR middleware integration that raises switching costs. Deepen backward integration into sensor transmitter manufacturing to reduce Dexcom and Abbott dependency exposure. Prioritize TGA software lifecycle compliance investment to accelerate automated insulin delivery algorithm updates ahead of emerging competitors. For New Entrants and Emerging Players: Establish a beachhead in Tasmania and Northern Territory telehealth-integrated pump management where endocrinologist scarcity creates service-model differentiation opportunities. Target insulin-naive Type 2 diabetics in Western Australia with tubeless patch pump offerings emphasizing sport and employment discretion. Pursue GPO contracts with Queensland home healthcare providers as the fastest-expanding channel bypassing hospital procurement complexity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among algorithm licensing platforms with sensor integration partnerships that generate subscription income beyond hardware depreciation cycles. Long-term viability over the projection horizon favors automated insulin delivery specialists with open API architectures compliant with My Health Record interoperability mandates. Monitor TGA artificial pancreas system classification approvals as the critical inflection signal for closed-loop competitive viability.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Artificial Pancreas Pathway Submission | Accelerates market authorization for closed-loop systems ahead of algorithm update competitors. |
| NDIS Assistive Technology Partnership | Locks in reimbursement eligibility and removes patient out-of-pocket barriers in Queensland and Western Australia. |
| My Health Record API Certification | Secures preferential clinician workflow adoption through Australian Digital Health Agency interoperability mandates. |
| Pediatric Endocrinology Unit Collaboration | Generates clinical evidence for nocturnal glucose stability in adolescent diabetes populations. |
| Dual-Hormone Glucagon Cassette Development | Addresses hypoglycemia mitigation in cystic fibrosis-related diabetes and acute complication prevention. |
Research Methodology
Desk research of TGA medical device registration databases, NDIS assistive technology approval records, and Australian Digital Health Agency interoperability specifications preceded structured interviews with hospital biomedical engineers, credentialled diabetes educators, GPO contracts managers, and endocrinology nursing directors. Secondary validation incorporated Therapeutic Goods Administration public assessment reports, state health department procurement tender documents, and private insurer benefit schedule filings. Bottom-up pump shipment estimates by state were triangulated against top-down reimbursement expenditure aggregates.
Assumptions regarding NDIS funding continuity, TGA regulatory pathway stability, and sensor manufacturer supply reliability were held fixed across the modeling period, while patient preference evolution and telehealth adoption velocity were varied in sensitivity scenarios. Segmentation dimensions modeled include product type tier, technology sophistication level, diabetes severity classification, and end-user channel concentration. CAGRs were derived from logarithmic trend fitting of historical reimbursement data extrapolated through patient population growth and penetration rate assumptions. Forecast inputs incorporated endocrinologist workforce density projections and My Health Record integration timeline milestones.
Stress conditions across NDIS policy revision, TGA software lifecycle compliance cost escalation, and single-source sensor supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and acknowledge that algorithm failure mode evidence requirements or interstate procurement consolidation could materially revise projections. Quarterly review of TGA artificial pancreas approval cadence and NDIS assistive technology eligibility expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market