
 South Africa Self-Monitoring Blood Glucose Devices Market | 2026-2036
South Africa Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Self-Monitoring Blood Glucose Devices Market Insights
Capital-intensity divergence between automated strip manufacturing and manual assembly operations is bifurcating competitive positioning across the South Africa Self-Monitoring Blood Glucose Devices Market. Roche Holding AG sustains integrated production of electrochemical biosensors at scale, while Abbott Diabetes Care leverages its flash glucose monitoring platform to command premium placement in private hospital networks. Ascensia Diabetes Care anchors its position through pharmacy-centric distribution partnerships that reach secondary cities beyond Gauteng's core.
Self-monitoring blood glucose devices comprise portable diagnostic instruments—glucometers, continuous glucose monitors, disposable test strips, and lancets—that measure capillary blood glucose concentration through electrochemical or optical transduction, typically requiring sample volumes between 0.3 and 1.0 microliters and producing results within five to fifteen seconds for real-time metabolic management by diabetic patients. The device type dimension shows test strips generating recurring revenue streams that subsidize glucometer hardware placement, while continuous glucose monitors capture the fastest expansion as private insurers in South Africa gradually expand reimbursement for flash-based systems. Electrochemical technology dominates unit economics due to mature enzymatic chemistry and minimal calibration requirements, though non-invasive approaches attract R&D investment despite unresolved accuracy constraints.
SAHPRA mandates ISO 13485 quality management certification and local adverse-event reporting for all imported glucose monitoring devices, raising compliance costs for smaller Asian manufacturers. The South African Bureau of Standards enforces electrical safety and electromagnetic compatibility testing that adds six to twelve months to product registration timelines. Stakeholders must monitor SAHPRA's evolving software-as-a-medical-device guidance, which will determine whether smartphone-integrated glucose apps require standalone regulatory review.
Market Dynamics
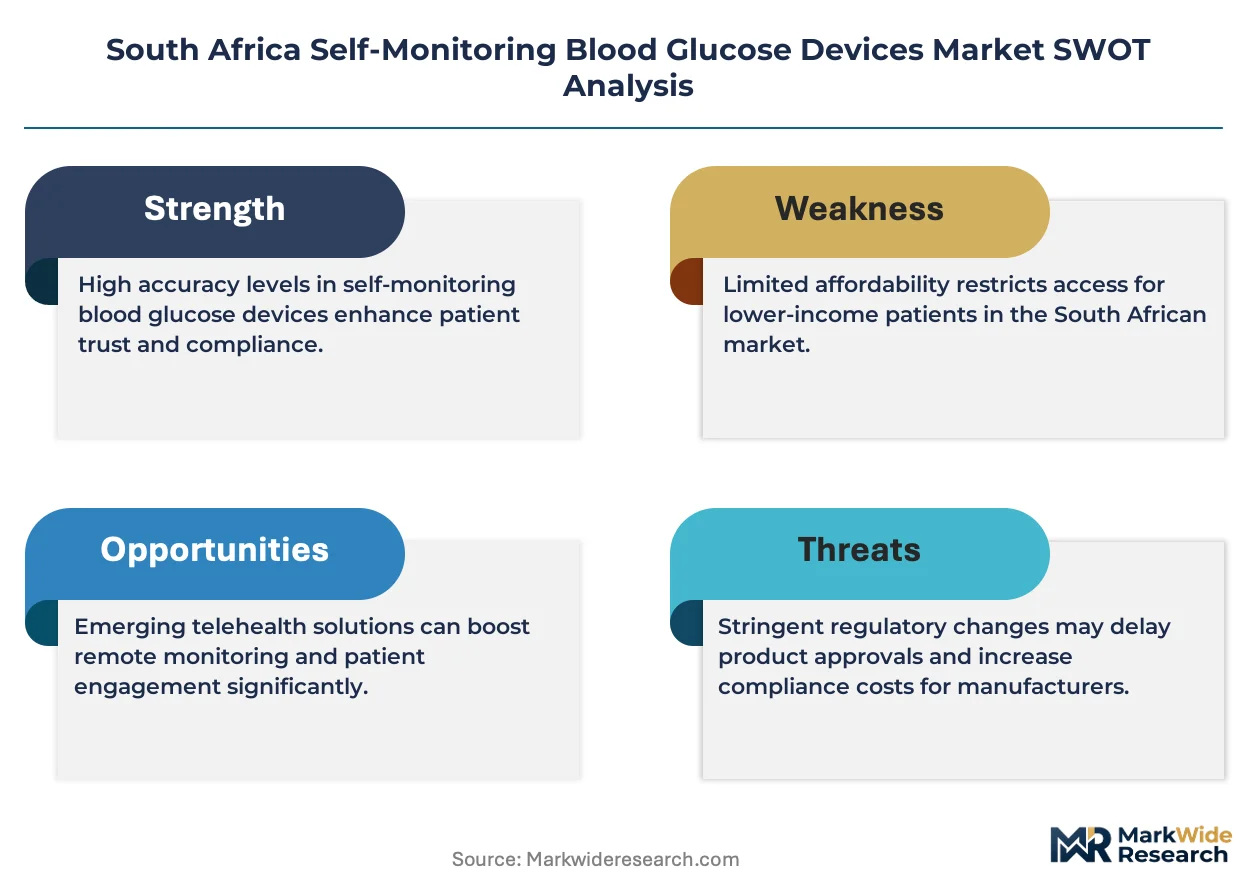
SAHPRA's tightened ISO 13485 certification requirements and extended registration timelines are compressing market entry for smaller manufacturers while reinforcing the dominance of established players with dedicated compliance infrastructure.
Growth Catalysts
- Point-of-care expansion:Clinics and hospital outpatient departments across Gauteng and Western Cape provinces are installing dedicated glucose testing stations to reduce laboratory turnaround times for diabetic patients.
- Flash glucose reimbursement:Private medical insurers in South Africa are gradually expanding coverage for continuous glucose monitoring systems, accelerating patient migration from traditional fingerstick methods.
- Enzymatic electrochemistry maturation:Third-generation glucose oxidase biosensors with minimal oxygen dependence are delivering laboratory-grade accuracy at consumer price points.
Market Restraints
- Extended SAHPRA timelines:Medical device registration now requires six to twelve months of electrical safety and electromagnetic compatibility testing through the South African Bureau of Standards.
- Test strip import concentration:Disposable consumables flow predominantly through Durban port logistics, creating vulnerability to customs processing delays and currency fluctuation exposure.
- Non-invasive accuracy ceiling:Optical and transdermal glucose sensing technologies remain constrained by physiological interference from hydration status and skin temperature variation.
Strategic Opportunities
- Eastern Cape penetration:Gqeberha and East London host underserved diabetic populations with limited access to endocrinology specialists and pharmacy-based monitoring services.
- Software-as-medical-device pathway:SAHPRA's evolving guidance on smartphone-integrated glucose applications may create first-mover advantage for platforms combining hardware and analytics.
- Pharmacy channel deepening:Independent pharmacy chains in secondary cities beyond Johannesburg and Pretoria present untapped distribution nodes for patient education and device placement.
Industry Challenges
- Biomedical engineering scarcity:South African universities produce insufficient electrochemical sensor specialists to support local manufacturing ambitions and quality assurance functions.
- Adverse-event reporting infrastructure:SAHPRA mandates local pharmacovigilance capabilities that smaller importers struggle to maintain without dedicated regulatory affairs personnel.
- Legacy meter interoperability:Proprietary data formats from installed glucometer bases complicate patient transitions to integrated digital health platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Self-Monitoring Blood Glucose Devices Market |
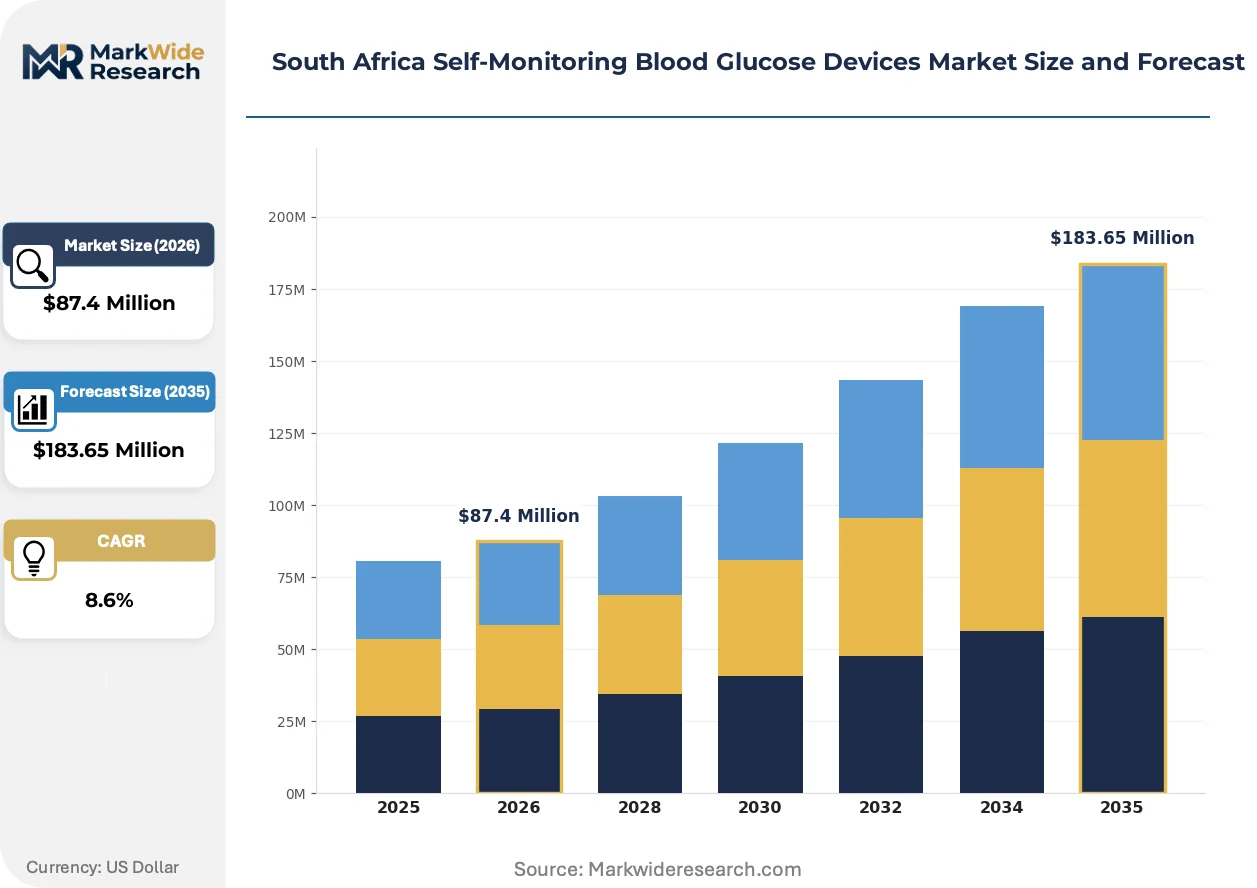
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Glucometers, Continuous Glucose Monitors, Test Strips, Lancets Technology: Electrochemical, Optical, Non-Invasive, Flash Glucose Monitoring User Type: Patients, Caregivers, Healthcare Providers, Clinics Distribution Channel: Pharmacies, Supermarkets, Online Stores, Hospitals |
| Companies Covered | Abbott Diabetes Care, Roche Holding AG, LifeScan, Ascensia Diabetes Care, Arkray Inc, Trividia Health, Acon Laboratories Inc, Bionime Corporation, Sinocare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Technology trajectories in South African glucose monitoring are diverging between premium continuous systems and cost-optimized strip-based platforms, with regulatory interpretation becoming the decisive competitive variable.
Electrochemical biosensor architecture is bifurcating between integrated automated manufacturing for high-volume strip production and manual assembly operations serving price-sensitive segments. Private hospital networks in Johannesburg and Pretoria are prioritizing factory-calibrated systems that eliminate patient coding errors. This technological division is compressing margins for mid-tier manufacturers lacking scale economies or premium feature differentiation.
SAHPRA's implementation of ISO 13485 quality management mandates and local adverse-event reporting requirements is elevating compliance burdens for imported devices. The South African Bureau of Standards enforces electrical safety testing that extends product registration cycles. Smaller Asian manufacturers are responding by withdrawing from direct market entry and licensing distribution to established local partners with existing regulatory infrastructure.
Patient acquisition patterns are rotating toward pharmacy-centric education and device initiation rather than specialist-led prescribing. Independent pharmacy chains in KwaZulu-Natal and Western Cape provinces are building diabetes care zones with trained staff conducting meter demonstrations. This channel shift is most visible in Cape Town's private healthcare corridor, where retail pharmacists now influence initial device selection more frequently than endocrinologists.
South Africa Self-Monitoring Blood Glucose Devices Market Segmentation
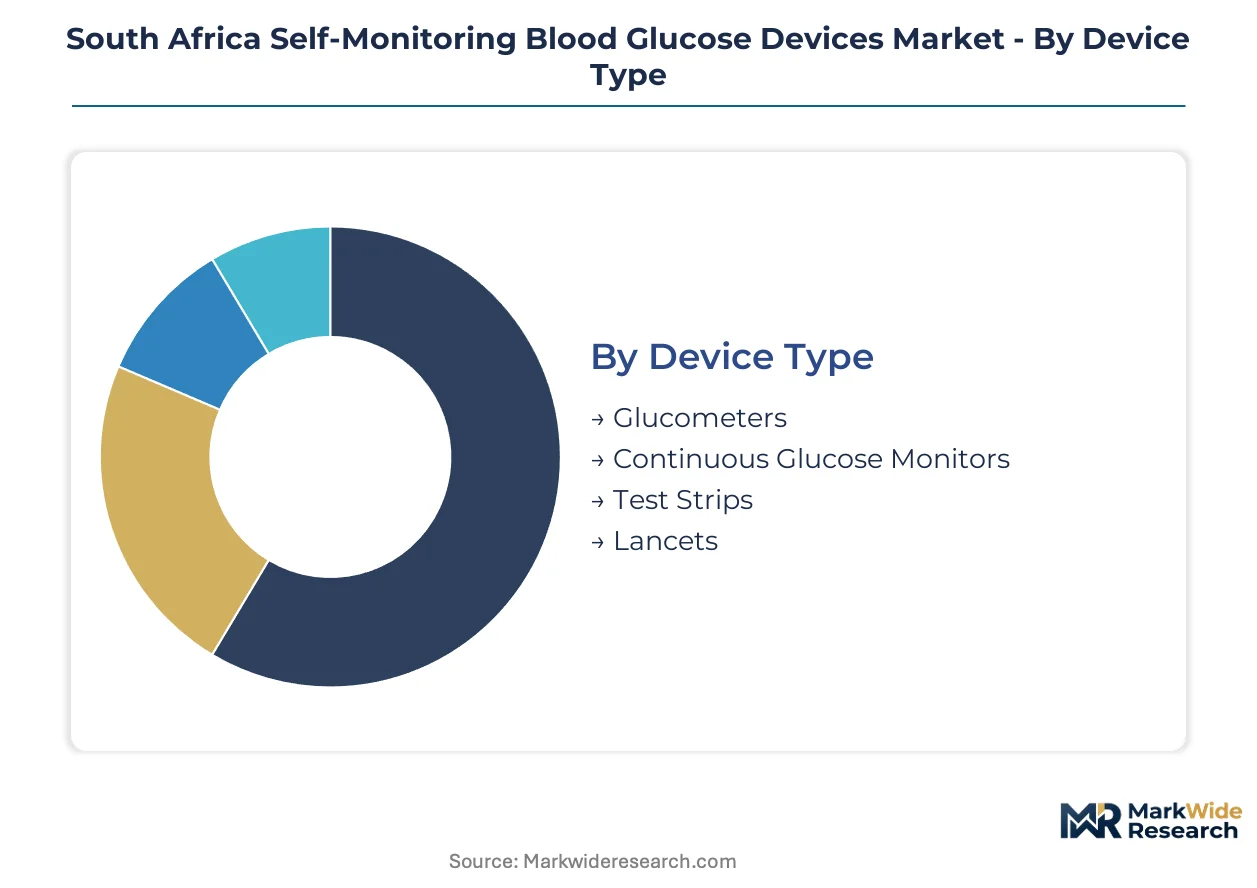
Segmentation in South Africa's glucose monitoring market reveals distinct channel affinities that shape procurement patterns. Each dimension exposes how technology maturity, user sophistication, and distribution infrastructure intersect to determine commercial outcomes.
Device Type:
Channel-mix patterns diverge sharply across device categories, with disposable consumables dominating pharmacy throughput while capital equipment concentrates in hospital procurement.
- Test Strips:Enzymatic electrochemical strips utilizing glucose oxidase chemistry require 0.3-1.0 microliter blood samples and deliver results within five to fifteen seconds. Pharmacy chains in Gauteng province move the highest volumes, driven by recurring replenishment cycles from Johannesburg's dense Type 2 diabetic population and private medical scheme coverage.
- Continuous Glucose Monitors:Factory-calibrated flash glucose systems with factory-embedded sensors eliminate patient calibration errors and stream real-time data to smartphone applications. Private hospital networks in Pretoria and Cape Town are expanding placement of these systems as Discovery Health and Momentum Medical Scheme broaden reimbursement eligibility.
- Glucometers:Portable electrochemical analyzers with digital displays and memory functions serve as the entry-level patient acquisition tool.
- Lancets:Spring-loaded peripheral blood sampling devices with adjustable depth settings accompany meter purchases in bundled starter kits.
By volume, Test Strips leads. By growth pace, Continuous Glucose Monitors is ahead.
Technology:
Cost tier stratification separates mature enzymatic platforms from premium optical and flash-based alternatives, with reimbursement policy determining accessible price points.
- Electrochemical:Third-generation glucose oxidase biosensors with minimal oxygen dependence achieve laboratory-grade accuracy at consumer price points. Public sector clinics in KwaZulu-Natal and Eastern Cape provinces rely predominantly on this technology due to established supply chains through Durban port logistics.
- Flash Glucose Monitoring:Factory-calibrated interstitial glucose sensors with 14-day wear duration and trend arrow displays eliminate fingerstick requirements. Private endocrinology practices in Johannesburg's northern suburbs are driving adoption as medical scheme coverage expands beyond insulin-dependent patients.
- Optical:Near-infrared and Raman spectroscopy approaches remain confined to research applications due to hydration interference.
- Non-Invasive:Transdermal glucose sensing technologies face unresolved accuracy constraints from skin temperature variation and perspiration effects.
Electrochemical platforms anchor volume shipments. Flash Glucose Monitoring climbs the fastest among reimbursed patient populations.
User Type:
Customer sophistication determines device complexity tolerance, with healthcare professionals prioritizing accuracy specifications while patients emphasize usability and cost.
- Patients:Individual diabetic users managing Type 1 or Type 2 conditions through self-monitoring protocols, ranging from newly diagnosed requiring education to long-term veterans seeking data integration. Pharmacy-based diabetes care zones in Cape Town's private healthcare corridor now initiate more device selections than specialist referrals.
- Healthcare Providers:General practitioners and endocrinologists prescribing monitoring protocols and interpreting trend data for treatment adjustment. Gauteng province's specialist density concentrates this user type in Johannesburg and Pretoria metropolitan areas.
- Caregivers:Family members and home health aides assisting pediatric or elderly patients with limited dexterity or cognitive capacity.
- Clinics:Primary care facilities and community health centers conducting point-of-care testing with waived laboratory turnaround requirements.
Patients generate the highest unit volume. Healthcare Providers are gaining influence fastest as remote monitoring platforms expand.
Distribution Channel:
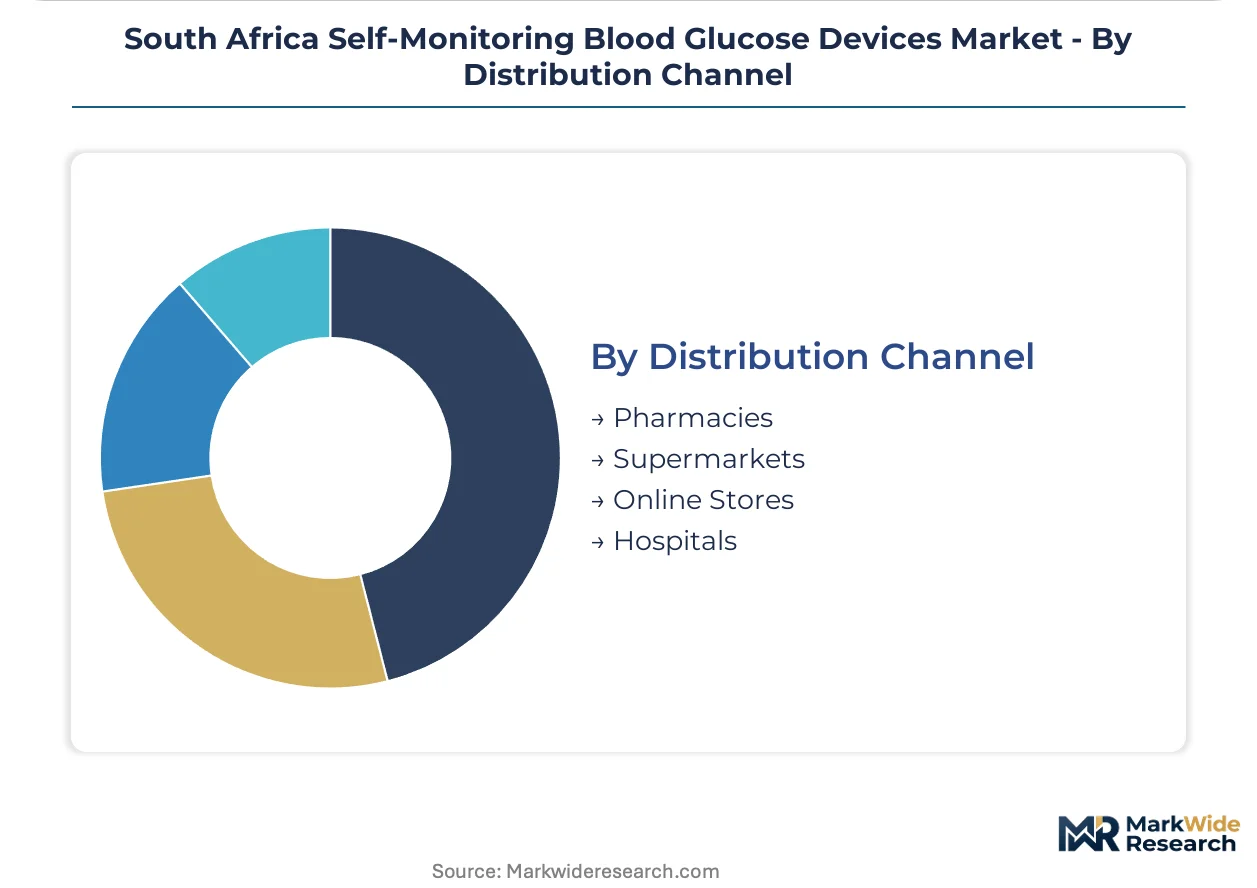
Geographic reach and patient education capacity separate channels, with urban concentration favoring pharmacy networks while rural access depends on hospital outreach.
- Pharmacies:Independent and chain retail dispensaries with trained staff conducting meter demonstrations and strip replenishment. Clicks and Dis-Chem networks dominate in secondary cities beyond Gauteng's core, building diabetes care zones with certified diabetes educator presence.
- Hospitals:Private hospital groups and public sector facilities procuring point-of-care systems for outpatient departments. Netcare and Life Healthcare installations in Johannesburg and Pretoria prioritize flash glucose systems for inpatient glycemic management.
- Online Stores:E-commerce platforms and direct-to-patient subscription services offering price comparison and home delivery convenience.
- Supermarkets:Mass retail channels with limited patient education capacity, primarily moving basic glucometer starter kits.
Pharmacies lead by transaction volume. Online Stores are expanding most quickly among digitally literate urban patients seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province commands pricing premiums 15-20% above Eastern Cape levels, reflecting specialist density and private medical scheme concentration in Johannesburg-Pretoria corridor versus public sector reliance elsewhere.
Gauteng
Johannesburg and Pretoria host South Africa's densest diabetic populations and private healthcare networks. SAHPRA's tightened ISO 13485 certification requirements elevate compliance costs for market entrants. Netcare and Life Healthcare installations in Sandton and Pretoria East prioritize flash glucose systems for inpatient glycemic management.
Western Cape
Cape Town's private healthcare corridor drives pharmacy-centric device initiation over specialist referrals. Discovery Health's reimbursement policies shape accessible price points for continuous monitoring systems. Clicks and Dis-Chem networks build diabetes care zones with certified educator presence in Claremont and Stellenbosch.
KwaZulu-Natal
Durban port logistics concentrate test strip import flows, creating customs processing vulnerabilities and currency exposure. Public sector clinics rely on enzymatic electrochemistry through established supply chains. Phoenix and Umhlanga pharmacy clusters serve as secondary distribution nodes beyond Gauteng core.
Eastern Cape
Gqeberha and East London present underserved diabetic populations with limited endocrinology specialist access. Provincial health department procurement favors cost-optimized strip-based platforms over premium continuous systems. Private hospital expansion in Port Elizabeth's Greenacres precinct is slowly building point-of-care capabilities.
South Africa Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South Africa Self-Monitoring Blood Glucose Devices Market. The vendor base concentrates around integrated multinationals with dedicated compliance infrastructure and specialized regional distributors serving price-sensitive segments. Three archetypes dominate: premium flash glucose platform providers, pharmacy-centric strip manufacturers, and value-oriented Asian importers. Competitive moves center on SAHPRA registration capacity expansion and pharmacy channel deepening in secondary cities.
Among integrated multinational players, Roche Holding AG and Abbott Diabetes Care exemplify divergent technology-cost positioning, while Ascensia Diabetes Care anchors the pharmacy partnership archetype. Roche represents the vertically integrated biosensor manufacturer with automated production scale. Abbott occupies the premium platform tier through flash glucose monitoring systems. Ascensia exemplifies distribution-centric positioning through independent pharmacy chain relationships beyond Gauteng's core metropolitan areas.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Holding AG |
| LifeScan |
| Ascensia Diabetes Care |
| Arkray Inc |
| Trividia Health |
| Acon Laboratories Inc |
| Bionime Corporation |
| Sinocare |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between private hospital networks and flash glucose system suppliers lock in both supply access and price visibility for Gauteng's premium healthcare corridor, insulating procurement teams from currency volatility while compressing margins for spot-market strip importers.
Pricing Analysis
The customization-premium spread between factory-calibrated continuous glucose monitors and standard glucometer configurations spans three distinct tiers: premium flash systems with embedded smartphone analytics, standard electrochemical meters with coded strips, and economy strip bundles for public sector clinics. Price differentiation rests on SAHPRA registration tier and after-sales calibration support, with ISO 13485-certified manufacturers commanding placement premiums in private networks. Cost compression in the economy tier intensifies as Asian manufacturers bypass direct registration and license through local distributors. Public sector procurement committees exhibit highest price sensitivity, while private endocrinology practices prioritize accuracy specifications over unit cost.
Supply Chain Analysis
Durban port customs clearance serves as the primary chokepoint for enzymatic test strip flows, with container processing delays cascading through KwaZulu-Natal distribution nodes to Eastern Cape clinics. Manufacturing concentration in China, South Korea, and Malaysia feeds electrochemical sensor components and finished glucometer assemblies through this single maritime gateway. Raw material dependencies span glucose oxidase enzyme precursors, PET substrate films, and precision lancet metals. Single-source vulnerability concentrates in Durban logistics, where currency fluctuation exposure compounds customs processing risk. Distribution runs through pharmacy chain warehouses in Johannesburg and Cape Town before reaching secondary city nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across South Africa's glucose monitoring landscape as pharmacy-centric patient acquisition displaces specialist-led prescribing, creating niche entry points for compliance-focused regional players.
For Market Incumbents: Fortify SAHPRA registration infrastructure against tightening ISO 13485 mandates while deepening vertical integration into electrochemical biosensor production to offset margin compression from Asian strip imports. Threat from flash glucose platform substitution demands accelerated software-as-medical-device certification for companion applications. Priority lever centers on captive supply of factory-calibrated sensors for private hospital networks. For New Entrants and Emerging Players: SAHPRA's expedited review pathway for devices with existing CE marking or FDA clearance offers fastest market access. Eastern Cape provinces present the most penetrable geography, with Gqeberha and East London clinics underserved by endocrinology specialists. Pharmacy channel partnerships with independent chains in secondary cities provide the strongest go-to-market angle, leveraging certified diabetes educator presence for patient initiation. For Investors and Strategic Acquirers: Capital is best deployed toward regional distributors with established SAHPRA compliance infrastructure and pharmacy network relationships rather than manufacturing assets. Long-term viability hinges on software integration capabilities across the 5-10 year horizon as continuous monitoring displaces fingerstick methods. Acquisition target archetype combines regulatory affairs expertise with secondary city pharmacy penetration. Signal to watch: Discovery Health and Momentum Medical Scheme reimbursement expansion for non-insulin-dependent patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Capacity Expansion | ISO 13485 certification investment accelerates product approval timelines for private hospital procurement. |
| Pharmacy Channel Deepening | Independent chain partnerships in KwaZulu-Natal and Western Cape extend reach beyond Gauteng core. |
| Flash Glucose Reimbursement Strategy | Medical scheme coverage expansion drives patient migration from fingerstick to continuous monitoring platforms. |
| Software-as-Medical-Device Development | Smartphone-integrated analytics platforms capture SAHPRA guidance first-mover advantage. |
| Eastern Cape Distribution Buildout | Gqeberha and East London nodes address underserved diabetic populations with limited specialist access. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs managers at medical device importers, pharmacy procurement directors, and hospital biomedical engineers; and secondary validation through SAHPRA registration databases, South African Bureau of Standards testing records, and private medical scheme reimbursement policy documents. Bottom-up triangulation across device shipment volumes and top-down reconciliation against healthcare expenditure flows anchored market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning device type, technology platform, user sophistication tier, and distribution channel density. CAGRs were derived from trend extrapolation of point-of-care expansion rates and flash glucose reimbursement trajectories. Industry-specific inputs included enzymatic biosensor cost curves and pharmacy network penetration indices.
Decision-makers should treat outputs as directional under assumptions of stable SAHPRA regulatory interpretation and continued private medical scheme coverage expansion; material deviation in reimbursement policy or customs processing efficiency would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Global Diabetic Ulcers Treatment Market