
 Blood Glucose Testing Devices Market | 2026-2036
Blood Glucose Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Glucose Testing Devices Market Analytics
Continuous glucose monitoring via subcutaneous sensor-to-receiver data streams is reshaping blood glucose testing architectures, displacing traditional fingerstick paradigms. Dexcom, Inc. sustains technology leadership in real-time glucose algorithms. Abbott Laboratories leverages vertically integrated biosensor manufacturing to control cost curves. Medtronic plc anchors hospital channel relationships that extend into ambulatory connected care ecosystems.
Blood glucose testing devices comprise electrochemical or optical sensor systems that quantify interstitial or capillary glucose concentrations, typically operating within 20-600 mg/dL measurement ranges for clinical and home-based glycemic management. Continuous glucose monitors capture the fastest expansion as patients and payers prioritize time-in-range metrics over episodic readings. Self-monitoring blood glucose systems retain volume dominance in emerging markets where cost sensitivity limits CGM penetration. Smart pens are emerging as a convergence point between insulin delivery and dose-data capture, creating new margin pools at the device-drug interface.
FDA premarket notification requirements under 21 CFR 862.1355 enforce analytical accuracy thresholds that shape product development timelines for US market entrants. EMA MDR classification and ISO 15197:2013 standards govern European commercialization and inter-laboratory performance validation. Stakeholders must monitor evolving CMS and national payer reimbursement decisions for non-adjunctive CGM indications, as coverage determinations will dictate adoption velocity across homecare and clinic segments regardless of technical capability advances.
Market Dynamics
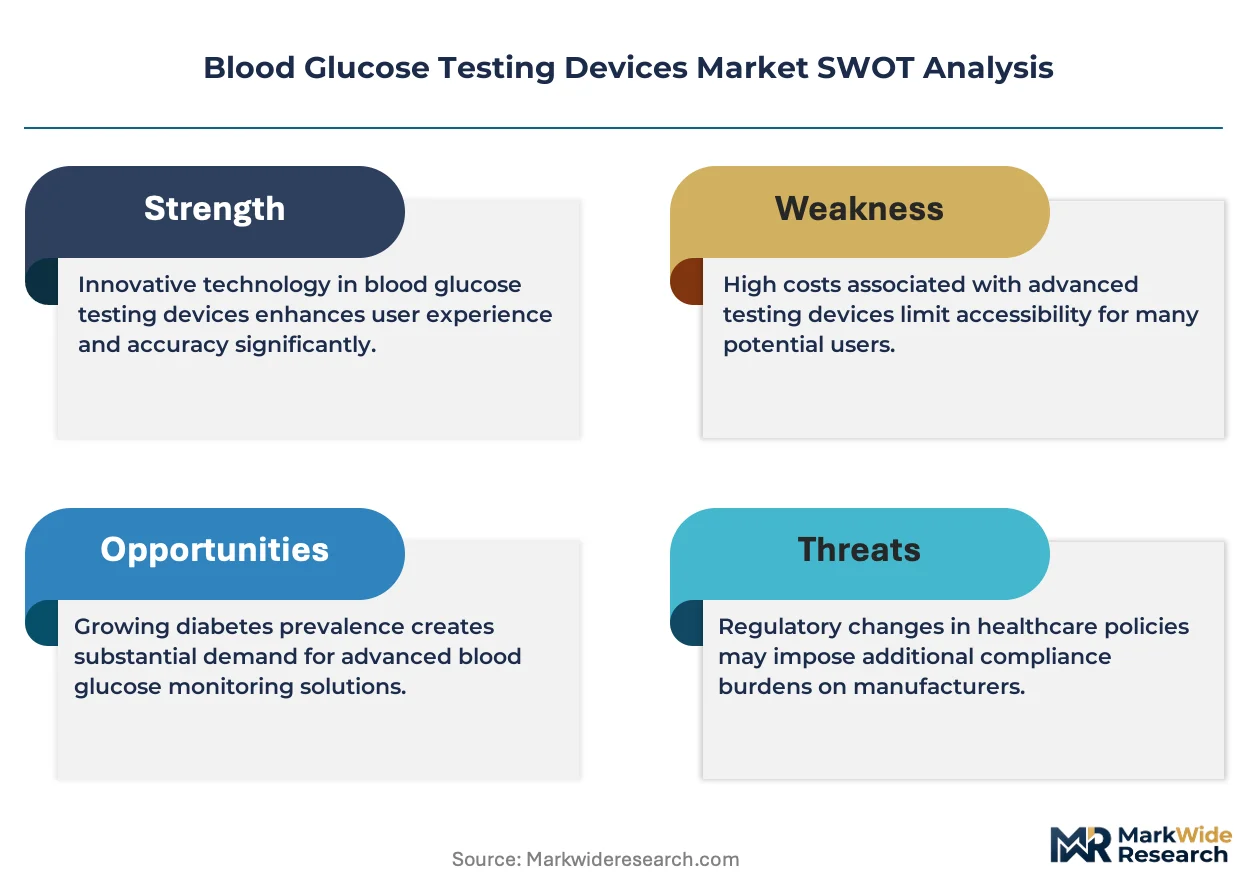
Continuous glucose monitoring is virtualizing the traditional fingerstick paradigm, compressing reimbursement windows and forcing manufacturers to prove time-in-range superiority over episodic testing in payer negotiations.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for non-adjunctive continuous glucose monitors removes prior authorization barriers for homecare patients in the United States.
- Time-in-Range Metrics:Endocrinology practices now prioritize glycemic variability data over HbA1c snapshots, elevating sensor-based systems in clinical protocols.
- Homecare Migration:Diabetes management is shifting from hospital outpatient clinics to residential settings, expanding addressable device volumes outside traditional channels.
Market Restraints
- Sensor Cost Structure:Platinum-based electrode materials and enzymatic reagent stability requirements create persistent manufacturing cost floors.
- Supply Concentration:Subcutaneous sensor membrane production clusters in single-source contract manufacturers, exposing volumes to geographic disruption risk.
- FDA Accuracy Thresholds:21 CFR 862.1355 premarket notification requirements extend development timelines for novel optical sensing approaches.
Strategic Opportunities
- Underpenetrated Rural Markets:Telehealth-integrated continuous monitors can reach patients in non-urban United States counties where endocrinologist density falls below national medians.
- Smart Pen Convergence:Bluetooth-enabled insulin delivery devices that capture dose-timing data create new revenue pools at the drug-device interface.
- EMA MDR Streamlining:Synchronized technical documentation pathways for EU member states reduce redundant conformity assessment costs for manufacturers.
Industry Challenges
- Algorithm Validation Talent:Real-time glucose prediction modeling requires scarce expertise in signal processing and metabolic physiology.
- Legacy System Integration:Electronic health record interoperability with proprietary CGM data formats creates implementation friction in hospital networks.
- ISO 15197 Recertification:Inter-laboratory performance validation cycles consume 18-24 months for product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Glucose Testing Devices Market |
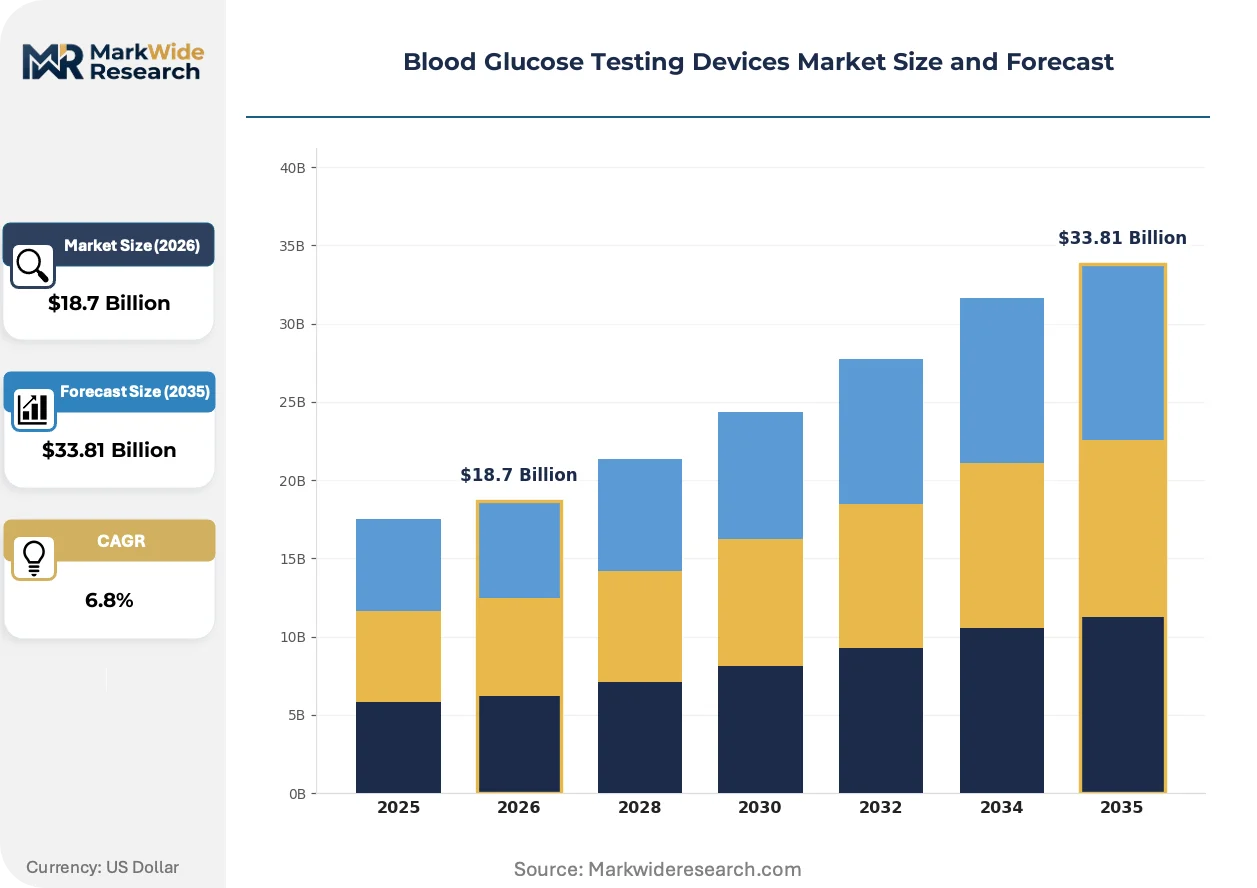
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Self-Monitoring, Continuous Glucose Monitors, Smart Pens, Test Strips End User: Homecare, Hospitals, Clinics, Pharmacies Technology: Enzymatic, Non-Enzymatic, Spectroscopy, Microfluidics Distribution Channel: Online Retail, Medical Stores, Direct Sales, Wholesale |
| Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, Ascensia Diabetes Care Holdings AG, LifeScan IP Holdings, LLC, Senseonics Holdings, Inc., ARKRAY, Inc., Ypsomed Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Glucose Testing Devices Market Evolving Landscape
Sensor miniaturization and algorithmic prediction are compressing the feedback loop between glucose detection and therapeutic response, while regulatory frameworks race to validate non-invasive alternatives.
Factory-calibrated continuous glucose monitors are virtualizing the patient onboarding experience by eliminating fingerstick calibration requirements. Homecare adopters in Germany and Japan are migrating to these systems at accelerated rates. The technology is virtualizing traditional pharmacy distribution models by enabling direct-to-patient subscription channels that bypass retail intermediaries.
EMA MDR classification for Class III active implantable devices is tightening post-market surveillance obligations for sensor-integrated systems. Manufacturers must now submit periodic safety update reports across all EU member states where devices are marketed. Ambulatory care segments in France and the Netherlands are responding by consolidating supplier relationships to reduce compliance overhead.
Patients are consolidating device preferences around ecosystems that unify glucose data, insulin dosing, and clinician dashboards. Hospital procurement committees in the United States are replacing standalone meter contracts with platform subscriptions. This behavioral shift is most visible in integrated delivery networks where value-based care contracts incentivize glycemic outcome guarantees.
Blood Glucose Testing Devices Market Segmentation
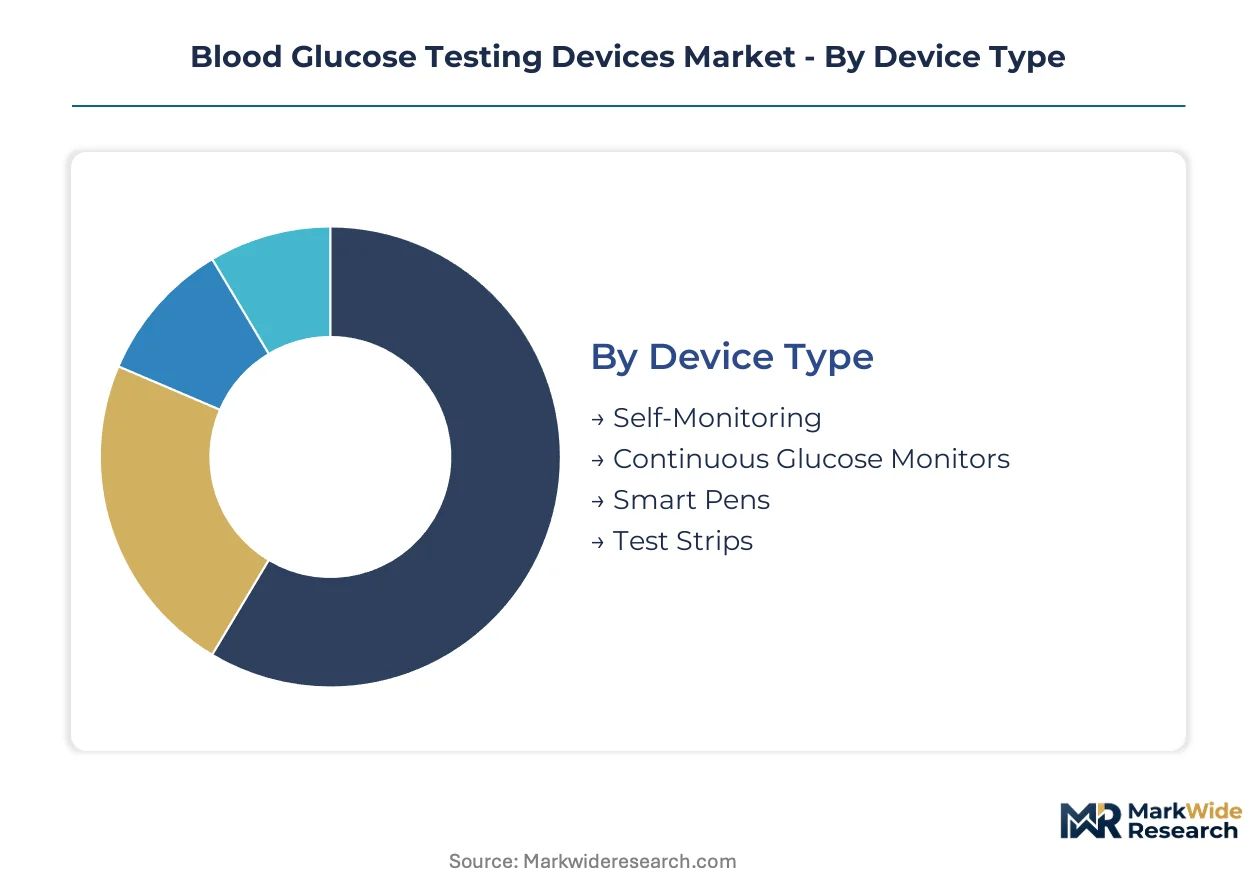
Segmentation in blood glucose testing devices reveals distinct replacement cycles and margin profiles. Device type and technology choices determine whether manufacturers capture recurring consumable revenue or one-time hardware sales. Understanding these patterns is essential for aligning production capacity with demand velocity across patient settings.
Device Type:
Replacement cycles vary dramatically across this category, with consumable-driven segments turning over fastest and capital equipment moving slowest. Sensor-based systems require 10-14 day replacement intervals, while meter hardware persists for years.
- Continuous Glucose Monitors:Factory-calibrated sensor-receiver systems capture glucose data at 1-5 minute intervals through subcutaneous filament technology. Demand concentrates in Germany and Japan where reimbursement frameworks favor time-in-range monitoring, though platinum electrode costs constrain margin expansion.
- Self-Monitoring:Electrochemical strip-based systems dominate unit volumes through fingerstick capillary sampling. Homecare patients in the United States retain these for backup calibration, creating stable replacement demand even as CGM penetration advances.
- Smart Pens:Bluetooth-enabled insulin delivery devices with dose-logging capabilities.
- Test Strips:Disposable enzymatic reagent strips for episodic glucose measurement.
Self-Monitoring anchors the volume base while Continuous Glucose Monitors gains share at the steepest rate.
End User:
Procurement authority and reimbursement pathways diverge sharply across patient settings. Homecare purchases flow through pharmacy benefit managers, while hospital procurement operates under group purchasing organization contracts.
- Homecare:Patients managing diabetes in residential settings drive the majority of device utilization. CMS reimbursement expansion for non-adjunctive CGM in the United States removed prior authorization barriers, accelerating residential adoption beyond clinical settings.
- Hospitals:Acute care facilities require FDA-cleared devices under 21 CFR 862.1355 for inpatient glycemic management. Integrated delivery networks in the United States are consolidating contracts around platform subscriptions rather than standalone meters.
- Clinics:Outpatient endocrinology practices.
- Pharmacies:Retail distribution points for over-the-counter and prescription devices.
Homecare generates the highest absolute volume while Hospitals deliver the most concentrated contract values.
Technology:
Enzymatic approaches face stability constraints that non-enzymatic alternatives seek to circumvent. Manufacturing complexity and regulatory validation burden vary substantially across detection principles.
- Enzymatic:Glucose oxidase or glucose dehydrogenase reactions with electrochemical signal transduction. Production clusters around contract manufacturers with membrane coating expertise, exposing supply chains to geographic concentration risk.
- Non-Enzymatic:Direct electrochemical detection without biological reagents. Research pipelines focus on platinum nanoparticle electrodes for improved stability, though FDA accuracy thresholds under 21 CFR 862.1355 extend development timelines.
- Spectroscopy:Optical glucose detection through near-infrared or Raman methods.
- Microfluidics:Miniaturized fluid handling for integrated sample processing.
Enzymatic systems retain commercial dominance while Non-Enzymatic approaches climb the fastest toward regulatory clearance.
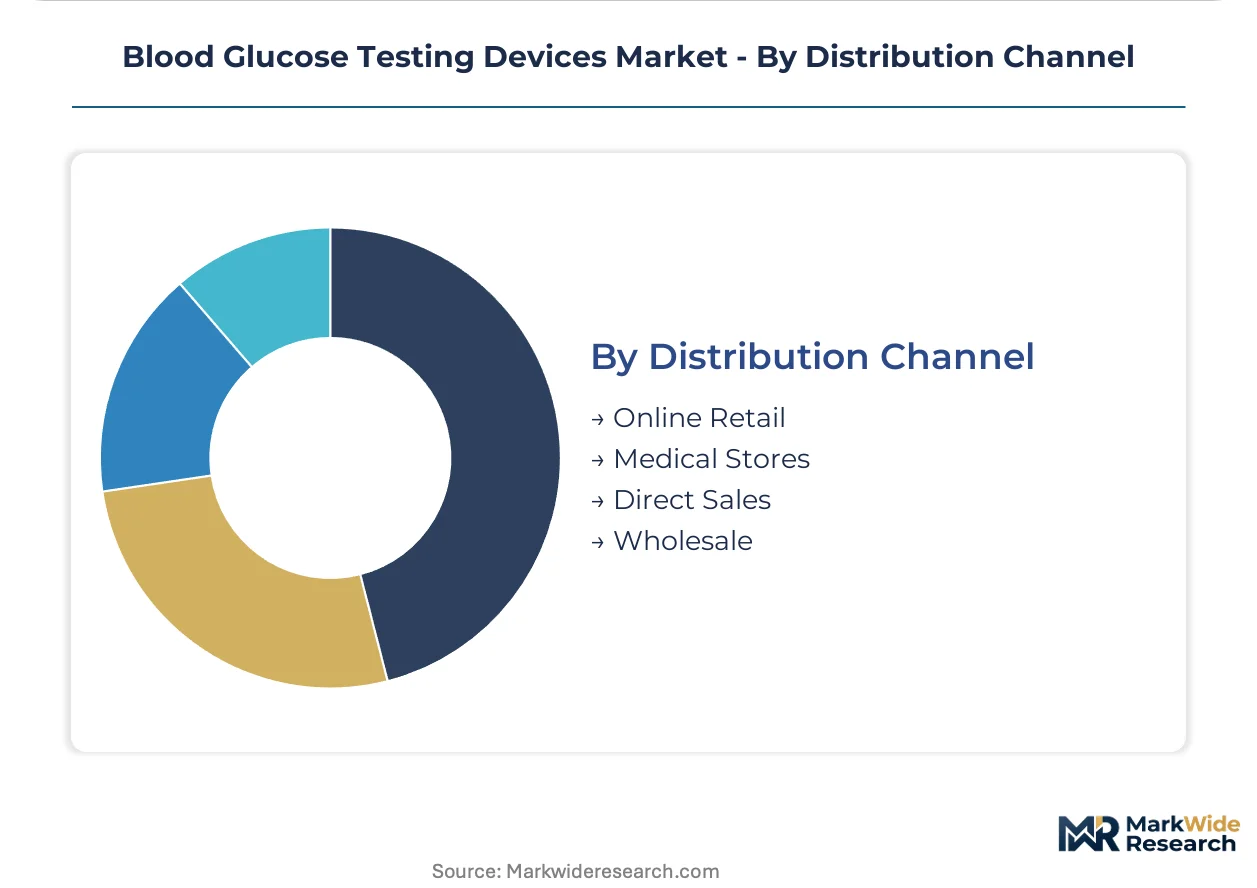
Distribution Channel:
Channel selection determines patient onboarding friction and recurring revenue capture. Direct subscription models are virtualizing traditional pharmacy distribution.
- Online Retail:E-commerce platforms enable direct-to-patient subscription channels that bypass retail intermediaries. Germany and Japan show accelerated migration to these models for factory-calibrated CGM systems.
- Medical Stores:Brick-and-mortar pharmacies and durable medical equipment suppliers. These retain importance for first-time device training and Medicare documentation requirements in the United States.
- Direct Sales:Manufacturer-controlled distribution to health systems.
- Wholesale:Third-party logistics and inventory pooling for retail chains.
Medical Stores maintain the broadest geographic reach while Online Retail expands most quickly among tech-adopter patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export factory-calibrated continuous glucose monitors to Japanese healthcare distributors under long-term supply agreements. United States-based sensor producers ship subcutaneous filament systems to German hospital procurement networks. Japanese precision electronics suppliers deliver receiver components to Abbott Laboratories' North American assembly facilities.
United States
CMS reimbursement expansion for non-adjunctive CGM removed prior authorization barriers, accelerating residential adoption beyond clinical settings. FDA premarket notification requirements under 21 CFR 862.1355 enforce analytical accuracy thresholds that shape product development timelines for market entrants. Minneapolis anchors Medtronic plc's hospital channel relationships that extend into ambulatory connected care ecosystems.
Germany
Endocrinology practices prioritize glycemic variability data over HbA1c snapshots, elevating sensor-based systems in clinical protocols. EMA MDR classification tightens post-market surveillance obligations for sensor-integrated systems across EU member states. Mannheim concentrates Ascensia Diabetes Care Holdings AG's European distribution infrastructure for self-monitoring blood glucose systems.
Japan
Reimbursement frameworks favor time-in-range monitoring, driving accelerated migration to factory-calibrated CGM systems. METI standards govern medical device software validation for real-time glucose prediction algorithms. Kyoto clusters ARKRAY, Inc.'s electrochemical sensor manufacturing for strip-based glucose measurement devices.
United Kingdom
National Health Service procurement committees consolidate contracts around platform subscriptions rather than standalone meters. MHRA operates as the national pharmaceutical regulator enforcing post-Brexit device registration requirements. Oxfordshire hosts emerging telehealth-integrated monitor deployments targeting rural counties where endocrinologist density falls below national medians.
Switzerland
Payers prioritize time-in-range metrics over episodic readings, concentrating demand for continuous monitoring systems. Swissmedic classification pathways align with EMA MDR technical documentation standards for streamlined EU market access. Basel anchors F. Hoffmann-La Roche Ltd's vertically integrated biosensor research operations.
Blood Glucose Testing Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital procurement networks and direct-to-patient subscription channels. The vendor base organizes around three strategic archetypes: vertically integrated biosensor manufacturers, algorithm-focused real-time monitoring specialists, and hospital channel incumbents extending into ambulatory care. Dominant competitive moves include strategic partnerships with insulin delivery device makers and portfolio diversification into smart pen convergence products.
Among United States-based technology developers, Dexcom, Inc. and Senseonics Holdings, Inc. occupy positions within the real-time glucose monitoring archetype, exemplifying algorithm-centric competitive positioning. Abbott Laboratories, a Delaware-registered corporation, anchors the vertically integrated tier through captive biosensor manufacturing control. Swiss-domiciled F. Hoffmann-La Roche Ltd represents the diversified diagnostics conglomerate model with historical strength in laboratory channel relationships.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom, Inc. |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Ascensia Diabetes Care Holdings AG |
| LifeScan IP Holdings, LLC |
| Senseonics Holdings, Inc. |
| ARKRAY, Inc. |
| Ypsomed Holdings |
| Others |
Value Network & Pricing Analysis
Kyoto's electrochemical sensor manufacturing cluster shapes downstream pricing power through captive enzyme supply and membrane coating expertise. Platinum electrode costs and enzymatic reagent stability requirements create persistent manufacturing cost floors that manufacturers pass through subscription pricing models.
Pricing Analysis
Factory-calibrated CGM systems command premium positioning against legacy fingerstick meters and emerging non-enzymatic alternatives. Pricing stratifies across premium sensor-receiver ecosystems, standard self-monitoring bundles, and economy strip-based systems, with FDA accuracy tier and real-time algorithm capability as primary differentiation drivers. Cost compression in the standard tier intensifies as vertically integrated biosensor manufacturers exploit captive production. Emerging market patients exhibit highest price sensitivity, while integrated US delivery networks prioritize outcome-linked platform subscriptions over unit economics.
Supply Chain Analysis
US export controls on advanced biosensor manufacturing equipment limit technology transfer to certain Asian production facilities. Subcutaneous sensor membrane production clusters in Japan, Germany, and the United States, drawing from platinum group metal feedstocks, specialized polymer substrates, and precision electronics components. Single-source contract manufacturer concentration in enzymatic reagent coating creates geographic disruption exposure. Distribution runs through direct-to-patient subscription channels that bypass traditional pharmacy intermediaries, particularly for factory-calibrated systems in reimbursed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm validation expertise in real-time glucose prediction modeling represents the critical capability bottleneck constraining competitive entry and acquisition premiums.
For Market Incumbents: Insulate core sensor-receiver ecosystems by deepening backward integration into platinum nanoparticle electrode production and securing exclusive hospital GPO contracts before non-adjunctive CGM reimbursement expands further. Acquire or partner with smart pen developers to control the drug-device interface as insulin delivery converges with dose-data capture. FDA premarket notification timelines for novel optical sensing approaches create a temporary defensive moat against optical disruptors. For New Entrants and Emerging Players: Rural United States counties with endocrinologist density below national medians offer the most penetrable white-space for telehealth-integrated continuous monitors with simplified onboarding. Target German and Japanese homecare segments through direct-to-patient subscription channels that bypass entrenched pharmacy distribution. Pursue EMA MDR technical documentation synchronization to reduce redundant conformity costs across EU member states as the fastest regulatory pathway to commercial scale. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because sensor replacement cycles and software subscription attach rates generate predictable cash flows superior to one-time hardware sales. Target acquisition candidates with validated real-time prediction algorithms and existing CMS reimbursement codes rather than pre-revenue optical sensing ventures. Monitor FDA clearance velocity for non-invasive alternatives as the primary inflection signal threatening incumbent sensor economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Premarket notification under 21 CFR 862.1355 determines competitive entry timing for optical sensing approaches. |
| Smart Pen Ecosystem Integration | Bluetooth-enabled insulin delivery convergence creates new margin pools at the device-drug interface. |
| CMS Reimbursement Strategy | Non-adjunctive CGM coverage determinations dictate adoption velocity across homecare segments regardless of technical advances. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate contracts around platform subscriptions rather than standalone meters. |
| EMA MDR Technical Documentation | Synchronized conformity assessment pathways reduce redundant costs for EU member state market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and CGM platform engineers. Secondary validation drew from FDA 510(k) premarket notification filings, EMA MDR classification databases, CMS Medicare coverage determinations, hospital procurement contract repositories, and ISO 15197 inter-laboratory performance standards. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates across the analysis window.
Calibration against historical CGM adoption curves, self-monitoring blood glucose strip consumption patterns, and smart pen penetration rates informed the analytical framework. Segmentation dimensions modeled include device type, end-user setting, detection technology, and distribution channel complexity alongside regional reimbursement framework clusters. CAGRs derived from fitted adoption S-curves adjusted for regulatory clearance velocity and payer coverage expansion timelines, with sensor replacement frequency and software subscription attach rates as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by non-invasive optical sensing developers or unexpected FDA breakthrough device designations would shift outcomes. Material shifts in CMS national coverage determinations, EMA MDR post-market surveillance enforcement, or platinum group metal supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Rapid Diagnostics Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Population Screening Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market