
 Global Concrete Repair Mortars Market | 2026-2036
Global Concrete Repair Mortars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Repair Mortars Market Foresight
Aftermarket structural refurbishment is rewriting margin distribution across the concrete repair value chain. Sika AG leverages its polymer-modified formulation portfolio to sustain premium positioning in bridge rehabilitation across European markets. MAPEI S.p.A. anchors its competitive stance through specialized trowel-applied systems for industrial flooring, while BASF SE differentiates via integrated supply control over cementitious raw materials.
Concrete repair mortars comprise cementitious or resin-based formulations engineered with compressive strengths exceeding 30 MPa and bond strengths above 1.5 MPa to restore structural integrity in deteriorated concrete elements. These materials are manufactured through controlled blending of Portland cement, graded aggregates, and polymer additives to achieve specified rheology and curing characteristics for load-bearing infrastructure repair. Polymer-modified systems command the dominant share due to superior adhesion and freeze-thaw resistance, while epoxy-based formulations represent the fastest-growing category in marine structure repair where chloride ingress resistance determines specification. Cementitious products occupy the volume-intensive tier for municipal parking deck renewal where cost sensitivity shapes procurement.
EMA durability standards under the EU Green Deal, EPA stormwater infrastructure guidelines, and Japan's METI building lifecycle extension protocols collectively elevate minimum performance thresholds for repair mortar certification. REACH chemical compliance and F-Gas Regulation restrictions on solvent-based systems are forcing reformulation investments that favor pre-packaged mix deployment with documented environmental product declarations. Stakeholders must monitor evolving carbon-emission accounting rules for repair-versus-replace decisions as infrastructure asset managers face capital allocation pressures between full reconstruction and targeted mortar intervention.
Market Dynamics
The EU Green Deal's embodied carbon accounting rules are forcing asset managers to weigh repair-versus-replace decisions differently, redirecting capital from full reconstruction toward targeted mortar intervention in aging infrastructure stock across Germany, the United States, and Japan.
Growth Catalysts
- EMA durability standards:The EU Green Deal mandates extended service-life certification for repair materials, compelling transportation authorities to specify high-performance polymer-modified systems in bridge rehabilitation contracts.
- Japan METI lifecycle extension protocols:Building owners must document structural maintenance intervals, creating systematic demand for cementitious repair mortars in commercial and industrial facility management.
- Chloride ingress resistance:Epoxy-based formulations are capturing specification share in marine structure repair where saltwater exposure accelerates conventional material degradation.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production concentrates in China and India, exposing formulators to input cost swings that compress blended-product margins.
- REACH chemical compliance:ECHA restrictions on solvent-based epoxy systems force reformulation investments that disadvantage smaller regional blenders lacking R&D scale.
- Full-depth reconstruction substitution:Some asset managers prefer complete structural replacement over patch repair when federal infrastructure grants cover replacement costs.
Strategic Opportunities
- India's urban infrastructure deficit:Municipal corporations in Mumbai and Delhi are piloting pre-packaged polymer-modified mortars for metro rail tunnel lining repair under accelerated procurement timelines.
- EPA stormwater infrastructure guidelines:New durability requirements for culvert and drainage structure repair create specification pull for freeze-thaw resistant cementitious systems in US municipal markets.
- Digital mix optimization:IoT-enabled batching systems are converging with predictive deterioration modeling to enable just-in-time mortar deployment based on structural health monitoring data.
Industry Challenges
- Certified applicator scarcity:Polymer-modified and epoxy systems demand specialized surface preparation and curing protocols that exceed the skill base of general concrete contractors.
- EPD documentation burden:Environmental product declaration requirements under EU Green Deal procurement rules extend bid preparation cycles and disqualify suppliers lacking verified lifecycle data.
- Legacy substrate variability:Deteriorated concrete elements present unpredictable moisture and contamination profiles that complicate bond-strength guarantees and warranty pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Repair Mortars Market |
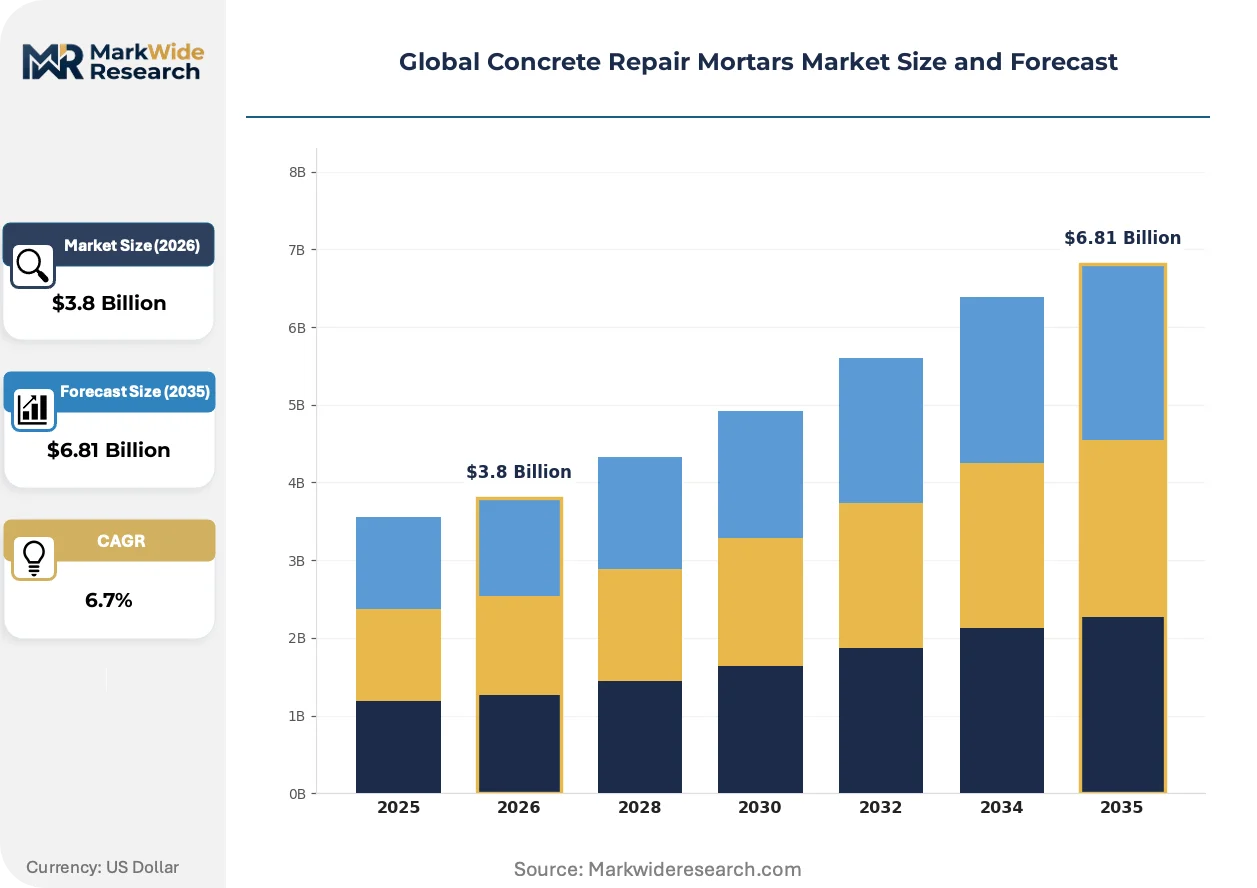
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Modified, Cementitious, Epoxy, Acrylic, Latex, Others Application: Bridge Rehabilitation, Tunnel Restoration, Industrial Flooring, Marine Structure Repair, Parking Deck Renewal, Water Tank Maintenance End User: Construction Contractors, Infrastructure Developers, Industrial Facility Managers, Transportation Authorities, Marine Engineering Firms, Municipal Works Departments Deployment: Pre-packaged Mix, Onsite Mixed, Ready-to-use, Spray-applied, Trowel Applied, Shotcrete |
| Companies Covered | Sika AG, Saint-Gobain, MAPEI S.p.A., BASF SE, Fosroc International, ARDEX GmbH, The Euclid Chemical Company, Pidilite Industries Ltd., Remmers Baustofftechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Repair Mortars Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are compressing traditional specification cycles while elevating performance transparency requirements across public infrastructure procurement.
Self-healing concrete additives incorporating microencapsulated bacteria or mineral precursors are collapsing the distinction between repair and preventive maintenance in water-retaining structures. German wastewater treatment authorities are piloting these systems in tank and channel applications where conventional mortar repair demands repeated intervention. The technology is compressing lifecycle cost models that previously justified cheaper cementitious patching over premium polymer alternatives.
REACH F-Gas Regulation restrictions on solvent-based epoxy formulations are mandating waterborne and high-solids alternatives in European marine and industrial repair applications. Formulators are reconfiguring production lines to eliminate volatile organic compound emissions while maintaining chloride resistance performance. German and Dutch port authorities are specifying these reformulated systems in quay wall rehabilitation contracts under accelerated environmental compliance timelines.
Asset managers are unbundling material supply from installation service in municipal bridge and parking deck contracts, shifting procurement toward certified product lists with owner-managed applicator qualification. This pattern compresses traditional contractor-package bidding and elevates manufacturer technical support responsibilities. The shift is most visible in US state transportation department contracts where design-build-finance models are displacing conventional low-bid procurement.
Global Concrete Repair Mortars Market Segmentation
Segmentation in concrete repair mortars exposes how technical specifications, application environments, and procurement protocols fragment demand across infrastructure asset classes. Specification power concentrates with transportation authorities and industrial facility managers who mandate certified performance tiers, while deployment method choices reflect labor skill availability and project timeline compression.
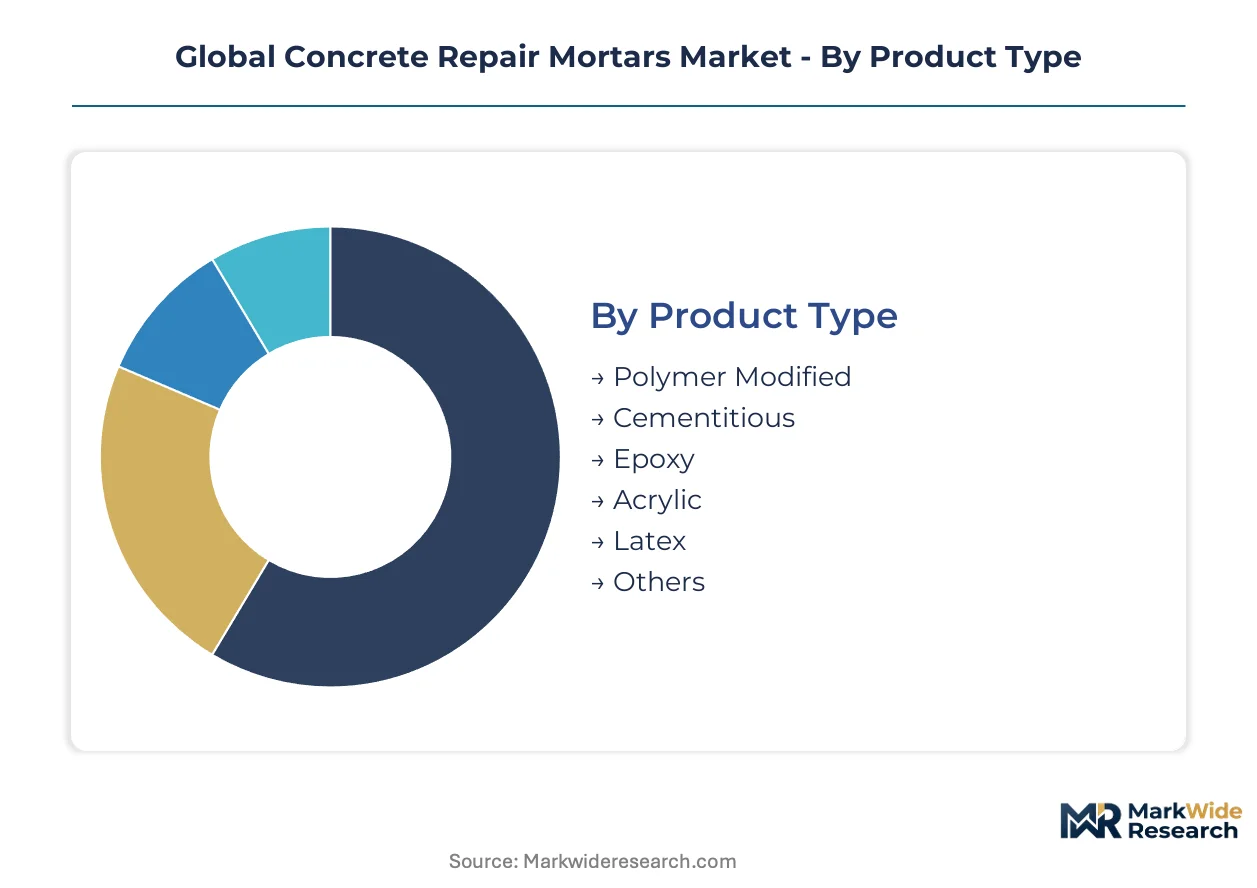
Product Type:
After-sales service intensity varies sharply across formulation chemistries, with polymer-modified and epoxy systems demanding certified applicator networks and technical field support that cementitious products rarely require.
- Polymer Modified:These formulations incorporate styrene-butadiene or acrylic latex emulsions to achieve bond strengths exceeding 2.0 MPa and enhanced freeze-thaw durability. German transportation authorities specify these systems in bridge deck overlays where thermal cycling resistance determines warranty terms. Sika AG and MAPEI S.p.A. maintain dedicated technical service teams for polymer-modified application support across European infrastructure contracts.
- Epoxy:Two-component thermosetting systems deliver compressive strengths above 50 MPa with near-zero permeability to chloride ions. Marine engineering firms in Japanese ports specify epoxy mortars for quay wall rehabilitation where saltwater exposure accelerates conventional material failure. The segment commands premium pricing but requires moisture-tolerant substrate preparation protocols that extend project mobilization timelines.
- Cementitious:Portland cement-based formulations with proprietary shrinkage-compensating additives dominate municipal parking deck renewal where cost sensitivity outweighs performance premiums.
- Acrylic:Water-based systems offering rapid set times and low VOC emissions serve interior industrial flooring repair under EPA and REACH compliance constraints.
- Latex:Natural rubber-modified mortars provide elastomeric crack-bridging capacity in water tank maintenance applications across Indian municipal infrastructure.
- Others:Geopolymer and magnesium phosphate formulations address specialty high-temperature or chemical-resistant repair niches in German industrial facilities.
By volume, cementitious products lead due to municipal cost constraints. By growth pace, epoxy formulations are expanding most quickly on marine infrastructure corrosion mandates.
Application:
Application-driven segmentation reveals how environmental exposure severity and structural load requirements stratify material performance tiers across infrastructure verticals.
- Bridge Rehabilitation:Deck spall repair and bearing pad replacement demand polymer-modified or epoxy systems with documented fatigue resistance under cyclic loading. US state transportation departments specify these materials through certified product lists with owner-managed applicator qualification, compressing traditional contractor-package bidding.
- Tunnel Restoration:Fire-resistant repair mortars with reduced smoke toxicity meet EU safety tunnel directives for transalpine rail corridors. Swiss and Austrian infrastructure managers specify pre-packaged shotcrete-compatible formulations for lining rehabilitation under accelerated procurement timelines.
- Industrial Flooring:Trowel-applied cementitious systems with metallic aggregate reinforcement serve manufacturing facilities where abrasion resistance and rapid return-to-service drive specification.
- Marine Structure Repair:Epoxy and polymer-modified systems with verified chloride diffusion coefficients address saltwater exposure in Japanese port facilities and North Sea offshore platforms.
- Parking Deck Renewal:Carbonation-resistant cementitious mortars with corrosion inhibitor admixtures dominate multi-story structure maintenance in German and US urban centers.
- Water Tank Maintenance:Potable water-certified epoxy and acrylic systems comply with NSF/ANSI 61 and equivalent European drinking water contact standards.
Bridge rehabilitation generates the highest revenue per ton applied. Marine structure repair is climbing the fastest on coastal infrastructure aging and saltwater ingress mandates.
End User:
End user segmentation tracks how procurement authority, technical specification capability, and lifecycle cost modeling sophistication distribute across infrastructure ownership models.
- Transportation Authorities:German federal highway administration and US state DOTs wield specification power through design-build-finance contracts that unbundle material supply from installation service, elevating manufacturer technical support responsibilities.
- Industrial Facility Managers:Japanese automotive and chemical plant operators document structural maintenance intervals under METI lifecycle extension protocols, creating systematic demand for certified repair mortar systems with verified durability data.
- Construction Contractors:General concrete contractors without specialized surface preparation equipment favor pre-packaged cementitious systems for volume-driven municipal contracts.
- Infrastructure Developers:Private toll road and airport concession operators specify high-performance systems to minimize lifecycle maintenance cost in availability-payment contracts.
- Marine Engineering Firms:Port authority contractors in Rotterdam and Singapore specify epoxy systems with applicator certification requirements that exclude generalist bidders.
- Municipal Works Departments:Indian urban corporations in Mumbai and Delhi pilot polymer-modified pre-packaged mortars for metro rail tunnel repair under compressed procurement timelines.
Transportation authorities command the highest specification rigor. Industrial facility managers are gaining procurement influence fastest on regulatory maintenance documentation requirements.
Deployment:
Deployment method segmentation captures the tension between quality assurance, labor skill requirements, and project schedule acceleration across infrastructure repair programs.
- Pre-packaged Mix:Factory-controlled blending with documented environmental product declarations satisfies EU Green Deal procurement rules and EPA stormwater infrastructure guidelines. German and Dutch authorities mandate these systems for bridge and culvert repair to eliminate onsite proportioning variability.
- Ready-to-use:Single-component moisture-tolerant formulations eliminate field mixing errors in confined tunnel and tank applications where ventilation constraints complicate two-component epoxy deployment.
- Onsite Mixed:Bulk cement and additive proportioning persists in emerging market municipal contracts where material cost minimization outweighs quality assurance premiums.
- Spray-applied:Wet-mix shotcrete systems with silica fume modification serve vertical and overhead repair in US dam rehabilitation and Indian hydroelectric tunnel lining.
- Trowel Applied:High-build epoxy and polymer-modified mortars with extended working times enable precision finish in industrial flooring and marine structure rehabilitation.
- Shotcrete:Dry-mix gunite systems with accelerators address emergency structural stabilization in seismic-damaged Japanese infrastructure and US earthquake-prone zones.
Pre-packaged mix leads by specification frequency in regulated markets. Ready-to-use systems are gaining share fastest on certified applicator scarcity and compressed project timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China weigh material cost above performance certification, while German and Japanese transportation authorities prioritize durability guarantees regardless of price premium. This elasticity divergence fragments procurement patterns across infrastructure markets.
United States
State transportation departments unbundle material supply from installation contracts, elevating manufacturer technical support obligations. EPA stormwater infrastructure guidelines mandate freeze-thaw resistant cementitious systems for culvert rehabilitation. Metropolitan clusters in Chicago and Los Angeles pilot pre-packaged polymer-modified mortars for parking deck renewal under compressed municipal timelines.
Germany
Federal highway administration specifications favor polymer-modified systems with documented fatigue resistance in bridge deck overlays. EU Green Deal embodied carbon accounting redirects capital from reconstruction toward targeted mortar intervention. Industrial concentration in North Rhine-Westphalia drives demand for high-temperature geopolymer formulations in chemical plant maintenance.
Japan
METI lifecycle extension protocols compel building owners to document structural maintenance intervals, creating systematic demand for certified repair systems. Port authorities in Osaka and Yokohama specify epoxy mortars with moisture-tolerant substrate preparation for quay wall rehabilitation. Seismic retrofit programs accelerate shotcrete deployment in Kanto region infrastructure.
India
Municipal corporations in Mumbai and Delhi pilot pre-packaged polymer-modified mortars for metro rail tunnel lining under accelerated procurement timelines. Central Public Works Department cost sensitivity sustains bulk cement and additive proportioning in volume-driven contracts. Western India industrial corridors generate demand for abrasion-resistant cementitious flooring systems in manufacturing facilities.
United Arab Emirates
Infrastructure developers specify high-performance systems to minimize lifecycle maintenance costs in availability-payment contracts for toll roads and airports. Dubai Municipality mandates environmental product declarations for public procurement, favoring pre-packaged factory-controlled blends. Coastal exposure in Abu Dhabi port facilities drives specification of chloride-resistant epoxy formulations.
Global Concrete Repair Mortars Market Competitive Landscape
Specialized formulation developers and integrated chemical conglomerates split the market between premium specification channels and volume-driven municipal procurement. The vendor base concentrates among European and Swiss parent companies with dedicated construction chemical divisions, while Asian manufacturers compete on cost in emerging market bulk contracts. Three archetypes dominate: polymer-modification specialists, cementitious system generalists, and epoxy formulators with marine engineering certification. Competitive moves center on certified applicator network expansion and environmental product declaration acquisition to satisfy EU Green Deal procurement rules.
Among Swiss-anchored specialists, Sika AG exemplifies the polymer-modification archetype through its bridge rehabilitation focus across European markets. MAPEI S.p.A. and BASF SE occupy distinct positioning within the formulation tier, with the Italian entity representing specialized trowel-applied system development and the German conglomerate anchoring integrated supply control over cementitious raw materials.
| Leading Market Players |
|---|
| Sika AG |
| Saint-Gobain |
| MAPEI S.p.A. |
| BASF SE |
| Fosroc International |
| ARDEX GmbH |
| The Euclid Chemical Company |
| Pidilite Industries Ltd. |
| Remmers Baustofftechnik GmbH |
| Others |
Supply & Pricing Matrix
Clinker production concentration in China and India exposes formulators to energy-cost volatility that compresses blended-product margins and redirects margin pools toward polymer-modified and epoxy system specialists with formulation differentiation. Cementitious generalists absorb the steepest input-cost pressure while premium tiers capture service-anchored value.
Pricing Analysis
After-sales technical service contracts drive lifetime value for polymer-modified and epoxy system manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates certified applicator-supported formulations from pre-packaged cementitious blends. Cost compression in bulk cementitious tiers is intensifying because municipal procurement favors lowest-bid material supply. Transportation authorities exhibit least price sensitivity; Indian municipal corporations demonstrate highest.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms are becoming standard for qualified applicator networks serving transportation authority contracts. Raw material sourcing draws from China and India for Portland cement clinker, Germany and Switzerland for specialty polymer additives, and Japan for epoxy resin precursors. Single-source vulnerability concentrates in energy-intensive clinker production. Distribution runs through certified product lists with owner-managed applicator qualification displacing traditional contractor-package bidding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
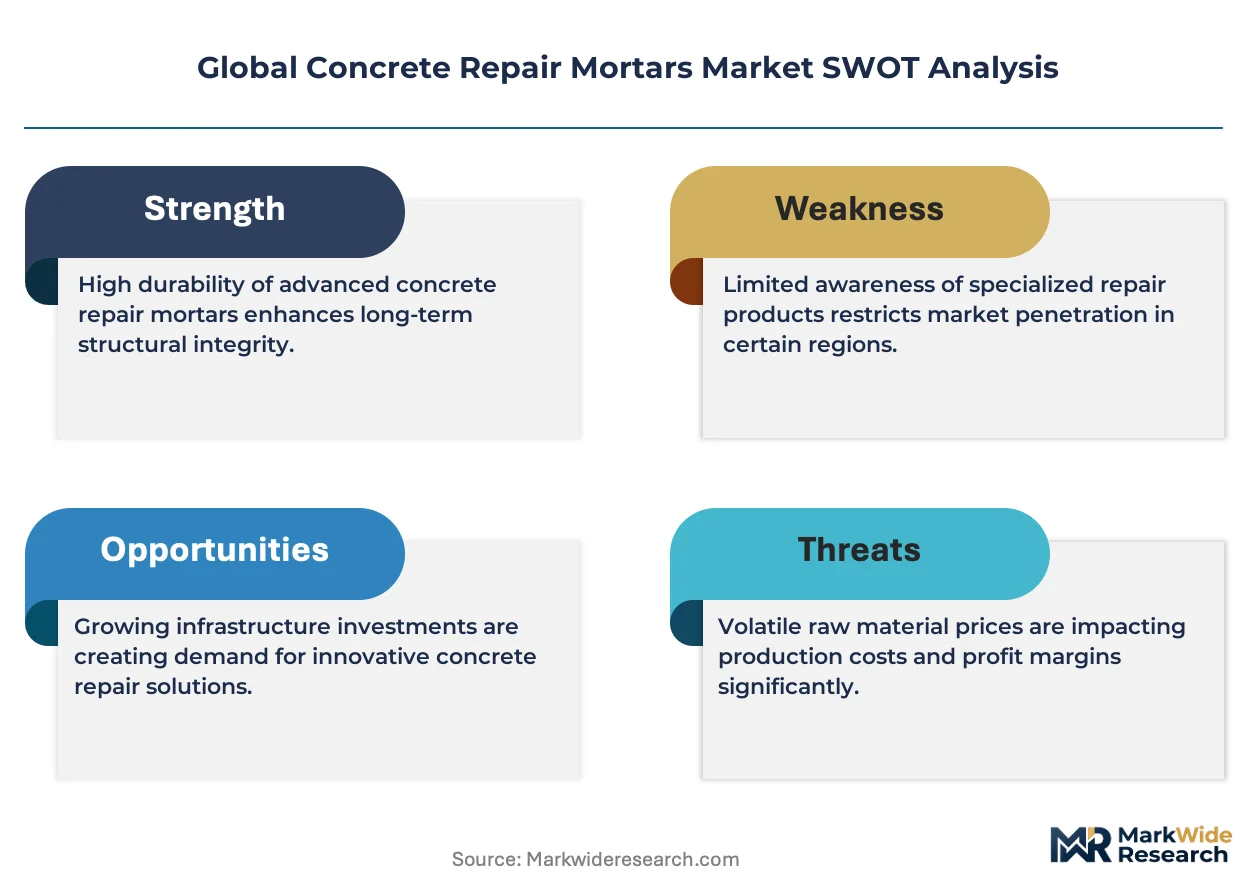
Full-depth reconstruction substitutes threaten patch-repair mortar demand when federal infrastructure grants cover replacement costs, forcing incumbents to demonstrate lifecycle cost superiority.
For Market Incumbents: Insulate specification position by deepening certified applicator networks and acquiring environmental product declarations ahead of EU Green Deal procurement expansion. Backward integration into cementitious raw materials buffers margin compression from clinker price volatility. Priority investment targets polymer-modification R&D for chloride-resistant marine formulations. For New Entrants and Emerging Players: Establish a beachhead in India's metro rail tunnel repair segment where accelerated procurement timelines favor pre-packaged polymer-modified systems over established bulk-mix suppliers. Target municipal corporations in Mumbai and Delhi with technical service partnerships that address certified applicator scarcity. Go-to-market angle centers on documented freeze-thaw performance under compressed project schedules. For Investors and Strategic Acquirers: Capital is best deployed toward polymer-modification specialists with bridge rehabilitation certification and established EPD libraries. Long-term viability hinges on regulatory maintenance-documentation mandates spreading from Japan METI protocols to European and North American jurisdictions. Signal to monitor: adoption of digital mix optimization converging with structural health monitoring data.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive clinker supply buffers Sika AG and BASF SE from energy-cost volatility. |
| Certified Applicator Network Expansion | MAPEI S.p.A. technical service teams secure transportation authority specification lock-in. |
| Environmental Product Declaration Acquisition | Documented lifecycle data satisfies EU Green Deal procurement disqualification thresholds. |
| Digital Mix Optimization Partnership | IoT-enabled batching convergence with predictive deterioration modeling enables just-in-time deployment. |
| Marine Formulation R&D Investment | Epoxy systems with verified chloride diffusion coefficients capture Japanese port authority contracts. |
Research Methodology
A standing panel of transportation authority specification engineers, industrial facility maintenance directors, certified mortar applicators, and construction chemical procurement leads provided ongoing calibration across primary interview rounds. Secondary validation drew from customs and trade data, SEC 10-K filings of listed construction chemical divisions, EU Green Deal procurement documentation, and EPA stormwater infrastructure guideline releases. Bottom-up volume modeling triangulated against top-down infrastructure spending forecasts.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across formulation chemistry, application environment, deployment method, and end-user procurement authority. CAGRs derived from infrastructure investment pipeline analysis and regulatory maintenance-interval mandates. Industry-specific inputs incorporated bridge rehabilitation backlog data, marine structure corrosion inspection frequencies, and municipal parking deck renewal cycle documentation.
Stress conditions across Portland cement price volatility, REACH chemical compliance timeline acceleration, and certified applicator availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure grant allocation patterns and regulatory durability standard evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Fire Rated Duct Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Gutter and Downspout Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Floor Screeds Market