
 Global Door Market | 2026-2036
Global Door Market Size, Share, and Industry Trends Forecast 2026-2036
Global Door Market Analysis
Skilled millwright labor scarcity is redrawing manufacturing footprints across the door industry. Assa Abloy leverages its access control integration to dominate commercial specification channels. JELD-WEN Holding Inc. anchors North American fiberglass production through captive pultrusion capacity. Masonite competes on molded panel density and finish consistency in big-box retail.
A door is a movable barrier, typically hinged, sliding, or rolling, engineered to seal an aperture with specified acoustic, thermal, or fire-resistance ratings measured in minutes of integrity retention. Its primary industrial purpose is to control environmental separation, security access, and life-safety egress in built structures. Interior doors generate the highest volume throughput but thinner margins, while security doors capture premium pricing through multi-point locking and ballistic certification. Aluminum framing is displacing steel in coastal commercial applications due to corrosion performance, though wood maintains brand strength in luxury residential specification.
The EPA regulates volatile organic compound emissions from door coatings through 40 CFR Part 63 Subpart QQQQ, while the EU Green Deal's embodied carbon requirements are reshaping material sourcing for European imports. China's SAMR enforces GB standards for fire-rated door assemblies in high-rise construction. India's BIS certification for fire doors is tightening market access for uncertified imports. Stakeholders must monitor divergence between regional fire-test protocols and embodied-carbon accounting rules to avoid stranded inventory in cross-border projects.
Market Dynamics
Skilled millwright labor scarcity is redrawing manufacturing footprints across the door industry, forcing producers to consolidate pultrusion operations and automate finishing lines. This structural compression intersects with diverging fire-test protocols between GB standards, EN classifications, and NFPA methods.
Growth Catalysts
- GB Fire-Rated Standards:China's SAMR enforcement of GB 12955 for high-rise fire door assemblies is accelerating certified production capacity expansion in Shandong and Jiangsu provinces.
- Fiberglass Pultrusion:Residential construction in suburban India is accelerating demand for fiberglass entry systems with thermal break performance.
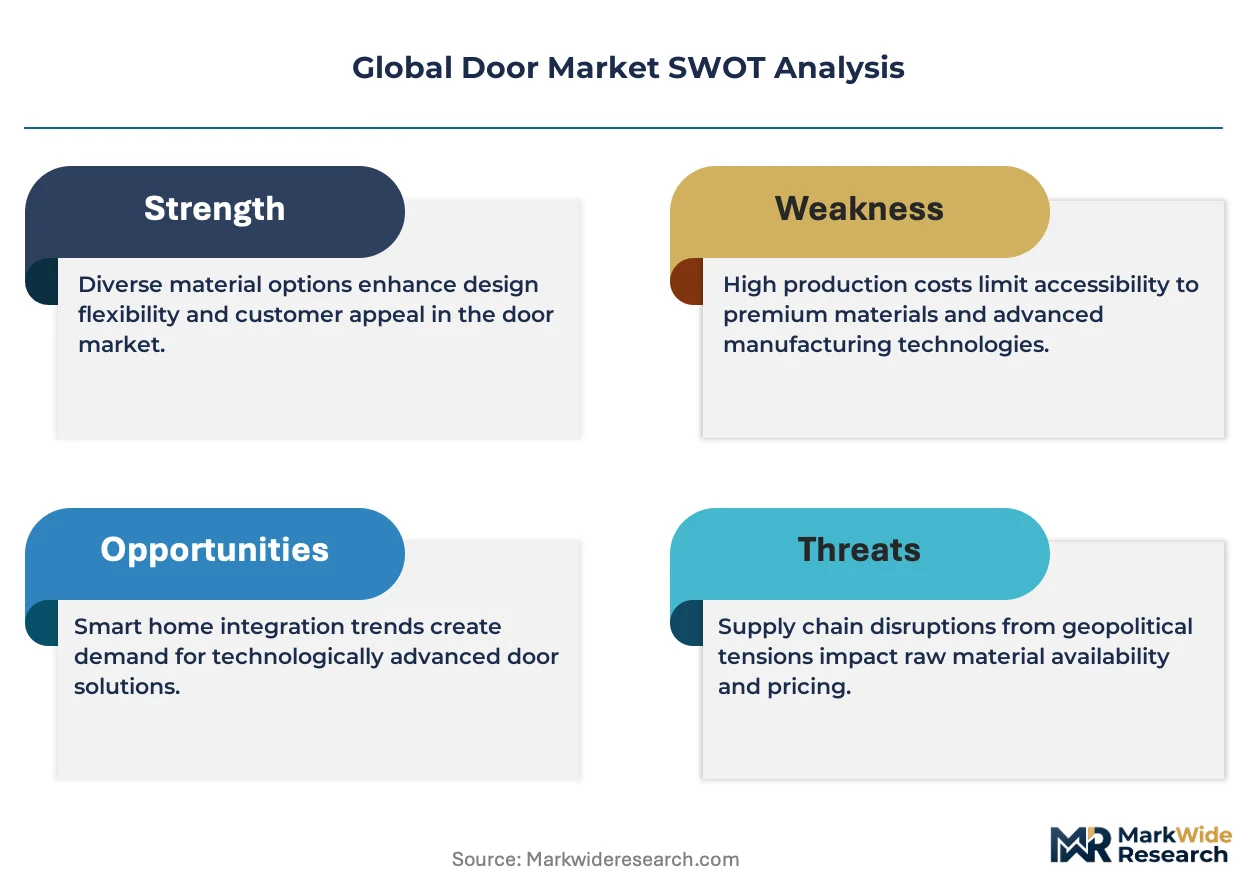
- CE Marking Expansion:Europe's Construction Products Regulation tightening on embodied carbon is pulling low-carbon aluminum framing into commercial specification channels.
Market Restraints
- Resin Price Volatility:Unsaturated polyester and epoxy feedstock costs fluctuate with crude oil derivatives, compressing fiberglass door margins unpredictably.
- Test Protocol Divergence:Stranded inventory risk rises when single production runs must satisfy NFPA 252, EN 1634-1, and GB 9978 simultaneously.
- Steel Substitution Pressure:Aluminum framing captures coastal commercial share due to salt-corrosion performance, eroding traditional steel specification.
Strategic Opportunities
- India BIS Certification Gap:Uncertified import displacement creates white space for domestic fire door producers meeting IS 3614 standards.
- Access Control Convergence:Electromechanical locking and biometric reader integration into door slabs opens premium commercial specification.
- EU Green Deal Tailwind:Embodied carbon accounting rules favor regional sourcing of FSC-certified wood cores and recycled aluminum billets.
Industry Challenges
- Millwright Skill Scarcity:CNC machining and automated finishing line operation expertise concentrates in aging workforces across Ohio and Ontario.
- Multi-Protocol Certification Timelines:Third-party fire testing backlogs at UL, Intertek, and CNAS laboratories extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Door Market |
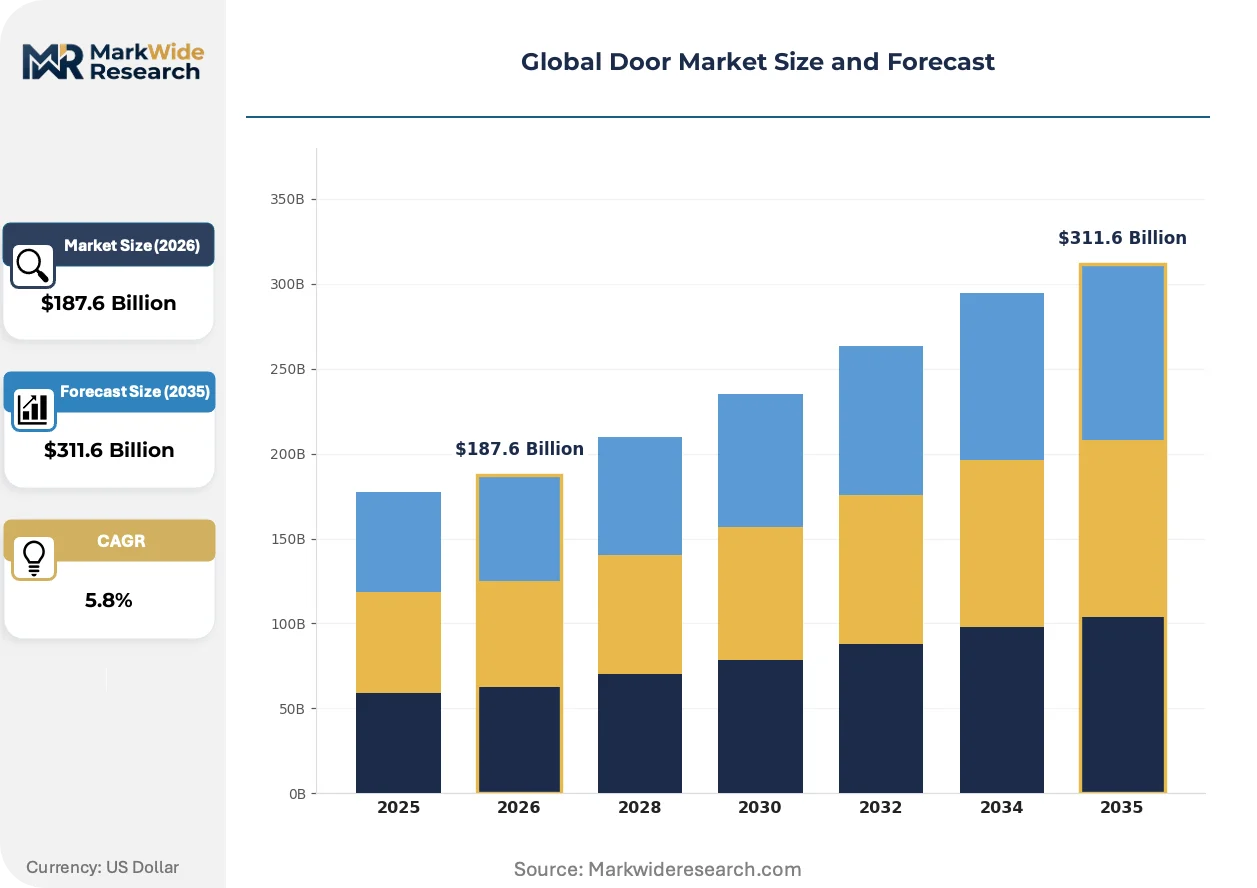
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Doors, Exterior Doors, Security Doors, Fire Doors Material: Wood, Steel, Aluminum, Fiberglass End User: Residential, Commercial, Industrial, Institutional Opening Mechanism: Hinged, Sliding, Folding, Rolling |
| Companies Covered | Assa Abloy, JELD-WEN Holding Inc., Andersen Corporation, Pella Corporation, Masonite, Simpson Door Company, Allegion plc, dormakaba Group, LIXIL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Door Market Emerging Trajectories
Material science and regulatory accounting are splitting the door market into performance-tiered supply chains. Producers now engineer for either code-minimum replacement cycles or decades-long institutional asset life.
Smart lock and access control integration is bifurcating the commercial metal door segment. Electromechanical mortise locks with Bluetooth and NFC credentialing are penetrating Class A office and healthcare facilities in the United States and Germany. This technology is compressing traditional mechanical hardware specification into commodity bid packages while premium integrated slab-and-electronics systems capture specification margins.
REACH and the EU Green Deal's embodied carbon requirements are reshaping material sourcing for European imports. Suppliers must now document cradle-to-gate carbon for steel cores, aluminum extrusions, and wood substrates. German and Dutch commercial projects are rejecting uncertified Asian fiberglass imports in favor of regional pultrusion with EPD verification.
Big-box retail buyers are consolidating vendor relationships around finish consistency and molded panel density. Masonite and JELD-WEN compete for shelf space through SKU rationalization and guaranteed 48-hour fulfillment from regional distribution centers. This concentration is visible in the Sun Belt United States, where replacement cycle compression and new construction volume reward inventory-heavy suppliers.
Global Door Market Segmentation
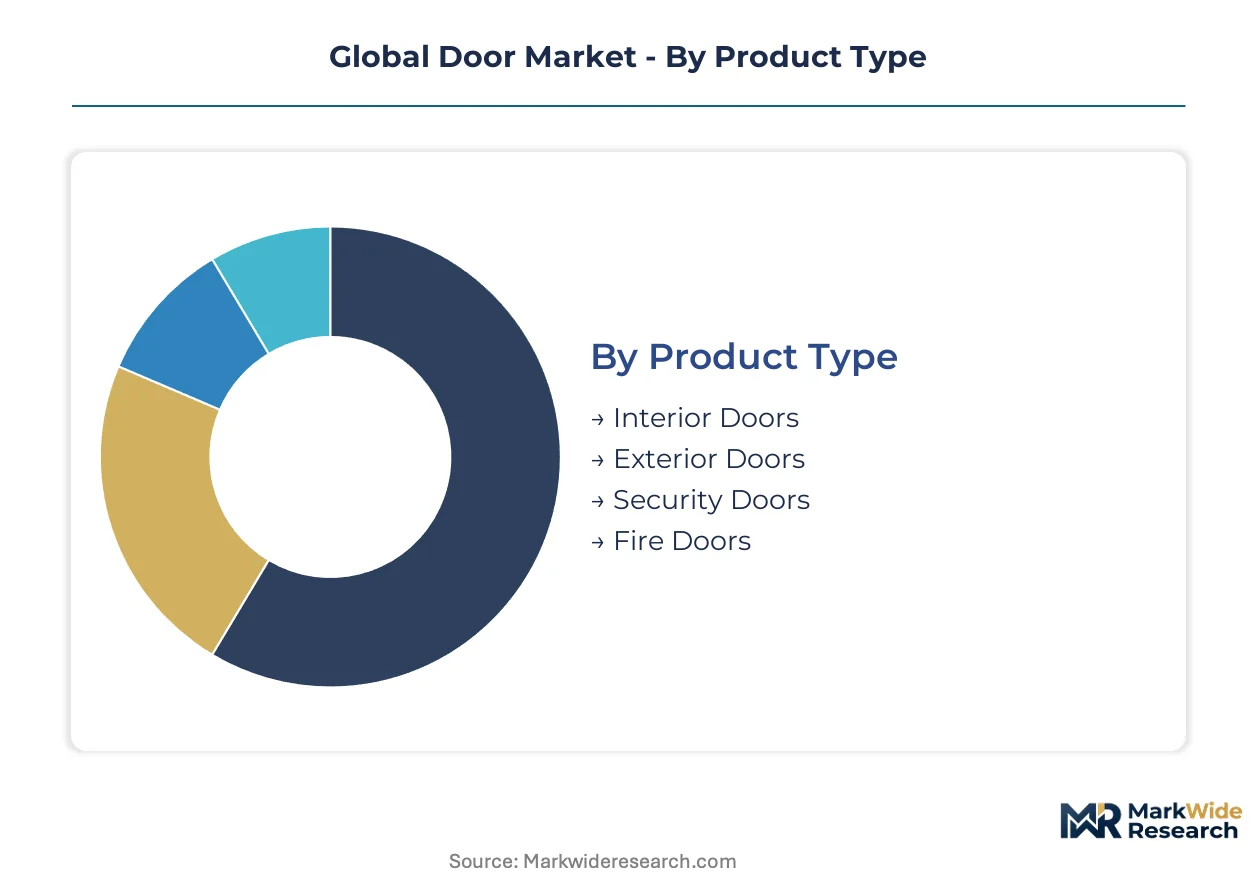
Door manufacturers configure production lines around distinct margin architectures. Product type determines certification burden and replacement cycle length, while material selection drives embodied carbon accounting and regional sourcing strategy.
Product Type:
Margin pools concentrate in certified safety products where third-party testing creates pricing power.
- Interior Doors:Hollow-core and solid-core configurations dominate residential volume. Demand concentrates in suburban United States and India where finish consistency and rapid fulfillment determine vendor selection. Big-box retail consolidation rewards suppliers with regional distribution density.
- Exterior Doors:Fiberglass and steel entry systems with thermal break performance command specification premium. Climate zone divergence between Northeast freeze-thaw cycles and Sun Belt humidity is fragmenting product requirements. Coastal corrosion resistance is displacing traditional steel in Florida and Gulf Coast markets.
- Security Doors:Multi-point locking and ballistic certification capture institutional specification. Banking and data center end-users in Germany and Saudi Arabia drive demand for certified forced-entry resistance.
- Fire Doors:GB 12955, EN 1634-1, and NFPA 252 certification timelines extend production cycles. High-rise construction in China and fire code tightening in India are accelerating certified capacity expansion.
The dominant share belongs to Interior Doors, while Fire Doors is closing the gap fastest.
Material:
Cost tier stratification separates commodity substitution from premium specification channels.
- Wood:FSC-certified cores and veneer consistency maintain luxury residential positioning. European Green Deal embodied carbon rules are pulling regional hardwood sourcing into Dutch and German commercial projects.
- Steel:Galvanized and stainless configurations retain institutional fire-rated specification. Salt-corrosion vulnerability is eroding coastal commercial share to aluminum alternatives.
- Aluminum:Low-carbon billet sourcing and thermal break extrusion capture coastal Class A office specification. CE marking tightening on embodied carbon favors regional European smelter supply.
- Fiberglass:Pultruded profiles with UV-stable gelcoat displace wood in moisture-exposed residential applications. Suburban India construction and Sun Belt United States replacement cycles are the primary demand anchors.
Wood holds the largest installed base, though Aluminum is expanding most quickly in coastal commercial specification.
End User:
Application type determines hardware integration depth and access control specification.
- Residential:Single-family and multi-family construction drive volume through fiberglass entry and molded panel interior products. Finish consistency and 48-hour fulfillment are the primary vendor selection criteria in United States big-box retail.
- Commercial:Class A office and healthcare facilities in Germany and United States are integrating electromechanical mortise locks with Bluetooth credentialing. Smart access convergence is bifurcating mechanical hardware from premium integrated slab-and-electronics systems.
- Industrial:High-cycle rolling and sliding configurations serve logistics and manufacturing facilities. Durability specifications prioritize seal integrity and motorized operation over aesthetic finish.
- Institutional:Schools, government buildings, and healthcare in China and India require GB and BIS fire-rated certification. Procurement runs through specification channels where certified test documentation determines vendor qualification.
Residential commands the highest unit volume, while Commercial is climbing the fastest on access control integration.
Opening Mechanism:
Customer type and space constraints dictate mechanism selection across new construction and retrofit.
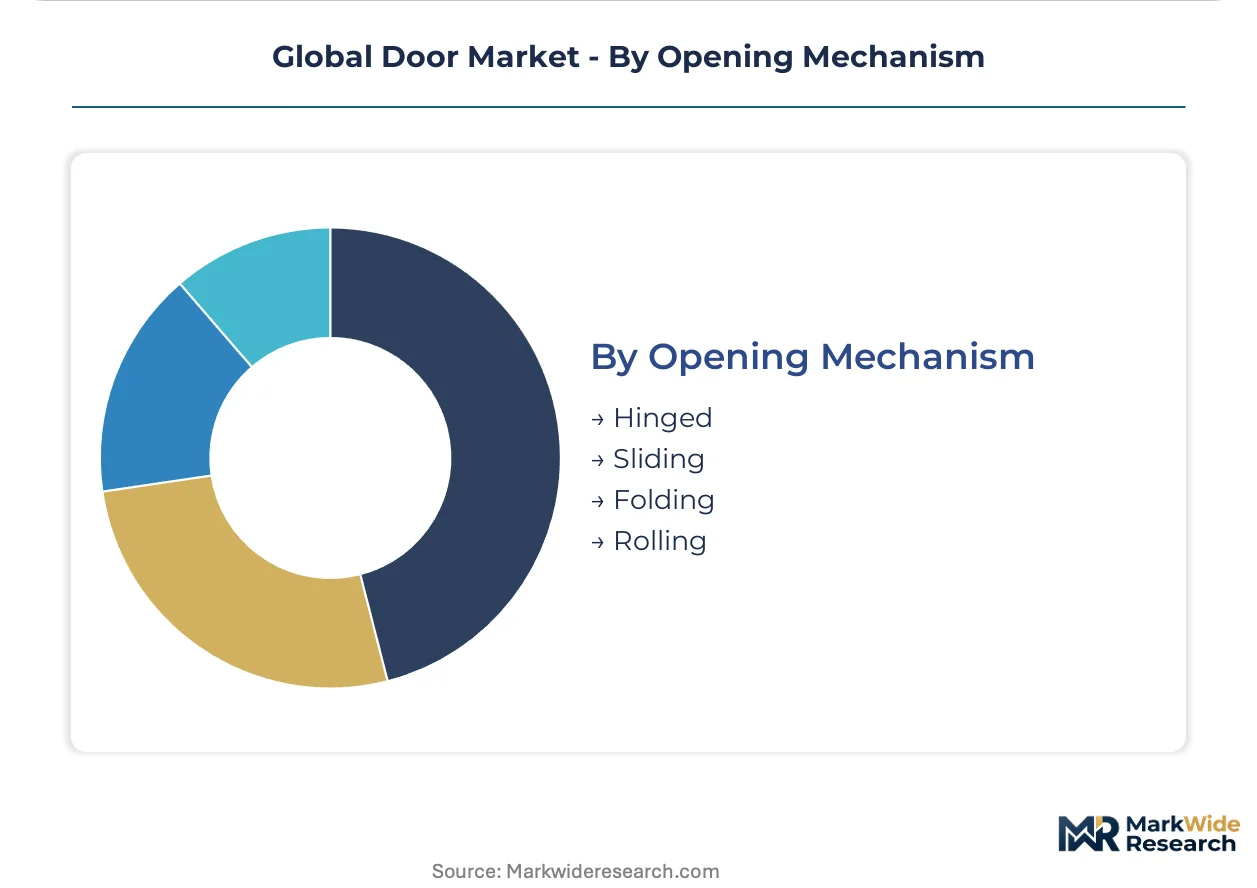
- Hinged:Conventional swing configurations dominate residential and standard commercial specification. Hinge mortise precision and frame alignment tolerance determine installation labor cost.
- Sliding:Barn-style and pocket configurations capture residential interior and space-constrained commercial retrofit. Hardware precision and track durability separate premium from commodity specification.
- Folding:Accordion and bi-fold systems serve commercial interior partition and residential closet applications. Panel alignment and hardware synchronization complexity limit supplier base.
- Rolling:Overhead coiling configurations secure industrial and commercial loading applications. Motorization and wind-load certification drive specification in hurricane-prone United States markets.
Hinged retains the dominant specification share, yet Sliding is gaining share fastest on residential interior design trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations on volatile organic compound emissions through 40 CFR Part 63 Subpart QQQQ anchor the United States market, while divergent fire-test protocols across GB standards, EN classifications, and NFPA methods fragment cross-border production planning.
United States
Replacement cycles in the Northeast and Sun Belt are diverging by climate zone, with coastal corrosion resistance displacing traditional steel in Florida and Gulf Coast markets. The EPA enforces coating emission limits under 40 CFR Part 63. Manufacturing clusters in Ohio and Ontario concentrate CNC machining and automated finishing expertise.
China
High-rise construction is accelerating demand for certified fire door assemblies. SAMR enforces GB 12955 standards for fire-rated door assemblies. Production capacity is expanding in Shandong and Jiangsu provinces to meet domestic certification requirements.
Germany
Class A office and healthcare facilities are integrating electromechanical mortise locks with Bluetooth credentialing. The EU Green Deal's embodied carbon requirements are reshaping material sourcing for construction products. Dutch and German commercial projects are rejecting uncertified Asian imports in favor of regional pultrusion with EPD verification.
India
Residential construction in suburban areas is accelerating demand for fiberglass entry systems with thermal break performance. BIS certification for fire doors under IS 3614 is tightening market access for uncertified imports. Domestic producers in Maharashtra and Gujarat are expanding certified capacity to displace imported supply.
Saudi Arabia
Banking and data center end-users are driving demand for certified forced-entry resistance in security door specification. The kingdom's national building safety regulator enforces fire-rated assembly standards for institutional construction. Industrial clusters in Riyadh and the Eastern Province are developing certified security door fabrication capacity.
Global Door Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with access control convergence and captive pultrusion capacity separating premium specification channels from commodity replacement cycles. The structure rewards inventory-heavy regional distribution in residential big-box retail while favoring certified test documentation in institutional procurement. Three archetypes dominate: integrated building product conglomerates with captive material production, access control specialists leveraging electromechanical lock integration, and regional fabricators competing on finish consistency and fulfillment speed. Competitive moves center on SKU rationalization for retail consolidation and multi-protocol certification investment to serve cross-border projects.
Among North American building product conglomerates, JELD-WEN Holding Inc. and Masonite exemplify divergent positioning strategies. JELD-WEN anchors fiberglass production through captive pultrusion capacity, while Masonite competes on molded panel density and finish consistency in big-box retail channels. Assa Abloy represents the access control convergence archetype, leveraging integration capabilities to dominate commercial specification channels where electromechanical locking and biometric reader penetration is highest.
| Leading Market Players |
|---|
| Assa Abloy |
| JELD-WEN Holding Inc. |
| Andersen Corporation |
| Pella Corporation |
| Masonite |
| Simpson Door Company |
| Allegion plc |
| dormakaba Group |
| LIXIL Corporation |
| Others |
Supply Flow & Price Mechanics
Captive pultrusion scale in Ohio and Jiangsu province creates asymmetric cost positions that compress price floors for commodity fiberglass entry systems while insulating vertically integrated producers from resin volatility. This concentration dynamic rewards inventory-heavy regional distributors in the United States Sun Belt with fulfillment premiums, while forcing smaller fabricators toward specialty fire-rated certification tiers to escape margin erosion.
Pricing Analysis
Geographic price spreads between Northeast freeze-thaw rated assemblies and Sun Belt corrosion-resistant configurations reflect climate-zone customization premiums and diverging replacement cycle compression. Three-tier pricing structure across premium integrated access-control systems, standard certified fire-rated assemblies, and economy hollow-core interior products stratifies the market by certification burden and hardware integration depth. Cost compression in economy interior tiers intensifies because big-box retail consolidation concentrates buyer power around finish consistency guarantees. Residential big-box channels exhibit highest price sensitivity, while institutional procurement in Saudi Arabian data centers and German healthcare facilities demonstrates lowest sensitivity due to specification-grade certification requirements.
Supply Chain Analysis
Forty-eight-hour fulfillment commitments in United States residential channels tether inventory positioning to regional distribution center density across Ohio, Texas, and Georgia. Raw material flows draw from unsaturated polyester resin producers in the United States Gulf Coast, aluminum billet smelters in Quebec and Norway, and hardwood veneer suppliers in Appalachian and Baltic regions. Single-source vulnerability concentrates in certified fire-test laboratory capacity at UL, Intertek, and CNAS facilities, where third-party backlog extends product launch timelines unpredictably. Distribution runs through specification channels for institutional and commercial segments, while big-box retail consolidation dominates residential fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millwright skill scarcity in CNC machining and automated finishing line operation across Ohio and Ontario manufacturing clusters constrains capacity expansion for producers lacking in-house training infrastructure or apprenticeship pipelines.
For Market Incumbents: Fortify captive pultrusion capacity in fiberglass entry systems to defend margin position against resin price volatility, while accelerating multi-protocol certification investment at UL and CNAS laboratories to serve cross-border projects without stranded inventory risk. Consolidate regional distribution center density in Sun Belt markets to capture replacement cycle compression premiums before smaller fabricators achieve equivalent fulfillment scale. For New Entrants and Emerging Players: BIS certification fast-track for IS 3614 fire-rated door standards in Maharashtra and Gujarat opens white-space displacement of uncertified imports in Indian high-rise construction. Target suburban India fiberglass entry system demand with thermal break performance specifications, leveraging domestic pultrusion partnerships to avoid import duty exposure and capture climate-zone customization premiums. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors access control integration specialists with electromechanical lock and biometric reader capabilities over pure-play door slab manufacturers. Long-term viability across the analysis window hinges on software-hardware convergence in commercial specification channels. Acquisition target archetype: regional fabricators with certified fire-rated capacity and underutilized finishing automation. Signal to watch: electromechanical mortise lock penetration rates in Class A office and healthcare facilities as inflection indicator for premium specification margin capture.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | UL, Intertek, and CNAS laboratory partnerships eliminate stranded inventory risk in cross-border projects. |
| Captive Pultrusion Capacity Expansion | In-house fiberglass production insulates margin from unsaturated polyester resin price volatility. |
| Access Control Hardware Integration | Electromechanical mortise locks with Bluetooth credentialing capture Class A office specification premiums. |
| Regional Distribution Center Consolidation | Forty-eight-hour fulfillment guarantees in Sun Belt markets anchor big-box retail vendor selection. |
| BIS Certification Fast-Track | IS 3614 fire-rated compliance displaces uncertified imports in Indian high-rise construction procurement. |
Methodological Framework
Operator-level perspectives from door manufacturing plant managers, commercial specification architects, big-box retail category buyers, fire-test laboratory technical directors, and millwright training program coordinators anchored the qualitative base. Secondary validation drew from EPA 40 CFR Part 63 Subpart QQQQ regulatory filings, SAMR GB standards documentation, BIS certification registries, SEC 10-K disclosures from listed building product conglomerates, and European EPD verification databases. Bottom-up production capacity modeling and top-down construction spending allocation triangulated volume estimates across product type, material, and end-user segments.
Sensitivity analysis tested forecast robustness against resin price volatility scenarios, fire-test protocol divergence impacts, and regional construction cycle compression assumptions over the projection horizon. Segmentation dimensions modeled included product type certification burden, material embodied carbon tier, end-user hardware integration depth, and regional regulatory cluster alignment. CAGRs derived from replacement cycle timing analysis, new construction permit trajectories, and certified capacity expansion schedules in Shandong, Jiangsu, Maharashtra, and Gujarat production zones.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and continued GB 12955, EN 1634-1, and NFPA 252 protocol divergence; material deviation in fire-test harmonization or embodied carbon accounting rules would warrant model refresh. Specific risk factors include millwright labor supply contraction, third-party laboratory capacity bottlenecks, and abrupt BIS or SAMR certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
North America Wood Based Panel Market