
 Europe AAC Blocks and Panels Market | 2026-2036
Europe AAC Blocks and Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AAC Blocks and Panels Market Insights
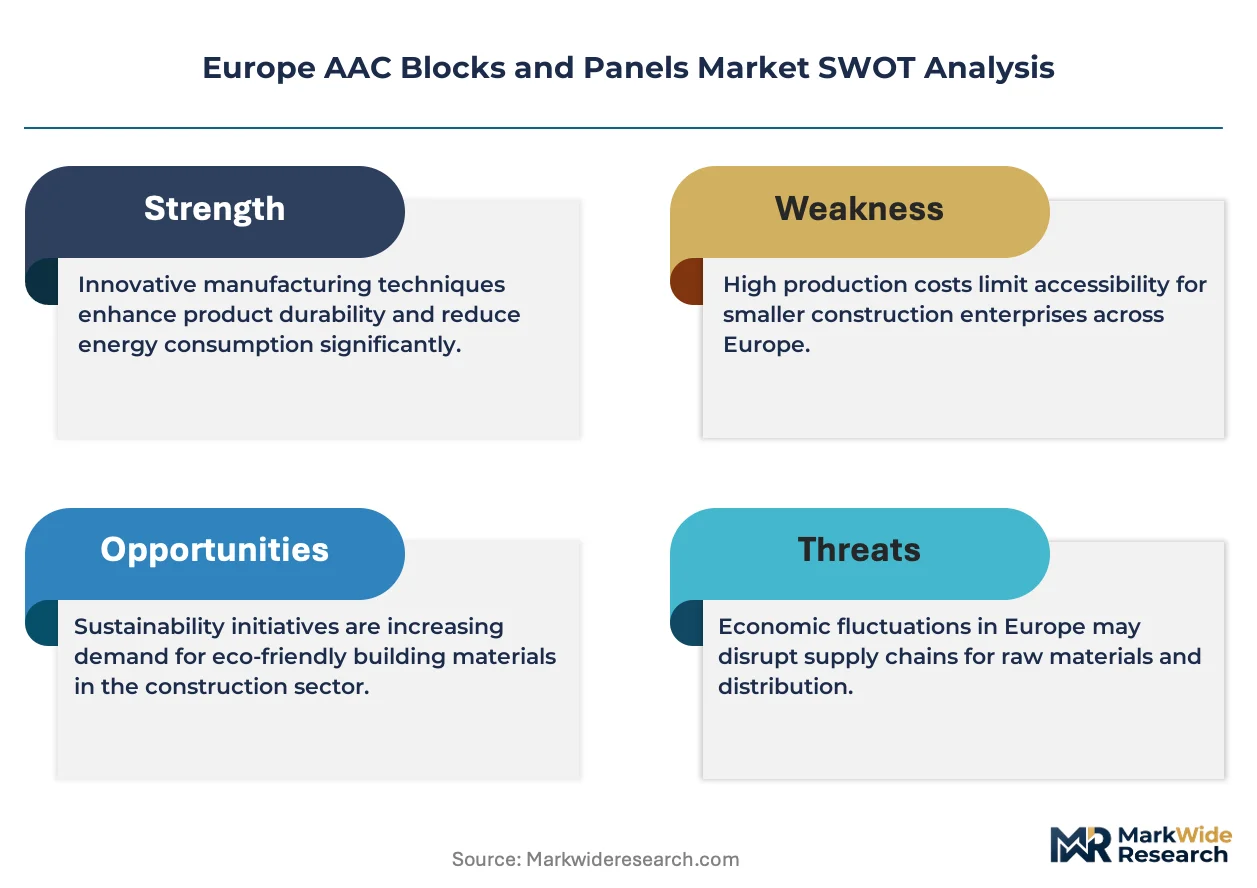
CE marking under the Construction Products Regulation is unwinding market access for uncertified producers across the European Economic Area. Xella Group leverages its pan-European plant network to sustain cost advantages in block production. H+H International A/S anchors its position through R&D intensity in thin-joint mortar systems. SOLBET competes on manufacturing scale across Poland and neighboring markets.
Autoclaved aerated concrete (AAC) consists of quartz sand, lime, cement, gypsum, and aluminum powder that expands under pressurized steam curing to form a cellular structure with bulk densities of 300–800 kg/m³ and thermal conductivity values as low as 0.07 W/mK, serving primarily as load-bearing or non-load-bearing wall elements in energy-efficient construction. Blocks dominate volume shipments across the region due to their compatibility with conventional masonry practices and established contractor training. Panels capture expanding share in commercial and infrastructure applications where crane-assisted installation accelerates project timelines. Lintels represent a mature, specification-driven segment where margin pools concentrate with engineered-custom producers.
The EU Green Deal and F-Gas Regulation shape material specifications and carbon accounting requirements for AAC manufacturers, while national building codes in Germany, France, and Poland enforce stricter U-value thresholds that favor high-performance cellular concrete. ECHA oversight of aluminum powder classification affects raw material sourcing costs and handling protocols. Stakeholders must monitor evolving national transpositions of the Energy Performance of Buildings Directive and assess whether captive lime supplies or third-party sourcing best insulate margin structures.
Market Dynamics
The EU Green Deal's tightening thermal performance mandates are compressing specification windows for masonry materials across Central and Eastern Europe, favoring autoclaved aerated concrete with demonstrably lower U-values over conventional clay brick and dense concrete block.
Growth Catalysts
- Energy Performance of Buildings Directive transposition:National building codes in Poland and Germany now mandate U-values below 0.24 W/m²K for external walls, directly advantaging AAC's thermal conductivity profile.
- Multi-family residential construction:Developers in Warsaw, Berlin, and Prague prioritize speed-to-enclosure and crane-assisted panel installation for mid-rise housing projects.
- Aluminum powder sourcing rationalization:ECHA classification harmonization is standardizing handling protocols and reducing cross-border procurement friction for cellular concrete producers.
Market Restraints
- Captive lime supply concentration:AAC production depends on high-calcium quicklime from specialized kilns concentrated in southern Poland and eastern Germany, creating input vulnerability.
- Steel reinforcement corrosion sensitivity:AAC's alkaline pore solution demands epoxy-coated or stainless reinforcement in humid climates, elevating engineered panel costs versus precast concrete alternatives.
- Clay brick substitution economics:Traditional masonry maintains contractor familiarity and lower material unit costs in single-family construction across rural Romania and Bulgaria.
Strategic Opportunities
- Romanian and Bulgarian retrofit markets:Deep energy renovation of Soviet-era panel housing stock creates demand for external AAC insulation cladding systems.
- Thin-joint mortar convergence:Combination of precision-manufactured blocks with polymer-modified adhesive bedding enables unskilled labor substitution and accelerates enclosure schedules.
- CSRD-aligned carbon accounting:Embodied carbon disclosure requirements favor AAC's 30-40% lower CO₂ footprint versus dense concrete in public procurement scoring.
Industry Challenges
- CE marking compliance timelines:Factory production control audits and initial type testing for new panel thicknesses extend product launch cycles by 8-14 months.
- Curing autoclave capacity constraints:Saturated steam generation infrastructure requires substantial capital deployment and skilled boiler operation, limiting greenfield entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AAC Blocks and Panels Market |
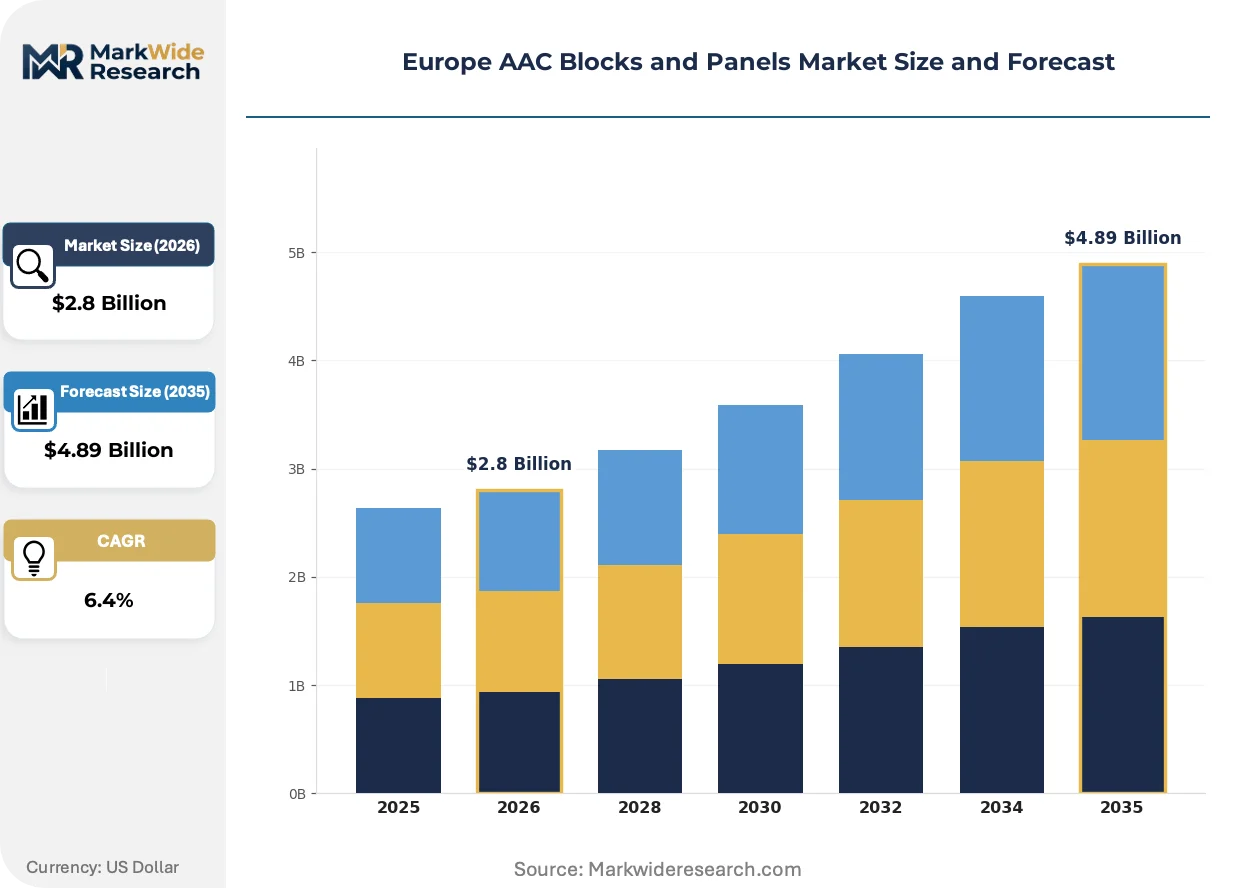
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blocks, Panels, Lintels, Products Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Builders, Architects, Developers Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Xella Group, H+H International A/S, SOLBET, AKG Gazbeton, Wehrhahn GmbH, HESS Group, WKB Systems GmbH, BAUROC AS, Celco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AAC Blocks and Panels Market Trends and Innovations
Formulation chemistry and installation methodology are converging to expand AAC's addressable market beyond traditional masonry replacement into high-performance building envelopes and accelerated construction programs.
Low-density AAC formulations incorporating microsilica and optimized aluminum powder dosing are displacing mineral wool cavity insulation in German passive house projects. Developers in Hamburg and Munich specify 350 kg/m³ blocks as monolithic exterior walls, eliminating thermal bridges from timber or metal framing. The structural consequence is compression of specialist insulation contractor roles into general masonry workflows.
F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate blowing agents with high global warming potential from AAC production. The industrial consequence is accelerated adoption of aluminum powder-only expansion systems and process heat recovery. Polish and Czech plants are most affected, retrofitting autoclave steam circuits to maintain production economics under carbon border adjustment mechanisms.
Design-build contractors are consolidating procurement authority for envelope materials, bypassing traditional merchant distributor networks. Large Polish residential developers now source AAC panels direct from manufacturing plants with fixed-price, indexed contracts spanning 18-24 months. This behavior is most visible in Warsaw's multi-family construction pipeline, where crane-ready panel packages displace block-and-mortar specifications for structures above four stories.
Europe AAC Blocks and Panels Market Segmentation
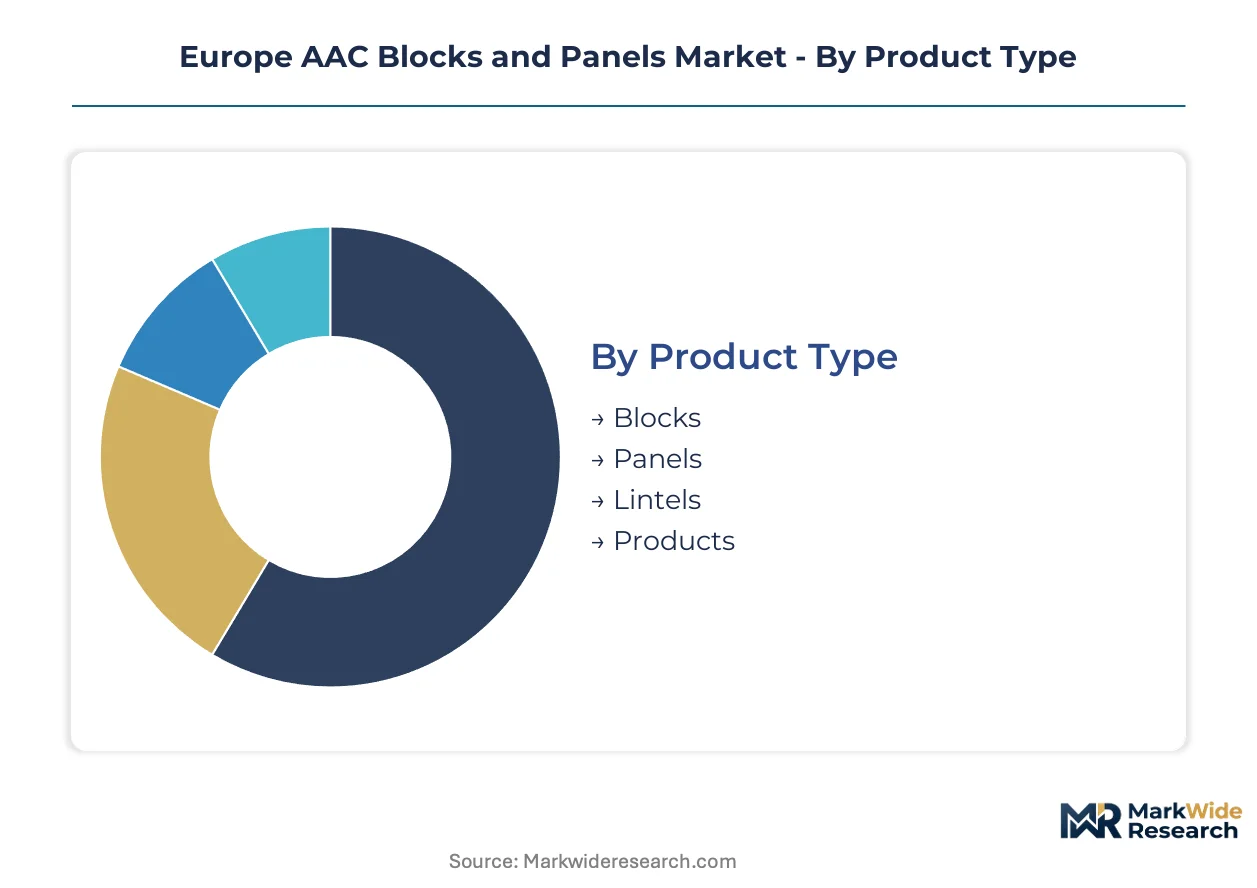
Autoclaved aerated concrete flows through distinct commercial channels shaped by project scale, thermal performance requirements, and installation methodology. Segment boundaries blur where precision-manufactured blocks meet crane-assisted panels, yet procurement patterns remain sharply differentiated by end-user sophistication and geographic concentration.
Product Type:
Blocks dominate domestic shipments across Poland and Germany where established masonry contractor networks favor conventional installation. Panels concentrate in export-led specifications for Scandinavian and Benelux markets demanding accelerated enclosure schedules.
- Blocks:Rectangular units with densities of 400–700 kg/m³ and standardized dimensions of 600×200×100–400 mm serve load-bearing and non-load-bearing wall construction. Polish and German residential developers absorb rising volumes as national building codes tighten U-value thresholds below 0.24 W/m²K.
- Panels:Reinforced floor, wall, and roof elements up to 6 meters in length enable crane-assisted installation for mid-rise structures. Demand concentrates in Warsaw and Prague multi-family projects where speed-to-enclosure compresses construction schedules by 30–40% versus block-and-mortar methods.
- Lintels:Load-bearing reinforced elements span window and door openings with engineered reinforcement configurations.
- Products:Specialty shapes including U-blocks, corner elements, and thin-joint accessories complete system specifications.
Blocks command the established base. The steepest expansion runs through Panels.
Application:
Cost tier stratification separates premium thermal performance specifications from commodity replacement of traditional masonry. Residential applications absorb volume at standard density grades while commercial projects specify low-density formulations for passive house compliance.
- Residential:Single-family and multi-family housing across Germany, Poland, and the Czech Republic drives block consumption for external walls and partition systems. Berlin and Warsaw developers specify 350–500 kg/m³ densities to meet EU Green Deal thermal mandates without supplementary insulation.
- Commercial:Office, retail, and hospitality structures in Hamburg, Munich, and Prague specify crane-ready panel systems for accelerated weather-tight enclosure. Thin-joint mortar compatibility reduces skilled labor dependency.
- Industrial:Warehouse and manufacturing facilities utilize AAC for fire-rated partitions and non-load-bearing envelope systems.
- Infrastructure:Schools, hospitals, and public buildings specify AAC for acoustic separation and thermal mass performance.
Residential absorbs the volume base. Commercial applications are climbing the fastest.
End User:
Customer type determines procurement authority and specification complexity. Design-build contractors consolidate direct manufacturing relationships while merchant distributors serve fragmented single-family builders.
- Contractors:General and specialty contractors across Central Europe execute masonry installation with established thin-joint training. Polish contractors increasingly source direct from manufacturing plants with 18–24 month indexed contracts.
- Builders:Small and mid-scale construction firms serve single-family and small multi-family projects through distributor networks.
- Architects:Specification authority for passive house and low-energy projects drives demand for low-density formulations and monolithic wall systems.
- Developers:Large residential developers in Warsaw and Berlin consolidate envelope procurement, bypassing traditional distribution for crane-ready panel packages.
Contractors retain the execution base. Developers are gaining specification authority fastest.
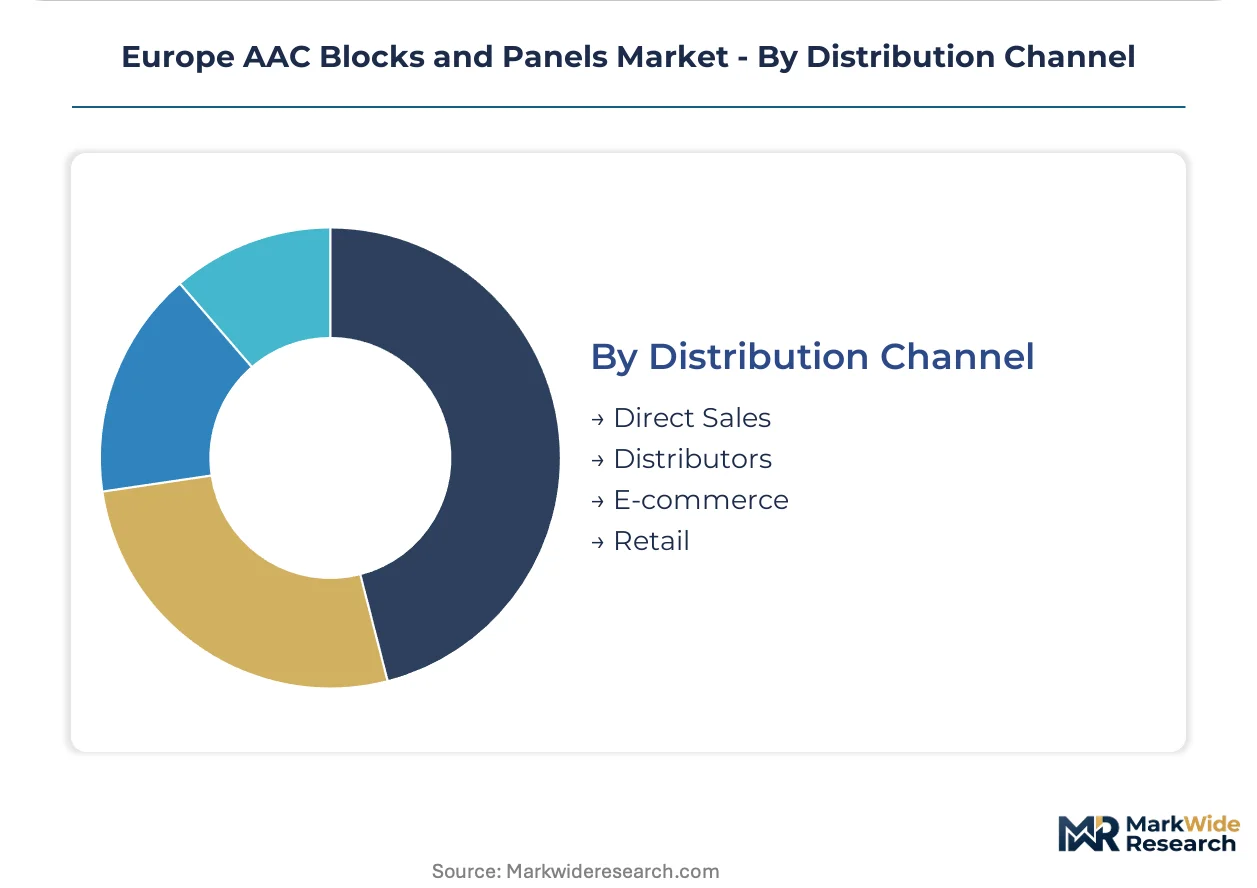
Distribution Channel:
Supply concentration in southern Poland and eastern Germany shapes channel economics. Direct sales penetrate where manufacturing plants align with dense construction corridors; distributors retain relevance in fragmented rural markets.
- Direct Sales:Manufacturing plants in Poland and Germany ship crane-ready panel packages direct to large Warsaw and Berlin developers. Fixed-price contracts spanning 18–24 months displace spot market purchasing.
- Distributors:Merchant networks across Romania, Bulgaria, and rural Poland serve fragmented contractor bases with block inventories and technical support.
- E-commerce:Digital procurement platforms emerge for standardized block specifications and accessory products.
- Retail:Builder merchant outlets stock limited AAC ranges for renovation and small-scale residential projects.
Distributors hold the geographic breadth. Direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's thermal performance mandates are compressing specification windows across member states, with national building codes in Germany, Poland, and the Czech Republic now enforcing U-values below 0.24 W/m²K for external walls. This regulatory convergence is accelerating AAC displacement of traditional clay brick and dense concrete block.
Germany
Berlin and Hamburg developers specify low-density 350 kg/m³ AAC blocks for passive house compliance, eliminating supplementary insulation layers. The Energy Performance of Buildings Directive transposition mandates stringent thermal envelopes. Manufacturing clusters in eastern Germany concentrate autoclave capacity to serve dense construction corridors.
Poland
Warsaw's multi-family residential pipeline absorbs rising panel volumes as crane-assisted installation compresses construction schedules. ECHA oversight of aluminum powder classification standardizes handling protocols across Polish plants. Southern Poland hosts concentrated quicklime kiln capacity serving regional AAC production.
Czech Republic
Prague developers prioritize speed-to-enclosure for mid-rise housing projects, favoring panel systems over conventional block-and-mortar methods. National building code alignment with EU Green Deal targets drives specification shifts. Industrial corridors near Brno concentrate manufacturing infrastructure for Central European distribution.
Romania
Bucharest's deep energy renovation of Soviet-era panel housing creates demand for external AAC insulation cladding systems. CSRD-aligned carbon accounting favors AAC's lower embodied carbon footprint in public procurement scoring. Regional distributors serve fragmented contractor bases beyond capital city construction clusters.
Bulgaria
Sofia's emerging multi-family construction adopts AAC blocks as clay brick substitution economics shift with EU accession-aligned regulations. Rural single-family construction maintains traditional masonry familiarity, constraining penetration. Black Sea coastal development corridors test panel specifications for accelerated tourism infrastructure.
Europe AAC Blocks and Panels Market Competitive Landscape
Player mix skews toward integrated building materials conglomerates with captive lime supplies and pan-European distribution networks. The competitive structure concentrates around three archetypes: vertically integrated lime-to-block producers, precision-manufacturing specialists in thin-joint systems, and regional scale players serving fragmented Central and Eastern European markets. Dominant competitive moves include autoclave capacity expansion in southern Poland and eastern Germany, plus direct sales channel development bypassing traditional merchant distribution for large Warsaw and Berlin developers.
Within the integrated conglomerate tier, Xella Group and H+H International A/S exemplify archetypes of pan-European network operators with distributed manufacturing footprints. SOLBET occupies a position representing regional scale concentration across Poland and neighboring markets. These three anchors illustrate how competitive positioning depends on lime supply security, autoclave throughput economics, and specification authority in multi-family residential procurement.
| Leading Market Players |
|---|
| Xella Group |
| H+H International A/S |
| SOLBET |
| AKG Gazbeton |
| Wehrhahn GmbH |
| HESS Group |
| WKB Systems GmbH |
| BAUROC AS |
| Celco |
| Others |
Pricing and Supply Chain Analysis
Long-term fixed-price contracts spanning 18–24 months now dominate procurement between large Warsaw and Berlin developers and manufacturing plants, locking in both autoclave capacity access and cost visibility against aluminum powder and quicklime volatility. This contract-structure pattern compresses spot-market liquidity and transfers input-price risk onto producers with captive lime kilns.
Pricing Analysis
Certification level (CE marking under the Construction Products Regulation) creates the primary spread between commodity block grades and engineered panel specifications. Three-tier pricing structure across premium, standard, and economy levels reflects density grade, thermal conductivity performance, and thin-joint mortar compatibility. Cost compression in standard-density blocks is intensifying because Polish and Romanian distributors compete for fragmented contractor volumes. Single-family builders in rural Bulgaria exhibit the highest price sensitivity, while passive house developers in Hamburg and Munich accept substantial premiums for 350 kg/m³ monolithic wall systems.
Supply Chain Analysis
Captive quicklime kiln capacity in southern Poland and eastern Germany anchors regional autoclave feedstock supply. AAC production draws from high-calcium quicklime, specialized aluminum powder, and quartz sand as core inputs. Single-source vulnerability concentrates in aluminum powder sourcing under ECHA classification harmonization. Distribution runs through direct manufacturing relationships for large developers and merchant networks for fragmented rural contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-joint mortar system sales and technical training services are expanding faster than base block volumes, transforming AAC from commodity supply into envelope-performance contracting. This service-attach dynamic favors players with field engineering capabilities over pure manufacturing scale.
For Market Incumbents: Compound defensibility through backward integration into captive lime kilns and autoclave capacity expansion in eastern Germany. Cement-based substitute materials threaten share in single-family construction; counter by deepening thin-joint certification investment and direct sales channel control for Warsaw multi-family developers. For New Entrants and Emerging Players: Lead with external insulation cladding systems for Romanian and Bulgarian deep energy renovation of Soviet-era panel housing. Romania's fragmented distributor networks represent the most penetrable geography. Pursue specification authority through architect-focused passive house education programs rather than contractor price competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thin-joint mortar and technical service providers with established field engineering teams. Long-term viability hinges on CSRD-aligned carbon accounting capabilities and EU Green Deal regulatory compliance infrastructure. Watch for aluminum powder sourcing consolidation as an inflection signal for margin compression among non-integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Eastern German manufacturing clusters serve Berlin passive house demand under tightened U-value mandates. |
| Backward Integration into Lime | Captive kiln supply insulates margin structures against southern Polish quicklime concentration. |
| Thin-Joint System Certification | CE marking compliance accelerates product launch cycles and blocks uncertified competitor entry. |
| Direct Sales Channel Development | Fixed-price contracts with Warsaw developers displace traditional merchant distribution economics. |
| Carbon Accounting Alignment | CSRD disclosure requirements favor AAC's lower embodied carbon in public procurement scoring. |
Research Methodology
The analysis maps block, panel, lintel, and specialty product sub-sectors, each validated through plant managers, procurement leads at multi-family developers, distribution channel partners, and technical R&D directors. Primary interviews with masonry contractors and thin-joint system specifiers combined with secondary validation from CE marking databases, national building code transpositions, ECHA regulatory filings, and construction permit data. Bottom-up volume triangulation against top-down envelope material demand modeling ensures cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product density grade, end-use application, installation methodology, and regional regulatory cluster. CAGRs were derived from construction pipeline analysis and thermal performance mandate trajectories. Forecast inputs incorporated EU Green Deal implementation timelines and F-Gas Regulation phase-down schedules.
Forecasts assume regulatory continuity in EU Green Deal transpositions and national building code enforcement; material policy shifts would require re-modeling. Aluminum powder reclassification or carbon border adjustment mechanism expansion represent specific risk factors that could revise demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Wood Truss Market