
 Street Furniture Market | 2026-2036
Street Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Street Furniture Market Analysis
Municipal leasing and performance-based service contracts are narrowing the competitive field for smaller fabricators lacking balance-sheet capacity for long-term asset ownership. Victor Stanley Inc leverages its vertically integrated foundry operations to sustain pricing discipline on cast-iron benches and bollards. JCDecaux SA anchors its street furniture footprint through exclusive advertising concession agreements with city governments, while Landscape Forms Inc differentiates via design-led product systems that command premium positioning in North American transit hub renovations.
Street furniture encompasses engineered outdoor fixtures including seating, waste receptacles, transit shelters, and lighting supports, typically fabricated from powder-coated steel, cast aluminum, FSC hardwood, or glass-reinforced polymer composites to withstand cyclic loading, UV exposure, and vandalism in publicly accessible spaces. Metal benches and shelters dominate installed value in transportation hub applications where durability requirements and high traffic volumes justify premium material specifications. Plastic waste bins and recycled polymer seating represent the fastest-expanding material segment as municipalities prioritize closed-loop procurement criteria, while concrete tables and fixed planters anchor mature demand in parks where permanence and low theft risk outweigh mobility needs.
EU Green Deal procurement guidelines and REACH substance restrictions are reshaping material specifications across European municipal tenders, compelling suppliers to certify recycled content thresholds and eliminate chromated copper arsenate treatments. The US EPA and FHWA contextual design standards influence sidewalk and transit-accessible fixture dimensions through ADA-compliant dimensional mandates. Stakeholders must monitor evolving extended producer responsibility frameworks in France and Germany, where forthcoming repairability labeling requirements could restructure supplier obligations for component replacement and end-of-life collection.
Market Dynamics
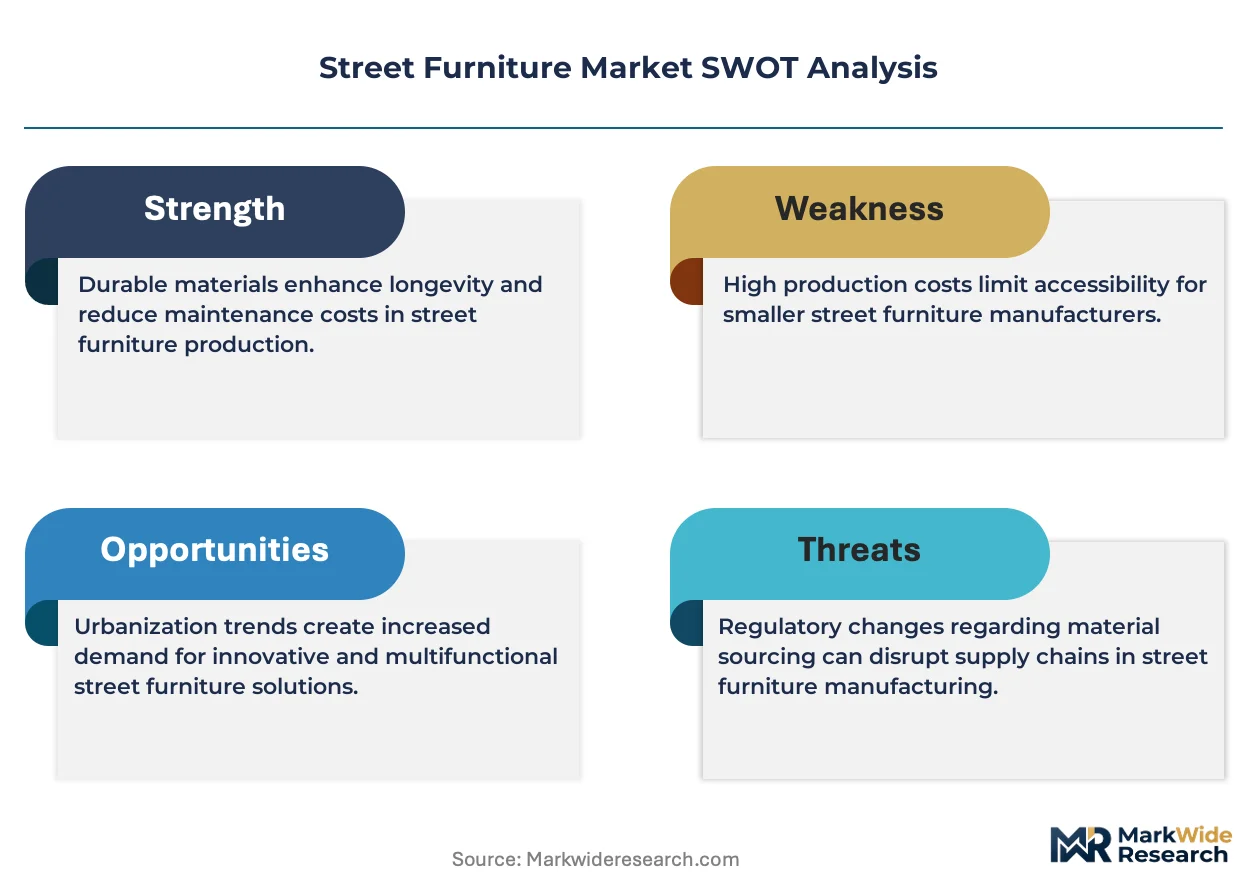
Municipal leasing models and EU Green Deal procurement mandates are compressing supplier margins while favoring fabricators with captive recycling streams and long-term balance-sheet capacity for asset retention.
Growth Catalysts
- Federal Städtebauförderung funding:German metropolitan regions channel investment into redesigned public squares and transit-adjacent streetscapes, expanding tender volumes for engineered outdoor fixtures.
- REACH substance restrictions:ECHA mandates on chromated copper arsenate elimination and recycled content thresholds compel specification upgrades across European municipal procurement.
- Closed-loop polymer recovery:Mechanical recycling advances enable post-consumer plastic conversion into UV-stable seating and waste receptacles meeting durability benchmarks for high-traffic installations.
Market Restraints
- Aluminum price volatility:LME spot fluctuations and energy cost pass-through from European smelters compress margin predictability for cast-component fabricators.
- Foundry capacity concentration:Specialist ductile-iron casting operations cluster in northern Italy and western Germany, creating geographic supply vulnerability for non-integrated assemblers.
- Timber certification bottlenecks:FSC chain-of-custody audit backlogs extend lead times for hardwood seating specified in Green Deal-compliant tenders.
Strategic Opportunities
- Sensor-integrated smart benches:WiFi access point and air quality monitoring convergence creates premium positioning in French and Dutch smart city deployments.
- Performance-based service contracts:Dutch and Belgian municipalities pilot availability-fee structures transferring maintenance liability to suppliers with asset-management capabilities.
- Repairability labeling mandates:Forthcoming French and German extended producer responsibility frameworks restructure supplier obligations toward modular component design and end-of-life collection infrastructure.
Industry Challenges
- ADA dimensional compliance:US FHWA and EPA contextual design standards mandate precise sidewalk fixture clearances, requiring design-engineering retooling for European suppliers entering North American transit hub projects.
- Multi-material welding certification:Fabricators joining aluminum frames to steel substructures face extended welder qualification timelines under EN 1090 structural execution standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Street Furniture Market |
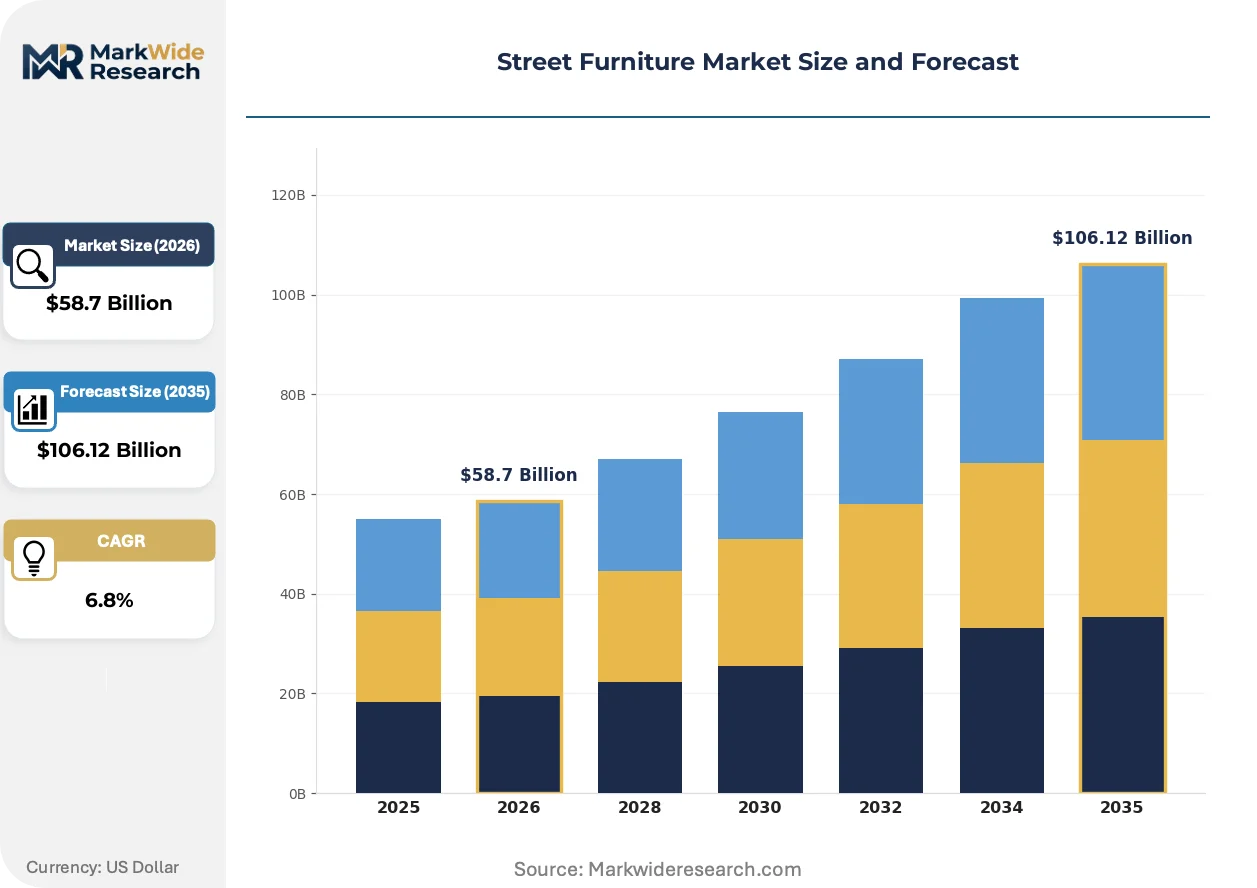
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benches, Waste Bins, Shelters, Tables Material: Metal, Wood, Plastic, Concrete Application: Parks, Public Squares, Sidewalks, Transportation Hubs Customer Type: Municipalities, Private Developers, Non-Profits, Urban Planners |
| Companies Covered | Victor Stanley Inc, Maglin Site Furniture Inc, JCDecaux SA, Clear Channel Outdoor, Street Furniture Group, Landscape Forms Inc, Metalco Srl, Glasdon International Limited, Forms+Surfaces, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Street Furniture Market Emerging Trajectories
Digital fabrication and circular material flows are restructuring how engineered outdoor fixtures are specified, procured, and maintained across publicly accessible spaces.
Glass-reinforced polymer composite manufacturing is rendering obsolete traditional cast-iron bench production for coastal and high-salinity installations. German and Dutch municipal procurement departments specify pultruded profiles for waterfront promenades where corrosion resistance outweighs heritage aesthetic requirements. The shift compresses maintenance liability windows from decades to years, altering supplier warranty structures and residual value calculations.
EU Green Deal circular economy procurement guidelines now mandate minimum recycled aluminum and FSC-certified timber thresholds in public realm tenders. ECHA REACH substance restrictions eliminate chromated copper arsenate treatments previously standard in hardwood preservation. European fabricators restructure supply chains toward certified scrap streams and thermally modified timber alternatives, with German federal building codes accelerating compliance timelines.
Leasing arrangements displace capital purchase in French and Belgian municipal procurement, transferring ownership and maintenance burden to suppliers. Mid-sized fabricators without balance-sheet depth lose access to multi-year concession agreements, while vertically integrated operators capture recurring revenue streams. The model concentrates in transit-adjacent deployments where asset utilization rates justify performance-based contracting structures.
Street Furniture Market Segmentation
Street furniture procurement patterns diverge sharply across installation contexts, from high-traffic transit nodes demanding structural longevity to civic spaces prioritizing aesthetic coherence. Material selection and ownership models further fragment demand, creating distinct competitive arenas where specification expertise outweighs scale economies.
Product Type:
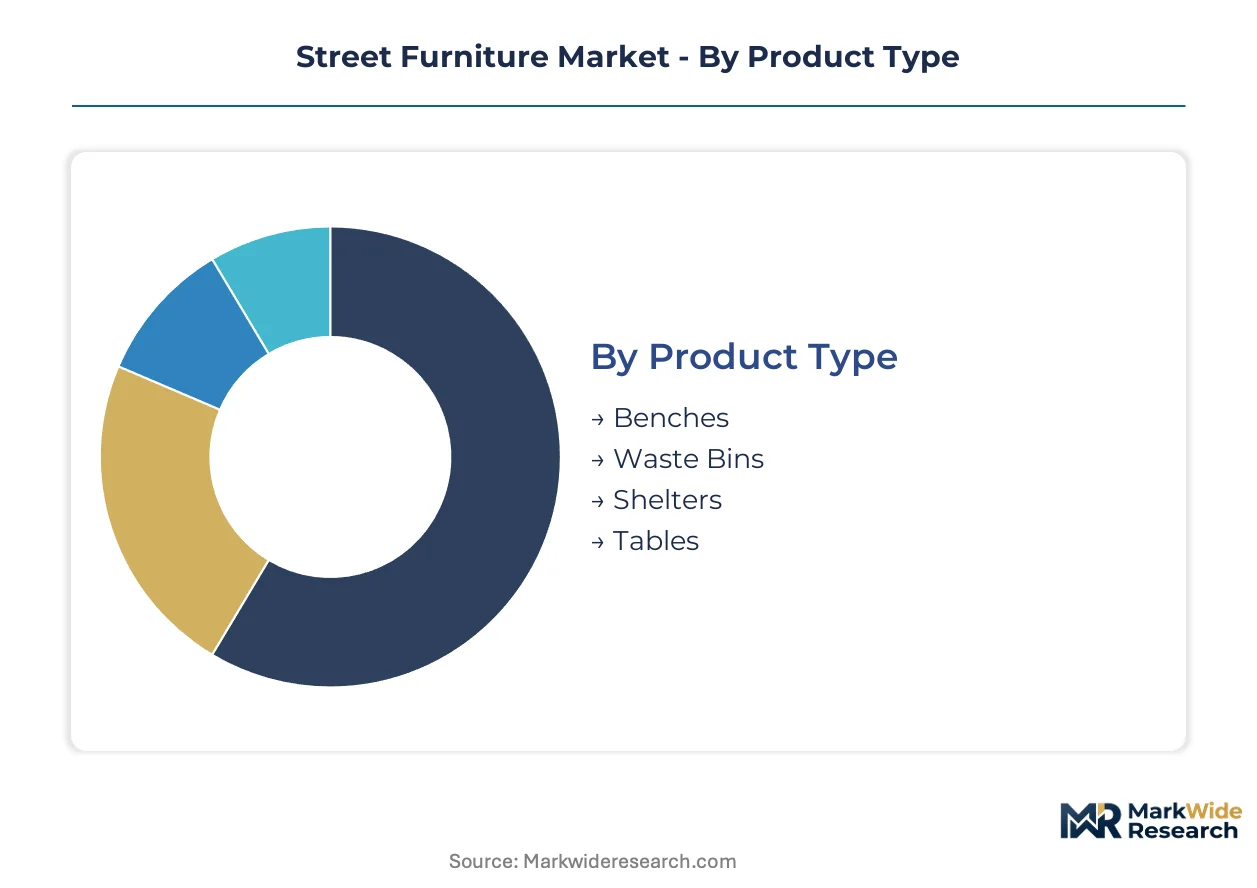
Engineered outdoor fixtures span functional categories calibrated to dwell time, traffic intensity, and maintenance liability in publicly accessible zones.
- Benches:Cast-iron and aluminum seating systems with powder-coated finishes dominate transportation hub installations where cyclic loading and vandalism resistance justify premium specifications. German Städtebauförderung-funded urban renewal projects in Frankfurt and Hamburg are channeling tender volume toward modular bench systems with integrated charging infrastructure.
- Waste Bins:Post-consumer recycled polymer receptacles with UV-stabilized shells represent the steepest expansion trajectory as EU Green Deal procurement mandates eliminate virgin plastic specifications. Dutch municipalities now require minimum recycled content thresholds for all public realm waste management fixtures.
- Shelters:Glass-reinforced polymer composite transit shelters with integrated lighting and real-time display compatibility anchor smart city deployments in French metropolitan regions.
- Tables:Fixed concrete and FSC-certified hardwood picnic systems anchor mature demand in parks where permanence and low theft risk outweigh mobility requirements.
The dominant share belongs to benches, while waste bins are closing the gap fastest.
Material:
Cost tiers stratify around durability benchmarks, circular certification requirements, and regional supply chain configurations.
- Metal:Powder-coated steel and cast aluminum deliver structural integrity for high-traffic installations. German and Italian foundry clusters supply ductile-iron components to transportation hub projects across the Benelux region.
- Wood:FSC-certified hardwood and thermally modified timber alternatives satisfy EU Green Deal chain-of-custody mandates. Certification audit backlogs in Baltic supply regions extend lead times for Green Deal-compliant tenders.
- Plastic:Closed-loop polymer recovery streams enable mechanical recycling into UV-stable seating and receptacles meeting durability benchmarks for coastal promenades in the Netherlands.
- Concrete:Precast reinforced systems deliver permanence and minimal maintenance liability for park installations where mobility is not a design priority.
Metal retains the largest installed base, though plastic is expanding most quickly on circular procurement tailwinds.
Application:
Volume concentrates in transportation-adjacent deployments where asset utilization rates justify performance-based contracting and premium material specifications.
- Transportation Hubs:Transit shelters, charging-integrated benches, and wayfinding fixtures command premium positioning. French and Dutch smart city pilots specify sensor-enabled assets with availability-fee structures transferring maintenance liability to suppliers.
- Parks:Low-mobility concrete tables, fixed planters, and hardwood seating systems anchor mature replacement cycles. German federal building codes accelerate compliance timelines for sustainable material specifications in green space renovations.
- Public Squares:Redesigned civic spaces in German metropolitan regions drive tender volume for coordinated fixture systems under Städtebauförderung urban renewal funding.
- Sidewalks:ADA-compliant dimensional mandates from US FHWA and EPA contextual design standards shape fixture clearances, requiring engineering retooling for European suppliers entering North American projects.
Transportation hubs capture the highest value per installation, while public squares are gaining share fastest on renewal funding expansion.
Customer Type:
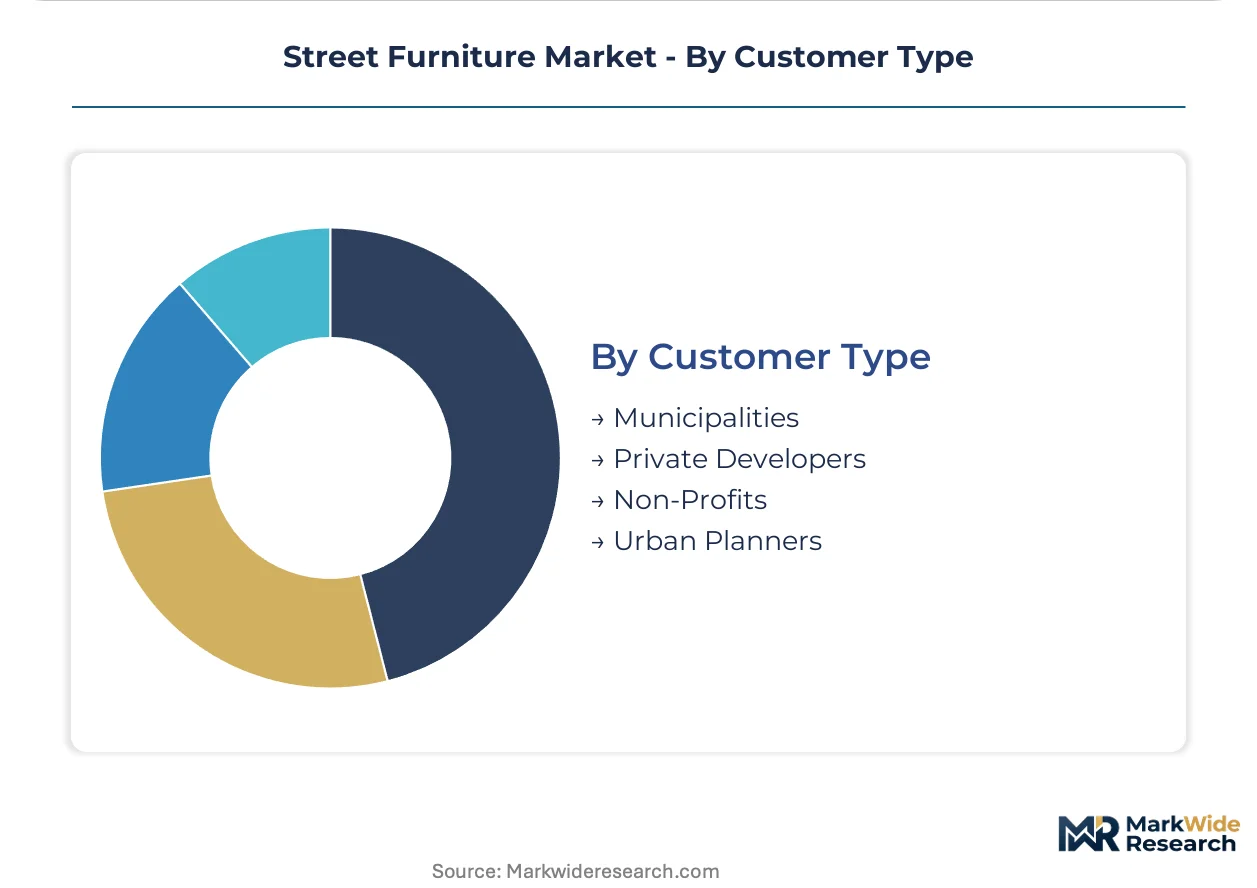
Procurement authority fragments across public budgets, private development timelines, and mission-driven funding streams with diverging specification priorities.
- Municipalities:Public procurement departments in Germany and France are expanding smart bench deployments with integrated charging and sensor capabilities. Leasing arrangements displace capital purchase in French and Belgian markets, concentrating contract awards on fabricators with balance-sheet capacity for long-term asset retention.
- Private Developers:Mixed-use and transit-oriented projects specify design-led product systems that command premium positioning in North American hub renovations.
- Non-Profits:Mission-driven funding supports community garden and neighborhood park installations with durability requirements balanced against constrained capital budgets.
- Urban Planners:Technical specification authority shapes material selection and dimensional compliance across public realm master plans in Dutch and German cities.
Municipalities dominate tender volume, yet private developers are expanding fastest on transit-oriented construction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal urban renewal funding in Germany channels substantial investment into redesigned public squares and transit-adjacent streetscapes, while EU Green Deal procurement mandates reshape material specifications across European tenders. Municipal leasing models in France and Belgium transfer asset ownership to suppliers with balance-sheet capacity for long-term retention. The United States maintains distinct regulatory requirements through ADA-compliant dimensional standards for sidewalk fixtures.
Germany
Städtebauförderung urban renewal funding drives tender volumes for engineered outdoor fixtures in Frankfurt, Hamburg, and Berlin metropolitan regions. ECHA REACH substance restrictions compel specification upgrades eliminating chromated copper arsenate treatments from hardwood preservation protocols. Northern Italian and western German foundry clusters supply ductile-iron casting components to transportation hub projects across the Benelux region.
France
Exclusive advertising concession agreements anchor street furniture footprints in Paris, Lyon, and Marseille municipal deployments. Forthcoming extended producer responsibility frameworks under EU Green Deal implementation restructure supplier obligations toward modular component design and end-of-life collection infrastructure. French metropolitan regions pilot sensor-integrated smart benches with WiFi access points and air quality monitoring capabilities.
United States
ADA-compliant dimensional mandates from the EPA and FHWA contextual design standards shape sidewalk fixture clearances for transit-accessible installations. Design-led product systems command premium positioning in North American transit hub renovations across major metropolitan markets. European suppliers entering US projects face engineering retooling requirements to meet precise dimensional specifications.
Netherlands
Availability-fee performance-based service contracts transfer maintenance liability to suppliers with asset-management capabilities in Dutch municipal procurement. Closed-loop polymer recovery streams enable mechanical recycling into UV-stable seating meeting durability benchmarks for coastal promenade installations. Randstad urban agglomerations specify minimum recycled content thresholds for all public realm waste management fixtures.
Belgium
Leasing arrangements displace capital purchase in Belgian municipal procurement, concentrating contract awards on fabricators with long-term balance-sheet capacity. EU Green Deal circular economy procurement guidelines mandate minimum recycled aluminum and FSC-certified timber thresholds in public realm tenders. Brussels and Antwerp metropolitan regions channel investment into coordinated fixture systems for redesigned civic spaces.
Street Furniture Market Vendor Landscape
On the supply side, the industry is consolidating around fabricators with captive recycling streams and balance-sheet depth for asset retention under municipal leasing models. Specialist foundry operations cluster geographically in northern Italy and western Germany, creating supply vulnerability for non-integrated assemblers. Three archetypes dominate: vertically integrated metal fabricators, advertising concession operators, and design-led premium specialists. Competitive moves center on strategic partnerships for smart city sensor integration and geographic expansion to capture Städtebauförderung-funded urban renewal projects.
Within the advertising concession tier, JCDecaux SA exemplifies the exclusive municipal agreement model transferring street furniture deployment risk to operators. Among North American fabricators, Victor Stanley Inc and Landscape Forms Inc occupy positions representing foundry-integrated production and design-led premium positioning respectively. These three anchors illustrate how competitive advantage stratifies across operational scale, material integration, and specification expertise in an environment where EU Green Deal compliance and long-term asset ownership capabilities determine contract access.
| Leading Market Players |
|---|
| Victor Stanley Inc |
| Maglin Site Furniture Inc |
| JCDecaux SA |
| Clear Channel Outdoor |
| Street Furniture Group |
| Landscape Forms Inc |
| Metalco Srl |
| Glasdon International Limited |
| Forms+Surfaces |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in northern Italy and western Germany is compressing supplier margins while amplifying pricing power for vertically integrated metal fabricators with captive casting operations. This utilization squeeze is reshaping procurement negotiations across European municipal tenders, where asset-heavy operators can absorb extended payment terms that strain balance-sheet-constrained competitors.
Pricing Analysis
Certification level creates the primary spread across the market, with FSC chain-of-custody and EU Green Deal compliance premiums separating qualified from non-qualified suppliers. Municipal leasing arrangements favor contract-based long-term offtake structures that transfer ownership risk to fabricators. Price differentiation stems from recycled content thresholds and after-sales service bundling. Municipal procurement departments exhibit highest price sensitivity, while private transit-oriented developers accept premium positioning for design-led systems.
Supply Chain Analysis
Extended payment terms from French and Belgian municipalities are forcing supply-chain finance facilities upon mid-tier fabricators lacking working capital depth. Raw material sourcing draws from German and Italian foundry clusters for ductile-iron components, Baltic regions for FSC-certified hardwood, and Dutch mechanical recycling streams for post-consumer polymers. Single-source vulnerability concentrates in northern Italian casting operations. Distribution runs through municipal procurement departments and exclusive advertising concession operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal procurement fragmentation is creating specialized niches for certified suppliers, as circular economy mandates disqualify generalist fabricators from tender participation. Municipal leasing models amplify this effect by rewarding balance-sheet capacity over production scale.
For Market Incumbents: Entrench position through backward integration into certified scrap streams and thermally modified timber supply. Foundry capacity additions in western Germany would neutralize geographic supply vulnerability. Capture recurring revenue through performance-based availability contracts in Dutch and Belgian markets where maintenance liability transfers are accelerating.
For New Entrants and Emerging Players: Pursue sensor-integrated smart bench deployments in French metropolitan regions where pilot programs lack established supplier relationships. Closed-loop polymer recovery for UV-stable seating offers the most penetrable entry point against metal-dominant incumbents. Lead with modular component design that anticipates forthcoming repairability labeling mandates.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across municipal leasing sub-segments as asset-retention requirements favor balance-sheet-heavy operators. Acquisition targets should display captive recycling streams and long-term concession contract portfolios. Watch for ECHA substance restriction announcements as inflection indicators that would restructure supplier compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Scrap Streams | EU Green Deal recycled aluminum mandates in German tenders require captive supply. |
| Sensor-Integrated Smart Bench Development | French metropolitan pilots specify WiFi and air quality monitoring capabilities. |
| Performance-Based Service Contract Piloting | Dutch availability-fee structures transfer maintenance liability to asset managers. |
| FSC Chain-of-Custody Certification Investment | Baltic audit backlogs create lead-time advantage for pre-certified suppliers. |
| Modular Component Design Restructuring | Extended producer responsibility frameworks in France and Germany mandate repairability. |
Methodological Framework
A standing panel of municipal procurement officers, foundry operations managers, urban planning directors, and advertising concession operators provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with technical specification authorities at German Städtebauförderung-funded projects and French smart city pilot programs. Secondary sources encompassed EU tender databases, ECHA regulatory filings, FSC chain-of-custody audit records, and municipal leasing contract disclosures. Bottom-up installation volume estimates triangulated against top-down material flow analysis across the analysis window.
Scenario-bracketing framed demand projections across product type, material certification tier, application intensity, and customer ownership-model preferences. CAGRs derived from segmented growth rate application with cross-validation against macroeconomic drivers. Industry-specific inputs incorporated foundry capacity utilization rates, aluminum LME price volatility bands, and municipal budget allocation patterns for urban renewal funding.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated metal fabricators or advertising concession operators would shift outcomes. Macroeconomic deviation, regulatory acceleration of ECHA substance restrictions, or technological breakthroughs in closed-loop polymer recovery would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Portable Ramps Market